
 Stalkerware Market | 2026-2036
Stalkerware Market Size, Share, and Industry Trends Forecast 2026-2036
Stalkerware Market Analytics
Subscription-based leasing of surveillance capabilities is rewriting competitive dynamics in the stalkerware sector. mSpy leverages recurring revenue models to sustain customer lock-in across multiple device platforms. FlexiSPY anchors its position through deep technical specialization in cross-platform interception. ClevGuard competes aggressively on price-accessibility for entry-tier monitoring tools.
Stalkerware comprises covert software installed on target devices without informed consent, typically operating through kernel-level access or accessibility service exploitation to exfiltrate messages, location data, and media files. The technology serves unauthorized surveillance purposes across intimate partner abuse, corporate espionage, and unlawful investigative contexts. Cloud-based deployment leads structural growth due to lower technical barriers for non-technical operators seeking remote dashboard access. Subscription models capture the dominant margin pool through automatic renewal mechanisms and tiered feature gating. Mobile deployment dominates volume as Android's open sideloading ecosystem enables distribution outside regulated app stores.
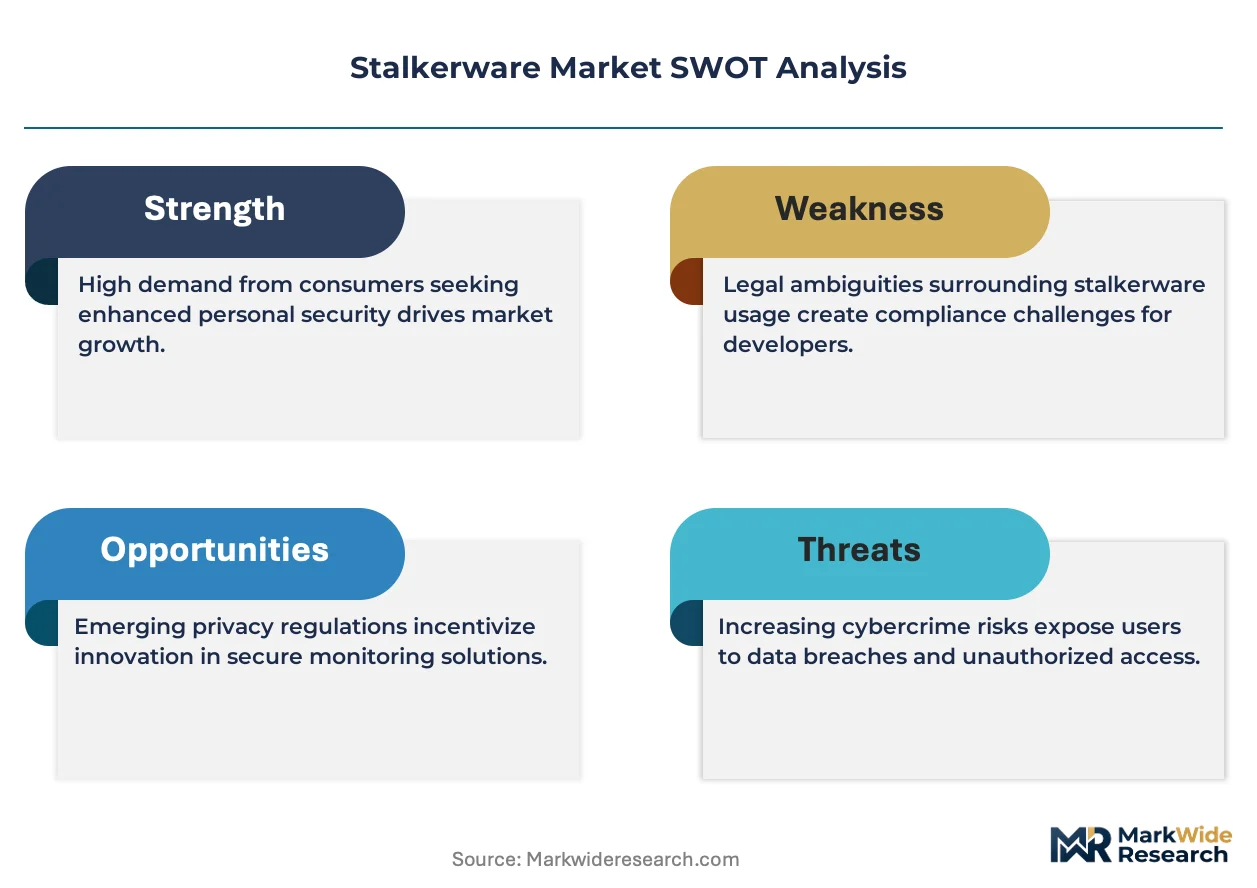
The Federal Trade Commission scrutinizes consumer harm from deceptive monitoring software marketing in the United States. The EU AI Act and GDPR jointly constrain cross-border data processing by surveillance tool vendors serving European users. Brazil's ANVISA and national data protection authority increasingly coordinate on health-adjacent privacy violations where stalkerware intercepts medical communications. Stakeholders must monitor evolving criminalization statutes that reclassify vendor liability from civil deception to felony facilitation.
Market Dynamics
Subscription billing models are restructuring competitive economics in the stalkerware sector, locking operators into recurring revenue streams while lowering upfront technical barriers for non-specialist users seeking remote surveillance capabilities.
Growth Catalysts
- Cloud dashboard architectures:Browser-based control interfaces eliminate local software expertise requirements, expanding the addressable user base to technically unsophisticated domestic abusers and amateur investigators.
- GDPR Article 58 enforcement:European data protection authorities are fining vendors for unlawful cross-border data transfers, paradoxically driving demand for jurisdictionally-agnostic hosting infrastructure.
- Android sideloading permissiveness:Google's open APK distribution ecosystem enables circumvention of app store content policies, sustaining distribution channels despite platform bans.
Market Restraints
- Payment processor deplatforming:Stripe and PayPal terminate merchant accounts for surveillance software vendors, forcing reliance on high-fee cryptocurrency or offshore banking rails.
- Kernel-level detection advances:Google Play Protect and mobile security suites now flag accessibility service exploitation patterns, increasing technical maintenance costs for evasion.
- Felony facilitation statutes:US state legislatures in California and New York criminalize commercial stalkerware distribution, exposing operators to criminal liability beyond civil deception claims.
Strategic Opportunities
- Medical communications interception:Health-adjacent surveillance represents an underexploited vector as telehealth adoption expands the attack surface for intimate partner monitoring.
- IoT device convergence:Smart home ecosystems and wearables create new exfiltration channels beyond smartphones, requiring cross-platform interception capabilities.
- Brazil's LGPD enforcement gap:Limited resourcing at ANPD creates a regulatory vacuum where vendors operate with reduced compliance friction relative to European markets.
Industry Challenges
- Zero-day acquisition costs:Exploit brokers charge premium rates for undisclosed Android and iOS vulnerabilities, compressing margins for vendors dependent on device compromise.
- Attribution engineering:Operators must continuously restructure corporate shells and hosting arrangements to evade law enforcement takedown operations and asset seizure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stalkerware Market |
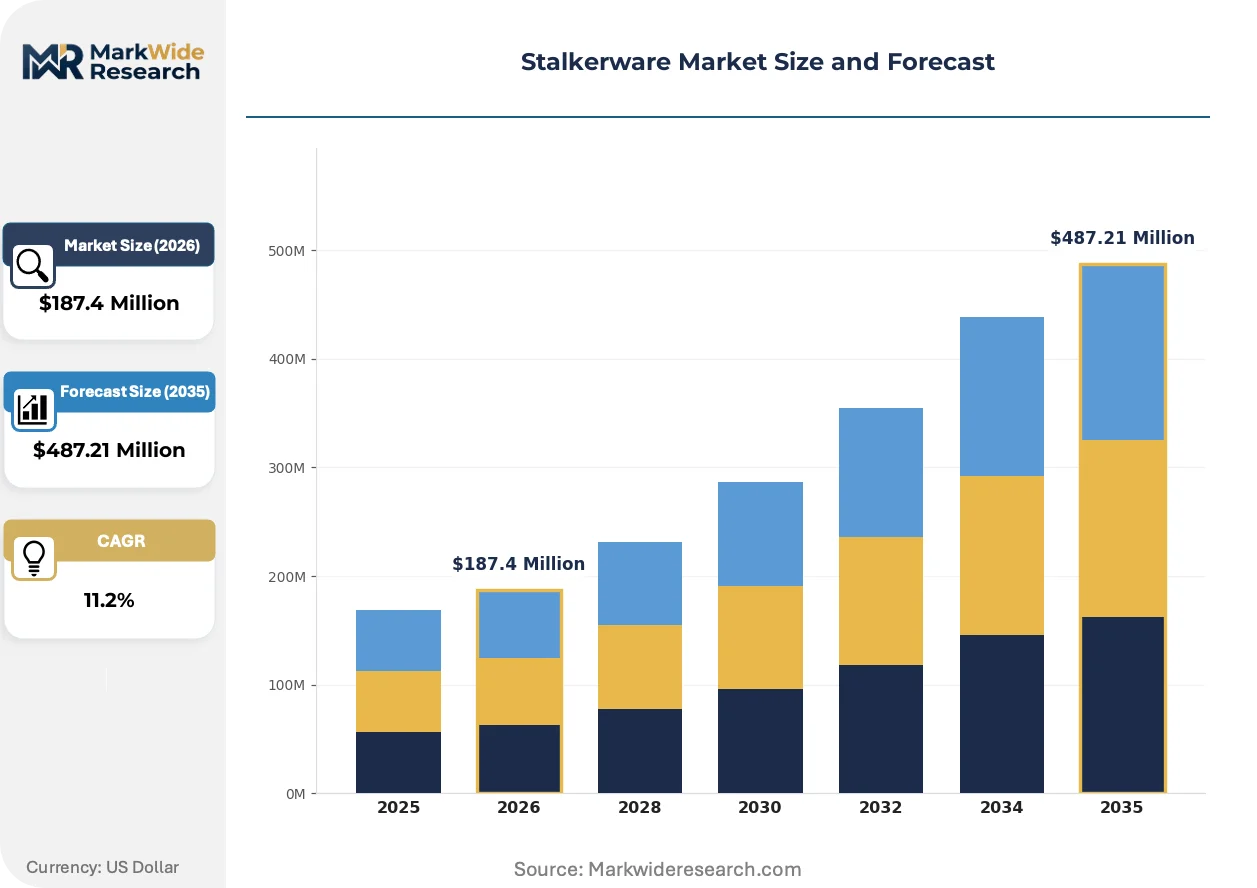
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
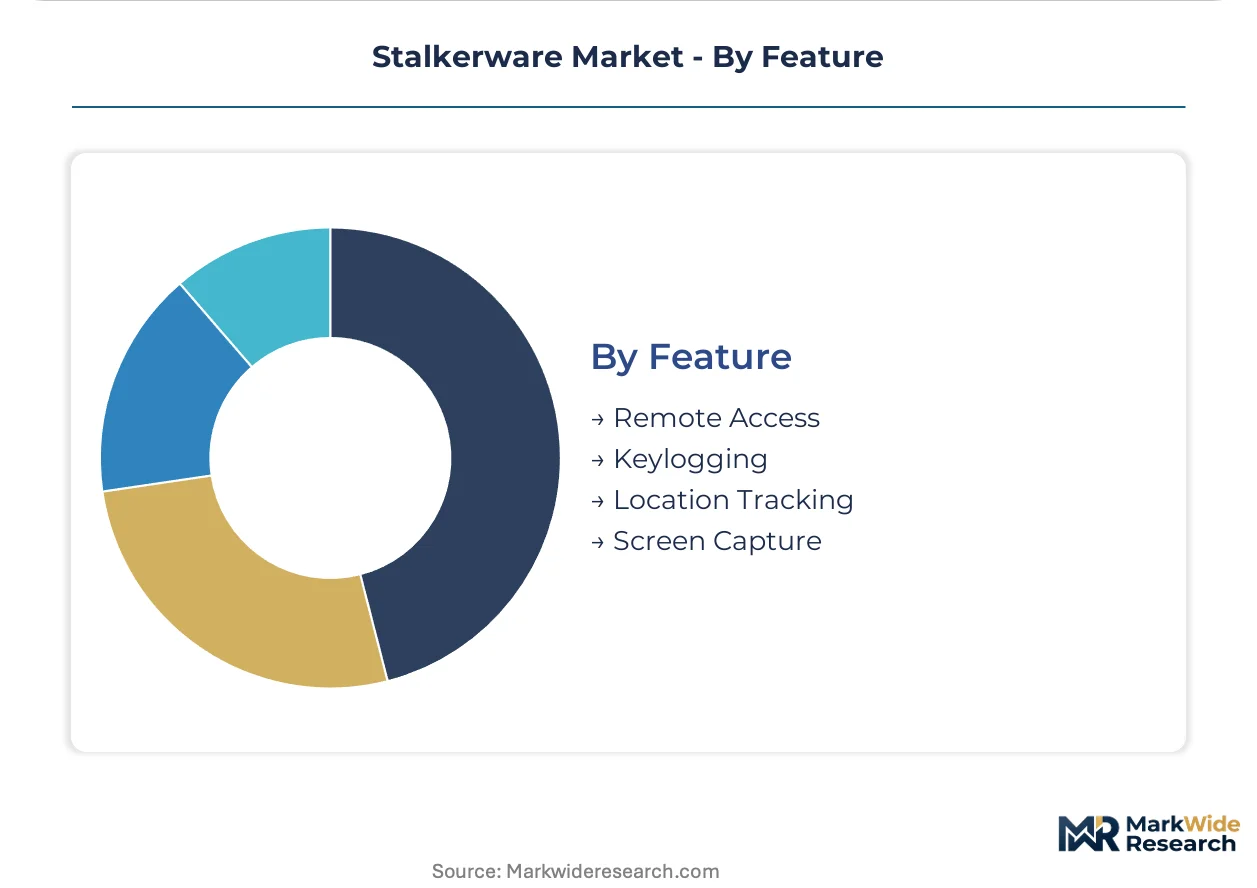
| Segmentation | Type: Commercial, Freeware, Subscriptions, Bundled Services Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Individuals, Enterprises, Law Enforcement, Investigative Agencies Feature: Remote Access, Keylogging, Location Tracking, Screen Capture |
| Companies Covered | mSpy, FlexiSPY, Cocospy, Spyzie, Spyic, Eyezy, Spynger, ClevGuard, Phonsee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stalkerware Market Evolving Landscape
Stalkerware technical architectures are fragmenting across deployment models as platform security hardening forces adaptive engineering. Three converging developments are restructuring how surveillance capabilities reach end-users.
Kernel-level rootkits are migrating from legacy Android versions to accessibility service frameworks as Google locks down lower-level system access. Domestic abusers and corporate espionage operators adopt these elevated-permission techniques to sustain message interception as OEM security patches proliferate. The migration from kernel exploitation to accessibility abuse is compressing the technical sophistication gap between commercial vendors and independent threat actors.
The EU AI Act's prohibited practices framework classifies certain automated surveillance outputs as unacceptable risk, forcing vendors serving European users to strip predictive location and behavioral analysis features. This regulatory constraint fragments product roadmaps between compliance-oriented and jurisdictionally-agnostic operators. Vendors with EU customer exposure are responding by geofencing feature availability and establishing non-EU data processing subsidiaries.
Buyer concentration around subscription auto-renewal mechanisms is displacing one-time license purchases across the surveillance software sector. Law firms and private investigation agencies now demand consumption-scaled billing tied to active monitoring seats rather than perpetual device licenses. This behavioral shift is most visible in the United States, where enterprise procurement departments increasingly reject capital expenditure models for operational intelligence tooling.
Stalkerware Market Segmentation
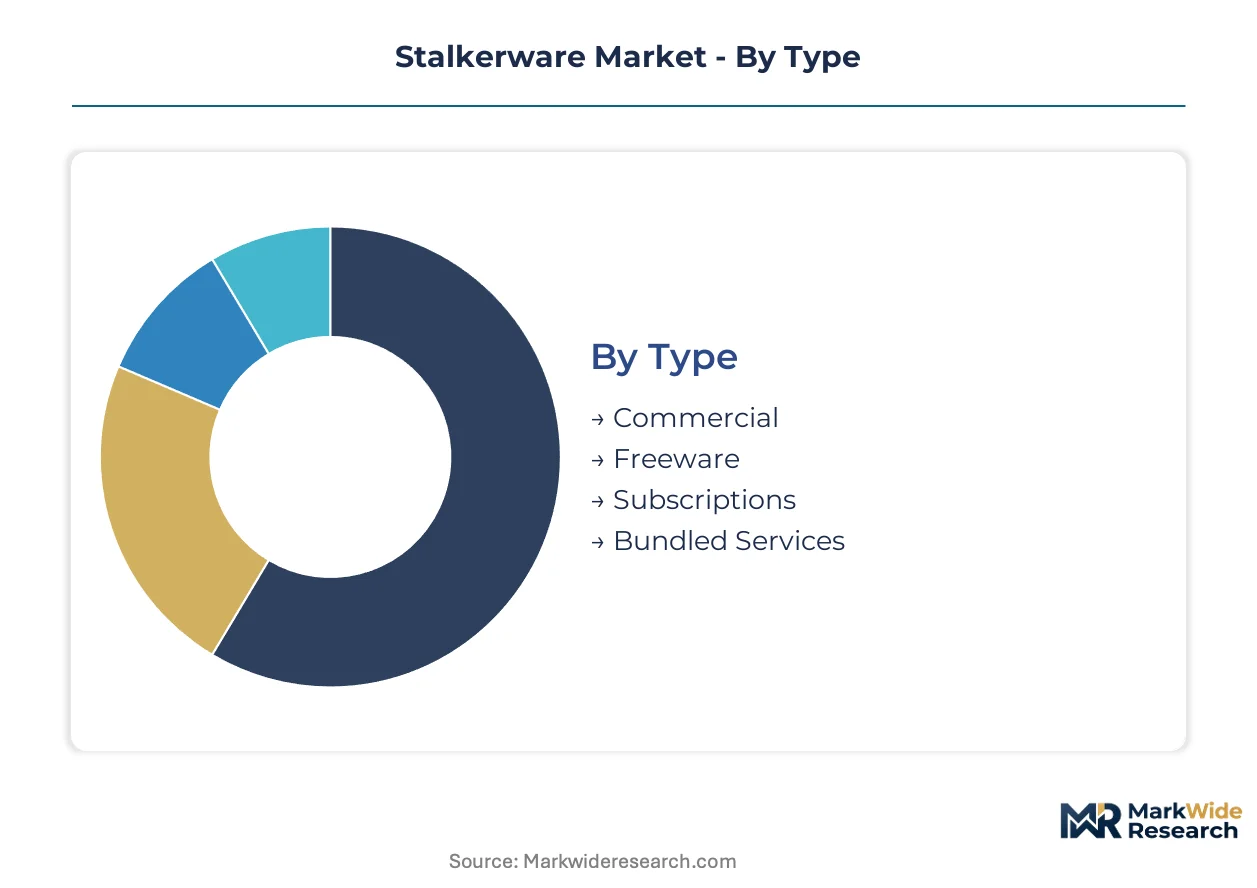
Stalkerware segmentation reveals how surveillance capabilities distribute across technical sophistication tiers and user risk profiles. Deployment models and pricing architectures determine accessibility for domestic abusers versus corporate operators. Feature differentiation separates commodity monitoring from specialized interception tools.
Type:
Mature subscription frameworks now dominate revenue capture, while freeware distribution persists at the entry tier.
- Commercial:Licensed software sold through direct vendor channels carries premium pricing for technical support and feature depth. Law enforcement procurement in the United States and corporate security budgets in Brazil concentrate demand here, though FTC scrutiny of deceptive marketing compresses margin expansion.
- Subscriptions:Recurring billing models with automatic renewal mechanisms lock operators into sustained revenue streams. Tiered feature gating—basic location monitoring versus full message interception—extracts maximum lifetime value from domestic abusers and private investigators.
- Freeware:Open-source or ad-supported tools lower barriers for technically unsophisticated users. Limited functionality and higher detection rates constrain penetration to experimental or low-budget surveillance contexts.
- Bundled Services:Surveillance capabilities packaged with device management or parental control software obscure true functionality. GDPR enforcement against misleading categorization pressures vendors serving European users to unbundle or geofence offerings.
Subscriptions retain volume leadership; bundled services hold the steepest expansion curve as vendors seek regulatory camouflage.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from operational expenditure cloud models.
- Cloud-Based:Browser-accessible dashboards eliminate local infrastructure requirements. Non-technical operators across India and Brazil drive adoption through simplified remote monitoring workflows, though payment processor deplatforming forces reliance on cryptocurrency rails.
- Mobile:Android APK sideloading dominates distribution volume outside regulated app stores. Accessibility service exploitation sustains message interception as Google Play Protect detection advances increase technical maintenance burdens.
- On-Premise:Self-hosted infrastructure serves enterprise and government clients with data sovereignty requirements. High upfront costs and specialized IT expertise limit addressable market to well-resourced investigative agencies.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud dashboards for remote access. Jurisdictional fragmentation between EU data residency requirements and operational flexibility demands drives niche adoption.
Mobile deployment captures the broadest user base; cloud-based architectures climb the fastest as technical barriers erode.
End User:
Customer type concentration spans domestic surveillance, corporate security, and sanctioned investigative applications.
- Individuals:Intimate partner monitoring represents the dominant unauthorized use case. Limited digital literacy in India and Brazil amplifies vulnerability to covert installation through social engineering.
- Enterprises:Corporate espionage and insider threat monitoring drive licensed procurement. Legal ambiguity around employee consent requirements varies by jurisdiction, constraining standardized product development.
- Law Enforcement:Warrant-backed surveillance operates through formal procurement channels. Vendor qualification requirements and audit trails separate legitimate government use from commercial stalkerware.
- Investigative Agencies:Private investigators demand consumption-scaled billing tied to active monitoring seats. United States law firms increasingly reject perpetual licenses for operational intelligence tooling.
Individuals retain volume leadership; investigative agencies hold the steepest expansion curve as procurement professionalizes.
Feature:
Application criticality stratifies basic monitoring from advanced interception capabilities.
- Remote Access:Real-time device control and file exfiltration require elevated system permissions. Kernel-level rootkit migration to accessibility frameworks sustains functionality as OEM security patches proliferate.
- Location Tracking:GPS and Wi-Fi positioning data serve domestic abusers seeking physical surveillance patterns. EU AI Act prohibitions on predictive behavioral analysis force feature geofencing for European users.
- Keylogging:Keystroke capture intercepts credentials and message composition before encryption. Detection by mobile security suites elevates technical maintenance costs for evasion engineering.
- Screen Capture:Periodic or triggered screenshots bypass end-to-end encryption by capturing displayed content. Storage and bandwidth requirements constrain deployment to high-priority targets.
Remote access retains volume leadership; location tracking holds the steepest expansion curve as telehealth adoption expands the medical communications attack surface.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR Article 58 enforcement and felony facilitation statutes are reshaping where stalkerware vendors establish data processing infrastructure and sales operations. Jurisdictional fragmentation between strict European privacy regimes and enforcement gaps elsewhere concentrates vendor activity in specific national markets.
United States
Domestic abusers and private investigators drive demand through subscription auto-renewal models. The FTC scrutinizes deceptive marketing practices while California and New York criminalize commercial distribution. Silicon Valley hosts infrastructure providers serving dashboard architectures despite payment processor deplatforming pressures.
Brazil
Limited digital literacy and smartphone penetration expansion create vulnerable user bases for covert installation. ANVISA coordinates with the national data protection authority on health-adjacent privacy violations. São Paulo concentrates investigative agency procurement of licensed surveillance tools.
Germany
GDPR enforcement by federal and state data protection authorities imposes substantial penalties for unlawful cross-border transfers. The EU AI Act prohibits predictive behavioral analysis features for vendors serving German users. Berlin hosts compliance-oriented operators restructuring data processing subsidiaries.
India
Smartphone adoption outpaces digital security awareness among target populations. The Information Technology Act provides limited specific criminalization of stalkerware distribution. Mumbai and Bangalore concentrate technical talent for accessibility service exploitation engineering.
United Kingdom
Domestic violence legislation tightens vendor accountability for intimate partner surveillance facilitation. The Information Commissioner's Office enforces GDPR-derived standards on data processing transparency. London serves as a coordination hub for investigative agency procurement professionalization.
Stalkerware Market Competitive Landscape
Channel-controlling players compete with product-specialist players across subscription billing and technical interception capabilities. The vendor base organizes around three archetypes: recurring revenue optimizers leveraging auto-renewal lock-in, deep technical specialists maintaining cross-platform exploitation capabilities, and price-accessibility competitors capturing entry-tier demand. Dominant competitive moves include jurisdictionally-agnostic hosting infrastructure establishment and feature geofencing for regulatory compliance.
Within the recurring revenue archetype, mSpy exemplifies subscription model optimization across multiple device platforms. FlexiSPY anchors the technical specialization tier through deep cross-platform interception engineering. ClevGuard occupies the price-accessibility position for entry-tier monitoring tools in cost-sensitive markets.
| Leading Market Players |
|---|
| mSpy |
| FlexiSPY |
| Cocospy |
| Spyzie |
| Spyic |
| Eyezy |
| Spynger |
| ClevGuard |
| Phonsee |
| Others |
Value Network & Pricing Analysis
Payment processor deplatforming by Stripe and PayPal determines both tiered subscription spreads and offshore banking infrastructure requirements across the stalkerware sector. This regulatory chokepoint forces vendors toward cryptocurrency rails and shell-company arrangements that compress margins at the entry tier while inflating operational overhead for compliance-agnostic operators.
Pricing Analysis
Feature depth creates the primary spread between premium interception suites and basic monitoring tools. Three-tier pricing structure across premium, standard, and economy levels extracts maximum lifetime value through automatic renewal mechanisms and tiered access to kernel-level capabilities. Cost compression in the economy tier intensifies because detection evasion engineering consumes disproportionate technical resources. Private investigators and law firms demonstrate least price sensitivity due to operational intelligence procurement budgets, while individual domestic abusers concentrate in cost-sensitive entry segments.
Supply Chain Analysis
US Commerce Department export controls on intrusion software under Wassenaar Arrangement restrictions limit cross-border flows of surveillance capabilities to certain national markets. Technical development concentrates in India, Russia, and Israel where exploit engineering talent pools and permissive regulatory environments coexist. Zero-day acquisition from brokers in these jurisdictions draws from undisclosed Android and iOS vulnerability markets. Single-source vulnerability in exploit broker relationships creates supply chain fragility when brokers face law enforcement takedown. Distribution runs through direct-to-consumer websites, encrypted messaging channels, and affiliate networks rather than conventional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free and open-source surveillance tools represent a substitution threat that commercial vendors must navigate through technical differentiation and service bundling. Incumbents face pressure to demonstrate value beyond commodity interception capabilities as barrier-free alternatives proliferate.
For Market Incumbents: Entrench market position through backward integration into exploit development capabilities rather than broker dependency, and establish jurisdictionally-agnostic hosting infrastructure to survive payment processor deplatforming. Kernel-level detection advances by Google Play Protect threaten technical moats; sustained R&D investment in accessibility framework exploitation maintains interception reliability against platform security hardening.
For New Entrants and Emerging Players: Medical communications interception within telehealth-adjacent surveillance represents the most penetrable entry point as healthcare data flows expand attack surfaces. Brazil's LGPD enforcement gap offers regulatory arbitrage opportunity relative to European compliance burdens. Go-to-market execution should emphasize consumption-scaled billing aligned with private investigator procurement professionalization rather than perpetual license models.
For Investors and Strategic Acquirers: The market sits at a regulatory escalation phase that favors technical specialists with deep cross-platform exploitation capabilities over pure subscription optimizers. Long-term viability across a 5-10 year window hinges on adaptation to felony facilitation statutes criminalizing commercial distribution. Acquisition target archetype: vendors with established jurisdictionally-agnostic infrastructure and in-house zero-day research programs. Signal to watch: coordinated payment processor blacklisting expansion beyond Stripe and PayPal to cryptocurrency exchanges.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Day Capability Buildout | In-house exploit research reduces dependency on premium broker pricing and law enforcement exposure. |
| Jurisdictional Arbitrage Structuring | Non-EU data processing subsidiaries enable feature availability despite EU AI Act prohibitions. |
| Cryptocurrency Payment Integration | Alternative rails survive Stripe and PayPal deplatforming that terminates conventional merchant accounts. |
| IoT Convergence Engineering | Smart home and wearable interception expands exfiltration channels beyond saturated smartphone monitoring. |
| Regulatory Camouflage Repositioning | Parental control and device management bundling obscures true surveillance functionality from app store policies. |
Research Methodology
A standing panel of surveillance software developers, digital forensics investigators, domestic violence shelter technology specialists, and payment risk compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FTC enforcement actions, GDPR Article 58 penalty registers, SEC filings by listed cybersecurity vendors, and academic research on intimate partner violence technology facilitation. Bottom-up triangulation of vendor pricing and subscription volumes against top-down market sizing from regulatory penalty data and infrastructure hosting analysis ensured analytical consistency.
Scenario-bracketing around regulatory enforcement intensity and platform security hardening pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, pricing model, end-user category, and feature sophistication tier, with cross-cutting analysis of jurisdictional regulatory cluster effects. CAGRs derived from trajectory fitting against historical enforcement wave impacts and smartphone adoption curves in target markets. Forecast inputs incorporated exploit broker pricing indices and mobile security suite detection rate improvements.
Practitioners should monitor payment processor blacklisting expansion, felony facilitation statute adoption across US states, and Google Play Protect detection algorithm updates for early signals of structural market contraction. Forecasts reflect assumptions regarding sustained Android sideloading permissiveness and limited international coordination on surveillance software criminalization. Material shifts in platform security architecture or coordinated multilateral enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Italy Endpoint Detection and Response Market
Security Software
Europe User Provisioning Market
Security Software
Digital Risk Protection Software Market
Security Software
Information Rights Management Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Communication Encryption Software Market
Security Software
Robocall Mitigation Market
Security Software
US Evidence Management Market
Security Software
Mass Notification System Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
US Hardware Encryption Market
Security Software
Data Masking Technology Market
Security Software
Global Electronic Passports Market