
 Brazil Aesthetic Equipment Market | 2026-2036
Brazil Aesthetic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Aesthetic Equipment Market Outlook
ANVISA's tightened medical device registration pathways is consolidating procurement standards across Brazilian aesthetic practices. Lumenis leverages its established service infrastructure to sustain recurring revenue from high-use laser platforms in major metro markets. Alma Lasers (Sisram Medical Ltd) anchors its position through localized technical support and training academies that reduce clinician onboarding friction. Cutera Inc. competes by specializing in multi-wavelength systems that address diverse skin phototypes prevalent in Brazil's population.
Brazil aesthetic equipment encompasses electromechanical and energy-based systems engineered to deliver controlled thermal, mechanical, or optical effects to cutaneous or subcutaneous tissue, typically operating at wavelengths between 400 nm and 10,600 nm with pulse durations calibrated to target specific chromophores or tissue structures. These systems serve commercial purposes across dermatology clinics, cosmetic surgery centers, and medical spas seeking to offer procedures that substitute for or complement surgical intervention. Laser devices occupy the largest revenue pool given their versatility across hair removal and skin rejuvenation protocols, while radiofrequency equipment represents the fastest-expanding category as practitioners adopt fractional and microneedling-integrated platforms for collagen remodeling. Non-invasive technologies dominate transaction volumes, though hybrid systems command premium positioning by combining multiple energy modalities within single treatment sessions.
ANVISA governs product registration, clinical evidence requirements, and post-market surveillance for all imported and domestically manufactured aesthetic devices, while INMETRO certification mandates electrical safety and electromagnetic compatibility testing prior to commercialization. The Brazilian Ministry of Health's periodic updates to medical device risk classifications directly influence which products require full clinical trial dossiers versus streamlined notification pathways, reshaping importer strategies and domestic assembly incentives. Stakeholders must monitor pending ANVISA resolutions on software-controlled devices and artificial intelligence-integrated diagnostic modules, as these frameworks will determine market access timelines for next-generation platforms.
Market Dynamics
ANVISA's 2024 medical device reclassification is forcing importers to rebuild entire registration dossiers, compressing market access timelines and concentrating procurement authority among distributors with established regulatory infrastructure.
Growth Catalysts
- Radiofrequency fractional platforms:Dermatology clinics in São Paulo and Rio de Janeiro are expanding device fleets to meet rising patient volumes for collagen remodeling procedures.
- ANVISA notification pathway streamlining:Lower-risk device categories now qualify for accelerated registration, reducing time-to-market for select energy-based systems.
- Southeast regional income concentration:Disposable income levels and clinic density in São Paulo, Minas Gerais, and Rio de Janeiro states outpace other Brazilian regions.
Market Restraints
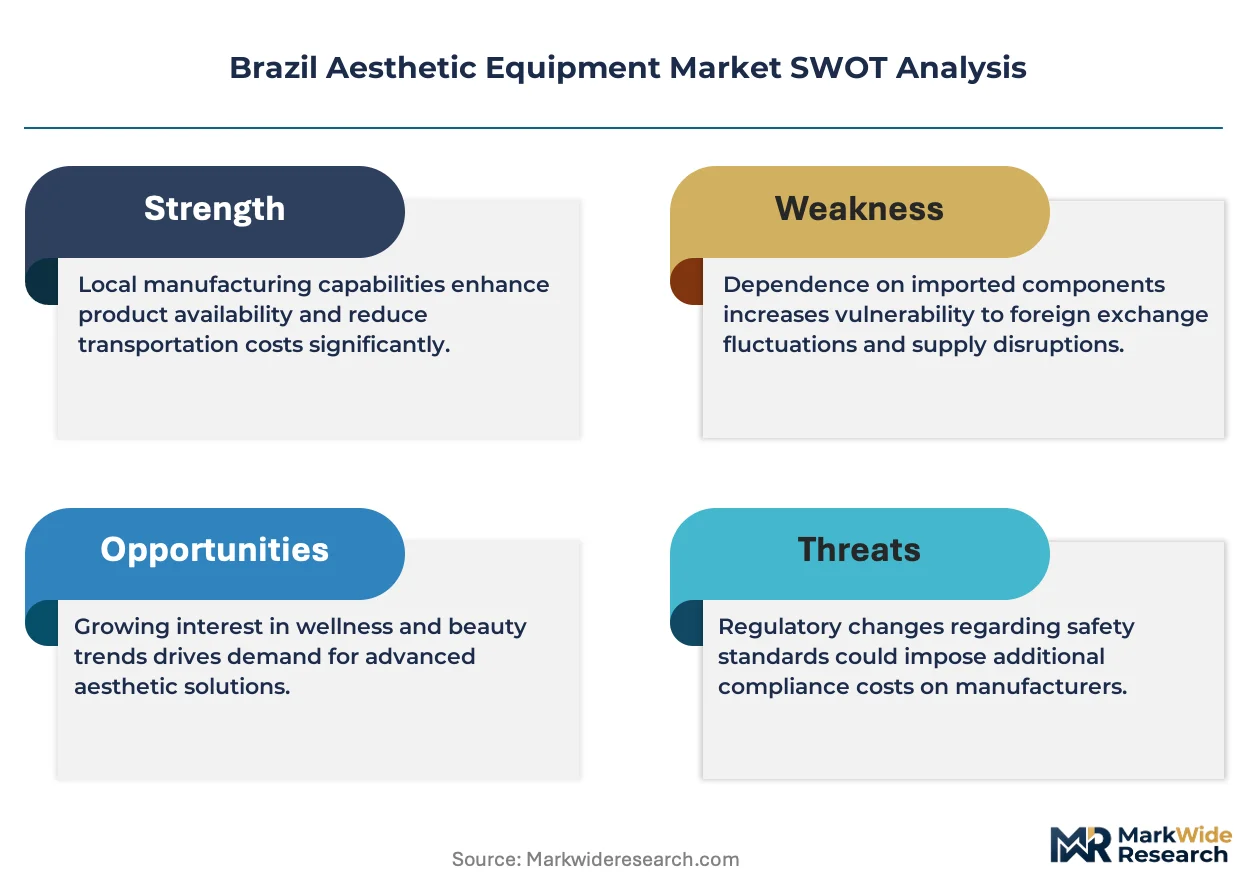
- Import duty structure:Electromechanical device tariffs elevate landed costs for laser and radiofrequency platforms sourced from Israeli and US manufacturers.
- Technical service infrastructure gaps:Remote states lack authorized repair technicians, extending equipment downtime and depressing utilization rates outside Southeast clusters.
- Currency volatility exposure:Real-dollar exchange rate swings directly impact importer margins and equipment pricing stability.
Strategic Opportunities
- Northeast and North regional expansion:Clinic penetration in Fortaleza, Recife, and Manaus remains substantially below Southeast benchmarks.
- AI-integrated diagnostic modules:ANVISA's pending software-controlled device framework will create first-mover advantages for platforms with embedded treatment planning algorithms.
- Hybrid modality convergence:Systems combining laser, radiofrequency, and microneedling within single platforms command premium positioning and reduce capital requirements per procedure type.
Industry Challenges
- Clinical training bandwidth:Safe operation of multi-wavelength systems requires certified technicians, and established training academies concentrate in São Paulo and Rio de Janeiro.
- INMETRO electrical safety certification delays:Electromagnetic compatibility testing backlogs extend pre-commercialization timelines by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Aesthetic Equipment Market |
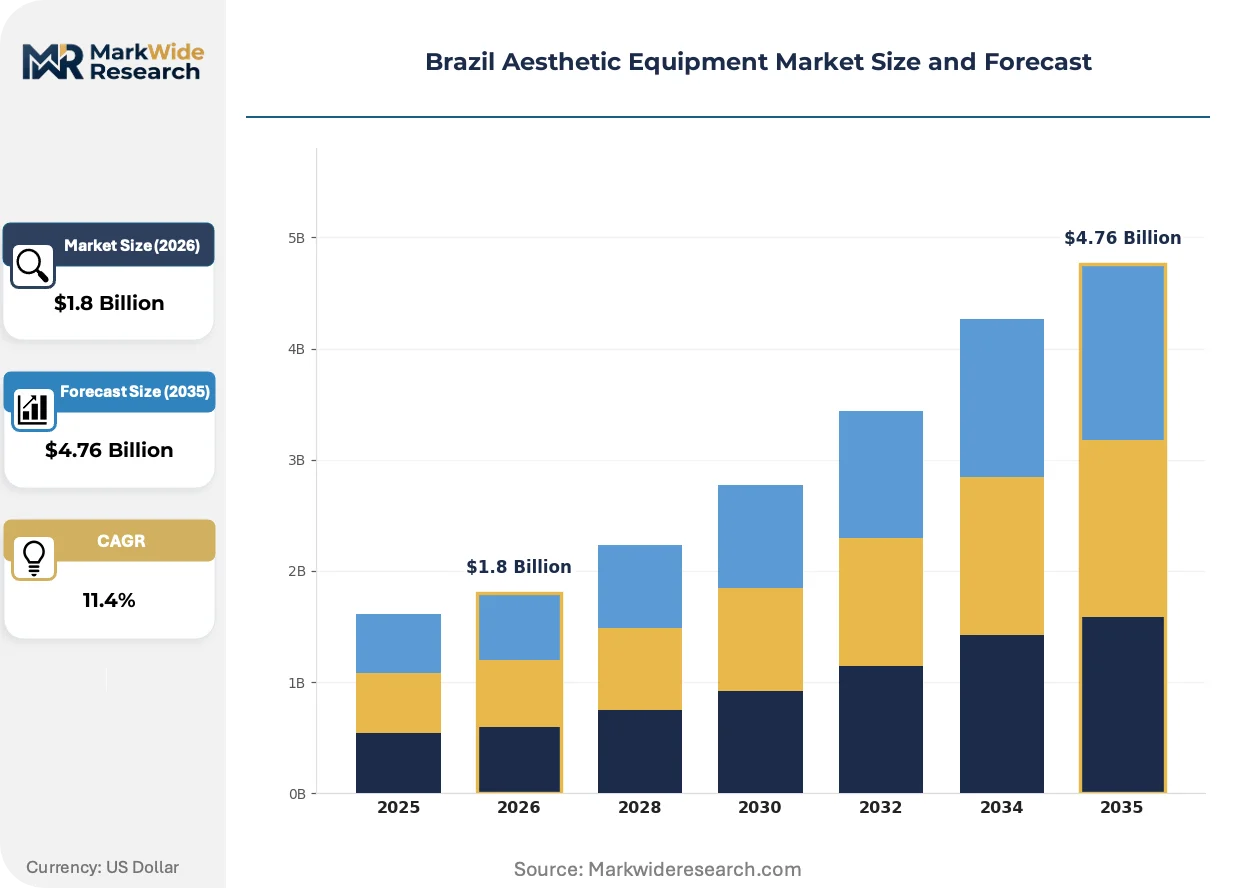
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Radiofrequency Equipment, Ultrasound Devices, Microdermabrasion Systems End User: Dermatology Clinics, Beauty Salons, Cosmetic Surgery Centers, Spas Technology: Non-Invasive Technologies, Invasive Technologies, Hybrid Systems, Combination Devices Application: Skin Rejuvenation, Hair Removal, Body Contouring, Acne Treatment |
| Companies Covered | Lumenis, Alma Lasers (Sisram Medical Ltd), Cynosure (Hologic), Cutera Inc., AbbVie (Allergan Aesthetics), Galderma, Merz Pharma GmbH & Co. KGaA, Ibramed, Candela Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Aesthetic Equipment Market Strategic Shifts
Device architecture is pivoting toward software-defined treatment protocols that reduce operator dependency while ANVISA prepares frameworks for artificial intelligence-integrated systems.
Picosecond laser technology is electrifying pigment and tattoo removal protocols through ultra-short pulse durations that minimize thermal diffusion. High-volume dermatology chains in São Paulo are replacing nanosecond platforms at fifteen-month replacement cycles. This compression is accelerating depreciation schedules and concentrating procurement decisions among multi-clinic operators with capital deployment capacity.
ANVISA's updated medical device risk classification rules are reshaping clinical evidence requirements for imported energy-based systems. Full dossier submissions now apply to fractional radiofrequency platforms previously eligible for notification pathways. Domestic assemblers in São Paulo state are responding by expanding local manufacturing to qualify for streamlined registration.
Clinic procurement patterns are fragmenting as independent practitioners bypass traditional distributors to source refurbished platforms through specialized secondary market channels. This disintermediation is most pronounced in Rio de Janeiro's cosmetic surgery corridor, where physician-owned facilities prioritize capital efficiency over manufacturer warranty coverage.
Brazil Aesthetic Equipment Market Segmentation
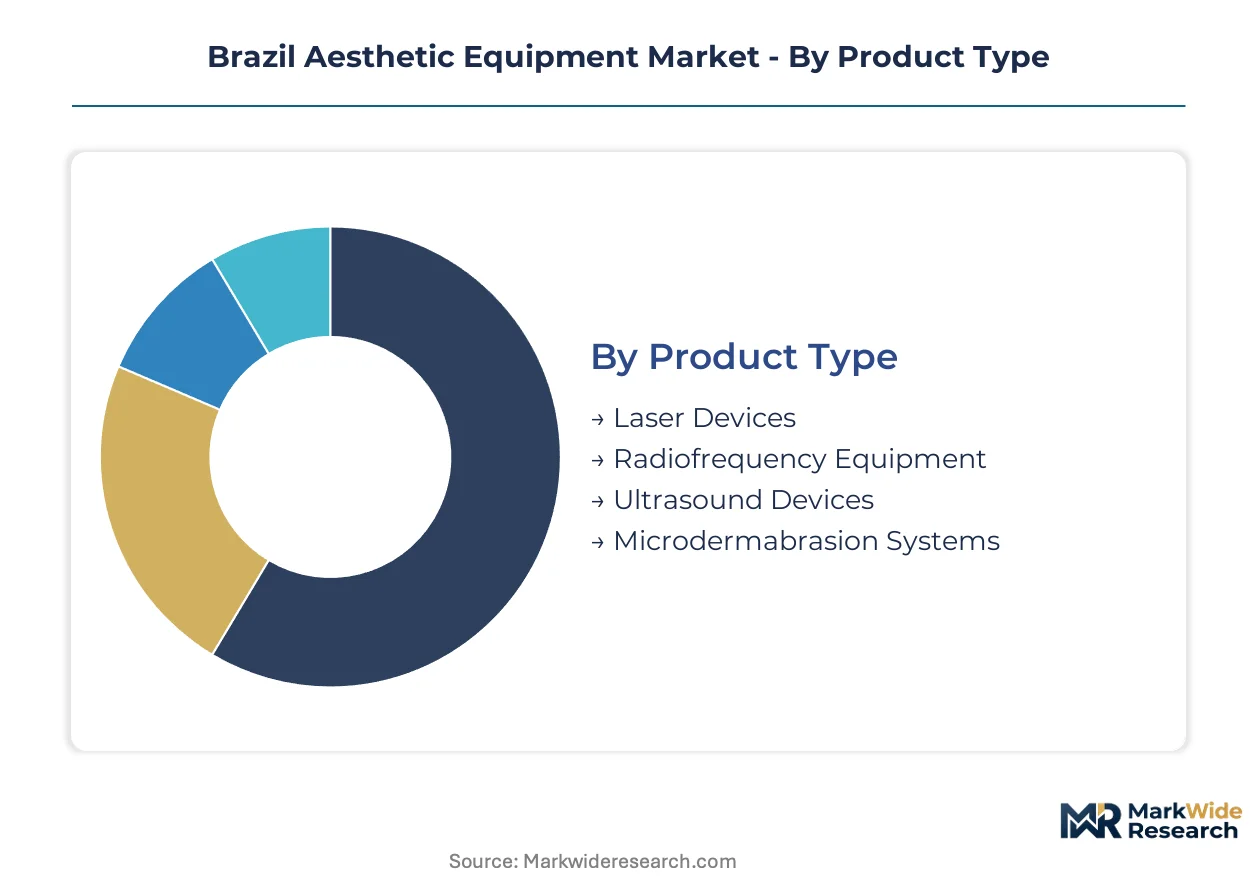
Segmentation in Brazil's aesthetic equipment market reflects divergent capital deployment strategies across clinic tiers and regional income disparities. Equipment procurement patterns cluster around procedure economics, with high-throughput metro operators favoring multi-modality platforms while independent practitioners optimize for single-technology utilization rates.
Product Type:
Laser devices command the volume premium, while radiofrequency equipment captures the steepest expansion trajectory among energy-based modalities.
- Laser Devices:These systems operate across 400 nm to 10,600 nm wavelengths with pulse durations calibrated to target melanin, hemoglobin, or water chromophores. São Paulo dermatology chains are replacing nanosecond platforms with picosecond architectures at compressed fifteen-month cycles to minimize thermal diffusion in pigment removal protocols.
- Radiofrequency Equipment:Fractional and microneedling-integrated platforms deliver controlled thermal injury to dermal collagen for remodeling applications. Rio de Janeiro cosmetic surgery centers are expanding device fleets to meet rising patient volumes for non-invasive tightening procedures.
- Ultrasound Devices:High-intensity focused ultrasound systems target subcutaneous adipose tissue at depths exceeding 4.5 mm for body contouring applications.
- Microdermabrasion Systems:Mechanical exfoliation platforms using aluminum oxide or diamond-tipped wands serve entry-level clinic segments with lower capital requirements.
Mature deployment sits with laser devices. Newer deployment is concentrated in radiofrequency equipment.
End User:
Procurement authority fragments across facility ownership structures, with physician-owned cosmetic surgery centers exhibiting distinct capital efficiency priorities compared to institutional dermatology chains.
- Dermatology Clinics:Multi-clinic operators in São Paulo and Rio de Janeiro concentrate procurement decisions for high-use laser platforms, leveraging established service infrastructure to sustain recurring revenue through maintenance contracts and consumable replenishment.
- Cosmetic Surgery Centers:Physician-owned facilities in Rio de Janeiro's aesthetic corridor increasingly source refurbished platforms through secondary market channels to optimize capital deployment, accepting reduced manufacturer warranty coverage for acquisition cost savings.
- Beauty Salons:Non-medical operators face ANVISA classification restrictions that limit device categories to lower-risk electromechanical systems.
- Spas:Wellness-oriented facilities prioritize non-invasive technologies with minimal operator certification requirements and reduced liability exposure.
Volume concentration favors dermatology clinics. Margin expansion opportunities cluster with cosmetic surgery centers.
Technology:
Hybrid architectures are displacing single-modality systems as capital efficiency pressures intensify across Brazilian aesthetic practices.
- Hybrid Systems:Platforms integrating laser, radiofrequency, and microneedling within single treatment sessions command premium positioning while reducing per-procedure-type capital requirements. ANVISA's pending software-controlled device framework will shape registration timelines for these complex architectures.
- Non-Invasive Technologies:Energy-based systems without epidermal breach dominate transaction volumes across Brazil's Southeast region, where disposable income levels support recurring treatment protocols.
- Invasive Technologies:Ablative laser and surgical adjunct systems require higher clinician certification tiers and carry elevated malpractice exposure.
- Combination Devices:Sequential-modality platforms allow treatment customization within single patient visits.
Non-invasive technologies anchor current installed base. Hybrid systems are gaining share fastest.
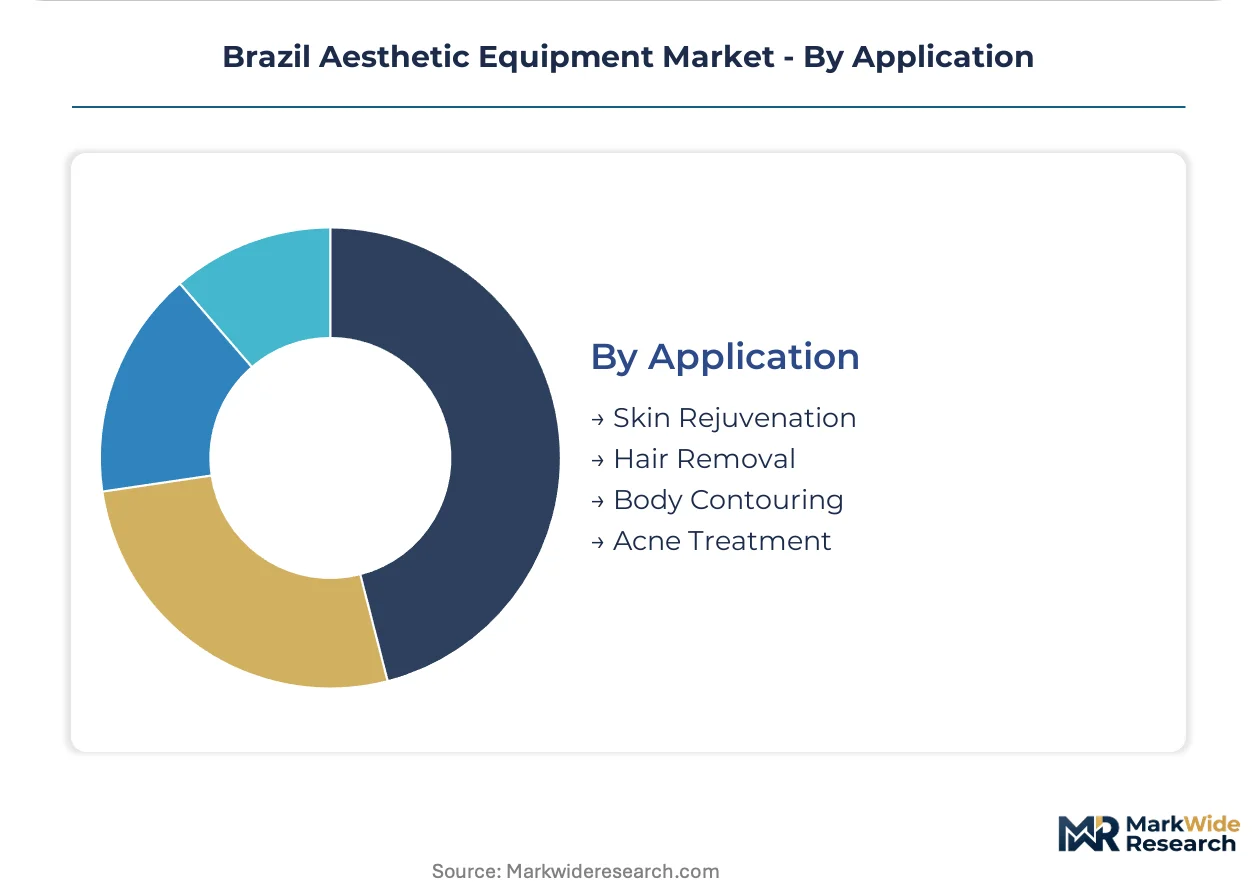
Application:
Procedure demand maps directly to Brazilian demographic characteristics, with skin phototype diversity and body composition patterns shaping technology selection.
- Skin Rejuvenation:Collagen remodeling protocols using fractional radiofrequency and non-ablative laser systems address photodamage across Fitzpatrick skin types prevalent in Brazil's population. Cutera Inc. competes through multi-wavelength configurations optimized for this diversity.
- Hair Removal:Alexandrite and diode laser platforms serve high-throughput metro clinics with established patient pipelines for maintenance protocols.
- Body Contouring:Cryolipolysis and high-intensity focused ultrasound systems target adipose tissue reduction without surgical intervention.
- Acne Treatment:Blue light photodynamic therapy and fractional platforms address inflammatory and scarring presentations.
Hair removal commands mature procedure volumes. Skin rejuvenation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan corridor concentrates Brazil's aesthetic equipment demand through its dense network of dermatology chains and cosmetic surgery centers that drive procurement volumes for energy-based systems.
São Paulo
São Paulo state hosts the highest clinic density and disposable income levels nationwide. ANVISA's updated medical device classification rules are accelerating compliance investments among domestic assemblers in the capital's industrial zones. Multi-clinic dermatology operators in São Paulo city are replacing nanosecond laser platforms with picosecond architectures at compressed fifteen-month cycles.
Rio de Janeiro
Rio de Janeiro's cosmetic surgery corridor generates concentrated demand for hybrid modality systems. INMETRO electrical safety certification mandates shape importer strategies for energy-based devices entering through the state's port infrastructure. Physician-owned facilities in Ipanema and Barra da Tijuca increasingly source refurbished platforms through secondary market channels to optimize capital deployment.
Minas Gerais
Minas Gerais exhibits growing clinic penetration in Belo Horizonte's medical services cluster. ANVISA notification pathway streamlining for lower-risk device categories is reducing time-to-market for select radiofrequency platforms. Technical service infrastructure gaps persist outside the capital, extending equipment downtime and depressing utilization rates in interior municipalities.
Rio Grande do Sul
Rio Grande do Sul represents a secondary demand center with Porto Alegre anchoring regional procurement. Currency volatility exposure affects importer margins for laser and radiofrequency equipment sourced from Israeli and US manufacturers. Local distributors are building authorized repair technician networks to address service coverage gaps that previously limited market development.
Bahia
Bahia and Brazil's Northeast region show substantial underpenetration relative to Southeast benchmarks. ANVISA's pending software-controlled device framework will determine market access timelines for next-generation platforms with embedded treatment planning algorithms. Salvador's emerging clinic clusters present expansion opportunities for distributors with established regulatory infrastructure.
Brazil Aesthetic Equipment Market Competitive Environment
Premium-margin players sit above commodity-margin players across service infrastructure depth and regulatory compliance capabilities. The vendor base stratifies into three tiers: established multinationals with ANVISA-registered portfolios, regional distributors with localized technical support, and secondary market operators supplying refurbished equipment. Market concentration favors players with captive service networks in São Paulo and Rio de Janeiro. Dominant competitive moves include geographic expansion into underpenetrated Northeast states and portfolio diversification toward hybrid modality platforms.
Within the multinational tier, Lumenis and Alma Lasers (Sisram Medical Ltd) exemplify archetypes built on recurring revenue from maintenance contracts and training academies. Cutera Inc. occupies a position representing specialization in multi-wavelength configurations. These three entities anchor the competitive structure through differentiated approaches to clinician onboarding and technical service coverage across Brazil's Southeast corridor.
| Leading Market Players |
|---|
| Lumenis |
| Alma Lasers (Sisram Medical Ltd) |
| Cynosure (Hologic) |
| Cutera Inc. |
| AbbVie (Allergan Aesthetics) |
| Galderma |
| Merz Pharma GmbH & Co. KGaA |
| Ibramed |
| Candela Medical |
| Others |
Value Chain & Pricing Dynamics
Picosecond laser platform adoption is compressing depreciation schedules to fifteen-month replacement cycles, simultaneously elevating capital intensity for high-throughput operators and concentrating procurement authority among multi-clinic chains with volume leverage. This technology transition reshapes cost economics by shortening payback periods while tilting pricing power toward distributors with captive service infrastructure in São Paulo and Rio de Janeiro.
Pricing Analysis
Outcome-based pricing anchored to procedure throughput dominates hybrid modality platforms, with premium tiers commanding positioning through bundled training academy access and maintenance uptime guarantees. Price differentiation hinges on ANVISA registration tier and localized technical support depth. Cost compression in refurbished equipment channels is intensifying because physician-owned cosmetic surgery centers in Rio de Janeiro prioritize capital efficiency over manufacturer warranty coverage. Independent practitioners exhibit highest price sensitivity; institutional dermatology chains with captive service networks demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Israeli and US laser component manufacturers, where optical resonator and cooling system fabrication concentrates. Domestic assembly in São Paulo state draws from German precision optics, Japanese solid-state electronics, and Chinese aluminum chassis fabrication. Supply chain risk centers on Real-dollar exchange rate volatility affecting landed costs for electromechanical platforms. Distribution runs through authorized distributors with ANVISA-registered portfolios, though secondary market channels are fragmenting procurement patterns in Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's tightened medical device reclassification functions as the binding capacity constraint, propping pricing power among incumbents with established regulatory infrastructure while compressing margins for importers forced to rebuild registration dossiers.
For Market Incumbents: Acquire authorized repair technician networks in Brazil's Northeast and North regions to preempt service coverage gaps that depress utilization rates. Consolidate procurement authority by embedding software-defined treatment protocols that reduce operator dependency and lock in recurring maintenance revenue. Threat substitution from AI-integrated diagnostic modules demands certification investment ahead of ANVISA's pending framework. For New Entrants and Emerging Players: Physician-owned cosmetic surgery centers in Fortaleza, Recife, and Manaus represent the most penetrable buyer archetype, with clinic density substantially below Southeast benchmarks. White-space targets include fractional radiofrequency platforms for collagen remodeling protocols and refurbished laser systems with localized warranty coverage. Go-to-market angle: partner with established São Paulo training academies to reduce clinician onboarding friction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational device manufacturers seeking ANVISA-registered portfolios and captive service networks. Long-term viability favors domestic assemblers with backward integration into precision component sourcing and software-controlled device capabilities. Signal to watch: ANVISA resolution timeline on artificial intelligence-integrated diagnostic modules as inflection indicator for next-generation platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Dossier Rebuild | Accelerated compliance investments consolidate procurement authority among distributors with established regulatory infrastructure. |
| Localized Technical Support Expansion | Authorized repair networks in remote states reduce equipment downtime and capture margin from service-deprived markets. |
| Hybrid Modality Platform Development | Systems combining laser, radiofrequency, and microneedling command premium positioning while reducing per-procedure capital requirements. |
| Training Academy Partnership | Collaboration with São Paulo and Rio de Janeiro academies reduces clinician onboarding friction for new platform adoption. |
| Secondary Market Channel Integration | Refurbished equipment sourcing addresses capital efficiency priorities of physician-owned cosmetic surgery centers. |
Study Parameters
Multi-period observation of ANVISA registration timelines, clinic fleet expansion rates, and device replacement cycles anchored the trend analysis, supplemented by interviews with biomedical engineers, dermatology clinic procurement directors, ANVISA regulatory consultants, and authorized distributor operations managers. Secondary validation drew from ANVISA medical device registration databases, INMETRO certification records, hospital procurement systems, and import customs data. Bottom-up equipment deployment tracking triangulated against top-down market sizing across the analysis window.
Segment-weighting approach distributed value estimates across product type, end user, technology, and application dimensions, with regional income concentration and clinic density as cross-cutting modifiers. CAGRs were derived from fitted growth curves applied to equipment shipment data and maintenance contract values. Forecast inputs incorporated ANVISA regulatory pathway timelines and currency volatility assumptions affecting importer margins.
Revisions become necessary when ANVISA finalizes software-controlled device frameworks, when Real-dollar exchange rate movements exceed historical bands, or when domestic assembler capacity expansion accelerates beyond projected timelines. Forecasts reflect documented assumptions about regulatory pathway efficiency and regional clinic penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Global External Fixators Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
IV Fluid Transfer Drugs Devices Market