
 Brazil Diagnostic Imaging Equipment Market | 2026-2036
Brazil Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Diagnostic Imaging Equipment Market Outlook
Market Context
Artificial intelligence integration into radiology workflows is rewriting how Brazilian providers interpret scans and manage imaging throughput. Siemens Healthineers leverages its digital platform footprint to anchor service contracts across major hospital networks in São Paulo and Rio de Janeiro. GE Healthcare sustains manufacturing scale through its established Brazilian assembly operations, competing on localization and aftermarket service density. Koninklijke Philips differentiates through advanced MRI spectroscopy capabilities targeted at neurological applications in academic medical centers.
Technical Definition and Segments
Diagnostic imaging equipment encompasses electromechanical systems that generate visual representations of internal body structures using ionizing radiation, magnetic fields, acoustic waves, or radioactive tracers, with spatial resolution thresholds ranging from sub-millimeter for CT to micrometer-scale for specialized digital X-ray detectors. These systems serve primarily to enable non-invasive disease detection, treatment planning, and interventional guidance across clinical settings. Ultrasound systems lead volume deployment in Brazil's municipal health networks due to lower capital requirements and minimal infrastructure demands, while MRI and CT Scan categories capture disproportionate value concentration tied to oncology and cardiovascular application growth. Digital technology platforms are displacing analog installations fastest in private imaging centers, though hybrid systems retain installed base relevance in budget-constrained public facilities.
Regulatory Environment
ANVISA governs medical device registration and post-market surveillance for diagnostic imaging equipment in Brazil, with specific technical standards for radiation-emitting systems that manufacturers must satisfy before commercialization. The national complementary health regulator supplements ANVISA oversight by accrediting imaging facilities for private insurance reimbursement eligibility, directly shaping provider investment decisions. Brazil's adherence to Mercosur harmonized technical regulations facilitates cross-border equipment certification while maintaining country-specific electromagnetic compatibility testing requirements. Stakeholders must monitor ANVISA's ongoing alignment with international medical device single audit program standards to anticipate streamlined conformity assessment pathways.
Market Dynamics
Artificial intelligence integration into radiology workflows is compressing scan interpretation timelines and forcing equipment vendors to bundle algorithmic modules with hardware contracts across Brazilian hospital networks.
Growth Catalysts
- ANVISA's streamlined registration pathways:Compressed approval timelines for digital imaging platforms accelerate commercialization of next-generation CT and MRI systems.
- Southeast regional hospital expansion:Public networks in São Paulo and Minas Gerais are procuring high-field MRI systems to reduce oncology patient wait times.
- AI-enabled image reconstruction:Deep learning algorithms reduce scan acquisition times by half, expanding throughput capacity in saturated diagnostic centers.
Market Restraints
- Import dependency for superconducting magnets:Brazil lacks domestic cryogenic component manufacturing, exposing buyers to currency fluctuation risk and extended lead times.
- ANVISA electromagnetic compatibility testing:Country-specific certification requirements add 4-6 months to product launch timelines versus Mercosur harmonized standards alone.
- Helium supply concentration:Global helium refining capacity constraints drive recurrent price volatility for MRI system coolants.
Strategic Opportunities
- North and Northeast regional penetration:Manaus and Recife diagnostic imaging centers operate at 40% equipment density versus Southeast levels.
- Portable ultrasound for primary care:Municipal health networks in Ceará and Piauí are piloting point-of-care devices for rural maternal screening.
- Interoperable cloud PACS integration:ANVISA's alignment with international medical device single audit program standards enables cross-border data architecture deployment.
Industry Challenges
- Trained radiologist scarcity:Brazil produces 400 new radiologists annually against demand for 1,200, forcing equipment utilization below optimal thresholds.
- Legacy analog system integration:Hybrid digital-analog workflows in budget-constrained public facilities complicate AI algorithm deployment and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Diagnostic Imaging Equipment Market |
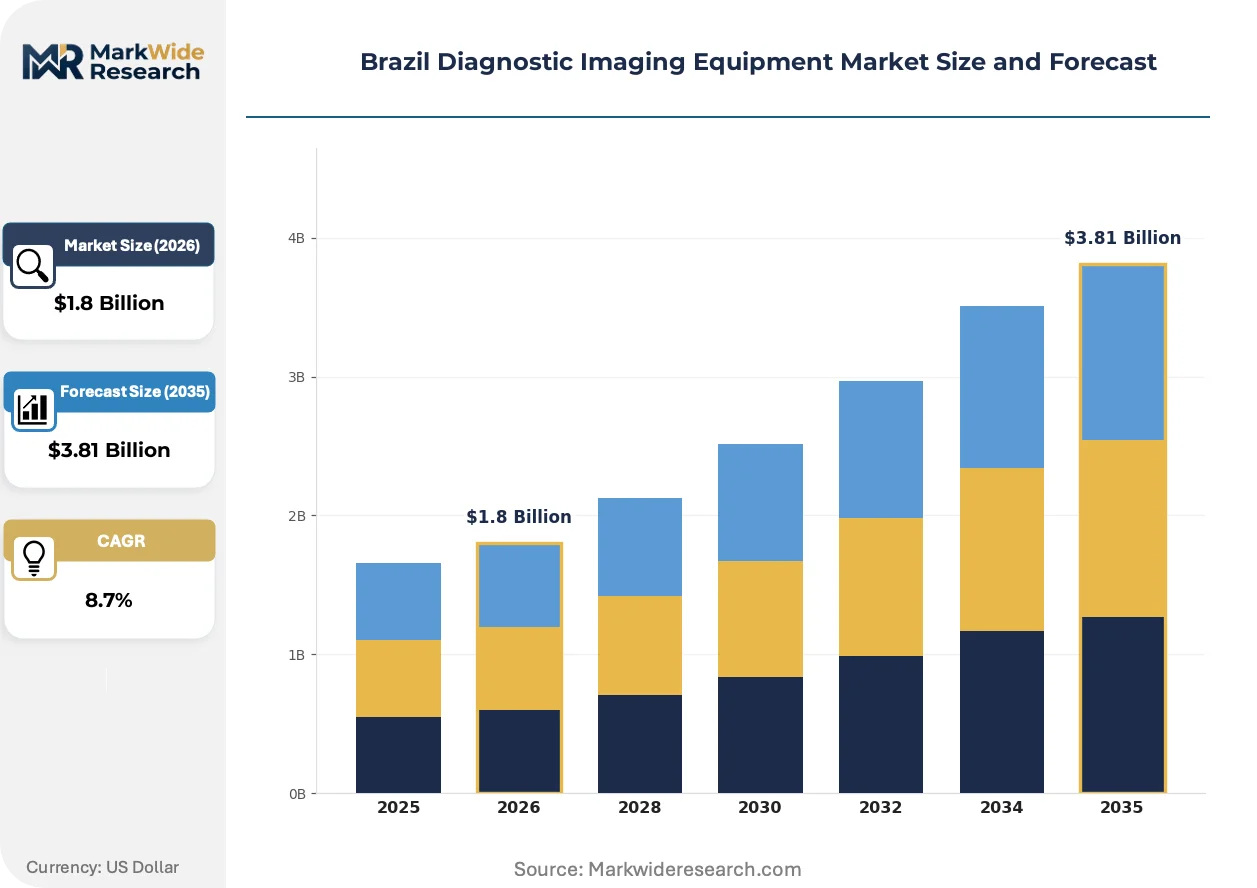
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scan, Ultrasound Technology: Digital, Analog, Hybrid, 3D Imaging End User: Hospitals, Clinics, Imaging Centers, Research Facilities Application: Oncology, Cardiovascular, Neurology, Orthopedics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings, United Imaging Healthcare, Mindray, Shimadzu Corporation, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Diagnostic Imaging Equipment Market Strategic Shifts
Digital platforms are displacing analog installations fastest in private imaging centers, while hybrid systems retain installed base relevance where capital constraints persist.
Photon-counting CT detector technology is hybridizing spectral imaging capabilities with conventional hardware architectures. Academic medical centers in São Paulo and Rio de Janeiro are piloting these systems for cardiovascular calcium scoring. This convergence is hybridizing hardware differentiation strategies, compressing the premium imaging tier into mid-range price bands.
ANVISA's updated technical standards for radiation-emitting medical devices mandate dose monitoring software integration. Manufacturers must now embed real-time exposure tracking across CT and fluoroscopy platforms. Private imaging centers in Belo Horizonte are accelerating compliance investments to maintain accreditation with the national complementary health regulator.
Service contract unbundling is fragmenting traditional vendor-captive maintenance relationships. Independent service organizations are capturing 30% of aftermarket revenue in São Paulo's diagnostic imaging center cluster. This disintermediation is most visible among mid-sized private operators seeking to reduce total cost of ownership on depreciated MRI and CT assets.
Brazil Diagnostic Imaging Equipment Market Segmentation
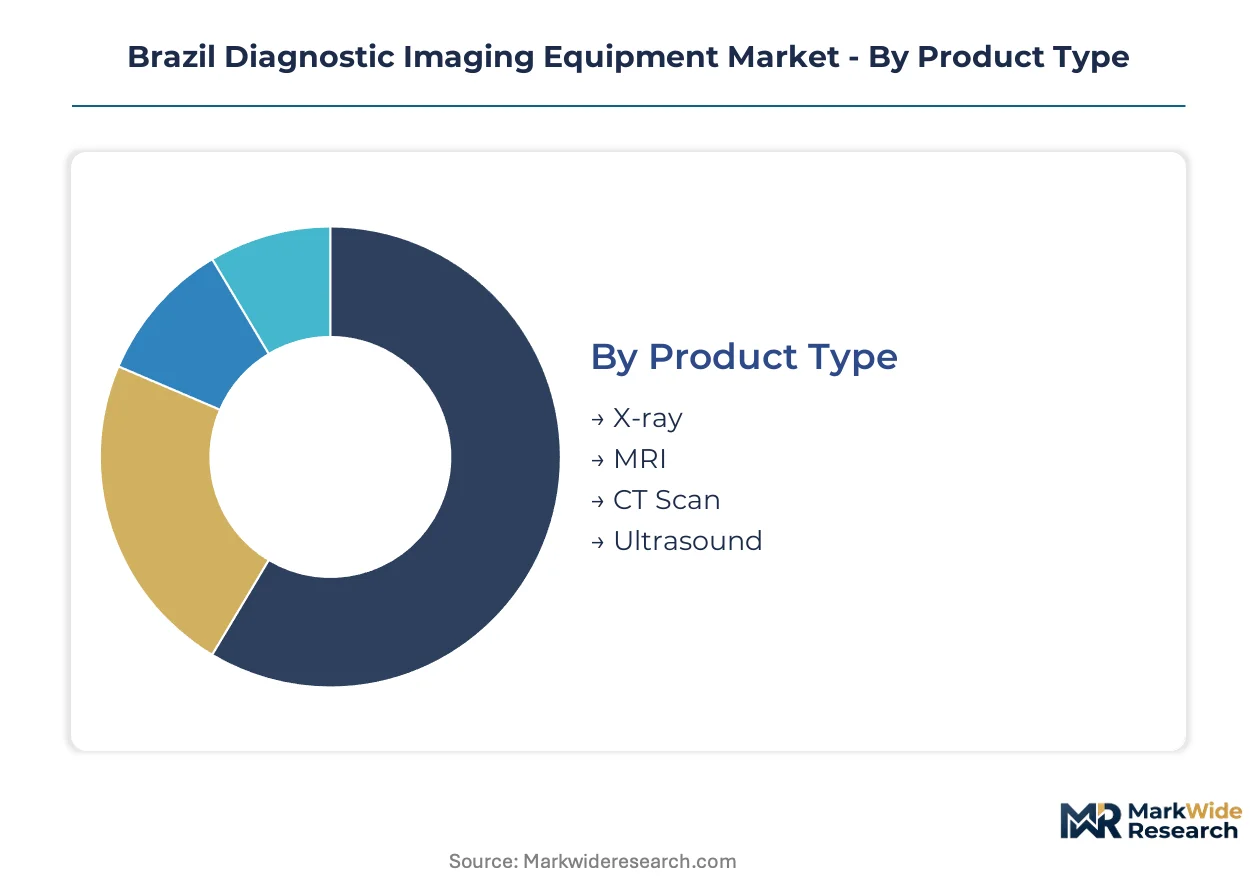
Segmentation reveals how capital intensity, reimbursement pathways, and clinical specialization fragment procurement patterns across Brazilian healthcare infrastructure. Equipment vendors configure product portfolios and service networks around these fault lines to capture volume in public tenders and private imaging chains.
Product Type:
Capital tier stratifies the installed base, with superconducting systems commanding premium pricing against portable modalities deployed in municipal networks.
- MRI:Superconducting systems with 1.5T and 3.0T field strengths dominate oncology and neurological diagnostics. Academic medical centers in São Paulo and Rio de Janeiro concentrate demand for high-field systems as ANVISA compresses registration timelines for next-generation platforms.
- CT Scan:Multi-slice helical architectures with photon-counting detector upgrades are displacing conventional hardware in private imaging centers. Cardiovascular calcium scoring applications in Belo Horizonte drive replacement cycles as dose monitoring software becomes mandatory under updated technical standards.
- X-ray:Digital radiography panels with wireless detector technology serve high-throughput emergency departments.
- Ultrasound:Portable systems with convex and linear transducer configurations penetrate primary care networks in Ceará and Piauí.
CT Scan holds installed capacity. MRI is rotating up the share rankings.
Technology:
Digital maturity divides the market between fully integrated PACS-compatible platforms and legacy analog infrastructure requiring hybrid transition pathways.
- Digital:Direct radiography and fully digital acquisition chains enable AI-enabled reconstruction algorithms. Private imaging centers in São Paulo accelerate analog-to-digital conversion to capture service contract unbundling opportunities and reduce total cost of ownership.
- Hybrid:Digital-analog transitional architectures retain relevance in budget-constrained public facilities where capital replacement cycles extend beyond typical depreciation periods.
- 3D Imaging:Volumetric reconstruction capabilities with multiplanar visualization serve orthopedic surgical planning.
- Analog:Screen-film and computed radiography systems persist in remote municipalities with limited technical service access.
Digital platforms anchor vendor service contracts. Hybrid configurations are climbing fastest as public networks phase replacements.
End User:
Customer type determines procurement modality, with centralized tenders dominating public hospital networks and lease-to-own structures prevailing among private operators.
- Imaging Centers:Specialized diagnostic facilities with high patient throughput optimize equipment utilization through extended operating hours and multi-specialty referral networks. Independent service organizations capture aftermarket revenue as these operators unbundle from manufacturer-captive maintenance agreements.
- Hospitals:Integrated acute care facilities with emergency and inpatient demands require 24/7 system availability and rapid turnaround protocols. Public networks in Minas Gerais expand MRI procurement to reduce oncology patient wait times.
- Clinics:Outpatient-focused practices with lower volume demands prioritize compact footprint and simplified operator interfaces.
- Research Facilities:Academic medical centers with clinical trial portfolios require advanced spectroscopy and functional imaging capabilities.
Imaging Centers concentrate vendor competition. Hospitals are gaining share fastest as public tenders accelerate.
Application:
Clinical specialization drives modality selection, with oncology and cardiovascular pathways commanding the highest reimbursement intensity and equipment specification requirements.
- Oncology:Staging and treatment monitoring applications require multi-parametric MRI and PET-CT hybrid systems with quantitative biomarker extraction. Southeast regional hospital expansion targets this segment specifically to address patient backlog.
- Cardiovascular:Coronary CT angiography and cardiac MRI with late gadolinium enhancement protocols serve structural and ischemic assessment. Photon-counting detector pilots in São Paulo academic centers target calcium scoring precision.
- Neurology:Functional MRI and advanced spectroscopy capabilities address epilepsy and neuro-oncology surgical planning.
- Orthopedics:Weight-bearing CT and high-resolution MRI serve sports medicine and arthroplasty assessment.
Oncology anchors premium system deployment. Cardiovascular is expanding most quickly as dose reduction algorithms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
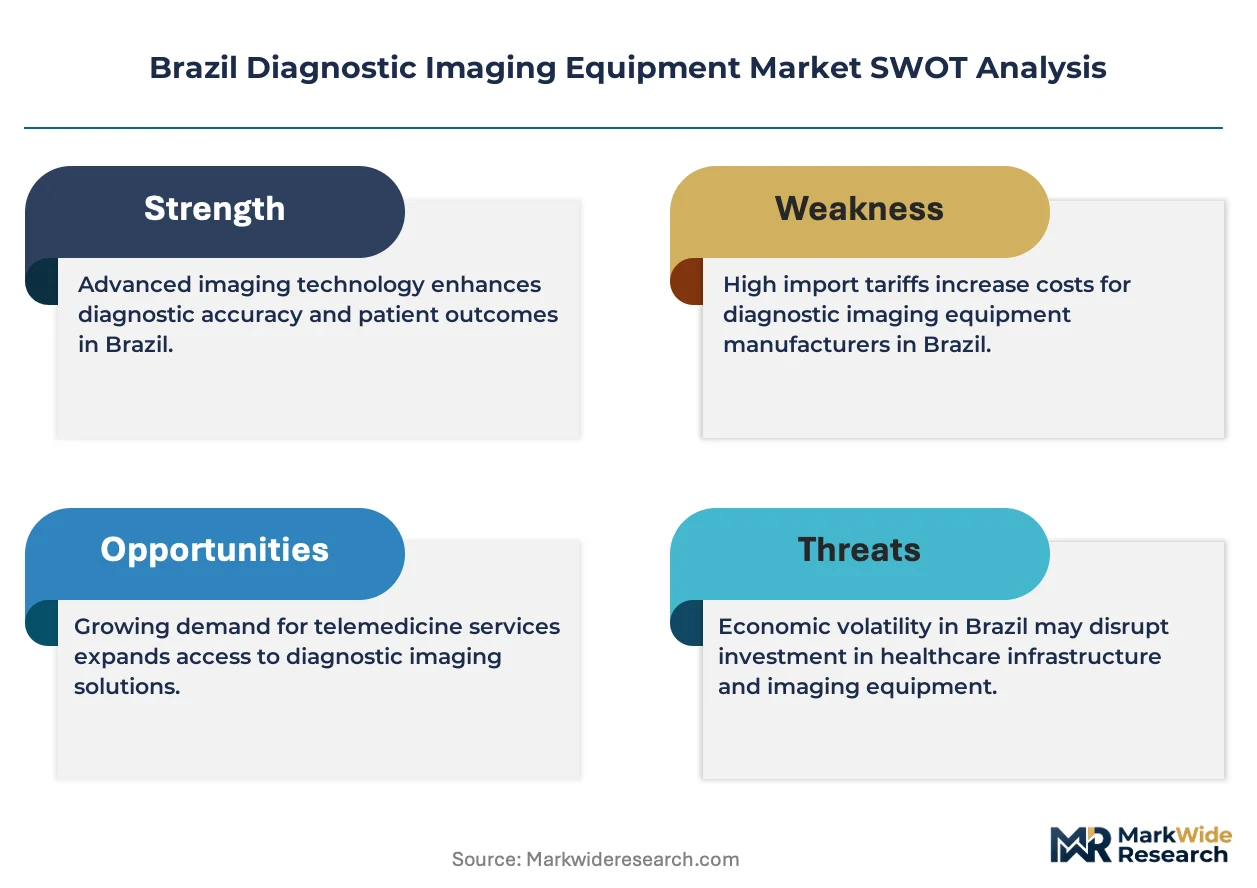
German and Japanese imaging equipment exporters dominate supply corridors into Brazilian healthcare infrastructure, with assembly operations in São Paulo state reducing import duty exposure for high-field MRI systems.
São Paulo
Southeast Brazil's economic engine concentrates diagnostic imaging demand through Hospital das Clínicas and Albert Einstein networks. ANVISA's compressed registration timelines accelerate deployment of photon-counting CT platforms. The São Paulo metropolitan corridor hosts 40% of national imaging center capacity.
Minas Gerais
Public hospital expansion in Belo Horizonte targets oncology patient backlogs with 3.0T MRI procurement. State health secretariat tenders prioritize equipment with embedded AI reconstruction modules. The Belo Horizonte medical cluster anchors southeastern supply chain logistics.
Rio de Janeiro
Academic medical centers at UFRJ and Fiocruz pilot spectral CT applications for cardiovascular calcium scoring. Municipal health networks replace analog X-ray systems with wireless digital radiography panels. The Rio metropolitan area serves as primary entry point for European imaging equipment imports.
Rio Grande do Sul
Porto Alegre's hospital networks maintain older installed bases, extending service contracts on depreciated MRI assets. State procurement regulations favor lease-to-own structures for CT replacement cycles. Southern Brazil's manufacturing heritage supports localized technical service capacity.
Bahia
Salvador diagnostic centers operate at 35% equipment density versus Southeast benchmarks. Federal university hospitals drive demand for mid-field MRI systems with simplified operator interfaces. Northeast regional penetration strategies target this undercapacity corridor.
Brazil Diagnostic Imaging Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazilian procurement channels. Three multinational conglomerates anchor 60% of installed base maintenance contracts through integrated service networks. Market structure stratifies between premium-tier vendors with captive financing arms and mid-tier Asian manufacturers competing on capital cost. Dominant competitive moves include unbundling service contracts to independent organizations and bundling AI algorithm modules with hardware tenders.
Among diversified health technology conglomerates, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions as archetype representatives of channel-controlling strategy. These entities exemplify integrated service network deployment across São Paulo and Rio de Janeiro hospital clusters. Mid-tier specialists including Canon Medical Systems and Fujifilm Holdings sit within product-focused competitive positioning. United Imaging Healthcare and Mindray represent scale-driven Asian manufacturing archetypes penetrating municipal health networks on cost-optimized tenders.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings |
| United Imaging Healthcare |
| Mindray |
| Shimadzu Corporation |
| Carestream Health |
| Others |
Value Chain & Pricing Dynamics
German and Japanese superconducting magnet suppliers anchor upstream concentration for Brazil's MRI market, directing margin pools toward service contract bundling and AI algorithm licensing rather than hardware alone.
Pricing Analysis
Next-generation photon-counting CT platforms command 40-60% premiums over conventional multi-slice systems, while prior-generation analog X-ray equipment faces steep depreciation in municipal tenders. Three-tier pricing structure across premium, standard, and economy levels segments buyers by field strength requirements and AI module inclusion. Cost compression in the mid-tier is intensifying because Asian manufacturers are penetrating municipal health networks with localized assembly advantages. Public hospital procurement committees exhibit highest price sensitivity, while academic medical centers prioritize spectroscopy capabilities over capital cost.
Supply Chain Analysis
Tariff exposure between Germany and Brazil dominates landed cost volatility for high-field MRI systems, with ANVISA's electromagnetic compatibility testing adding procedural delays beyond Mercosur harmonization. Supply draws from Germany, Japan, and China for superconducting magnets, detector arrays, and RF coils respectively. Single-source vulnerability concentrates in cryogenic helium refining, where global capacity constraints drive recurrent price spikes. Distribution runs through São Paulo-based assembly operations and Rio de Janeiro import corridors to Southeast diagnostic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable ultrasound and AI-native teleradiology platforms threaten incumbent hardware vendors with substitution at the primary care tier, forcing equipment suppliers to defend integrated service relationships.
For Market Incumbents: Harden service contract stickiness by embedding predictive maintenance algorithms and training certification programs that lock hospital biomedical engineering staff into proprietary ecosystems. Anchor AI reconstruction modules to hardware leases, creating switching costs that resist independent service organization poaching. Prioritize backward integration into refurbished equipment channels to capture secondary-market revenue from depreciated CT and MRI assets in Rio Grande do Sul.
For New Entrants and Emerging Players: Northeast regional underpenetration offers white-space entry below incumbent radar, with Salvador and Recife diagnostic centers operating at 35-40% equipment density versus Southeast benchmarks. Target municipal health secretariats in Ceará and Piauí with portable ultrasound pilot programs that demonstrate rural maternal screening ROI. Pursue lease-to-own structures that align with state procurement regulations favoring operational expenditure over capital commitment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed imaging center rollups in São Paulo and Belo Horizonte that acquired depreciated MRI fleets during 2018-2022 consolidation waves. Long-term viability hinges on AI-enabled throughput expansion that justifies premium equipment replacement cycles against teleradiology cost compression. Watch ANVISA's alignment with international medical device single audit program standards as the signal for streamlined cross-border M&A due diligence.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Bundling | Siemens Healthineers and GE Healthcare embed reconstruction modules to lock hospital networks into captive service ecosystems. |
| Regional Assembly Localization | São Paulo state manufacturing reduces import duty exposure and compresses delivery timelines for high-field MRI procurement. |
| Independent Service Organization Partnership | Mid-sized private operators in São Paulo unbundle maintenance to reduce total cost of ownership on depreciated assets. |
| Photon-Counting CT Pilot Programs | Academic medical centers at UFRJ and Hospital das Clínicas validate cardiovascular calcium scoring applications. |
| Cloud PACS Interoperability Investment | ANVISA's international standards alignment enables cross-border data architecture deployment for multi-site imaging chains. |
Study Parameters
Cross-validation between ANVISA registration databases and hospital procurement records anchors the qualitative findings on equipment deployment timelines. Primary interviews with biomedical engineering directors, diagnostic center operations managers, GPO contracts specialists, and radiology department heads combined with secondary validation from ANVISA technical standards filings, Mercosur harmonized regulation texts, and national complementary health regulator accreditation lists. Bottom-up installed base enumeration triangulates against top-down market size estimates across product type, technology tier, and end-user category.
Calibration against historical replacement cycles and tender award patterns shapes the projection framework across the analysis window. Segmentation dimensions modeled include product modality, field strength tier, digital maturity level, end-user facility type, and clinical application intensity. CAGRs derive from equipment shipment trajectories, reimbursement pathway evolution, and ANVISA registration velocity. Forecast inputs incorporate radiologist training pipeline constraints and helium supply price volatility assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese manufacturers into mid-field MRI segments would shift outcomes beyond modeled parameters. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
C-Arms Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Japan Digital Radiology Market