
 Cold Seal Plastic Films Market | 2026-2036
Cold Seal Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Seal Plastic Films Market Outlook
Chocolate and confectionery packaging is hardening as the dominant end-use vertical for cold seal plastic films, displacing slower-growth industrial applications. Amcor Plc leverages its global manufacturing footprint to supply multinational confectionery brands with consistent film specifications across continents. Mondi Group anchors its position through captive paper-plastic integration, serving European chocolate producers with tailored barrier structures. Toray Plastics specializes in high-clarity cast polypropylene variants that preserve product visibility while delivering reliable seal integrity at reduced temperatures.
Cold seal plastic films are pressure-sensitive packaging materials coated with natural rubber or synthetic latex adhesives that activate without heat, typically sealing at 20-40 psi with ambient surface temperatures between 15°C and 35°C. Their primary purpose is to protect heat-sensitive products such as chocolate, pharmaceuticals, and temperature-delicate electronics from thermal degradation during packaging operations. Polyethylene formulations dominate volume production due to cost efficiency and broad compatibility with form-fill-seal equipment, while polypropylene variants command premium positioning through superior optical clarity and moisture barrier performance. Extrusion technology leads manufacturing throughput, though coating processes attract investment for precision adhesive deposition in medical packaging applications.
FDA food contact regulations govern adhesive migration limits and substrate purity requirements in the United States, while EU REACH and the EU Packaging and Packaging Waste Directive impose substance restrictions and recyclability mandates across European supply chains. These frameworks compel manufacturers to reformulate adhesives and validate alternative substrates, elevating R&D costs but creating competitive differentiation for compliant suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based adhesive certifications as these standards increasingly determine market access and procurement eligibility.
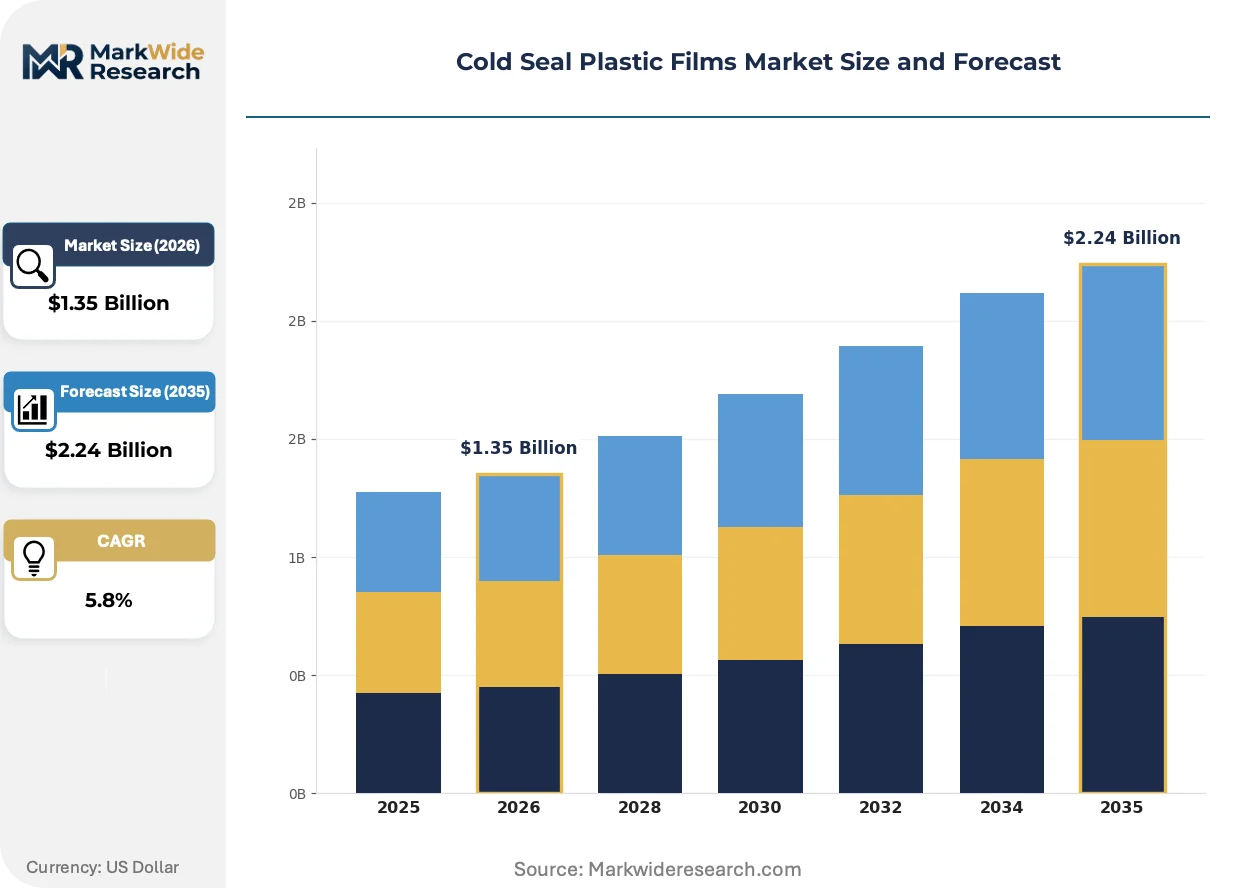
Market Dynamics
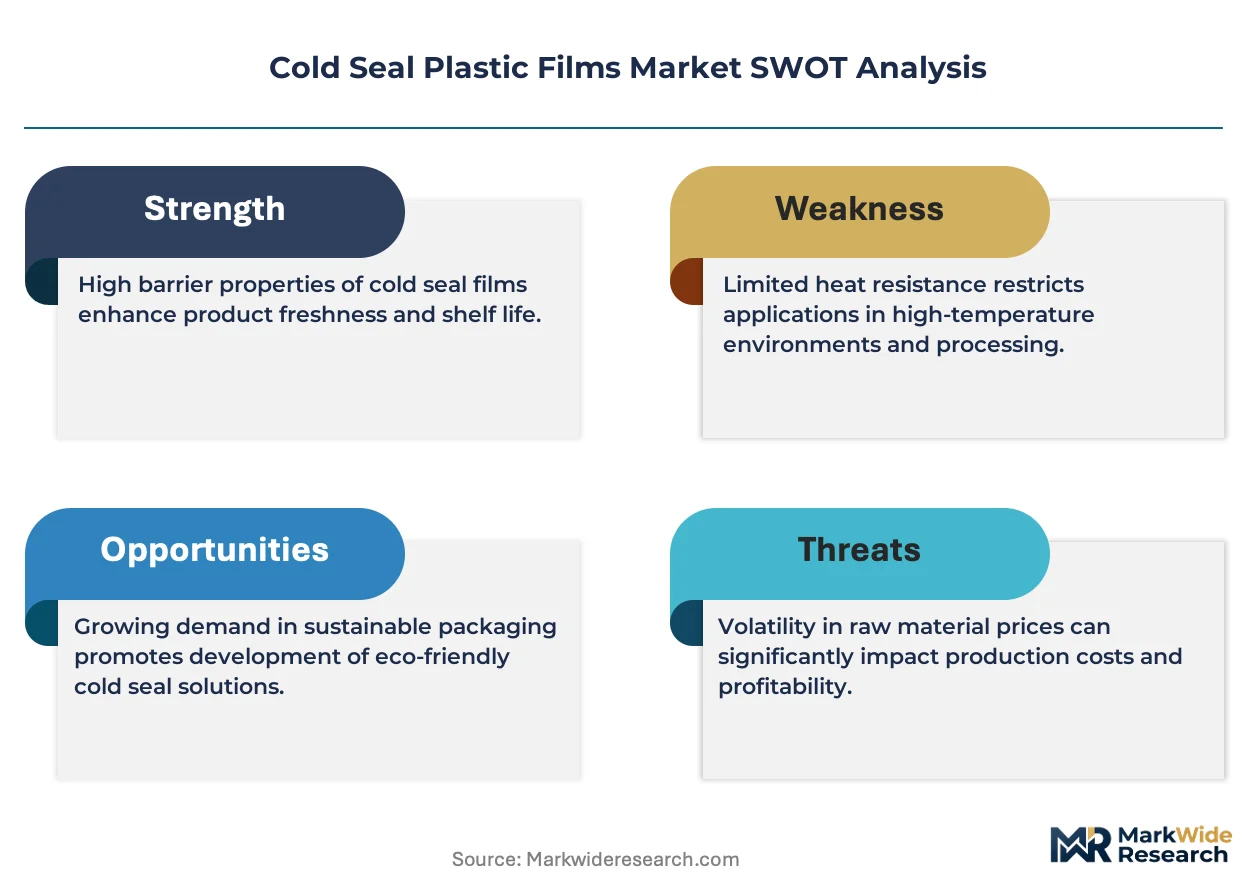
EU REACH substance restrictions and FDA migration limits are forcing adhesive reformulation across cold seal film supply chains, elevating R&D expenditures while compressing margins for non-compliant producers. This regulatory compression is reshaping competitive positioning toward certified suppliers with validated alternative substrates.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Recyclability mandates are accelerating mono-material film development, creating procurement pull from brands with circular economy commitments.
- Chocolate segment expansion:Premium confectionery brands in Germany are demanding high-clarity barrier structures with validated cold seal integrity for temperature-sensitive products.
- Cast polypropylene technology:Superior optical clarity and moisture barrier performance is displacing polyethylene in visibility-critical applications.
Market Restraints
- Natural rubber adhesive volatility:Latex supply concentration in Southeast Asia creates input cost instability and formulation inconsistency.
- Medical packaging certification friction:FDA validation timelines for direct-contact pharmaceutical films extend 18-24 months, freezing new supplier entry.
- Heat-seal substitution threat:Ultrasonic sealing equipment advances are encroaching on cold seal's temperature-sensitive niche in electronics packaging.
Strategic Opportunities
- India confectionery growth:FSSAI-compliant cold seal demand from domestic chocolate brands remains underpenetrated relative to per-capita consumption potential.
- Bio-based adhesive certification:USDA BioPreferred and EU Ecolabel standards are creating premium positioning for natural rubber alternatives with validated carbon profiles.
- Digital printing convergence:Variable-data flexography integration with cold seal webs enables short-run personalization for seasonal confectionery.
Industry Challenges
- Coating precision skill gap:Adhesive deposition uniformity at medical-grade tolerances requires specialized technicians scarce in emerging production regions.
- Legacy form-fill-seal integration:Retrofitting ambient-temperature sealing stations onto heat-calibrated lines demands mechanical reconfiguration and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Seal Plastic Films Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Food Packaging, Medical Packaging, Consumer Goods, Industrial Packaging Technology: Extrusion, Casting, Coating, Laminating End User: Food Industry, Healthcare, Electronics, Retail |
| Companies Covered | Bemis Company, Amcor Plc, Sealed Air Corporation, Berry Global, Mondi Group, Constantia Flexibles, Uflex Ltd., Toray Plastics, Innovia Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Seal Plastic Films Market Strategic Shifts
Active reformulation of adhesive chemistries and substrate architectures is compressing development cycles while expanding addressable applications beyond traditional confectionery protection.
Water-based synthetic latex formulations are consolidating as the dominant adhesive platform for medical and pharmaceutical cold seal applications. European contract packagers are adopting these systems at accelerated pace to preempt REACH substance restrictions. This consolidation is compressing market share for solvent-based alternatives and elevating capital requirements for coating line conversion.
REACH Annex XVII substance restrictions are compelling systematic substitution of specific rubber accelerators in cold seal adhesives. Industrial consequence includes extended validation protocols for migration testing and extractables profiling. Pharmaceutical packaging segments in Germany and Switzerland are responding by consolidating procurement around suppliers with pre-validated compliant formulations.
Brand-direct specification of certified sustainable films is restructuring traditional distributor channels in premium confectionery. Chocolate producers in Belgium and the Netherlands are bypassing regional converters to contract directly with film manufacturers holding Ecolabel and OK Compost certifications. This channel compression is most visible in seasonal product lines where traceability claims command shelf price premiums.
Cold Seal Plastic Films Market Segmentation
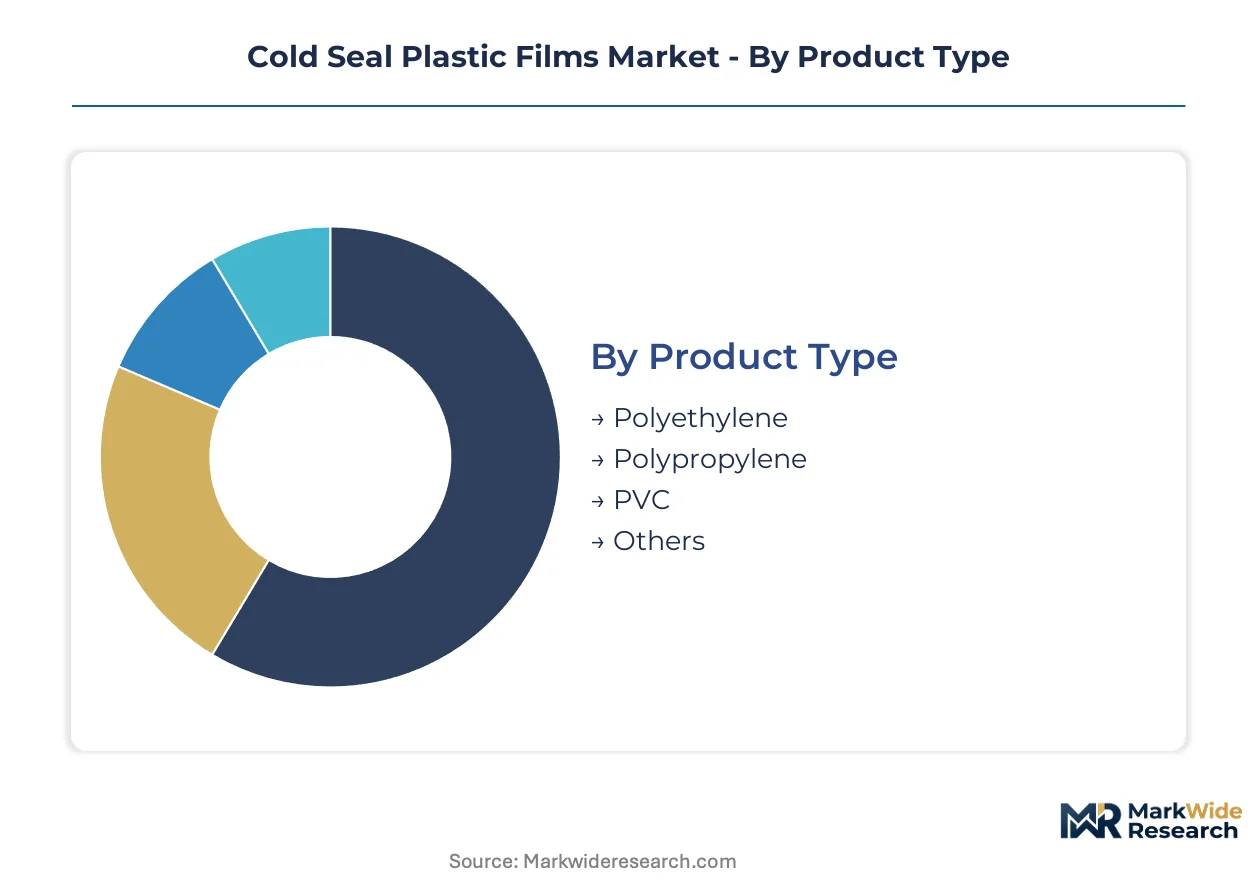
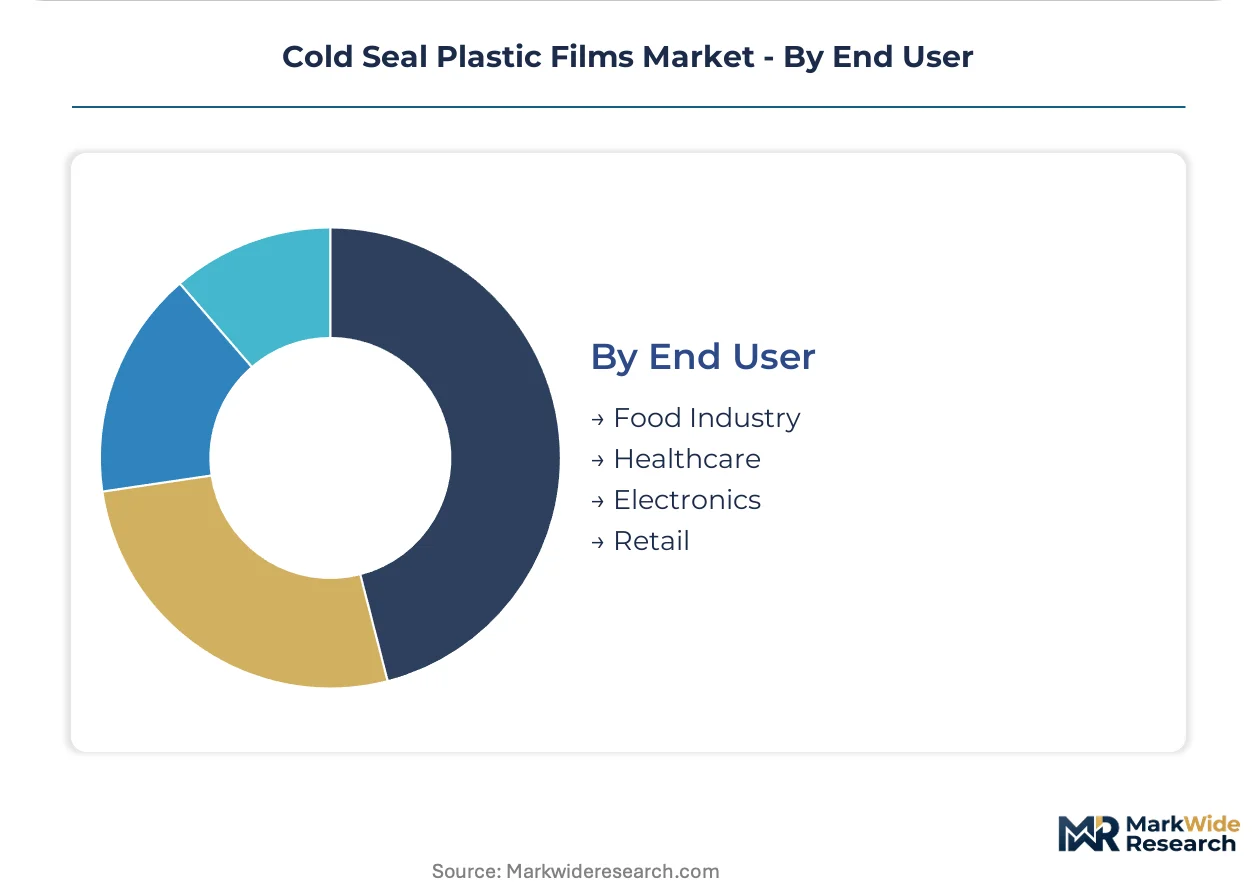
Cold seal plastic films serve divergent performance requirements across temperature-sensitive packaging applications. Segmentation reveals how formulation choices map to specific regulatory thresholds and equipment compatibility constraints.
Product Type:
Buyers in this category differentiate primarily by optical clarity requirements versus moisture barrier specifications.
- Polyethylene:Cost-efficient linear low-density formulations dominate volume production for form-fill-seal equipment compatibility. Demand concentrates in mass-market chocolate packaging across Germany and Switzerland where FDA migration compliance is mandatory.
- Polypropylene:Cast variants deliver superior clarity and moisture resistance for premium confectionery visibility. Belgian and Dutch chocolate producers specify these films for seasonal lines requiring direct brand-to-manufacturer contracting.
- PVC:Declining share due to REACH substance restrictions and recycling complexity in EU markets.
- Others:Bio-based and mono-material alternatives emerging under Ecolabel certification requirements.
Polyethylene leads volumes today; polypropylene is gaining share fastest.
Application:
Segment selection here tracks directly to validation burden and regulatory jurisdiction.
- Food Packaging:Dominant vertical encompassing chocolate and confectionery protection. German precision packaging requirements drive specialized film procurement with validated cold seal integrity at 15-35°C ambient temperatures.
- Medical Packaging:Direct-contact pharmaceutical applications face FDA validation timelines of 18-24 months. Swissmedic and EMA compliance requirements in Switzerland and Europe concentrate demand around pre-validated adhesive formulations.
- Consumer Goods:Temperature-sensitive cosmetics and personal care products requiring barrier protection without thermal degradation.
- Industrial Packaging:Electronics and temperature-delicate components where ultrasonic sealing advances threaten cold seal niche penetration.
Food packaging anchors current revenue; medical packaging shows steepest expansion trajectory.
Technology:
Capital intensity and adhesive precision requirements separate procurement tiers in this category.
- Extrusion:Highest throughput manufacturing for polyethylene volume production. Cost efficiency drives adoption across mass-market confectionery supply chains.
- Casting:Cast polypropylene technology commands premium positioning through optical clarity performance. European contract packagers accelerate adoption for REACH-compliant medical applications.
- Coating:Precision adhesive deposition attracts investment for pharmaceutical-grade migration control. Skill gaps in coating uniformity limit supplier base expansion.
- Laminating:Multi-layer barrier structures for complex protection requirements in premium food segments.
Extrusion dominates installed capacity; coating is climbing the fastest.
End User:
Procurement sophistication and certification requirements define customer tiers here.
- Food Industry:Chocolate and confectionery producers in Belgium, Netherlands, and Germany bypass distributors for direct film manufacturer relationships. Ecolabel and OK Compost certifications command shelf price premiums.
- Healthcare:Pharmaceutical packaging consolidation around REACH Annex XVII compliant suppliers in Germany and Switzerland. Extended validation protocols for rubber accelerator substitution reshape procurement.
- Electronics:Temperature-sensitive component protection facing substitution pressure from ultrasonic sealing equipment advances.
- Retail:Private label and seasonal product lines driving short-run personalization through digital printing convergence.
Food industry captures largest share; healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward jurisdictions with streamlined REACH compliance pathways and lower validation burdens for adhesive reformulation.
Germany
Precision packaging demand from premium confectionery brands in Cologne and Hamburg drives specialized film procurement with validated cold seal integrity. ECHA REACH Annex XVII substance restrictions compel systematic rubber accelerator substitution in adhesive formulations. The Baden-Württemberg industrial corridor concentrates coating technology investment for medical-grade migration control.
United States
FDA migration limits for direct food contact films elevate R&D expenditure for compliant adhesive platforms. Chocolate producers in Pennsylvania and Illinois specify polyethylene formulations for mass-market form-fill-seal compatibility. The Midwest packaging belt anchors extrusion capacity expansion serving domestic confectionery supply chains.
Belgium
Brand-direct specification of Ecolabel-certified films is compressing traditional distributor channels in seasonal confectionery packaging. EU Packaging and Packaging Waste Directive recyclability mandates accelerate mono-material film development. The Flanders region hosts concentrated demand from chocolate producers bypassing regional converters for manufacturer-direct relationships.
India
FSSAI-compliant cold seal demand from domestic chocolate brands remains underpenetrated relative to per-capita consumption potential in Maharashtra and Gujarat. Central government PLI scheme incentives for packaging materials attract multinational film manufacturers. The Mumbai-Pune industrial corridor concentrates emerging extrusion capacity serving FMCG sector growth.
Switzerland
Swissmedic compliance requirements for direct-contact pharmaceutical films concentrate procurement around pre-validated adhesive formulations. Extended validation protocols for rubber accelerator substitution reshape healthcare packaging procurement patterns. The Basel-Zurich corridor anchors specialized coating operations for medical-grade barrier structures.
Cold Seal Plastic Films Market Competitive Environment
Capacity expansion dominates the current landscape as established players retrofit coating lines for water-based synthetic latex conversion ahead of REACH deadlines. The vendor base clusters around three strategic tiers: multinational integrated packaging conglomerates with captive film production, specialized film manufacturers with precision coating capabilities, and regional extrusion specialists serving commodity confectionery segments. Portfolio diversification and geographic expansion represent the dominant competitive vectors as companies seek to offset margin compression from regulatory compliance costs.
Within the multinational integrated tier, Amcor Plc and Mondi Group exemplify scale-driven positioning through global manufacturing footprints and paper-plastic integration respectively. Toray Plastics occupies a specialized position representing high-clarity cast polypropylene technology for visibility-critical applications. These three entities anchor competitive dynamics as regulatory compression elevates capital requirements for compliant adhesive platforms and validated substrate architectures.
| Leading Market Players |
|---|
| Bemis Company |
| Amcor Plc |
| Sealed Air Corporation |
| Berry Global |
| Mondi Group |
| Constantia Flexibles |
| Uflex Ltd. |
| Toray Plastics |
| Innovia Films |
| Others |
Value Chain & Pricing Dynamics
Natural rubber latex costs cascade through cold seal film pricing tiers from Southeast Asian plantations through European coating operations to German confectionery brands, with REACH-compliant adhesive formulations commanding substantial premiums over commodity polyethylene grades.
Pricing Analysis
Distributor margins compress most severely in standard polyethylene segments where mass-market chocolate producers in Germany and Switzerland negotiate volume-driven contract structures. Three-tier pricing structure across REACH-certified premium, FDA-compliant standard, and economy polyethylene levels separates procurement tiers by validation burden and optical clarity specification. Pricing pressure stems from natural rubber supply volatility and coating line conversion capital requirements for water-based synthetic latex migration. Small regional extrusion specialists exhibit highest price sensitivity, while premium confectionery brands in Belgium absorb certification premiums for Ecolabel traceability claims.
Supply Chain Analysis
Container freight rates from Malaysian latex processing centers to European coating facilities directly impact adhesive cost structures for medical-grade film production. Raw material concentration draws from Thailand and Indonesia for natural rubber, Germany and Belgium for specialty polymer resins, and China for commodity polyethylene substrates. Single-source vulnerability concentrates in Southeast Asian latex supply chains where climate disruption and labor availability trigger formulation inconsistency. Distribution runs through integrated multinational packaging conglomerates serving multinational confectionery brands, with regional extrusion specialists supplying commodity segments through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold seal plastic films function as a stable compounder anchored by regulatory mandates for temperature-sensitive pharmaceutical and confectionery protection that perpetually renew equipment upgrade cycles.
For Market Incumbents: Deploy coating precision capabilities as a defensive moat against ultrasonic sealing substitution threats in electronics packaging. Amcor Plc and Mondi Group should accelerate water-based synthetic latex line conversion ahead of REACH Annex XVII deadlines to freeze out capital-constrained competitors. Captive paper-plastic integration and pre-validated medical-grade formulations protect margin structures against emerging regional extrusion specialists. For New Entrants and Emerging Players: EU REACH Annex XVII substance restrictions in Germany and Switzerland open a window for specialized coating operations with compliant adhesive platforms. FSSAI-compliant film supply for India's underpenetrated domestic chocolate sector offers the most penetrable geography, with Maharashtra and Gujarat production clusters enabling cost-competitive positioning. Go-to-market execution should target direct manufacturer relationships bypassing traditional distributor channels for seasonal confectionery lines. For Investors and Strategic Acquirers: Consolidation pressure builds where coating precision skill scarcity intersects with extended FDA validation timelines for pharmaceutical-grade migration control. The five-to-ten-year viability window favors targets with pre-validated REACH-compliant adhesive formulations and established relationships with Swissmedic and EMA regulatory pathways. Watch for rubber accelerator substitution completion rates as the inflection signal indicating which suppliers have secured sustainable medical packaging procurement positions.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Platform Conversion | REACH Annex XVII compliance secures pharmaceutical procurement eligibility in Germany and Switzerland. |
| Mono-Material Film Development | EU Packaging and Packaging Waste Directive recyclability mandates drive brand-direct specification from Belgian chocolate producers. |
| Cast Polypropylene Capacity Expansion | Superior optical clarity captures premium positioning for seasonal confectionery visibility requirements. |
| Direct-to-Manufacturer Channel Bypass | Ecolabel and OK Compost certifications command shelf price premiums through traceability claims. |
| Medical-Grade Coating Precision Investment | FDA validation timelines of 18-24 months freeze new supplier entry and protect incumbent margins. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating line engineers, pharmaceutical packaging procurement managers, confectionery brand technical directors, and regulatory affairs specialists at ECHA and FDA with secondary validation from customs trade data, SEC filings of integrated packaging conglomerates, REACH Annex XVII substance restriction updates, and Swissmedic compliance bulletins. Bottom-up film production capacity modeling and top-down end-use demand estimation triangulated market sizing across the analysis window.
Segment-weighting approaches applied product type, application vertical, manufacturing technology, and end-user procurement sophistication dimensions throughout the modeling period. CAGRs derived from adhesive formulation substitution rates, equipment upgrade cycles, and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated natural rubber latex price volatility indices and REACH substance restriction implementation schedules.
Revisions become necessary when rubber accelerator substitution protocols extend beyond anticipated validation timelines or when ultrasonic sealing technology achieves cost parity in temperature-sensitive electronics applications. Forecasts reflect assumptions regarding regulatory enforcement consistency and coating technician availability in emerging production regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Oil Resistant Packaging Market