
 Hydrocolloid Coating Market | 2026-2036
Hydrocolloid Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocolloid Coating Market Insights
Aftermarket technical service revenue is reconfiguring competitive economics across the hydrocolloid coating value chain. Cargill leverages its agricultural raw material sourcing to control input costs for plant-derived hydrocolloid feedstocks. Ingredion anchors North American supply through its corn wet-milling infrastructure and modified starch derivatives portfolio.
Hydrocolloid coatings comprise water-soluble polymeric substances—typically carboxymethyl cellulose, pectin, or gelatin derivatives—applied as viscous layers that form cohesive gels upon moisture contact, functioning primarily as protective barriers and controlled-release matrices in medical and food systems. Hydrocolloid adhesives dominate wound care applications due to established clinical acceptance and reimbursement pathways, while hydrocolloid gels represent the fastest-expanding category driven by transdermal drug delivery platform development. Spray coating technology leads manufacturing throughput for medical-grade films, though dip coating retains premium positioning for complex geometries in drug delivery devices.
The U.S. FDA biocompatibility framework and ISO 10993 standards govern material safety for skin-contact hydrocolloid applications, with FDA 510(k) clearance requirements creating sustained barriers to market entry for novel formulations. REACH compliance across Europe mandates extensive substance registration for imported hydrocolloid raw materials, elevating documentation burdens for non-European suppliers. Stakeholders must monitor evolving FDA guidance on absorbable medical device coatings and prioritize early engagement with notified bodies to secure CE marking under the EU Medical Device Regulation.
Market Dynamics
FDA 510(k) clearance requirements for novel hydrocolloid formulations are compressing product development timelines while elevating R&D capital intensity across medical-grade coating segments. Medical device manufacturers now face extended validation cycles that favor incumbents with established biocompatibility dossiers.
Growth Catalysts
- EU Medical Device Regulation (MDR) transition:Stricter clinical evidence requirements for wound care dressings are accelerating replacement demand for legacy products with updated hydrocolloid formulations.
- Transdermal drug delivery platforms:Pharmaceutical formulators are expanding hydrocolloid gel adoption for controlled-release patches targeting chronic disease management.
- German wound care supply chain:Concentrated procurement by hospital networks and homecare distributors is standardizing hydrocolloid specifications across Central European markets.
Market Restraints
- Raw material concentration:Seaweed-derived alginate and pectin feedstock sourcing clusters in coastal processing regions of Norway and Chile, creating weather-dependent supply volatility.
- Biocompatibility testing costs:ISO 10993 cytotoxicity and sensitization studies for new hydrocolloid chemistries impose six-figure validation burdens that exclude smaller compounders.
- Silicone adhesive substitution:Advanced silicone gel formulations are capturing select wound care segments where extended wear time and reduced skin trauma outweigh hydrocolloid cost advantages.
Strategic Opportunities
- Brazil ANVISA regulatory pathway:Streamlined medical device registration for Class II dressings is opening import substitution opportunities for hydrocolloid manufacturers establishing local technical dossiers.
- 3D bioprinting convergence:Integration of hydrocolloid hydrogels with extrusion-based tissue engineering platforms is creating demand for sterilizable, cell-compatible coating grades.
- Direct-to-patient e-commerce:Chronic wound patients in the United States are bypassing traditional durable medical equipment distributors through Amazon and specialized telehealth platforms.
Industry Challenges
- Cross-functional formulation expertise:Hydrocolloid development requires simultaneous mastery of polymer rheology, adhesive science, and sterilization validation—skill sets rarely concentrated in single technical teams.
- Legacy equipment retrofitting:Converting solvent-based coating lines to aqueous hydrocolloid systems demands capital expenditure in drying capacity and humidity-controlled cleanrooms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocolloid Coating Market |
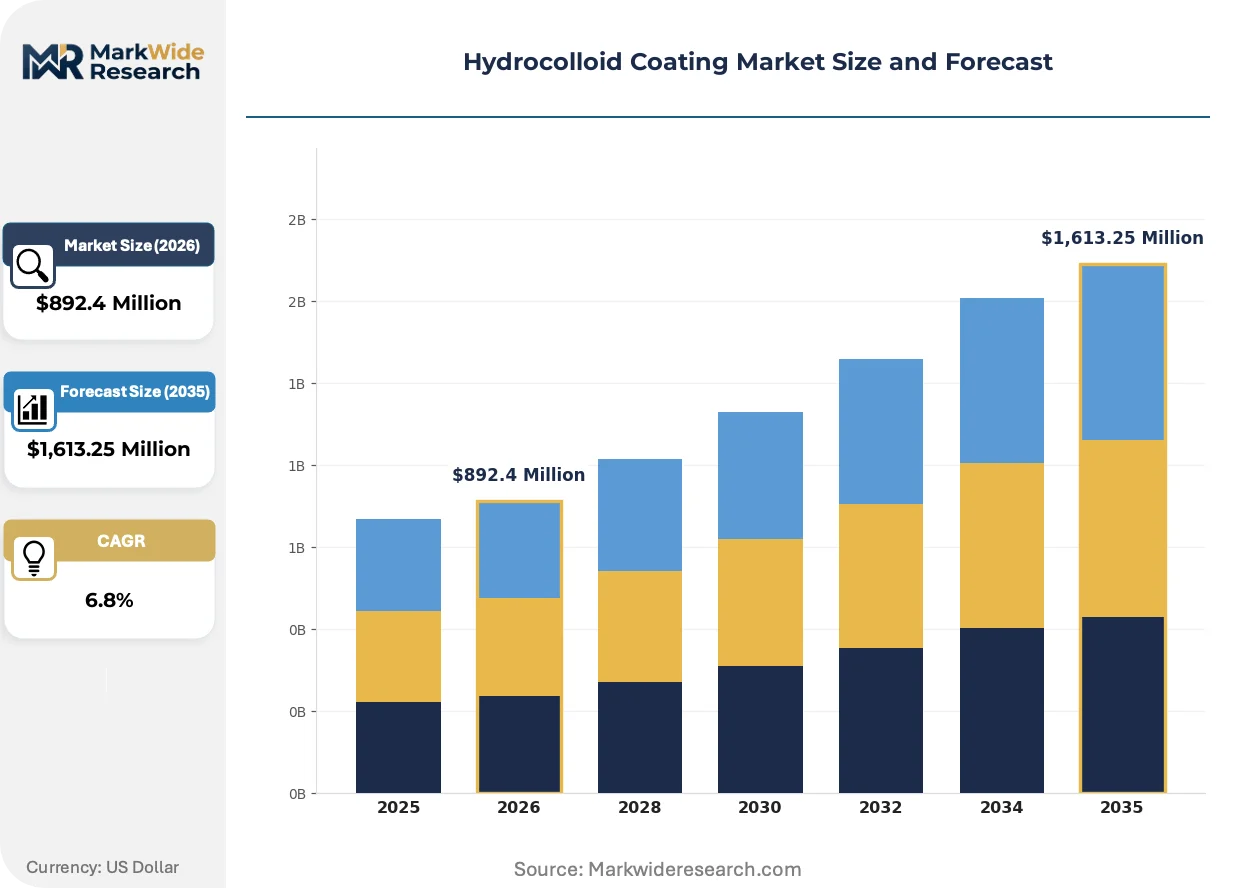
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Adhesives, Hydrocolloid Gels, Hydrocolloid Films, Hydrocolloid Powders End User: Healthcare, Food Industry, Cosmetics, Personal Care Application: Wound Care, Drug Delivery, Food Coating, Thickening Agent Technology: Spray Coating, Dip Coating, Roll Coating, Extrusion Coating |
| Companies Covered | Cargill, Ingredion, Tate & Lyle, ADM, DuPont, CP Kelco U.S. Inc., Ashland, DSM, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocolloid Coating Market Trends and Innovations
Process analytical technology is penetrating hydrocolloid manufacturing floors, replacing offline quality control with real-time viscosity and moisture monitoring. This shift is compressing batch release timelines while tightening specification windows for medical-grade output.
Inline rheometry coupled with machine vision inspection is digitizing coating uniformity verification across continuous web production. Medical film converters in Minnesota and Baden-Württemberg are retrofitting legacy slot-die lines with sensor arrays that flag gel thickness deviations within seconds rather than post-production laboratory testing. The technology is digitizing quality assurance labor, reducing headcount in final inspection while accelerating lot release for just-in-time wound care supply chains.
REACH substance registration deadlines for imported hydrocolloid raw materials are elevating documentation burdens for non-European suppliers. ECHA's revised guidance on polymer characterization requires detailed monomer composition disclosure that many Asian compounders have not previously maintained. Small-volume hydrocolloid importers are consolidating supplier relationships to share registration costs, compressing the vendor base serving European medical device manufacturers.
Hospital procurement departments are consolidating hydrocolloid dressing contracts under outcome-based frameworks that penalize dressing failure rates rather than rewarding unit cost reductions. German hospital networks and NHS Trusts in England are piloting total-cost-of-care models where dressing manufacturers assume partial liability for delayed wound healing. The shift is visible most acutely in pressure ulcer prevention programs where nursing labor costs dominate over material spend.
Hydrocolloid Coating Market Segmentation
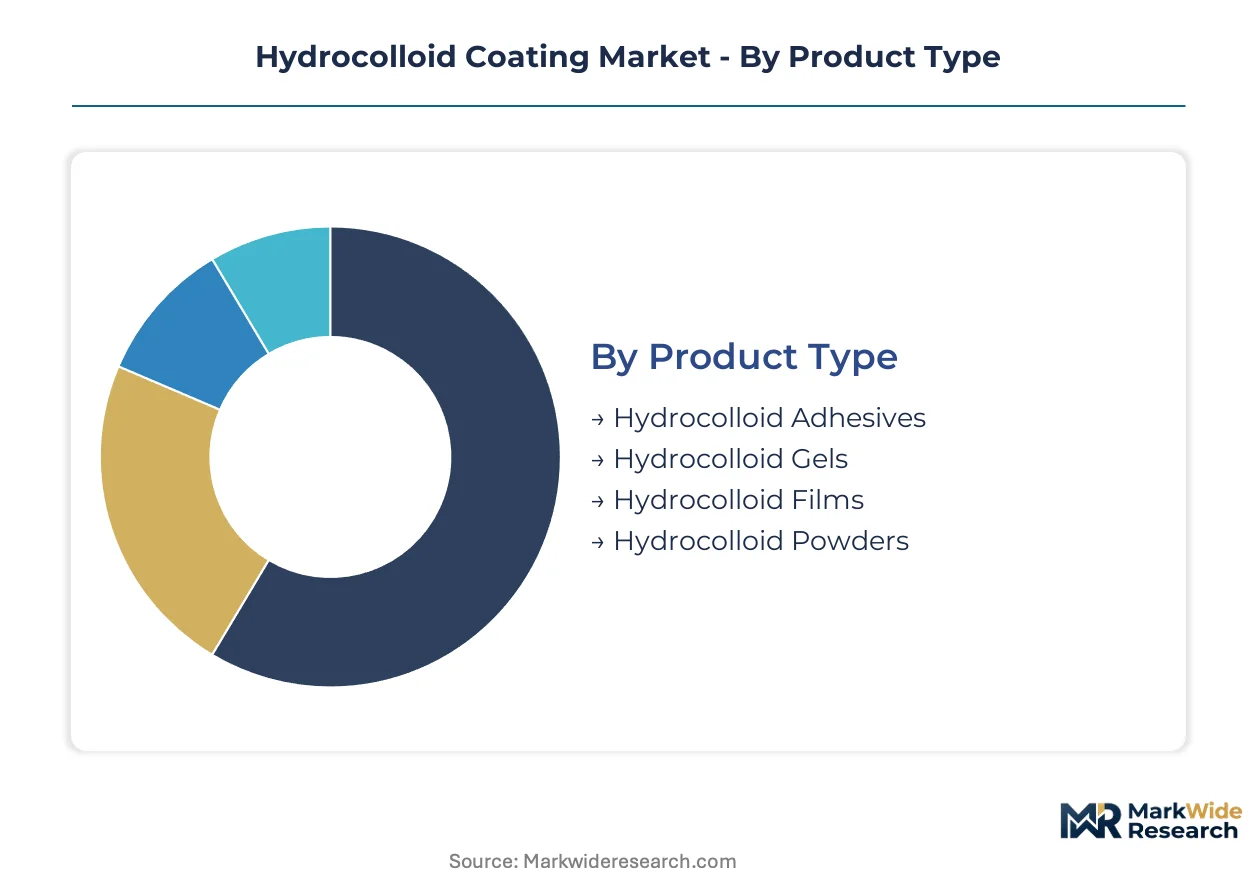
Hydrocolloid coating manufacturers configure product portfolios around distinct rheological behaviors and moisture-response profiles. Each segment category maps to different capital intensity requirements and regulatory validation pathways across medical and industrial applications.
Product Type:
Medical-grade hydrocolloid formulations span adhesive bonding, gel matrix formation, film barrier protection, and powdered excipient functions across wound management and pharmaceutical systems.
- Hydrocolloid Adhesives:Pressure-sensitive formulations combining carboxymethyl cellulose with elastomeric rubbers deliver skin-adherent bonding for extended-wear dressings. Demand concentrates in German hospital procurement networks where ISO 10993 biocompatibility certification gates supplier qualification.
- Hydrocolloid Gels:Viscous aqueous matrices of pectin or gelatin derivatives form cohesive moisture-retentive layers upon exudate contact. Transdermal patch manufacturers in Minnesota and Baden-Württemberg are expanding gel adoption for controlled-release APIs targeting chronic disease management.
- Hydrocolloid Films:Thin, flexible barriers manufactured via solvent casting or hot-melt extrusion for moisture vapor transmission control.
- Hydrocolloid Powders:Granulated excipients for tablet disintegration and sustained-release matrix compression in oral dosage forms.
The dominant share belongs to Hydrocolloid Adhesives, while Hydrocolloid Gels is closing the gap fastest.
End User:
Customer segments stratify by regulatory burden intensity and formulation complexity tolerance.
- Healthcare:Medical device manufacturers and hospital systems drive specification standards for biocompatibility-validated grades. FDA 510(k) clearance requirements and EU MDR technical documentation impose multi-year qualification cycles that favor incumbent suppliers with established dossiers.
- Food Industry:Confectionery and processed food manufacturers utilize hydrocolloid coatings for moisture barrier and controlled-release flavor applications. EFSA food additive approvals and Clean Label positioning requirements are reshaping sourcing toward plant-derived pectin and modified starch alternatives.
- Cosmetics:Skincare formulators incorporate hydrocolloid films for occlusive hydration and active ingredient delivery.
- Personal Care:Consumer hygiene product manufacturers employ hydrocolloid adhesives for gentle skin attachment in wearable formats.
Healthcare commands the specification premium tier, with Food Industry expanding most quickly as natural-label positioning displaces synthetic alternatives.
Application:
Functional deployment of hydrocolloid coatings traces the intersection of moisture management requirements and controlled-release engineering demands.
- Wound Care:Exudate-absorbent dressings leveraging gel-forming pectin and carboxymethyl cellulose matrices maintain moist healing environments. German hospital networks and NHS Trusts are consolidating procurement under outcome-based contracts that penalize dressing failure rates.
- Drug Delivery:Transdermal patches and buccal films employ hydrocolloid gels for API dissolution control and adhesion to mucosal surfaces. Pharmaceutical formulators are advancing platform development for chronic disease management applications.
- Food Coating:Edible moisture barriers extend shelf stability in confectionery and fried snack categories.
- Thickening Agent:Viscosity modification in sauces, dressings, and beverage systems utilizing xanthan and guar derivatives.
Wound Care retains the volume anchor position, though Drug Delivery is gaining share fastest as transdermal platform investments accelerate.
Technology:
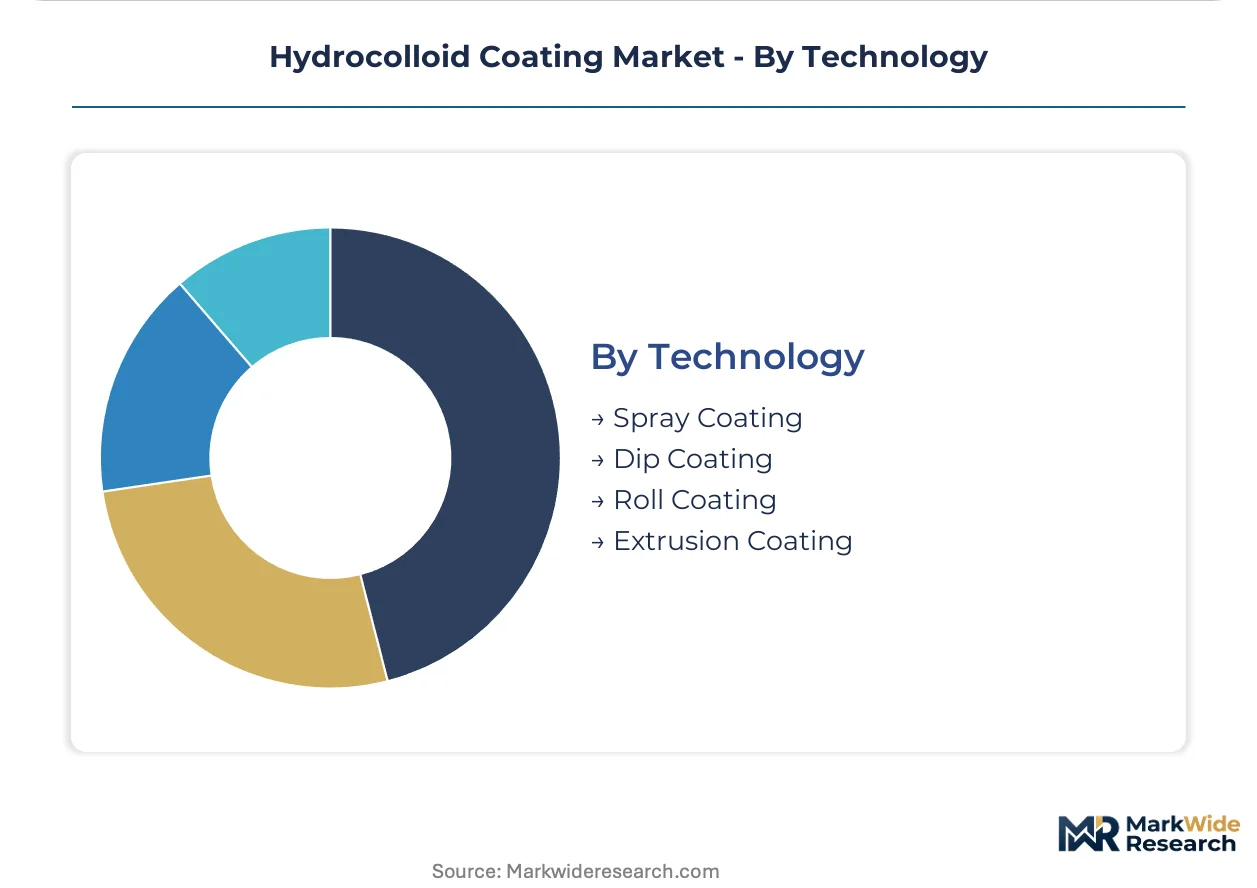
Manufacturing process selection determines coating uniformity, throughput economics, and geometric adaptability for target substrates.
- Spray Coating:Atomized deposition of viscous hydrocolloid solutions onto continuous webs delivers high-throughput film production for medical-grade applications. Minnesota-based converters are retrofitting lines with inline rheometry and machine vision for real-time thickness verification.
- Dip Coating:Immersion-based application achieves conformal coverage of complex three-dimensional geometries in drug delivery device manufacturing. Premium positioning reflects slower throughput and superior uniformity for precision-coated components.
- Roll Coating:Direct gravure or reverse-roll transfer of formulated coatings onto flat substrates for food packaging and label applications.
- Extrusion Coating:Hot-melt extrusion of thermoplastic hydrocolloid compounds onto moving webs for multi-layer barrier structures.
Spray Coating holds the throughput leadership position, while Dip Coating is climbing the fastest as geometric complexity requirements intensify in combination device segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German hospital networks prioritize ISO 10993-certified medical grades under tender consolidation, while U.S. formulators drive transdermal drug delivery adoption. Brazilian regulators meanwhile accelerate import substitution through ANVISA pathway streamlining.
United States
FDA 510(k) clearance requirements compress development timelines for novel hydrocolloid formulations. Transdermal patch manufacturers in Minnesota expand gel adoption for chronic disease APIs. Inline rheometry and machine vision retrofitting across Twin Cities converters digitizes quality assurance labor.
Germany
Hospital procurement networks consolidate contracts under outcome-based frameworks penalizing dressing failure rates. EU MDR technical documentation demands accelerate replacement demand for legacy wound care products. Baden-Württemberg medical film producers standardize specifications across Central European supply chains.
Brazil
Chronic wound prevalence drives demand for advanced dressing formats in public health systems. ANVISA streamlined registration for Class II medical devices opens import substitution opportunities. São Paulo-based distributors build local technical dossiers to bypass legacy import dependency.
China
NMPA medical device classification reforms elevate biocompatibility documentation requirements for skin-contact coatings. Yangtze River Delta pharmaceutical formulators invest in controlled-release platform development. Shanghai-area converters scale aqueous coating capacity for domestic wound care brands.
Japan
PMDA QMS ministerial ordinances enforce sterilization validation rigor for absorbent medical coatings. Aging demographics expand homecare dressing demand through long-term care insurance reimbursement. Kansai region chemical compounders develop cell-compatible hydrogel grades for regenerative medicine convergence.
Hydrocolloid Coating Market Competitive Landscape
Capability concentration sits with specialized polymer compounders holding ISO 10993 dossiers; scale advantage sits with agricultural processors commanding feedstock supply chains. The vendor base stratifies across three tiers: multinational ingredient suppliers with wet-milling infrastructure, mid-cap coating specialists with sterilization validation expertise, and regional compounders serving food-grade applications. Dominant competitive moves include backward integration into alginate and pectin sourcing clusters, plus technology licensing partnerships bridging pharmaceutical and medical device qualification requirements.
Among agricultural-derivative suppliers, Cargill exemplifies feedstock cost control through coastal seaweed and corn wet-milling infrastructure. Ingredion anchors North American supply security via modified starch derivatives and aqueous formulation expertise. CP Kelco U.S. Inc. occupies a position within the specialized hydrocolloid tier, representing the fermentation-based biopolymer segment serving medical-grade gel applications.
| Leading Market Players |
|---|
| Cargill |
| Ingredion |
| Tate & Lyle |
| ADM |
| DuPont |
| CP Kelco U.S. Inc. |
| Ashland |
| DSM |
| International Flavors & Fragrances Inc. |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure through EU MDR technical documentation requirements and FDA 510(k) clearance timelines compresses pricing tier spreads while forcing supply chain consolidation around dossier-holding compounders in Germany and Minnesota. This structural bottleneck elevates medical-grade premiums against commoditized food-grade alternatives and anchors procurement relationships with validated suppliers.
Pricing Analysis
Contract-based long-term offtake agreements dominate medical-grade hydrocolloid procurement, with German hospital networks and U.S. wound care manufacturers locking multi-year supply commitments. Price differentiation rests on ISO 10993 biocompatibility certification tier and volume scale, with validated medical grades commanding substantial premiums over food-grade alternatives. Cost compression in standard adhesive formulations is intensifying because Brazilian and Chinese converters are scaling aqueous coating capacity. Food industry buyers exhibit highest price sensitivity, while pharmaceutical formulators tolerate premium positioning for transdermal drug delivery grades.
Supply Chain Analysis
Tariff exposure between Asian pectin compounders and European medical device manufacturers dominates supply chain risk calculus for non-REACH-registered suppliers. Raw material sourcing draws from Norwegian and Chilean coastal alginate processing clusters, corn wet-milling infrastructure in the U.S. Midwest, and pectin extraction facilities in Brazil and Mexico. Single-source vulnerability concentrates in seaweed-derived feedstocks vulnerable to weather-driven harvest volatility. Distribution runs through specialized chemical distributors serving medical film converters in Baden-Württemberg and Minnesota, plus direct procurement relationships with hospital GPO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise spanning polymer rheology, adhesive science, and sterilization validation represents the critical scarcity constraining competitive entry. Incumbents possessing cross-functional technical teams hold durable advantage against pure-play compounders lacking integrated qualification capabilities.
For Market Incumbents: Pre-empt silicone adhesive substitution in extended-wear wound care by accelerating CE marking pathway completion for next-generation gel formulations under EU MDR. Backward integration into Norwegian alginate sourcing clusters secures feedstock cost position against weather-driven supply volatility. Channel control through direct-to-patient e-commerce partnerships with Amazon and telehealth platforms defends margin position against distributor disintermediation.
For New Entrants and Emerging Players: Brazilian ANVISA Class II device registration streamlining represents the most penetrable entry point for hydrocolloid manufacturers lacking legacy FDA dossiers. 3D bioprinting convergence applications in regenerative medicine offer white-space demand for sterilizable, cell-compatible hydrogel grades underserved by incumbent food-grade suppliers. Go-to-market execution through São Paulo-based technical dossier partnerships bypasses legacy import dependency and accelerates hospital procurement qualification.
For Investors and Strategic Acquirers: FDA evolving guidance on absorbable medical device coatings reshapes the acquisition landscape toward compounders with sterilization validation infrastructure and ISO 10993 dossier depth. Long-term viability in this market hinges on technical capabilities that cannot be replicated through capital deployment alone. Mid-cap coating specialists with cross-functional formulation teams and established notified body relationships represent the priority acquisition archetype. The signal to watch is early-stage 3D bioprinting platform partnerships as inflection indicator for next-generation medical-grade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation accelerates replacement demand for legacy wound care formulations. |
| Backward Integration | Captive supply of Norwegian alginate and Brazilian pectin insulates against weather-driven feedstock volatility. |
| Hospital System Partnership | Outcome-based contracts with German networks and NHS Trusts lock multi-year procurement relationships. |
| Software Companion Development | Digital wound monitoring integration with hydrocolloid dressings enables data-driven reimbursement strategies. |
| Reimbursement Strategy | Medicare and long-term care insurance pathways in Japan and the United States determine homecare market access. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, pharmaceutical formulators, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork with medical film converters in Baden-Württemberg and Minnesota supplemented secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, ECHA REACH substance registrations, and hospital procurement contract disclosures. Bottom-up demand modeling across wound care, drug delivery, and food coating applications triangulated against top-down hydrocolloid raw material trade flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user, application, and technology. Modeled variables included rheological grade tier, biocompatibility certification status, regional regulatory cluster, and coating process technology. CAGRs derived from historical volume trajectories adjusted for EU MDR transition acceleration and transdermal platform investment cycles. Industry-specific forecast inputs incorporated alginate harvest yield variability and aqueous coating line capacity expansion announcements.
Practitioners should monitor FDA guidance evolution on absorbable coatings, ANVISA registration processing timelines, and 3D bioprinting platform partnerships for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Transport Protection Film Market