
 Asia-Pacific Retort Pouch Market | 2026-2036
Asia-Pacific Retort Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Retort Pouch Market Insights
China's Yangtze River Delta capacity build-out is reshaping regional supply dynamics for high-barrier flexible packaging. Amcor leverages its integrated film extrusion network to sustain cost leadership across Southeast Asian export channels. Huhtamaki anchors premium retort lidding demand through specialized aluminum foil laminates for Japanese seafood processors. Toppan Holdings competes on oxygen-barrier technology leadership, particularly EVOH coextrusion systems designed for extended shelf-life applications.
A retort pouch is a multi-layer laminated flexible container engineered to withstand sterilization temperatures of 121°C to 135°C while maintaining seal integrity, typically constructed from polyethylene terephthalate, aluminum foil, polypropylene, and adhesive tie layers through coextrusion or lamination processes. Its primary commercial purpose is to replace rigid metal cans and glass jars in shelf-stable food distribution, reducing shipping weight and enabling microwave-ready convenience. Stand-up pouch configurations command the largest volume share due to retail shelf visibility and consumer handling ergonomics, while zipper pouch formats represent the fastest-growing structural category as resealability becomes standard in premium pet food and ready-meal segments. Plastic laminates dominate material demand for cost-sensitive mass-market applications, though EVOH barrier layers are displacing conventional structures in pharmaceutical and high-acid food categories where oxygen ingress tolerance has tightened.
Japan's METI enforces container and packaging recycling targets that mandate minimum recycled content thresholds, directly influencing laminate design decisions among domestic converters. China's SAMR and GB standards govern food-contact material migration limits, creating compliance barriers for imported pre-formed pouches that lack domestic testing certification. Australia's TGA maintains parallel pharmaceutical packaging integrity standards that extend retort validation requirements to oncology nutrition products. Stakeholders must monitor how divergent national recycling infrastructure capabilities will fragment laminate specifications across the region's fragmented regulatory landscape.
Market Dynamics
China's Yangtze River Delta manufacturing corridor is consolidating retort pouch capacity as food processors abandon metal can lines for flexible sterilizable formats, compressing regional supply chains and forcing laminate converters to co-locate near sterilization facilities.
Growth Catalysts
- Urban ready-to-eat meal penetration:China's eastern seaboard cities are absorbing shelf-stable pouch formats at rates that outpace traditional canning infrastructure expansion, pulling laminate demand toward high-barrier coextrusion systems.
- India's BIS packaging safety mandates:The Bureau of Indian Standards is tightening migration limit testing for food-contact laminates, accelerating domestic certification investments by regional converters seeking formaldehyde-free adhesive systems.
- Japan's METI sustainability guidelines:Minimum recycled content thresholds are forcing laminate redesigns toward mono-material compatible structures, creating pull-through demand for EVOH barrier layers that maintain performance at reduced aluminum foil gauges.
Market Restraints
- Aluminum foil supply concentration:China's Qingyuan and Zhengzhou smelter clusters control regional foil rolling capacity, exposing downstream converters to ingot price volatility and dual carbon policy production curtailments.
- EVOH resin import dependency:Asia-Pacific converters rely on Kureha and Chang Chun Petrochemical for ethylene vinyl alcohol supply, creating polymer sourcing risk when Japanese petrochemical maintenance cycles tighten.
- GB standards compliance friction:China's SAMR requires domestic migration testing certification for all food-contact laminates, blocking pre-formed pouch imports that lack NMPA-registered testing laboratory validation.
Strategic Opportunities
- Vietnam's underpenetrated seafood processing:Mekong Delta tuna and pangasius exporters are converting from frozen bulk to retort pouch value-added formats, creating first-mover advantage for laminate suppliers establishing local slitting operations.
- Australia's TGA pharmaceutical nutrition:Oncology and geriatric nutrition products are extending retort validation requirements to flexible packaging, opening high-margin barrier film demand beyond conventional food applications.
- Indonesia's palm oil derivative integration:Domestic polypropylene resin capacity from Cilegon petrochemical complexes is enabling backward integration into cast film production for cost-sensitive mass-market pouch formats.
Industry Challenges
- High-barrier adhesive formulation expertise:Solventless polyurethane lamination chemistry requires specialized technicians scarce in Southeast Asian converter workforces, slowing production ramp at new greenfield facilities.
- Retort validation cycle compression:Shelf-life testing protocols for 121°C sterilization cycles demand 6-12 month certification timelines that conflict with food processor product launch schedules.
- Legacy canning equipment stranded assets:Metal can line depreciation schedules and unionized workforce obligations are delaying processor conversion decisions despite flexible packaging total cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Retort Pouch Market |
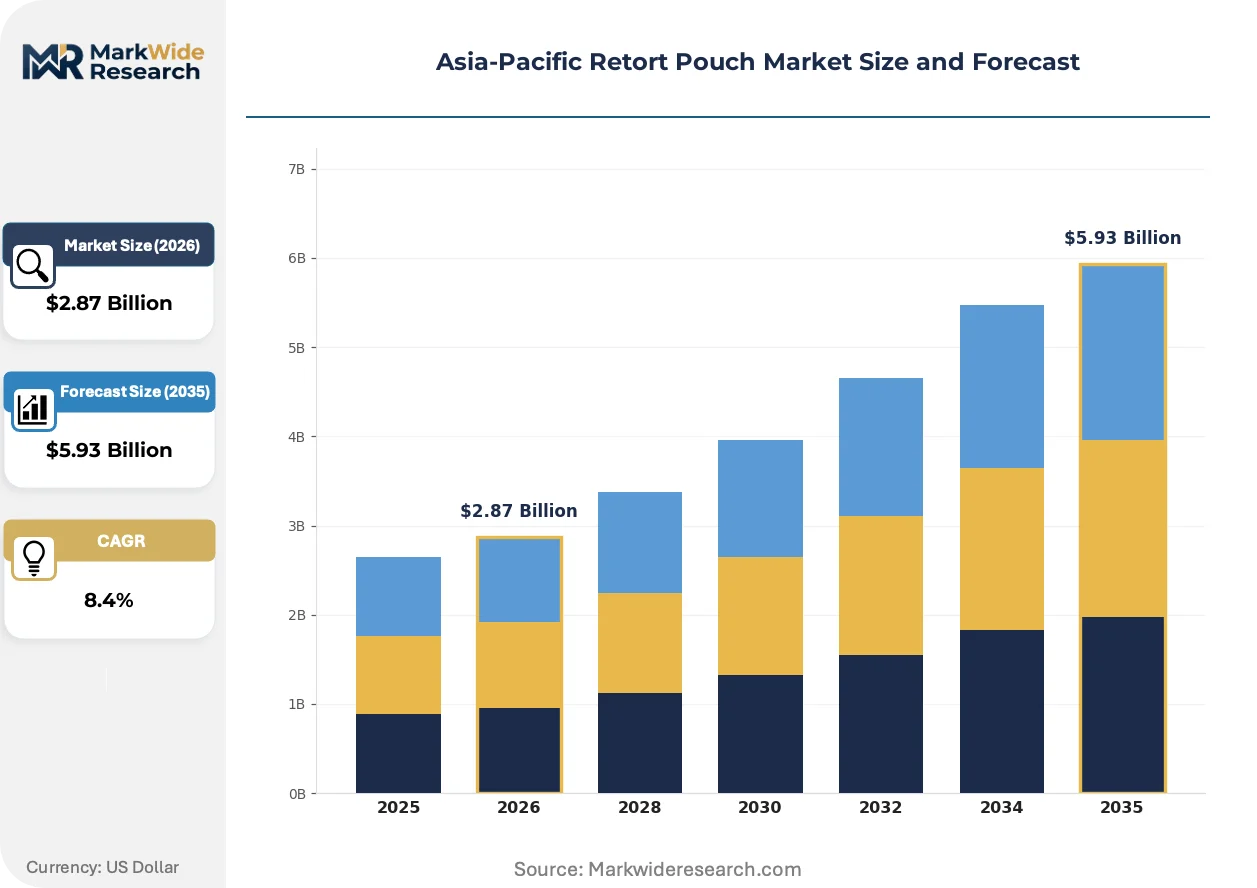
| Market Size in 2026 | $2.87 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouch, Flat Pouch, Zipper Pouch, Vacuum Pouch Application: Food & Beverage, Pharmaceuticals, Pet Food, Personal Care Material: Aluminum Foil, Plastic Laminates, PET, EVOH End User: Manufacturers, Retailers, Distributors, Food Service |
| Companies Covered | Amcor, Mondi Group, Sealed Air, Berry Global, Huhtamaki, Sonoco Products, ProAmpac, Toppan Holdings, Toyo Seikan Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Retort Pouch Market Trends and Innovations
Retort pouch engineering is pivoting toward mono-material compatibility and reduced aluminum dependency as circular economy mandates penetrate Asia-Pacific packaging procurement specifications. Three convergent developments are compressing traditional laminate architectures.
Barrier technology is hybridizing conventional aluminum foil laminates with EVOH coextrusion systems to maintain oxygen ingress protection at reduced metal gauges. Japanese seafood processors are specifying these hybrid structures for premium sashimi-grade tuna pouches requiring 24-month shelf life. The technology is hybridizing material cost structures and enabling compliance with METI recycled content mandates without sacrificing barrier performance.
China's SAMR is enforcing GB 4806 series migration limits through expanded market surveillance testing of imported pre-formed pouches. The regulation is forcing multinational brand owners to establish domestic testing partnerships or abandon direct import channels. High-acid sauce categories are most affected, with processors accelerating local laminate sourcing to avoid customs detention risks at Shanghai and Ningbo ports.
Convenience-oriented consumption is compressing traditional retail distribution cycles for shelf-stable proteins. Southeast Asian e-commerce platforms are absorbing direct-to-consumer pouch formats that bypass conventional wholesaler markups, with Indonesian and Vietnamese urban consumers leading channel migration. Pet food applications are most visible, where zipper-equipped stand-up pouches are displacing multi-serve cans in premium segment shelf sets.
Asia-Pacific Retort Pouch Market Segmentation
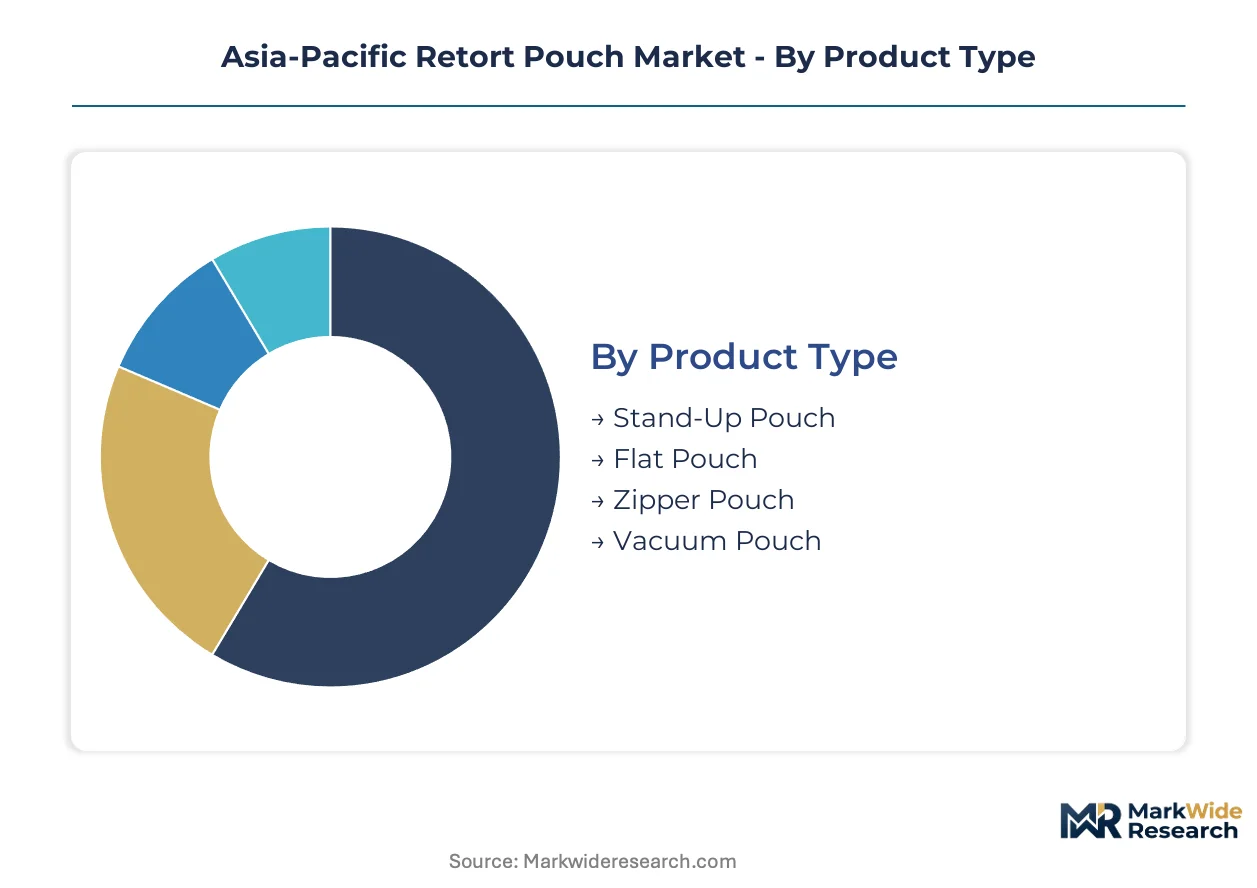
Retort pouch demand fragments across structural formats, barrier technologies, and procurement channels. Each segmentation dimension carries distinct margin profiles and certification requirements that shape converter investment priorities.
Product Type:
Mature stand-up formats dominate current throughput, while emerging zipper configurations are capturing premium shelf-space allocations.
- Stand-Up Pouch:Gusseted bottom construction enables vertical retail display and improved shelf visibility. China's Yangtze River Delta food processors specify this format for ready-to-eat meal lines converting from metal cans.
- Zipper Pouch:Resealable track systems add 15-20% material cost but enable multi-serve consumption patterns. Japanese pet food brands and Australian oncology nutrition suppliers are standardizing this format for premium segment positioning.
- Flat Pouch:Three-side-seal construction minimizes material usage for single-serve sauce and seafood portions. Mekong Delta tuna exporters favor this format for cost-sensitive export contracts.
- Vacuum Pouch:High-barrier coextrusion enables oxygen exclusion without rigid container requirements. South Korean ready-meal processors specify vacuum formats for extended ambient distribution.
Stand-up configurations handle the majority of throughput; zipper-equipped formats are expanding most quickly on share.
Application:
Volume concentrates in mass-market food sterilization, while pharmaceutical and pet nutrition applications command structural premiums.
- Food & Beverage:Shelf-stable proteins, sauces, and ready meals constitute the core demand base. China's SAMR GB 4806 migration limits are accelerating domestic laminate sourcing for high-acid sauce categories.
- Pet Food:Premium segment migration toward single-serve wet formats is displacing multi-serve cans. Indonesian and Vietnamese e-commerce platforms are absorbing direct-to-consumer pouch shipments.
- Pharmaceuticals:Australia's TGA enforces retort validation protocols for oncology and geriatric nutrition products. Barrier specifications exceed conventional food-grade requirements.
- Personal Care:Sterilizable mask and topical treatment formats represent nascent demand. Japanese cosmetic brands are piloting retort-compatible laminate structures for preservative-free formulations.
Food and beverage applications anchor volume throughput; pharmaceutical nutrition is climbing the fastest on margin contribution.
Material:
Cost structures diverge between commodity polyolefin laminates and high-performance barrier systems.
- Aluminum Foil:Conventional 7-9 micron foil layers deliver near-zero oxygen transmission rates. Japan's METI recycled content mandates are forcing gauge reductions and hybrid EVOH substitution.
- EVOH:Ethylene vinyl alcohol coextrusion enables mono-material compatible barrier performance. Kureha and Chang Chun Petrochemical supply chains constrain regional availability during maintenance cycles.
- Plastic Laminates:Polypropylene and polyethylene structures dominate mass-market cost-sensitive applications. Indonesia's Cilegon petrochemical complexes are enabling backward integration into cast film production.
- PET:Polyester outer layers provide printability and mechanical strength for retort sterilization cycles. China's Qingyuan foil rolling clusters supply adjacent PET film capacity.
Aluminum foil laminates retain the majority of high-barrier applications; EVOH hybrid structures are gaining share fastest on sustainability compliance.
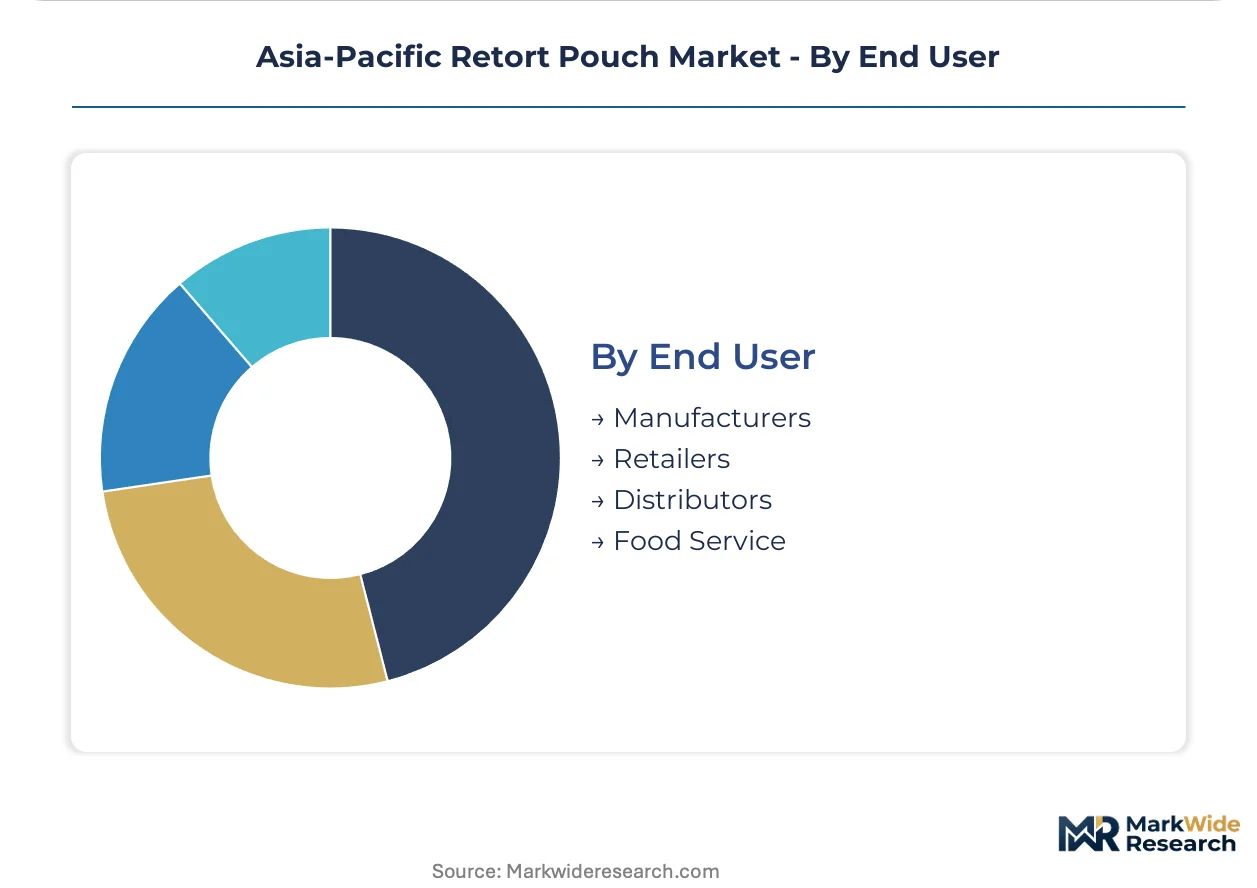
End User:
Procurement authority concentrates with sterilization facility operators, while distributor intermediaries face margin compression.
- Manufacturers:Food processors with in-house retort chambers specify laminate performance directly. India's BIS certification requirements are filtering supplier bases toward formaldehyde-free adhesive systems.
- Food Service:Institutional catering and ready-meal assembly operations specify pre-formed pouches for portion control. Southeast Asian airport and railway catering contracts are standardizing retort formats.
- Retailers:Private label shelf-stable protein lines specify pouch formats for differentiation. Australian supermarket chains are accelerating direct sourcing from Vietnam and Indonesia.
- Distributors:Intermediary stocking roles are compressing as processors consolidate direct converter relationships. GB standards compliance friction is accelerating domestic certification investments.
Manufacturers control the majority of specification authority; food service procurement is expanding most quickly on channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region: China's eastern seaboard favors stand-up ready-meal formats, Japan's seafood sector demands premium barrier hybrids, and Southeast Asian exporters prioritize cost-optimized flat pouches for commodity tuna and pangasius.
China
Food processors in Shanghai and Suzhou are abandoning metal can lines for flexible sterilizable formats, pulling laminate demand toward high-barrier coextrusion systems. SAMR's GB 4806 migration limits block pre-formed pouch imports lacking NMPA-registered laboratory validation. The Yangtze River Delta manufacturing corridor is consolidating retort pouch capacity as converters co-locate near sterilization facilities.
Japan
Premium seafood processors specify hybrid EVOH-aluminum structures for sashimi-grade tuna requiring 24-month shelf life. METI's recycled content thresholds force laminate redesigns toward mono-material compatible formats at reduced foil gauges. Kureha's ethylene vinyl alcohol supply chains constrain regional availability during petrochemical maintenance cycles.
India
Urban ready-to-eat meal penetration is accelerating pouch demand among eastern seaboard cities outpacing traditional canning infrastructure expansion. BIS packaging safety mandates tighten migration limit testing for food-contact laminates, filtering supplier bases toward formaldehyde-free adhesive systems. Domestic converters in Maharashtra and Gujarat are accelerating certification investments to capture formaldehyde-compliant supply contracts.
Vietnam
Mekong Delta tuna and pangasius exporters are converting from frozen bulk to retort pouch value-added formats, creating first-mover advantage for laminate suppliers establishing local slitting operations. The country's national food safety regulator enforces evolving import compliance requirements for EU and US-bound seafood shipments. Ho Chi Minh City corridor processors are piloting zipper-equipped stand-up formats for premium retail channel access.
Australia
Oncology and geriatric nutrition products are extending retort validation requirements to flexible packaging, opening high-margin barrier film demand beyond conventional food applications. TGA maintains pharmaceutical packaging integrity standards that compress certification timelines for 121°C sterilization cycles. Sydney and Melbourne-based nutrition manufacturers are standardizing zipper pouch formats for premium segment positioning.
Asia-Pacific Retort Pouch Market Competitive Landscape
Capability concentration sits with specialized barrier technology developers; scale advantage sits with integrated film extrusion networks spanning multiple countries. The market structures around three tiers: multinational laminate converters with captive resin supply, regional specialists in seafood and pharmaceutical certification, and emerging Southeast Asian fabricators leveraging domestic polypropylene capacity. Dominant competitive moves include backward integration into cast film production and geographic co-location with sterilization facilities.
Within the multinational converter tier, Amcor leverages integrated film extrusion networks across Southeast Asian export channels, while Huhtamaki anchors premium retort lidding demand through specialized aluminum foil laminates. Toppan Holdings occupies a position on oxygen-barrier technology leadership, particularly EVOH coextrusion systems designed for extended shelf-life applications. Among Japanese packaging specialists, Toyo Seikan Co. Ltd exemplifies the seafood-processor-facing archetype with deep certification expertise in 24-month shelf-life validation. These named entities represent distinct capability vectors rather than direct market share claims, with competitive positioning determined by barrier performance specifications and regulatory compliance depth rather than scale alone.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air |
| Berry Global |
| Huhtamaki |
| Sonoco Products |
| ProAmpac |
| Toppan Holdings |
| Toyo Seikan Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Qingyuan's aluminum foil rolling clusters anchor regional laminate cost structures, with ingot price volatility transmitting directly into converter margins across downstream sterilization facilities. China's dual carbon policy production curtailments at Zhengzhou smelters periodically tighten foil availability, forcing pouch fabricators toward EVOH hybrid structures at premium price points.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational food processors and integrated laminate suppliers, insulating volume buyers from spot aluminum volatility while locking in formaldehyde-free adhesive premiums. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade EVOH hybrids from commodity polypropylene laminates, with certification grade as the primary differentiation driver. Cost compression in standard-tier food-grade laminates is intensifying because Indonesia's Cilegon polypropylene capacity enables backward-integrated local production. Mass-market sauce processors exhibit highest price sensitivity, while Australian TGA-validated nutrition manufacturers accept 40-60% premiums for extended shelf-life barrier performance.
Supply Chain Analysis
Contract manufacturing concentration sits with Amcor's integrated film extrusion network across Thailand and Malaysia, Huhtamaki's specialized lidding operations in Japan, and Toppan Holdings' EVOH coextrusion facilities in Nagoya. Raw material dependencies draw from Kureha's ethylene vinyl alcohol resin supply in Japan, Chang Chun Petrochemical's Taiwanese petrochemical complexes, and China's Qingyuan aluminum smelter corridor. Single-source vulnerability in EVOH resin creates polymer sourcing risk during Japanese petrochemical maintenance cycles. Distribution runs through direct converter-processor relationships consolidated in China's Yangtze River Delta and Vietnam's Ho Chi Minh City corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized adhesive formulation expertise and retort validation certification capacity represent the scarcest capabilities in this market, with solventless polyurethane lamination technicians and 24-month shelf-life testing infrastructure commanding strategic premiums. Converters lacking these assets face 6-12 month product launch delays that disqualify them from premium seafood and pharmaceutical nutrition contracts.
For Market Incumbents: Entrench barrier technology leadership by acquiring EVOH coextrusion specialists in Japan and establishing captive solventless lamination training academies in Vietnam. Amcor and Huhtamaki should preempt emerging Thai and Indonesian fabricators by locking exclusive aluminum foil offtake with Qingyuan smelters before dual carbon policy curtailments deepen. Certification investment in India's BIS formaldehyde-free adhesive standards filters supplier bases and creates defensive moats. For New Entrants and Emerging Players: Vietnam's Mekong Delta tuna exporters converting from frozen bulk to value-added retort formats represent the most penetrable entry point, with local slitting operations capturing first-mover advantage before multinational converters establish regional extrusion capacity. Indonesian pet food e-commerce platforms absorbing direct-to-consumer zipper pouch shipments offer a second white-space target. A go-to-market angle anchored in Indonesia's Cilegon polypropylene backward integration enables cost-competitive flat pouch positioning against imported Chinese laminates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors EVOH hybrid barrier specialists with established pharmaceutical certification pathways over commodity aluminum foil laminators facing METI recycled content displacement. Long-term viability across the analysis window hinges on mono-material compatibility R&D pipelines and Southeast Asian sterilization facility co-location. Acquisition targets should display dual capability in solventless adhesive chemistry and domestic migration testing certification. The signal to watch is Kureha's maintenance cycle announcements, which predict EVOH supply tightness and margin expansion windows for inventory-positioned converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cast Film Production | Indonesia's Cilegon polypropylene complexes enable captive supply of cost-sensitive mass-market pouch substrates. |
| EVOH Coextrusion Capacity Expansion | Toppan Holdings' oxygen-barrier systems address Japan's METI recycled content mandates without sacrificing 24-month shelf-life performance. |
| Domestic Migration Testing Certification | China's SAMR GB 4806 compliance unlocks direct procurement channels with Yangtze River Delta food processors. |
| Solventless Lamination Training Academy | Vietnam's greenfield converter workforce scarcity creates competitive moat through proprietary technician pipelines. |
| Sterilization Facility Co-location | Proximity to Shanghai and Suzhou retort chambers compresses logistics costs and accelerates product launch timelines. |
Research Methodology
A spread of perspectives from laminate converter plant managers, food processor procurement leads, pharmaceutical packaging engineers, and BIS certification auditors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through China's SAMR GB standard filings, Japan's METI container recycling reports, India's BIS packaging safety circulars, and Australia's TGA pharmaceutical guidance documents. Bottom-up capacity assessments at Qingyuan foil rolling clusters and Cilegon petrochemical complexes were triangulated against top-down demand estimates from Yangtze River Delta sterilization facility utilization rates.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning structural format (stand-up, zipper, flat, vacuum), barrier technology (aluminum foil, EVOH hybrid, plastic laminate), application vertical (food, pet nutrition, pharmaceutical), and procurement channel (direct manufacturer, food service, retail private label). CAGRs were derived from elasticity modeling of urban ready-to-eat meal penetration rates and sterilization facility conversion timelines from metal cans to flexible formats. Industry-specific inputs included Kureha's ethylene vinyl alcohol supply schedules and METI recycled content threshold implementation trajectories.
Macroeconomic conditions sit as an overlay; deviation in aluminum ingot pricing, dual carbon policy enforcement intensity, or Japanese petrochemical maintenance cycles would shift the trajectory. Forecasts reflect assumptions about BIS certification adoption rates and SAMR import compliance friction persistence. Quarterly review of foil rolling capacity utilization at Qingyuan clusters and EVOH resin inventory positions at regional converters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Paper Pouch Market
Pouch
Twin Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Child Resistant Pouches Market
Pouch
Flexible Pouch Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Portion Control Packs Market
Pouch
Peelable Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
Slider Zipper Pouch Market
Pouch
United States Retort Pouches Market
Pouch
Pouch Dispensing Fitment Market