
 Cold Seal Lamination Pouch Market | 2026-2036
Cold Seal Lamination Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Seal Lamination Pouch Market Analytics
REACH is repositioning material compliance costs across European supply chains. 3M Company leverages its polymer science depth to sustain premium positioning in medical-grade barrier films. Fellowes Brands anchors its competitive stance through office and light-industrial channel control across North America. Deli Group Co., Ltd. dominates manufacturing scale in Asia, competing on cost-engineered standard pouch formats for high-volume export markets.
Cold seal lamination pouches are multi-layer flexible packaging structures bonded through pressure-sensitive adhesive coatings rather than heat activation, typically incorporating BOPP, PET, or foil substrates with seal strengths ranging from 200 to 800 grams per inch depending on end-use requirements. These pouches serve primarily to protect moisture-sensitive or contamination-vulnerable contents across food, medical, and electronics sectors without thermal degradation of heat-sensitive materials. Stand-up pouches command the strongest margin pools in food packaging applications where shelf differentiation and consumer convenience intersect, while reclosable formats represent the fastest-expanding segment driven by e-commerce fulfillment requirements for repeated access. Foil-based material constructions lead in medical supplies and electronics applications where oxygen and moisture barrier performance determines product integrity.
FDA medical device packaging regulations and EU MDR standards enforce biocompatibility and sterility maintenance documentation, directly shaping material selection and validation protocols for pouch suppliers serving regulated industries. ISO 11607 sterilization packaging requirements further constrain design freedom, creating compliance moats that favor established testing-capable manufacturers over commodity entrants. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in the United States and pending EU packaging waste revisions that threaten to recast single-use flexible packaging economics.
Market Dynamics
Pharmaceutical cold-chain logistics is forcing material specifications upward as temperature-sensitive biologics and generic drug exports require medical-grade barrier performance without thermal degradation during sealing.
Growth Catalysts
- EU MDR compliance mandates:Sterility maintenance documentation requirements for medical device packaging are expanding validation protocols and favoring suppliers with ISO 11607 testing capabilities across European supply chains.
- India's generic drug export expansion:Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are driving procurement of foil-based cold seal pouches for moisture-sensitive active pharmaceutical ingredients bound for regulated markets.
- E-commerce fulfillment requirements:Reclosable pouch formats are capturing demand from direct-to-consumer medical supply distributors requiring repeated access without compromising barrier integrity.
Market Restraints
- Adhesive raw material volatility:Pressure-sensitive acrylic and rubber-based formulations face input cost swings tied to petrochemical feedstock pricing, compressing margin stability for mid-tier converters.
- Supply concentration in BOPP substrates:Film extrusion capacity clusters in China and the Middle East create geographic dependency risks for European and North American pouch converters.
- Heat-seal substitution in non-critical applications:Standard food packaging segments are migrating to lower-cost thermal lamination where content sensitivity permits, narrowing cold seal's addressable market.
Strategic Opportunities
- Brazil's ANVISA regulatory alignment:Latin American pharmaceutical packaging standards are converging with FDA and EMA benchmarks, opening certification-driven procurement channels for validated medical-grade suppliers.
- Printed electronics protection:Flexible circuit and sensor manufacturers require oxygen barrier performance without thermal stress, creating a technical application wedge for foil-laminated cold seal formats.
- Extended producer responsibility frameworks:Pending EU packaging waste revisions and state-level EPR laws in California and New York are incentivizing mono-material recyclable constructions that cold seal adhesive systems can enable.
Industry Challenges
- ISO 11607 validation timelines:Sterilization packaging certification cycles stretch 18-24 months, locking working capital and creating barriers to entry for new medical-grade pouch suppliers.
- Legacy equipment retrofit requirements:Converters with installed heat-seal infrastructure face capital intensity to reconfigure lines for pressure-sensitive adhesive coating and nip-roll bonding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Seal Lamination Pouch Market |
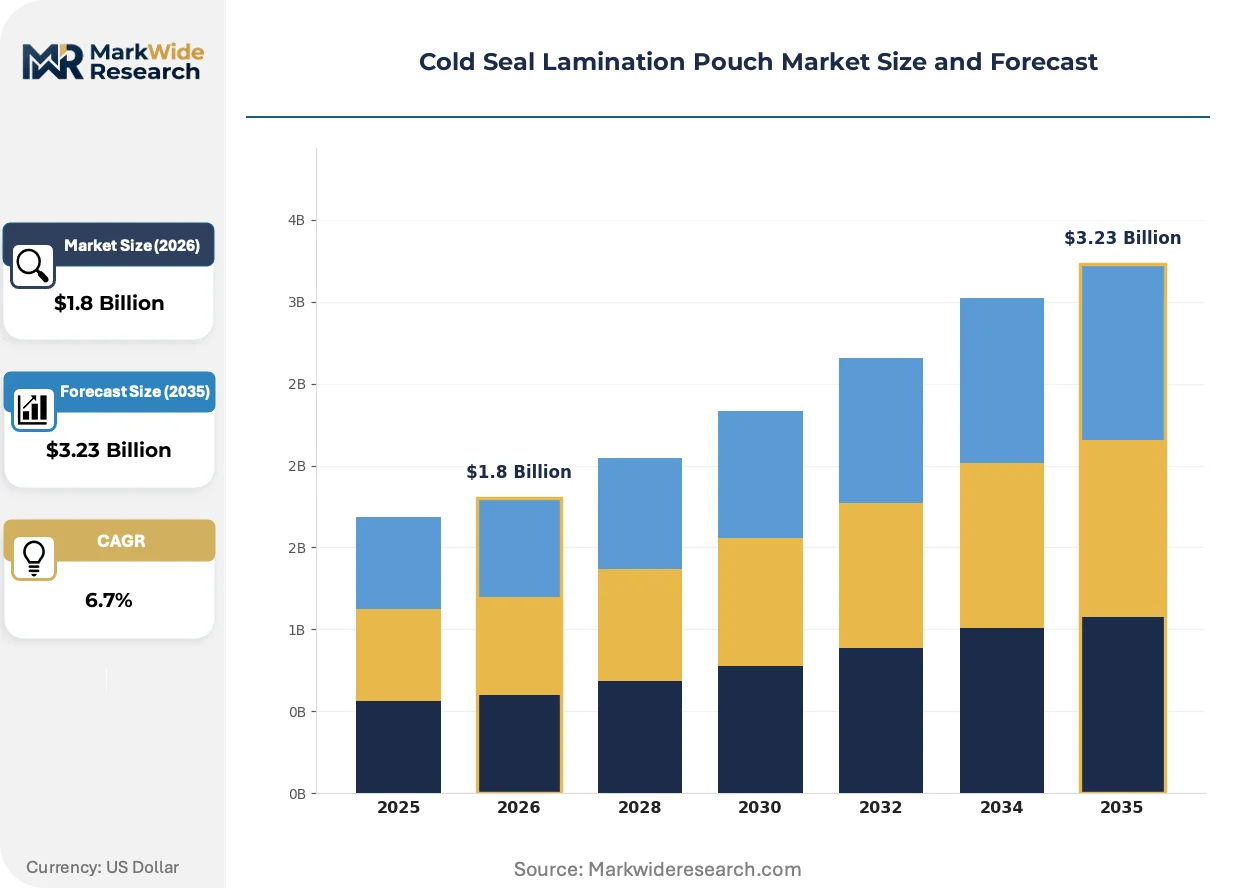
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pouches, Stand-up Pouches, Flat Pouches, Reclosable Pouches Material: BOPP, PET, Nylon, Foil Application: Food Packaging, Medical Supplies, Electronics, Cosmetics End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | GBC (General Binding Corporation), Fellowes Brands, 3M Company, ACCO Brands Corporation, Avery Products Corporation, Royal Sovereign International, Deli Group Co., Ltd., Office Depot, Inc., Staples Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Seal Lamination Pouch Market Evolving Landscape
Material science advances and regulatory convergence are compressing development cycles for medical-grade barrier films while reshaping competitive requirements across pharmaceutical and electronics end-uses.
Water-based acrylic adhesive systems are integrating into multi-layer laminates as converters seek to eliminate solvent-based coating emissions while maintaining seal strength thresholds for sterile medical packaging. German pharmaceutical corridor manufacturers are piloting these formulations at scale. This transition is integrating environmental compliance into premium product specifications without sacrificing barrier performance.
REACH substance restrictions are recasting material qualification costs across European flexible packaging supply chains as ECHA adds polymer additives and adhesive components to candidate lists. Suppliers must now maintain extensive substance documentation to retain medical device packaging approvals. German and Swiss pouch converters are absorbing disproportionate compliance overhead compared to Asian competitors.
Direct procurement from generic drug manufacturers is consolidating purchasing power previously fragmented through distribution intermediaries, particularly in India's export-oriented pharmaceutical hubs. Large-volume contract negotiations now dominate transaction patterns for standard pouch formats. This concentration is most visible in Ahmedabad and Hyderabad manufacturing clusters serving regulated European and North American markets.
Cold Seal Lamination Pouch Market Segmentation
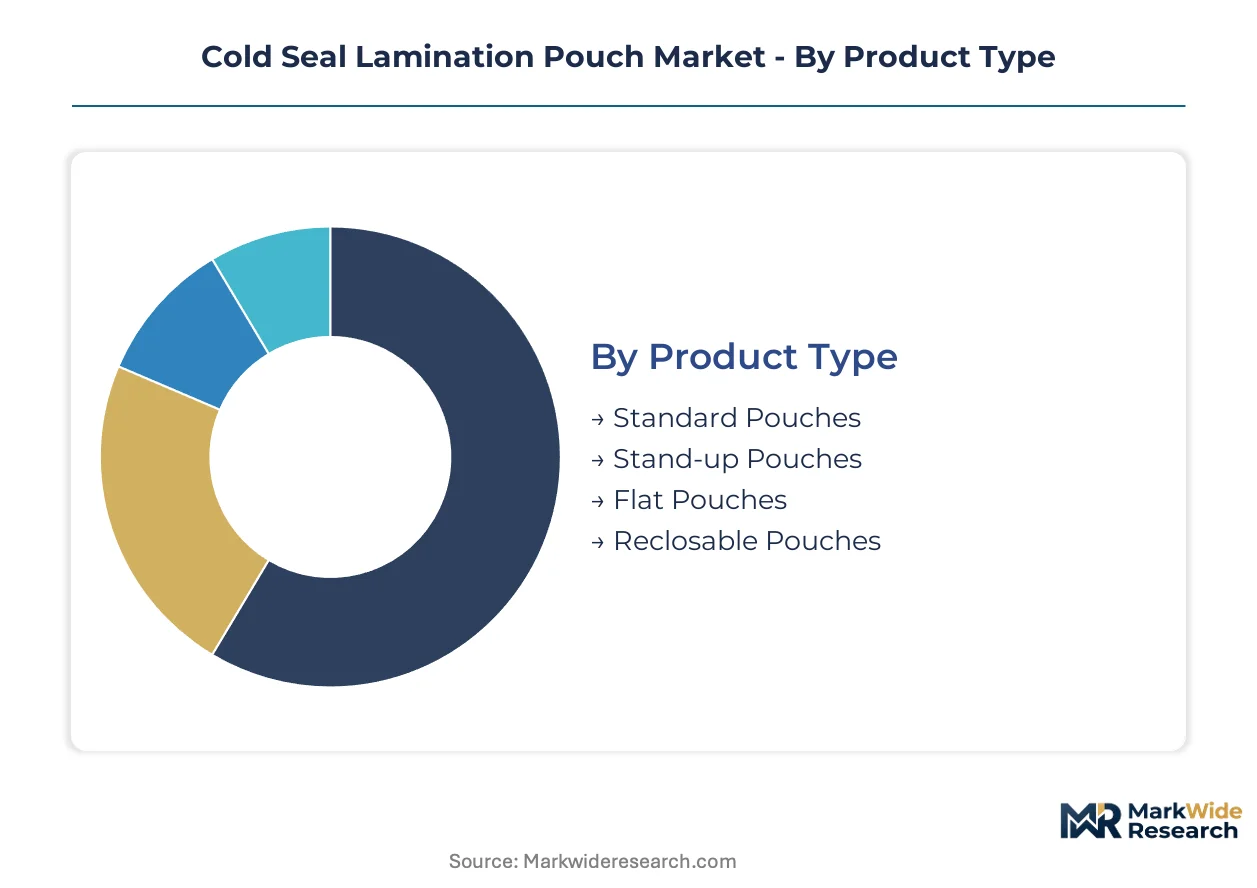
Cold seal lamination pouch specifications diverge sharply across end-use requirements, with medical-grade barrier demands commanding premium material stacks while food packaging prioritizes cost-engineered formats. Segmentation logic follows pressure-sensitive adhesive compatibility, substrate barrier performance, and regulatory validation tiers rather than conventional packaging taxonomies.
Product Type:
Volume production concentrates in standard formats, while margin capture shifts toward specialized constructions with functional differentiation.
- Standard Pouches:Three-side-seal or four-side-seal constructions using BOPP or PET substrates with acrylic adhesive coatings dominate high-volume pharmaceutical and food packaging procurement. India's generic drug export hubs in Hyderabad and Ahmedabad source these formats for moisture-sensitive active pharmaceutical ingredients bound for FDA and EMA regulated markets.
- Stand-up Pouches:Gusseted bottom constructions with die-cut handles or pour spouts incorporate multi-layer laminates with 200-400 gram per inch seal strength for shelf differentiation in retail environments. German pharmaceutical corridor manufacturers deploy these for over-the-counter medical supplies where consumer convenience intersects with barrier performance requirements.
- Flat Pouches:Simple two-ply constructions serve cost-sensitive electronics and cosmetic sampling applications where minimal barrier specifications permit thinner substrate gauges.
- Reclosable Pouches:Zipper-profile or slider-equipped formats with cold seal base closures enable repeated access without thermal resealing, addressing direct-to-consumer medical supply distribution requirements.
Mature deployment sits with standard pouch formats across established pharmaceutical supply chains. Newer deployment is concentrated in reclosable configurations serving e-commerce fulfillment channels.
Material:
Substrate selection traces directly to oxygen and moisture transmission rate requirements, with foil constructions reserving for the most sensitive contents.
- BOPP:Biaxially oriented polypropylene films provide cost-efficient moisture barriers with 20-30 gram per square meter per day water vapor transmission rates, serving standard food and non-critical medical packaging where thermal degradation risks are minimal.
- PET:Polyethylene terephthalate substrates deliver superior dimensional stability and printability for pharmaceutical labeling compliance, with metallized variants extending barrier performance for mid-tier medical device packaging in European markets subject to EU MDR documentation requirements.
- Nylon:Polyamide layers puncture resistance for industrial and logistics-intensive applications where mechanical stress threatens pouch integrity during distribution.
- Foil:Aluminum-laminate constructions achieve near-zero oxygen and moisture transmission, mandatory for biologics and temperature-sensitive generics in cold-chain logistics where ISO 11607 sterilization validation applies.
Cost-engineered specifications gravitate toward BOPP dominance in high-volume export markets. Technical performance requirements are driving fastest adoption for foil constructions in regulated medical applications.
Application:
End-use specifications fragment across contamination sensitivity thresholds, with medical and electronics demands imposing the strictest material qualification protocols.
- Food Packaging:Moisture-sensitive snacks and confectionery drive standard BOPP and PET pouch procurement, with stand-up formats capturing premium shelf positioning in retail environments.
- Medical Supplies:Sterile device packaging and pharmaceutical active ingredient protection require foil-based laminates with ISO 11607 validation, biocompatibility documentation, and seal strength thresholds of 400-800 grams per inch.
- Electronics:Flexible circuit and sensor manufacturers specify oxygen barrier performance without thermal stress during sealing, creating technical entry points for cold seal foil formats in printed electronics protection.
- Cosmetics:Sample and travel-size packaging prioritizes print quality and consumer aesthetics over extreme barrier performance, permitting thinner substrate constructions.
Procurement concentration aligns with medical supplies validation requirements in Germany and India. Electronics protection is expanding most quickly as flexible sensor manufacturing scales.
End User:
Purchasing power consolidation varies across channel structures, with direct manufacturer procurement reshaping contract dynamics in pharmaceutical segments.
- Manufacturers:Generic drug producers and medical device OEMs in India's export corridors negotiate large-volume contracts for validated pouch formats, consolidating previously fragmented distributor-mediated procurement.
- Retailers:Private-label food and cosmetic brands specify standard and stand-up pouch formats through converter-direct relationships, with sustainability requirements increasingly influencing material selection.
- Distributors:Medical supply intermediaries maintain inventory of ISO 11607-certified formats for smaller manufacturers lacking direct validation capabilities.
- E-commerce:Direct-to-consumer medical and cosmetic fulfillment channels prioritize reclosable formats with repeated access functionality and ship-ready durability.
Established procurement patterns persist through distributor networks serving mid-tier manufacturers. Direct purchasing from generic drug manufacturers is gaining share fastest in India's pharmaceutical export hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical export processing zones concentrate cold seal lamination pouch demand through tax-advantaged manufacturing clusters serving regulated markets.
Germany
EU MDR compliance mandates drive medical-grade pouch procurement from Baden-Württemberg device manufacturers. ECHA REACH substance documentation requirements constrain adhesive formulation choices for Stuttgart-based converters. The Rhine-Main pharmaceutical corridor anchors sterile packaging validation capacity for biologics exports.
United States
FDA 21 CFR Part 820 quality system regulations enforce sterilization packaging documentation for domestic device manufacturers. California's extended producer responsibility framework pressures mono-material recyclable construction adoption. Minneapolis-St. Paul medical technology clusters source foil-laminated formats for temperature-sensitive diagnostics.
India
CDSCO export certification requirements align Hyderabad and Ahmedabad generic drug manufacturers with FDA and EMA packaging standards. PLI scheme incentives expand active pharmaceutical ingredient production requiring moisture-barrier protection. Gujarat's special economic zones concentrate high-volume pouch procurement for regulated-market shipments.
China
NMPA medical device registration rules tighten biocompatibility documentation for imported packaging materials. Yangtze River Delta electronics manufacturers specify oxygen barrier films for flexible circuit protection. Zhejiang province BOPP film extrusion capacity supplies cost-engineered substrates for standard pouch formats.
Brazil
ANVISA regulatory alignment with FDA benchmarks opens certification-driven procurement for validated medical-grade suppliers. São Paulo state pharmaceutical manufacturing expansion drives sterile packaging demand for temperature-sensitive generics. The São Paulo-Minas Gerais industrial corridor attracts pouch converters establishing local validation capabilities.
Cold Seal Lamination Pouch Market Competitive Landscape
North American producers anchor the premium-tier medical-grade segment; Asian fabricators hold volume-driven standard pouch capacity. Market structure splits between consolidated multinational material science platforms and fragmented regional converters serving price-sensitive food packaging. Three archetypes dominate: polymer science specialists with ISO 11607 validation capabilities, office supply channel controllers leveraging distribution density, and scale-driven Asian manufacturers competing on cost-engineered formats. Dominant competitive moves include backward integration into adhesive formulation and strategic partnerships with generic drug manufacturers for direct procurement contracts.
Within the polymer science tier, 3M Company exemplifies premium positioning through material depth and regulatory documentation capabilities. Fellowes Brands occupies a position as a channel-anchored specialist leveraging North American office and light-industrial distribution control. Deli Group Co., Ltd. represents the scale-driven archetype, competing from manufacturing concentration in Asia on high-volume export formats for cost-sensitive procurement channels.
| Leading Market Players |
|---|
| GBC (General Binding Corporation) |
| Fellowes Brands |
| 3M Company |
| ACCO Brands Corporation |
| Avery Products Corporation |
| Royal Sovereign International |
| Deli Group Co., Ltd. |
| Office Depot, Inc. |
| Staples Inc. |
| Others |
Value Network & Pricing Analysis
ISO 11607 certification tiers bifurcate the cold seal lamination pouch landscape into validated medical-grade suppliers commanding premium positioning and commodity converters competing on spot-market BOPP substrates, with this divergence manifesting in both pricing power concentration and supply chain geographic clustering around testing-capable manufacturing hubs.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid-turnaround medical-grade pouch producers with 15-25% premiums over standard-format spot inventory. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 11607 validation status, foil-laminate construction depth, and direct-procurement contract scale. Cost compression in standard BOPP formats is intensifying because Yangtze River Delta film extrusion capacity expansion outpaces converter demand growth. Generic drug manufacturers in India's export corridors exhibit highest price sensitivity, while German biologics producers prioritize barrier performance over unit economics.
Supply Chain Analysis
Workforce availability constraints in Zhejiang province BOPP extrusion facilities and Gujarat special economic zone converting plants are tightening operational flexibility for high-volume pouch producers. Raw material sourcing draws from Saudi petrochemical feedstocks for acrylic adhesive monomers, Taiwanese metallized PET film, and domestic Chinese aluminum foil rolling capacity. Single-source vulnerability concentrates in pressure-sensitive adhesive formulation expertise held by a limited tier of polymer science specialists. Distribution runs through direct procurement contracts with generic drug manufacturers, medical device OEMs, and distributor-mediated channels serving mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around ISO 11607 validation capacity prop pricing premiums, as sterilization packaging certification cycles stretching 18-24 months create artificial scarcity for qualified medical-grade pouch suppliers.
For Market Incumbents: Lock in backward integration into water-based acrylic adhesive formulation to capture margin pool erosion from REACH substance documentation requirements. Expand captive testing laboratory capacity in Germany's pharmaceutical corridor to shorten validation timelines and defend against emerging Asian competitors pursuing EMA alignment. Prioritize direct procurement contracts with Hyderabad and Ahmedabad generic drug clusters before purchasing power consolidates further. For New Entrants and Emerging Players: E-commerce fulfillment channel specialization offers lowest barrier-to-entry expansion path for reclosable pouch formats serving direct-to-consumer medical supply distributors. Target Brazil's ANVISA regulatory alignment window before certification requirements harden to FDA-equivalent standards. Pursue printed electronics protection applications where oxygen barrier specifications without thermal stress create technical differentiation wedge against heat-seal incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by polymer science platforms seeking ISO 11607 capabilities, with strategic buyers from adjacent barrier film segments most active. Long-term viability favors validated medical-grade specialists over commodity converters facing heat-seal substitution and EPR framework compliance costs. Watch ANVISA certification completion rates as inflection indicator for Latin American market timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607 Validation Laboratory Expansion | Shortens certification cycles from 24 months, capturing premium medical-grade contract flow from German biologics exporters. |
| Water-Based Adhesive Formulation Transition | Eliminates solvent-based coating emissions while maintaining seal strength for EU MDR-compliant sterile packaging. |
| Direct Procurement Partnership with Indian Generics | Bypasses distributor intermediaries in Hyderabad and Ahmedabad clusters, locking volume commitments for foil-laminate formats. |
| Brazil ANVISA Certification Pre-Positioning | Establishes regulatory documentation capabilities ahead of FDA-equivalent standard enforcement in São Paulo pharmaceutical corridor. |
| Mono-Material Recyclable Construction Development | Aligns pouch substrate stacks with pending EU packaging waste revisions and California EPR framework incentives. |
Research Methodology
Document review covered FDA 21 CFR Part 820 filings, EMA MDR technical documentation, CDSCO export certification records, and ISO 11607 sterilization packaging standards, complemented by interviews with procurement directors at Indian generic drug manufacturers, biomedical engineers at German medical device OEMs, and flexible packaging converters in the Yangtze River Delta. Secondary validation drew from customs trade data, pharmaceutical packaging industry associations, and SEC filings of listed material science platforms. Bottom-up demand modeling from end-use procurement patterns was cross-referenced against top-down supply capacity assessments.
Cross-reference between historical validation timeline data and expert panel input on regulatory convergence shaped the analytical framework across the analysis window. Segmentation dimensions modeled include pouch format type, substrate material stack, application sector, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from volume-weighted average growth trajectories across these segments, incorporating pharmaceutical cold-chain logistics expansion rates and electronics protection application adoption curves as industry-specific forecast inputs.
The model holds under stable regulatory alignment between FDA, EMA, and ANVISA standards; deviation in REACH substance restriction timelines or BOPP substrate supply disruptions would shift capacity utilization assumptions. Forecasts reflect documented sterilization packaging demand patterns and adhesive raw material cost structures. Material deviation in EU MDR enforcement intensity or Indian PLI scheme pharmaceutical production incentives warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Liquid Pouch Packing Machine Market
Pouch
Squeeze Pouch Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Foil Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
PCR Pouches Market
Pouch
Spout Pouch Market
Pouch
Aluminum Pouches Market
Pouch
Latin America Pouch Packaging Market
Pouch
Argentina Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Flexible Pouch Market
Pouch
Liquid Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Stick Pouches Packaging Market