
 Aesthetic Ophthalmology Device Market | 2026-2036
Aesthetic Ophthalmology Device Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Ophthalmology Device Market Analytics
Pay-per-procedure leasing and subscription-based equipment financing is reshaping competitive dynamics in aesthetic ophthalmology, lowering capital barriers for independent clinics and med spa chains. Alcon Inc. leverages its extensive refractive surgery installed base to cross-sell complementary aesthetic platforms. Johnson & Johnson Vision anchors its position through deep R&D pipelines spanning both diagnostic and therapeutic eye care modalities. Syneron Candela differentiates via specialized energy-based systems targeting periorbital applications.
Aesthetic ophthalmology devices encompass precision instruments engineered to modify or enhance ocular and periocular anatomy, typically operating at wavelength-specific energy outputs measured in nanometers for laser platforms and megahertz frequencies for ultrasound modalities, with primary commercial purpose spanning cosmetic rejuvenation and functional correction of eyelid, tear trough, and orbital surface conditions. Laser Systems occupy the dominant revenue position given their versatility across ablative resurfacing and non-ablative collagen stimulation protocols, while Aesthetic Injections represent the fastest-expanding category as hyaluronic acid and biostimulator formulations gain traction for nonsurgical orbital enhancement. Med Spas are capturing disproportionate growth within the End User dimension as regulatory clarity around scope-of-practice rules enables broader device deployment outside traditional hospital settings.
FDA 510(k) clearance requirements and the EU Medical Device Regulation establish divergent compliance burdens that shape product development timelines and geographic launch sequencing for aesthetic ophthalmology device manufacturers. ISO 13485 quality management standards and IEC 60601 electrical safety protocols further constrain design choices for multi-modality platforms intended for simultaneous diagnostic and therapeutic use. Stakeholders must monitor evolving scope-of-practice regulations in key states and European member countries to anticipate where device utilization permissions will expand or contract.
Market Dynamics
Pay-per-procedure leasing and subscription-based equipment financing is compressing capital barriers for independent clinics and med spa chains, reshaping competitive dynamics in aesthetic ophthalmology by enabling broader device deployment outside traditional hospital procurement channels.
Growth Catalysts
- Med Spa Regulatory Clarity:Scope-of-practice rule expansions in key US states are enabling broader device utilization outside hospital settings. Med spas now deploy laser and energy-based platforms previously restricted to ophthalmology suites.
- FDA 510(k) Pathway Compression:Streamlined clearance timelines for laser platforms with predicate device equivalence are accelerating time-to-market for novel periorbital treatment systems.
- Hyaluronic Acid Formulation Advances:Next-generation biostimulator compounds are extending treatment longevity for tear trough and orbital contouring applications, expanding addressable patient populations.
Market Restraints
- EU MDR Compliance Burden:The European Medical Device Regulation's enhanced clinical evidence requirements are extending product development timelines and increasing certification costs for multi-modality platforms.
- Laser Component Supply Concentration:Precision optical components and wavelength-specific diodes concentrate manufacturing in specialized German and Japanese supplier networks, creating input vulnerability.
- Non-Surgical Substitute Efficacy:Topical retinoid and peptide formulations are improving periorbital skin quality sufficiently to delay or replace energy-based interventions for early-stage aging concerns.
Strategic Opportunities
- Underpenetrated Indian Metro Markets:Mumbai, Delhi, and Bangalore present whitespace for premium device deployment as disposable income rises and dermatology clinic chains professionalize periorbital service offerings.
- Diagnostic-Therapeutic Convergence:Integration of high-resolution anterior segment imaging with real-time laser delivery systems is enabling personalized treatment parameter selection and outcome prediction.
- Subscription Equipment Financing:Usage-based leasing models are lowering acquisition barriers for independent aesthetic practitioners, expanding the addressable clinic base beyond capital-rich hospital systems.
Industry Challenges
- Periorbital Anatomy Expertise Gap:Safe device operation around the orbital rim and lacrimal apparatus requires specialized anatomical knowledge that standard aesthetic training curricula inadequately address.
- Legacy EMR Integration Friction:Aesthetic ophthalmology platforms must interface with diverse electronic medical record systems, complicating workflow automation and outcome tracking across multi-site clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Ophthalmology Device Market |
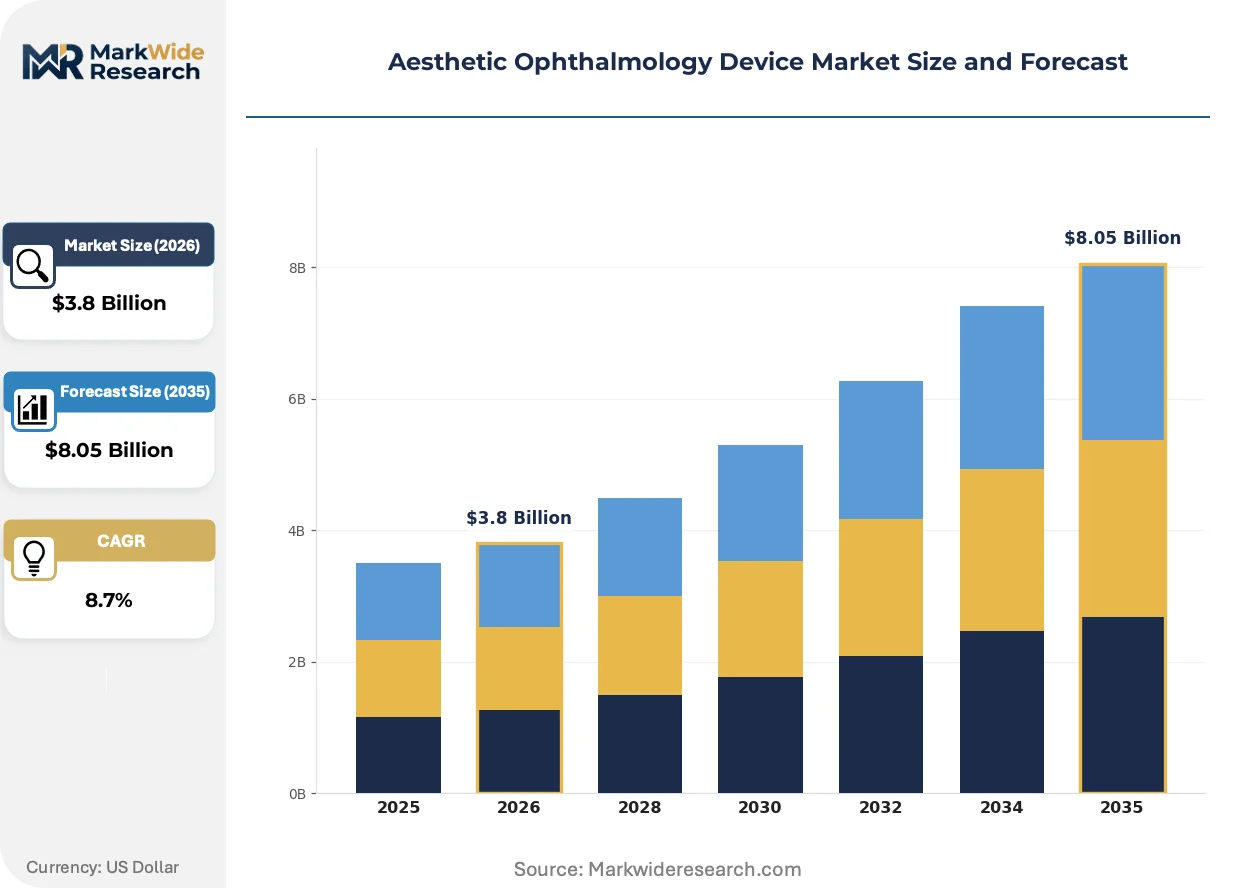
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Ultrasound Devices, Aesthetic Injections, Surgical Instruments Technology: Non-ablative, Ablative, Radiofrequency, Cryotherapy End User: Clinics, Hospitals, Med Spas, Eye Care Centers Application: Rejuvenation, Correction, Enhancement, Treatment |
| Companies Covered | Alcon Inc., Allergan Plc., Carl Zeiss Meditec AG, Bausch & Lomb Inc., Lumenis Ltd., Johnson & Johnson Vision, Topcon Corporation, Zeimer Ophthalmic Systems AG, Syneron Candela, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Ophthalmology Device Market Evolving Landscape
Energy-based modalities and precision injection systems are converging with digital imaging to enable personalized, minimally invasive periorbital rejuvenation protocols that reduce downtime and improve predictability.
Picosecond and femtosecond laser platforms with tunable wavelength outputs are enabling selective photothermolysis of melanin and hemoglobin chromophores in periorbital skin. High-end med spas and oculoplastic surgery centers are replacing traditional nanosecond systems at accelerated replacement cycles. The superior safety profile for darker skin phototypes is rendering obsolete older ablative resurfacing protocols that carried elevated dyschromia risk.
The EU Medical Device Regulation's 2021 implementation is mandating enhanced post-market surveillance and unique device identification for all laser and energy-based aesthetic platforms. Manufacturers must now maintain clinical registries and periodic safety update reports across their European installed base. Class IIa and IIb devices for periorbital application face the steepest compliance cost increases, compressing margins for mid-tier equipment suppliers.
After-sales service unbundling is separating equipment maintenance contracts from consumable supply agreements. Independent clinic buyers increasingly procure disaggregated service tiers through third-party biomedical engineering networks rather than captive manufacturer programs. This disintermediation is most pronounced in the United States, where dense independent service organization networks compete directly with OEM service divisions for multi-site dermatology and ophthalmology group contracts.
Aesthetic Ophthalmology Device Market Segmentation
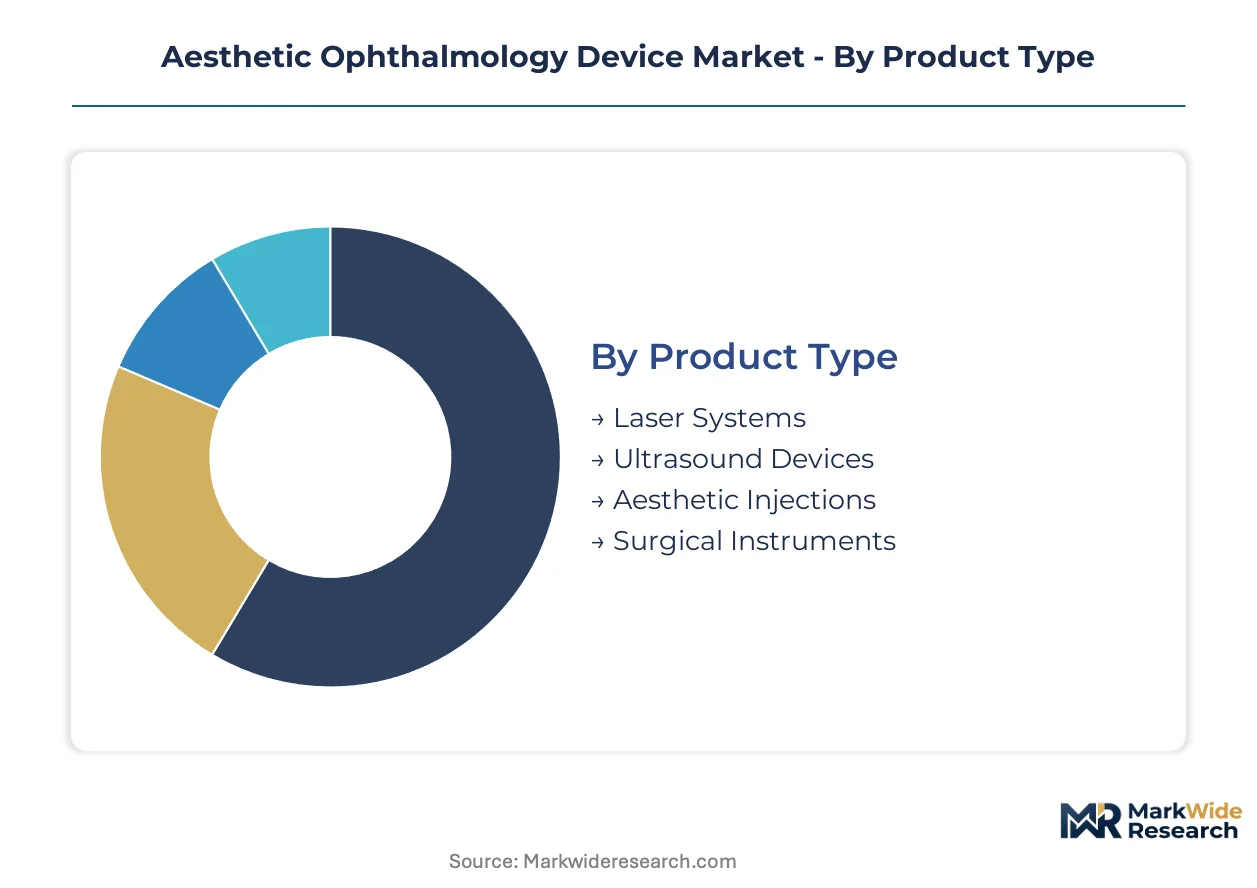
Device taxonomy in aesthetic ophthalmology determines reimbursement pathways, regulatory classification, and procurement channel selection. Manufacturers configure platform portfolios across multiple segmentation dimensions to capture volume in high-throughput settings while defending margin in specialized applications.
Product Type:
Mature capital equipment categories coexist with emerging consumable-heavy modalities, creating divergent margin profiles and replacement cycle dynamics.
- Laser Systems:Wavelength-specific platforms operating in nanometer ranges enable selective photothermolysis for periorbital resurfacing and pigment correction. Demand concentrates in United States oculoplastic surgery centers where high disposable income supports premium platform acquisition and where FDA 510(k) pathway compression accelerates technology refresh cycles.
- Aesthetic Injections:Hyaluronic acid and biostimulator formulations delivered via precision micro-cannula systems address tear trough hollowing and orbital contouring without energy-based tissue interaction. Med spas in California, Texas, and Florida deploy these systems most intensively as scope-of-practice expansions enable non-physician injector operation under medical director supervision.
- Ultrasound Devices:Micro-focused ultrasound platforms deliver thermal coagulation points at specified depths for brow lifting and periorbital tightening.
- Surgical Instruments:Precision blepharoplasty tools and orbital implants address functional eyelid malposition and aesthetic contour modification.
Laser Systems handle the majority of throughput; Aesthetic Injections are gaining share fastest as procedure volume migrates toward minimally invasive alternatives.
Technology:
Cost tier stratification separates premium wavelength-tunable platforms from standardized single-modality systems, with reimbursement and outcome predictability driving selection.
- Non-ablative:Fractional and bulk heating modalities stimulate collagen remodeling without epidermal disruption, enabling minimal-downtime protocols. United States dermatology clinic chains prioritize these systems for patient throughput optimization and reduced complication management burden.
- Ablative:Er:YAG and CO2 laser platforms deliver controlled epidermal vaporization for severe periorbital rhytidosis. Academic medical centers in Germany and Japan maintain installed bases for complex revision cases where tissue tightening magnitude justifies extended recovery.
- Radiofrequency:Bipolar and multipolar devices deliver dermal heating through electrical resistance rather than optical absorption.
- Cryotherapy:Controlled cooling platforms address periorbital fat herniation and skin laxity through selective adipocyte injury.
Non-ablative technology dominates current procurement volume; Ablative systems retain position in high-acuity correction segments.
End User:
Customer type determines capital availability, regulatory scrutiny intensity, and service model requirements for equipment manufacturers.
- Med Spas:Freestanding aesthetic facilities outside hospital ownership deploy devices under medical director protocols with varying state-level supervision requirements. Texas, Arizona, and Colorado have clarified scope-of-practice rules most explicitly, enabling accelerated device deployment and technician-level operation for specified modalities.
- Clinics:Physician-owned dermatology and ophthalmology practices balance equipment utilization across medical and aesthetic service lines.
- Hospitals:Academic and community health systems integrate aesthetic platforms within oculoplastic and facial plastic surgery departments.
- Eye Care Centers:Optometry-forward chains and refractive surgery centers add periorbital aesthetic services to capture patient lifetime value.
Med Spas are expanding most quickly as capital-light leasing models enable independent operator entry; Hospitals retain highest per-platform revenue concentration.
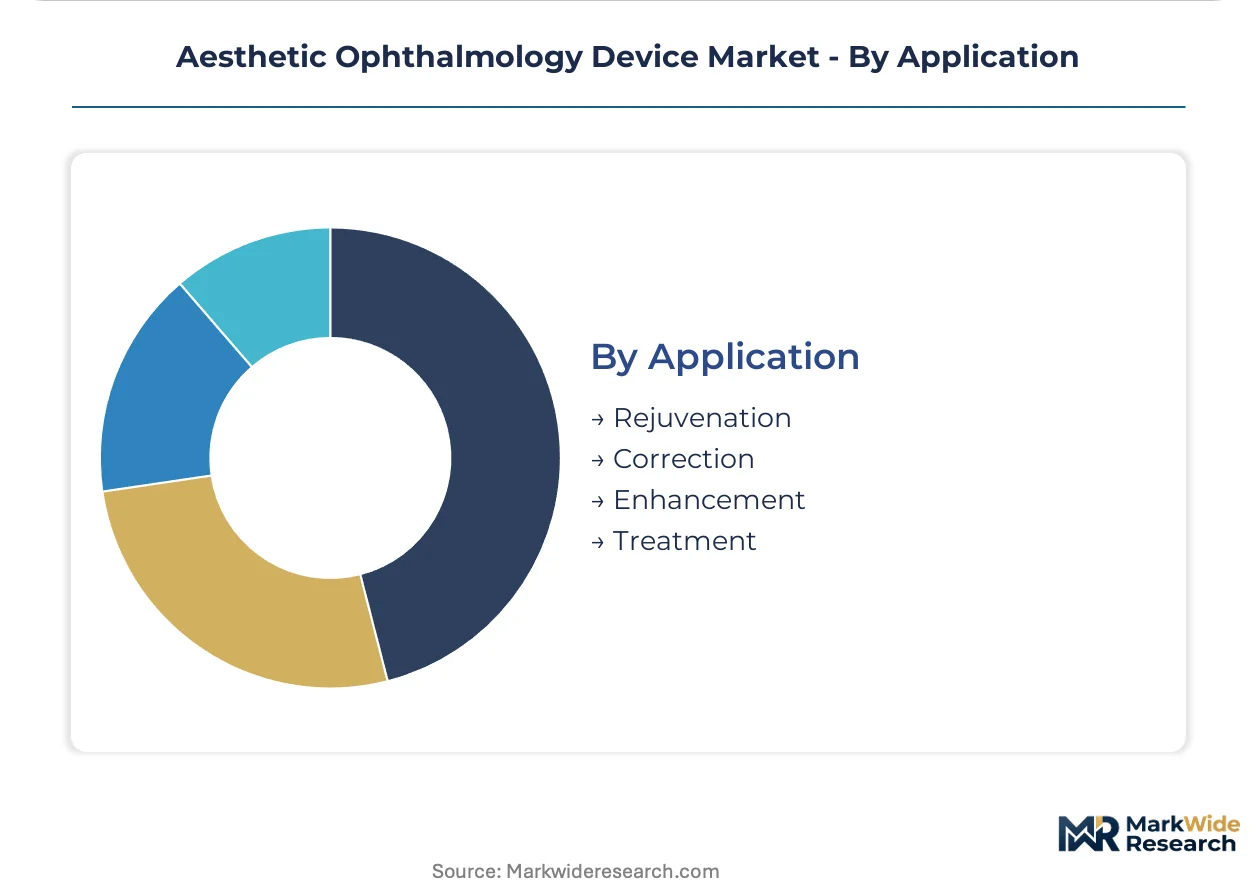
Application:
Volume distribution across application types reflects demographic aging patterns and cultural preference for preventive versus corrective intervention.
- Rejuvenation:Collagen stimulation, pigment correction, and surface texture improvement protocols target early to moderate periorbital aging. United States coastal metropolitan markets show highest procedure density as consumer aesthetic awareness and disposable income concentrate.
- Enhancement:Tear trough volumization, brow shaping, and orbital contour definition address structural rather than age-related concerns.
- Correction:Functional and aesthetic revision of prior surgical outcomes or congenital asymmetries.
- Treatment:Pathology-directed intervention for dermatologic conditions affecting periorbital appearance.
Rejuvenation commands the largest addressable population; Enhancement shows the steepest expansion trajectory as younger demographics enter the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented German laser component suppliers dominate upstream supply chains for wavelength-specific diodes, while the United States runs the largest import surplus for finished aesthetic platforms. Device trade flows concentrate between specialized manufacturing clusters in Bavaria and consumption hubs in coastal US metropolitan markets.
United States
High disposable income in California, Texas, and Florida drives premium laser platform procurement for med spa chains. FDA 510(k) pathway compression accelerates time-to-market for novel periorbital systems. Los Angeles and Miami host the densest concentrations of oculoplastic surgery centers deploying picosecond wavelength technologies.
Germany
Precision optical component manufacturing in Bavaria and Baden-Württemberg supplies wavelength-specific diodes to global device assemblers. EU MDR compliance requirements extend certification timelines for multi-modality platforms. Munich anchors the highest concentration of laser subsystem engineering firms serving aesthetic ophthalmology OEMs.
Japan
Aging demographics in Tokyo and Osaka sustain demand for minimally invasive periorbital rejuvenation protocols. PMDA regulatory frameworks maintain stringent clinical evidence standards for energy-based devices. Nagoya's industrial corridor concentrates manufacturing of high-precision optical assemblies for export to Asian device integrators.
India
Rising disposable income in Mumbai, Delhi, and Bangalore creates whitespace for premium device deployment in professionalizing dermatology chains. CDSCO import regulations shape geographic launch sequencing for multinational manufacturers. Hyderabad's medical technology corridor attracts contract manufacturing for mid-tier laser platforms targeting domestic and Southeast Asian markets.
South Korea
Advanced aesthetic medicine culture in Seoul drives early adoption of picosecond and femtosecond laser systems. MFDS regulatory alignment with international standards facilitates parallel device registrations. The Seoul Capital Area concentrates both consumption demand and domestic manufacturing of ultrasound-based periorbital tightening platforms.
Aesthetic Ophthalmology Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying wavelength-specific diodes and precision optical assemblies. The vendor base separates into three tiers: multinational conglomerates with installed base advantages, mid-scale specialists in energy-based modalities, and regional assemblers serving price-sensitive markets. Strategic moves concentrate on cross-selling complementary platforms to existing refractive surgery accounts and disaggregating after-sales service from captive manufacturer programs.
Among diversified ophthalmology conglomerates, Alcon Inc. and Johnson & Johnson Vision occupy positions leveraging extensive refractive surgery installed bases for aesthetic platform cross-selling. Carl Zeiss Meditec AG represents the precision optics archetype, with German engineering heritage anchoring high-end diagnostic-therapeutic convergence systems. Syneron Candela exemplifies the energy-based specialist tier, differentiated through focused periorbital applications rather than broad ophthalmology portfolios.
| Leading Market Players |
|---|
| Alcon Inc. |
| Allergan Plc. |
| Carl Zeiss Meditec AG |
| Bausch & Lomb Inc. |
| Lumenis Ltd. |
| Johnson & Johnson Vision |
| Topcon Corporation |
| Zeimer Ophthalmic Systems AG |
| Syneron Candela |
| Others |
Value Network & Pricing Analysis
The Frankfurt-Mumbai air freight corridor carries wavelength-specific laser diodes and precision optical assemblies from Bavarian manufacturing clusters to Indian device integrators, with per-kilogram freight costs feeding directly into margin structures for mid-tier platform assemblers and reinforcing price stratification between FDA-cleared premium systems and CDSCO-registered economy alternatives.
Pricing Analysis
Hospital procurement committees and med spa chains anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) predicate equivalence and ISO 13485 certification grade serving as the primary differentiation drivers. Pricing pressure stems from EU MDR compliance cost absorption compressing margins for Class IIb device manufacturers serving European oculoplastic centers. Independent dermatology clinics exhibit highest price sensitivity due to capital constraints, while academic medical centers demonstrate lowest sensitivity given grant-funded acquisition channels.
Supply Chain Analysis
Precision optical feedstock draws from concentrated German and Japanese supplier networks, with erbium-doped fiber amplifiers and picosecond pulse generators resting on specialized Bavarian engineering capabilities. Single-source vulnerability concentrates around wavelength-tunable diode arrays manufactured in Nagoya's industrial corridor. Distribution runs through authorized device distributors serving multi-site clinic networks, with after-sales service increasingly disaggregated from captive OEM programs through third-party biomedical engineering contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create entrenched switching costs that protect incumbent installed bases from rapid displacement.
For Market Incumbents: Insulate market position by deepening backward integration into precision optical component manufacturing to offset German and Japanese supplier concentration, while accelerating diagnostic-therapeutic platform convergence to raise replacement-cycle barriers against standalone laser competitors. The threat of pay-per-procedure leasing models from emerging capital-light entrants demands defensive certification investment in next-generation picosecond wavelength systems. For New Entrants and Emerging Players: Build out white-space presence in Indian metropolitan dermatology chains where CDSCO import regulations lag FDA clearance timelines, creating temporal arbitrage opportunities for mid-tier platform deployment. The most penetrable segment lies in subscription-based equipment financing for independent med spas in Texas and Arizona where scope-of-practice clarity enables technician-level device operation under medical director protocols. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating compliance infrastructure value for Class IIa and IIb device portfolios. Long-term viability centers on platforms with dual US-EU regulatory clearance spanning the projection horizon. Target acquisition archetypes include energy-based specialists with concentrated periorbital applications and established clinical registries. The signal to watch is FDA 510(k) predicate device expansion rates for novel wavelength platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Platform Convergence | Integration of anterior segment imaging with laser delivery enables personalized parameter selection in oculoplastic surgery centers. |
| Subscription Equipment Financing Expansion | Usage-based leasing lowers capital barriers for independent med spa chains in California and Florida. |
| EU MDR Clinical Registry Development | Post-market surveillance infrastructure satisfies enhanced evidence requirements for Class IIb periorbital devices. |
| Backward Integration into Optical Components | Captive supply of wavelength-specific diodes reduces dependency on Bavarian and Nagoya supplier networks. |
| Scope-of-Practice Regulatory Engagement | Active participation in state-level supervision rule clarifications expands addressable technician-operated device markets. |
Research Methodology
Cross-validation between primary interviews with oculoplastic surgeons, med spa medical directors, biomedical procurement managers, and GPO contracts administrators anchors the qualitative findings, while secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare procedure databases, and hospital procurement platform records. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from equipment manufacturer revenue disclosures.
Calibration against historical technology refresh cycles and replacement dynamics informs the analytical framework across the analysis window, with segmentation modeling spanning product type, technology modality, end-user facility category, and application purpose. CAGRs derive from fitted growth curves incorporating procedure volume migration toward minimally invasive alternatives and capital expenditure patterns across hospital and non-hospital settings.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated optical component manufacturers or rapid scope-of-practice expansions in additional US states would shift outcomes beyond modeled ranges. Cross-checking against oculoplastic society procedure registries and state-level med spa licensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Disease Therapeutics Market