
 Peas Market | 2026-2036
Peas Market Size, Share, and Industry Trends Forecast 2026-2036
Peas Market Analysis
Agronomic expertise in pulse-crop rotation is collapsing across North American growing regions, constraining yield consistency for pea protein suppliers. Roquette Frères anchors its position through backward integration into European pea starch extraction. Kerry competes by leveraging its flavor-systems R&D to mask off-tastes in plant-based formulations. Emsland Group dominates modified pea starch production for industrial food applications.
Peas are leguminous seeds of Pisum sativum, containing approximately 20-25% protein by dry weight and valued for their balanced amino-acid profile with notable lysine content. The crop serves as a rotational nitrogen-fixing plant and as a raw material for protein isolates, starches, and fibers in food manufacturing. Yellow peas lead the product-type segment due to their higher protein yield and superior processing efficiency for isolate production. The snack-products end-use category is expanding fastest, driven by extruded high-protein crisps and puffed formulations. Ingredient suppliers occupy the deepest margin pools through long-term contracts with CPG brands seeking clean-label protein alternatives.
The USDA enforces grading standards for dry peas under the Agricultural Marketing Act, directly shaping export eligibility and price premiums for North American growers. The EU Green Deal and REACH frameworks impose sustainability and chemical-compliance requirements on pea-processing facilities selling into European food channels. India's FSSAI mandates contaminant thresholds and labeling protocols for pea-protein imports destined for domestic retail. Stakeholders must monitor evolving carbon-accounting rules for agricultural inputs, as scope-three emissions disclosure becomes a procurement gate for multinational food manufacturers.
Market Dynamics
Plant-based protein procurement is reshaping pea supply chains as multinational food manufacturers impose scope-three carbon disclosure requirements on ingredient suppliers, forcing backward integration investments across North American and European processing infrastructure.
Growth Catalysts
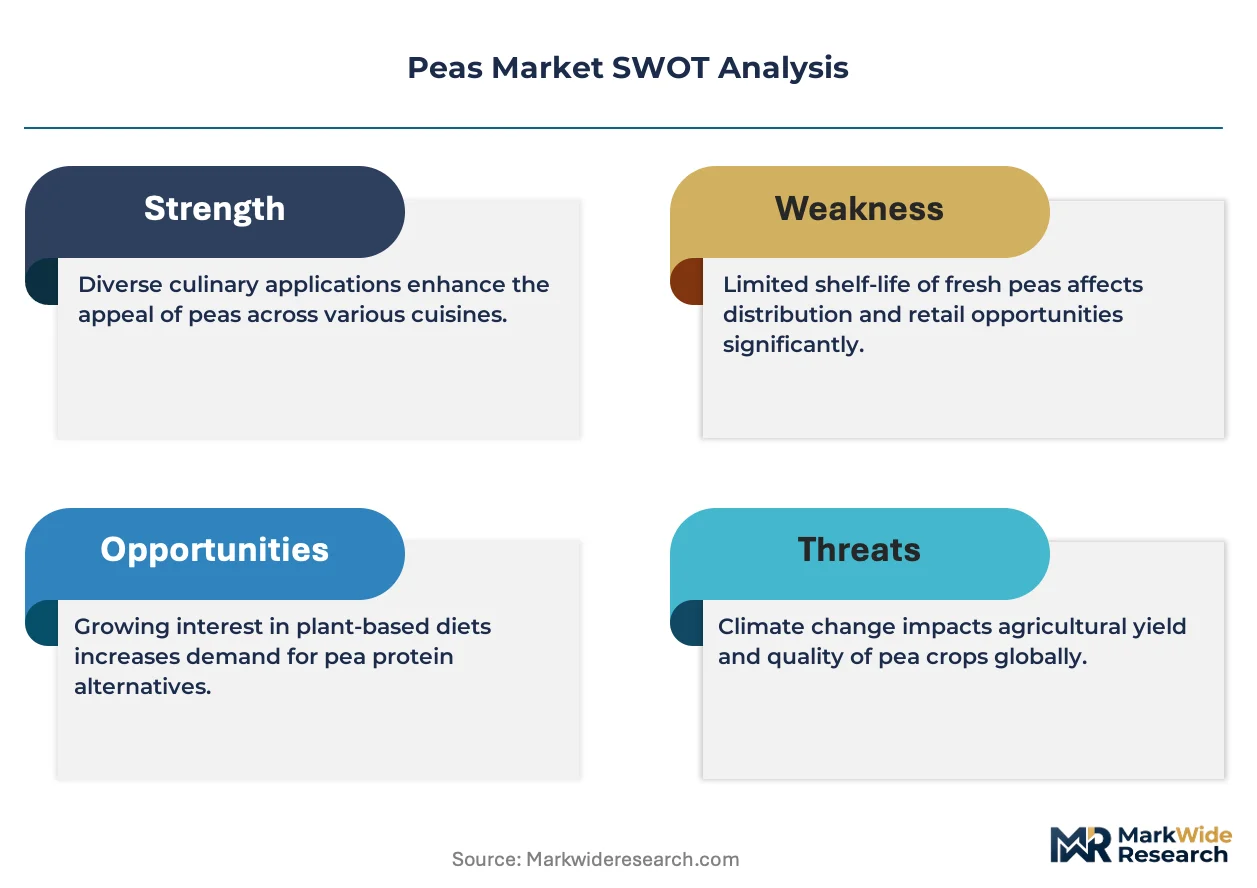
- EU Green Deal carbon-accounting mandates:European food manufacturers now require documented agricultural emissions data from pea protein suppliers, creating competitive advantage for processors with certified low-carbon extraction facilities.
- Snack-product extrusion technology:High-protein puffed formulations are capturing shelf space previously dominated by corn and potato bases, driving isolate demand from extrusion equipment operators.
- India:FSSAI's tightening contaminant thresholds for imported pea protein are accelerating domestic processing capacity buildout to serve both local retail and re-export channels.
Market Restraints
- Yellow pea protein concentrate supply:Canadian prairie agronomic expertise in pulse rotation has eroded, constraining consistent raw material flow to isolate producers.
- REACH chemical-compliance costs:European pea starch processors face escalating registration and testing burdens for modified starch derivatives entering food contact applications.
- Soy protein isolate substitution:Mature soy processing infrastructure and established supply relationships limit pea protein penetration in cost-sensitive meat-analogue formulations.
Strategic Opportunities
- India domestic market:Underdeveloped organized retail penetration for plant-based ingredients creates first-mover advantage for processors establishing direct distribution to emerging CPG brands.
- Precision fermentation convergence:Hybrid formulations combining pea protein base with fermentation-derived functional ingredients enable texture properties unmatched by single-source alternatives.
- E-commerce ingredient channels:Direct-to-manufacturer platforms are disintermediating traditional commodity brokers, allowing smaller processors to secure long-term contracts with specialty food startups.
Industry Challenges
- Agronomic skill reconstruction:North American extension services lack personnel trained in pulse-crop management, delaying yield recovery programs.
- Carbon certification timeline:Third-party verification of scope-three agricultural emissions remains inconsistent across certifying bodies, complicating customer qualification.
- Modified starch IP complexity:Patent thickets surrounding specific esterification processes for pea starch derivatives create licensing friction for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peas Market |
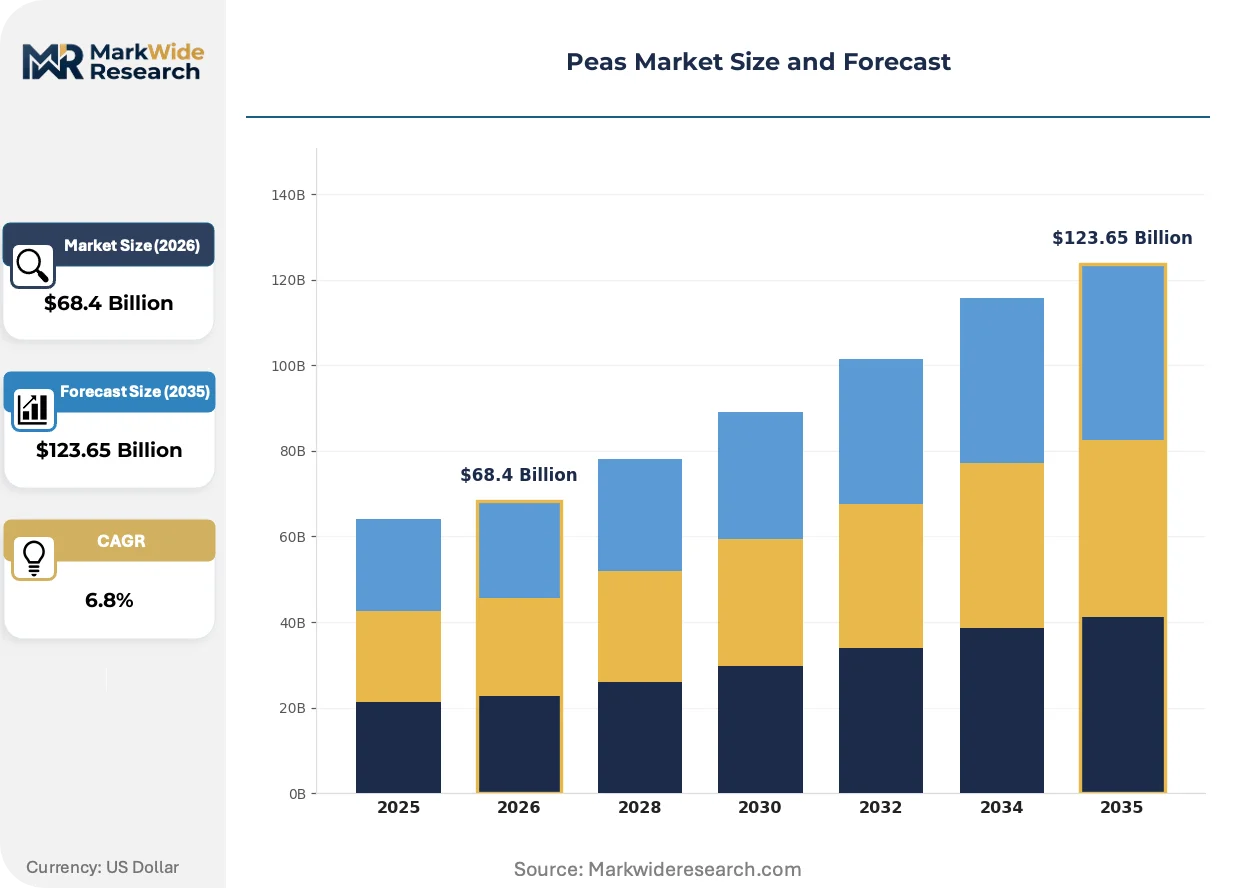
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
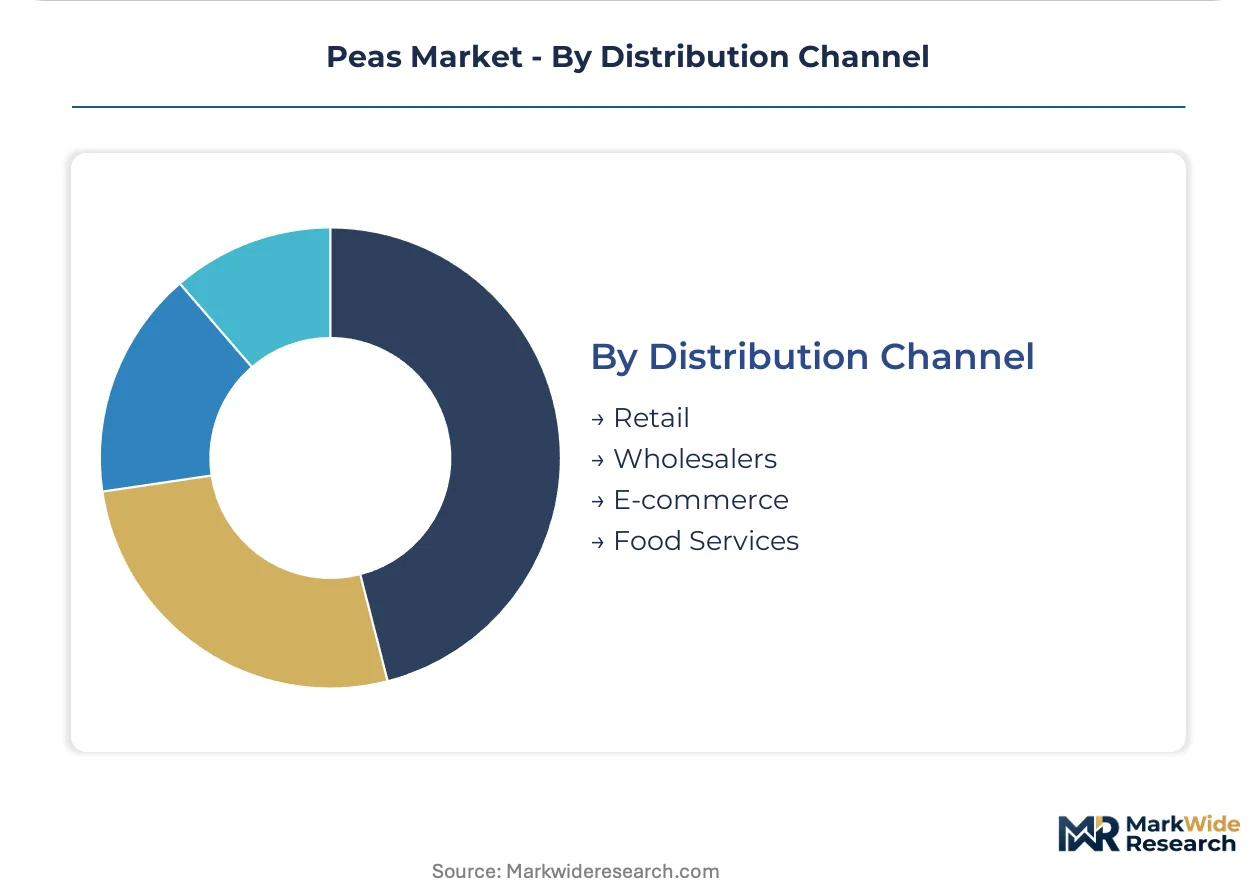
| Segmentation | Product Type: Green Peas, Yellow Peas, Frozen Peas, Canned Peas End Use: Food Industry, Snack Products, Animal Feed, Ingredient Suppliers Packaging Type: Bagged, Canned, Frozen, Bulk Distribution Channel: Retail, Wholesalers, E-commerce, Food Services |
| Companies Covered | Kerry, Emsland Group, Roquette Frères, The Scoular Company, Yantai Shuangta Foods Co, Ltd, Cargill, Incorporated, Ingredion Incorporated, Burcon Nutrascience Corp, Glanbia PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peas Market Emerging Trajectories
Processing technology convergence with sustainability verification systems is compressing development cycles for pea-derived ingredients while fragmenting procurement authority across sustainability, R&D, and procurement functions within buyer organizations.
Dry-fractionation equipment is miniaturizing. Mobile processing units now enable on-farm protein concentration, reducing transport costs for decentralized Canadian prairie production. Small-scale food manufacturers are adopting these systems at pilot scale. This distributed architecture is compressing the traditional hub-and-spoke supply model dominated by central isolate facilities.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in pea protein drying operations. European processors must retrofit spray-drying equipment with alternative refrigerant systems or absorb compliance penalties. Modified starch production lines in Germany and the Netherlands are experiencing the most acute retrofit timelines and capital allocation pressure.
CPG brand technical buyers now require full supply chain transparency documentation prior to contract negotiation. Traditional broker-mediated spot purchasing is yielding to direct processor relationships with multi-year volume commitments. This behavioral shift is most pronounced among North American alternative-meat startups and European clean-label snack manufacturers seeking defensible sourcing narratives for investor and consumer communications.
Peas Market Segmentation
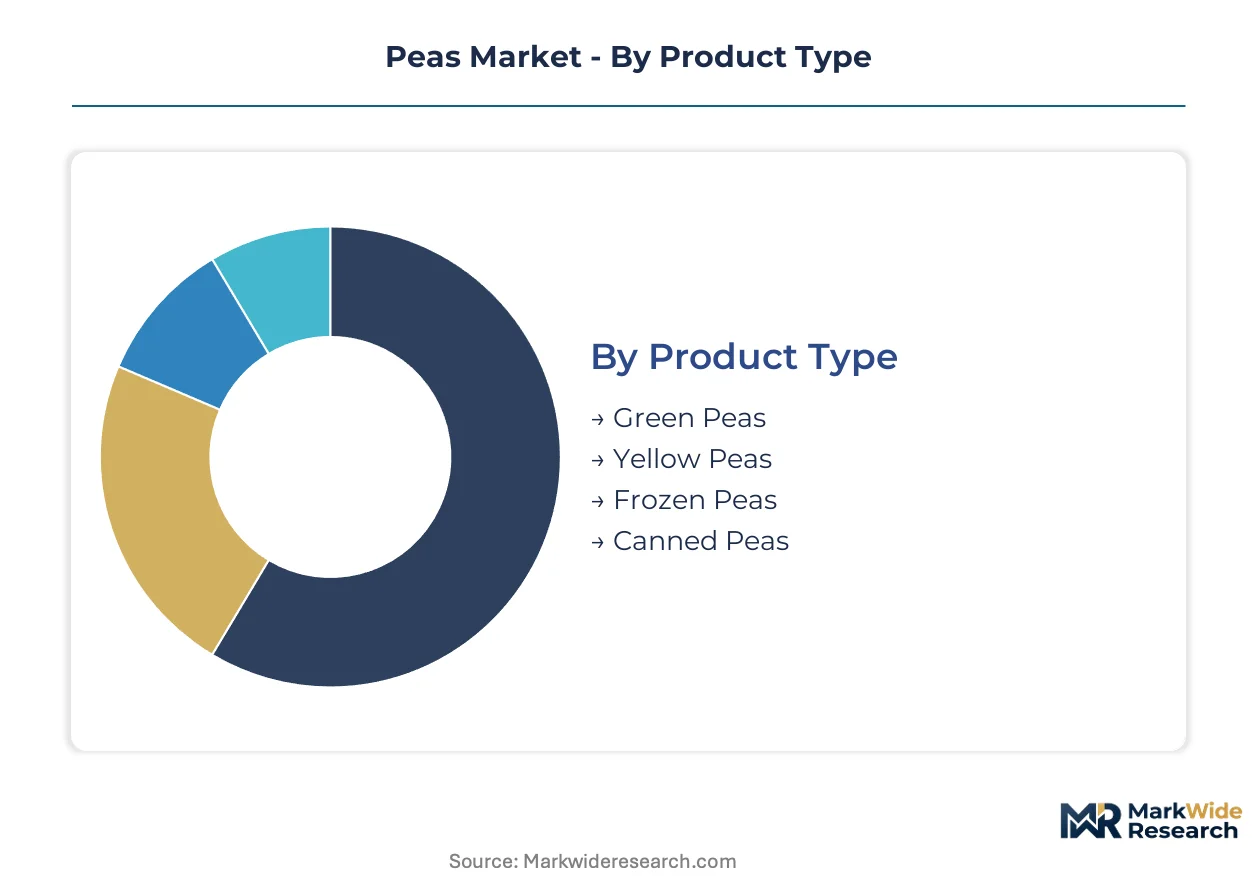
Pea market segmentation reveals divergent margin structures across product forms and channel strategies. Ingredient-grade isolates command premium pricing through long-term CPG contracts, while commodity frozen and canned formats compete on volume efficiency in retail channels.
Product Type:
Yellow peas dominate export-oriented processing corridors, while green peas anchor domestic fresh and frozen consumption. Supply concentration varies sharply by color and preservation method.
- Yellow Peas:Higher protein concentration (20-25% dry weight) and superior processing efficiency for isolate extraction. Demand concentrates in European and North American ingredient manufacturing, where EU Green Deal carbon-accounting requirements favor certified low-carbon extraction facilities.
- Green Peas:Preferred for fresh consumption and premium frozen retail positioning. Domestic consumption in India and European fresh markets drives procurement patterns, with shorter supply chains reducing scope-three disclosure burdens.
- Frozen Peas:Blast-freezing technology preserves cellular structure for retail and foodservice channels. Emsland Group and similar processors leverage European cold-chain infrastructure.
- Canned Peas:Thermal processing extends shelf stability for emergency food programs and institutional procurement. USDA grading standards govern North American export eligibility.
Yellow peas holds the largest share; momentum sits with frozen peas.
End Use:
Cost-tier differentiation separates commodity feed applications from pharmaceutical-grade protein isolates. Margin capture concentrates at the ingredient-supplier level.
- Ingredient Suppliers:Deep margin pools through backward-integrated starch and protein extraction. Roquette Frères and Kerry secure multi-year contracts with CPG brands seeking clean-label alternatives.
- Snack Products:Extruded high-protein crisps and puffed formulations are climbing the fastest, displacing corn and potato bases on retail shelves. Extrusion equipment operators drive isolate demand.
- Food Industry:Meat-analogue and dairy-alternative manufacturers source pea protein for amino-acid complementarity. FSSAI contaminant thresholds reshape import flows into India.
- Animal Feed:Pulse-crop rotation byproducts and lower-grade fractions enter compound feed formulations. Price-sensitive procurement competes with soy meal on cost-per-protein metrics.
Ingredient suppliers capture the deepest margins; snack products are gaining share fastest.
Packaging Type:
Volume scale separates industrial bulk flows from consumer unit economics. Channel-specific packaging requirements dictate processing location and capital intensity.
- Bulk:Rail-silo and containerized shipments serve ingredient processors and feed compounders. Canadian prairie elevators and European port terminals anchor distribution.
- Frozen:Retail-ready IQF formats require continuous cold-chain integrity. Supermarket private-label programs drive specification standardization.
- Bagged:Dried whole peas and split peas for ethnic food retail and home cooking. South Asian diaspora markets in the UK, Canada, and US sustain demand.
- Canned:Ambient-stable formats for institutional procurement and emergency food reserves. USDA Agricultural Marketing Act grading governs North American production.
Bulk holds the largest share; frozen formats are expanding most quickly.
Distribution Channel:
Customer-type fragmentation separates spot commodity brokers from direct processor relationships. Procurement authority is shifting toward sustainability and R&D functions within buyer organizations.
- Wholesalers:Traditional hub-and-spoke aggregation for commodity dried peas and feed-grade materials. Margin compression from disintermediation pressures broker viability.
- E-commerce:Direct-to-manufacturer platforms enable smaller processors to contract with specialty food startups. Kerry and Roquette maintain digital procurement portals for technical buyers.
- Retail:Supermarket and hypermarket chains dominate consumer packaged pea sales. Clean-label positioning requires supply chain transparency documentation.
- Food Services:Institutional catering and restaurant procurement of frozen and canned formats. Cost-per-serving metrics favor standardized specifications.
Wholesalers hold the largest share; e-commerce channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie-origin yellow peas command premium pricing in European ingredient channels, while Indian domestic markets trade at narrower spreads due to localized processing capacity expansion.
United States
Snack-product extrusion demand and meat-analogue formulation requirements drive pea protein isolate procurement. The USDA Agricultural Marketing Act enforces grading standards that govern export eligibility and price premiums for North American growers. Processing infrastructure concentrates in the upper Midwest, where backward-integrated facilities link prairie elevators to CPG contract channels.
Canada
Pulse-crop rotation acreage and prairie agronomic expertise erosion constrain raw material flow consistency for isolate producers. The Canadian Grain Commission maintains quality certification protocols for export-bound yellow peas. Saskatchewan and Manitoba processing corridors anchor the North American supply base for European and Asian ingredient markets.
Germany
Modified pea starch production for industrial food applications and REACH chemical-compliance requirements shape processor capital allocation. The EU F-Gas Regulation mandates spray-drying equipment retrofits with alternative refrigerant systems. Emsland Group facilities in Lower Saxony experience acute retrofit timelines and compliance cost pressure.
India
Domestic retail expansion for plant-based ingredients and re-export channel development accelerate processing capacity buildout. The FSSAI mandates contaminant thresholds and labeling protocols for pea-protein imports destined for domestic retail. Gujarat and Maharashtra industrial corridors host emerging extrusion and isolate facilities serving both local CPG brands and Middle Eastern export markets.
France
Clean-label snack manufacturing demand and carbon-accounting documentation requirements favor certified low-carbon extraction facilities. The EU Green Deal imposes sustainability disclosure obligations on agricultural inputs entering European food channels. Roquette Frères operations in Lestrem anchor backward-integrated pea starch extraction serving multinational CPG contract portfolios.
Peas Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with ingredient-grade isolate specialists commanding premium pricing through R&D-intensive formulation services while commodity processors compete on volume scale and agricultural sourcing efficiency. The vendor base fragments across backward-integrated European starch extractors, North American protein concentrate suppliers, and Asian packaged food exporters. Three archetypes dominate: multinational ingredient conglomerates with flavor-systems capabilities, regional pulse processors with captive agronomy relationships, and contract manufacturers serving private-label retail programs. Competitive moves concentrate on capacity expansion in Indian domestic markets and strategic partnerships linking prairie elevators to extrusion equipment operators.
Among European-based processors, Roquette Frères and Emsland Group exemplify the backward-integrated archetype, anchoring positions through in-house extraction infrastructure and long-term CPG supply contracts. Kerry occupies a distinct tier representing the flavor-systems R&D specialist model, leveraging taste-masking capabilities to secure multi-year agreements with plant-based formulation brands. These three entities collectively illustrate the competitive divergence between starch-derivative scale players and protein-isolate technology providers.
| Leading Market Players |
|---|
| Kerry |
| Emsland Group |
| Roquette Frères |
| The Scoular Company |
| Yantai Shuangta Foods Co, Ltd |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Burcon Nutrascience Corp |
| Glanbia PLC |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at European spray-drying facilities shapes both supply concentration and price floors for pea protein isolates, with EU F-Gas Regulation compliance costs compressing margins for retrofit-dependent processors while certified low-carbon extraction sites capture premium positioning.
Pricing Analysis
The customization-premium spread in pea-derived ingredients separates long-term CPG contract pricing from spot commodity transactions, with ingredient-grade isolates commanding substantial premiums through multi-year volume commitments and documented carbon-accounting transparency. Price differentiation hinges on EU Green Deal certification status and FSSAI contaminant compliance for Indian market access. Pricing pressure stems from soy protein isolate substitution in cost-sensitive meat-analogue formulations, eroding share in mid-tier applications. Animal feed compounders exhibit highest price sensitivity, while clean-label snack manufacturers and pharmaceutical-grade buyers demonstrate lowest elasticity.
Supply Chain Analysis
Prairie elevator aggregation through Saskatchewan and Manitoba anchors North American yellow pea flows, with Canadian Grain Commission certification serving as the chokepoint for export eligibility to European and Asian ingredient markets. Raw material dependencies center on prairie-origin pulse crops, natural gas for spray-drying thermal energy, and hydrofluorocarbon refrigerant alternatives under EU F-Gas phase-down schedules. Tariff exposure on processed starch derivatives into REACH-governed European food contact applications constitutes the dominant structural risk. Distribution runs through backward-integrated processor direct contracts with CPG technical buyers, displacing traditional commodity broker mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peas market functions as a defensive-moat story where regulatory entrenchment in carbon-accounting certification and long-term CPG contract structures create substantial switching costs for incumbent processors.
For Market Incumbents: Shield contract portfolios by accelerating backward integration into prairie elevator networks, securing captive supply as Canadian pulse-crop rotation expertise erodes. Invest in EU Green Deal certification infrastructure to maintain premium positioning against emerging Indian processors. Prioritize flavor-systems R&D partnerships with Kerry-type specialists to mask off-tastes in plant-based formulations, defending against precision-fermentation hybrid substitutes.
For New Entrants and Emerging Players: Technical buyer dissatisfaction with carbon-verification inconsistency across certifying bodies creates white-space opportunity for processors offering unified scope-three disclosure platforms. Target India's underdeveloped organized retail penetration for plant-based ingredients, establishing direct distribution to emerging CPG brands in Gujarat and Maharashtra corridors. Pursue mobile dry-fractionation unit deployment for on-farm protein concentration, capturing decentralized Canadian prairie production outside incumbent hub-and-spoke networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated starch extractors with multi-year CPG contracts and in-house carbon-certification capabilities. Long-term viability favors processors with demonstrated regulatory navigation across EU REACH, F-Gas, and Indian FSSAI regimes simultaneously. Monitor Indian domestic processing capacity buildout as the inflection signal for re-export channel margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Elevators | Captive supply secures raw material flow as Canadian agronomic expertise collapses. |
| EU Green Deal Certification Investment | Low-carbon extraction status unlocks premium pricing with European CPG manufacturers. |
| Mobile Dry-Fractionation Deployment | On-farm protein concentration reduces transport costs for decentralized prairie production. |
| FSSAI Compliance Infrastructure Buildout | Contaminant threshold navigation enables access to Indian domestic retail and re-export channels. |
| Precision Fermentation Partnership | Hybrid formulations with fermentation-derived ingredients achieve unmatched texture properties. |
Methodological Framework
A standing panel of ingredient procurement directors at CPG manufacturers, pea processing plant managers, agricultural extension service leads, and carbon-certification auditors provided ongoing calibration throughout this study. Primary interviews with these stakeholders combined with secondary validation against USDA Agricultural Marketing Act filings, EU ECHA REACH registrations, Indian FSSAI import protocols, and customs trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, end use, and regional demand clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including yellow versus green pea varieties, ingredient supplier versus snack product versus food industry versus animal feed end uses, and bulk versus frozen versus bagged versus canned packaging formats. CAGRs derived from trend extrapolation adjusted for EU F-Gas Regulation retrofit timelines and Indian domestic capacity expansion trajectories. Industry-specific forecast inputs incorporated prairie acreage rotation patterns and extrusion equipment operator isolate demand curves.
Forecasts assume regulatory continuity in EU Green Deal carbon-accounting mandates, REACH chemical-compliance requirements, and FSSAI contaminant threshold enforcement; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated soy protein substitution in meat-analogue applications, breakthroughs in precision fermentation cost reduction, and prairie climate volatility affecting yield consistency. Practitioners should keep alternative scenarios live as Indian processing capacity buildout and carbon-certification standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Fresh Vegetables Market
Vegetables
Dried Peas Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Dried Mushroom Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
United States Microgreens Market
Vegetables
Field Peas Market
Vegetables
South America Peas Market
Vegetables
Carrots and Turnips Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Global Indoor Plant Market
Vegetables
Sprouts Market
Vegetables
North America Microgreens Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
North America Christmas Tree Market
Vegetables
Vegetable Chutney Market