
 North America Christmas Tree Market | 2026-2036
North America Christmas Tree Market Size, Share, and Industry Trends Forecast 2026-2036
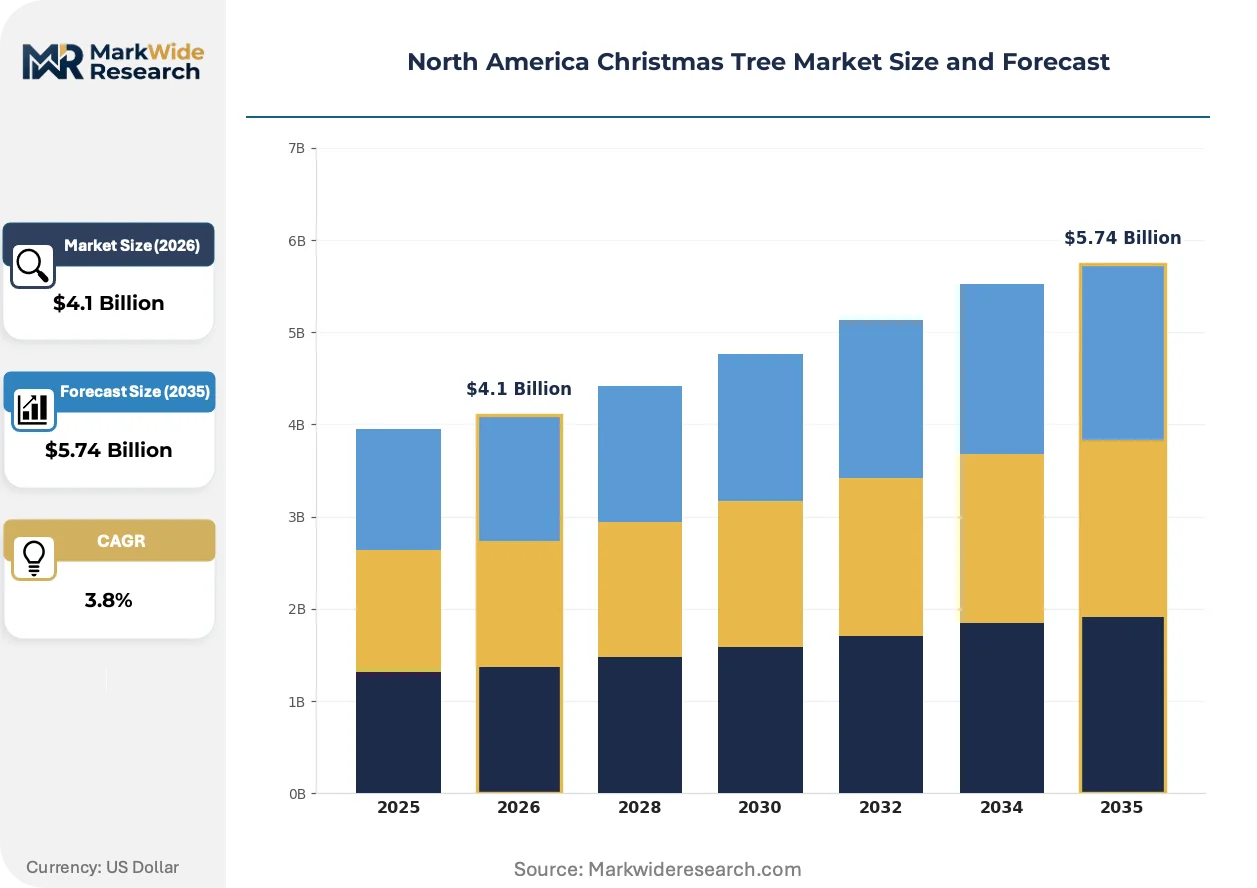
North America Christmas Tree Market Analytics
Precision needle injection molding is reconfiguring how artificial Christmas trees achieve botanical realism at commercial scale. Balsam Hill leverages proprietary PE-PVC blend formulations to replicate Fraser fir needle texture. National Tree Company sustains manufacturing scale across multiple North American distribution nodes. J G Brands anchors its position through direct-to-consumer logistics during compressed seasonal windows.
North America Christmas trees encompass both cultivated evergreen species harvested from managed plantations and engineered polymeric replicas designed for multi-season reuse, with artificial variants typically employing polyethylene tips over steel-hinged frames rated for decade-long service cycles. The tree type segment splits between natural fir and artificial pine, with artificial pine commanding margin pools through premium pricing on hyper-realistic needle architectures. Distribution channel dynamics favor garden centers for natural tree tactile selection, while online retail captures artificial tree volume through augmented reality visualization tools that reduce return rates.
The U.S. Department of Agriculture enforces grading standards for natural Christmas tree height, taper, and needle retention, while the EPA oversees phthalate restrictions in PVC-dominant artificial formulations, and California's Proposition 65 mandates labeling for flame retardant chemical disclosures. These frameworks elevate compliance costs for artificial producers while certifying natural tree quality tiers that influence wholesale auction pricing. Stakeholders must monitor biodegradable needle coatings and carbon footprint labeling as emerging battlegrounds for consumer preference formation.
Market Dynamics
Precision needle injection molding and PE-PVC blend formulations are compressing the realism gap between artificial and natural Christmas trees, forcing Oregon and Washington plantation operators to differentiate through USDA-certified grading tiers rather than needle density alone.
Growth Catalysts
- Commercial space procurement:Hotel and retail chain buyers are expanding artificial tree orders to reduce seasonal labor and disposal costs. These institutional accounts prioritize decade-long service cycles over annual replacement.
- USDA grading standardization:Tightened federal benchmarks for height, taper, and needle retention are creating transparent quality tiers that command premium auction pricing at Pacific Northwest wholesale markets.
- Augmented reality visualization:Online retailers deploying AR tools for artificial tree selection are compressing return rates and capturing volume from garden center foot traffic.
Market Restraints
- Phthalate compliance costs:EPA restrictions on PVC-dominant artificial formulations and California Proposition 65 flame retardant labeling mandates are elevating manufacturing overhead for polymeric replica producers.
- Input cost volatility:Steel prices for hinged frames and petroleum-derived polyethylene feedstocks create margin pressure on artificial tree assemblers without captive resin supply.
- Natural tree supply concentration:Oregon and Washington farms control the majority of North American fir production, exposing wholesale buyers to weather-driven yield variance and regional logistics bottlenecks.
Strategic Opportunities
- Biodegradable needle coatings:Emerging bio-based surface treatments for artificial trees address landfill disposal concerns and align with municipal composting program expansion in Canadian provinces.
- Carbon footprint labeling:Retailers implementing lifecycle emissions disclosure for natural versus artificial trees are capturing preference formation among environmentally motivated households.
- Direct-to-consumer logistics:Compressed seasonal windows favor operators with dedicated last-mile networks capable of delivering pre-lit artificial trees to residential addresses within 48-hour fulfillment cycles.
Industry Challenges
- Seasonal workforce compression:Natural tree harvest operations in the Pacific Northwest face acute labor scarcity during the six-week peak cutting window, forcing wage premiums and automated baling system investments.
- SKU proliferation complexity:Artificial tree manufacturers managing hyper-realistic needle architectures across multiple height tiers and lighting configurations confront inventory carrying cost escalation and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Christmas Tree Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tree Type: Natural Fir, Artificial Pine, Spruce, Cedar End User: Residential Homes, Commercial Spaces, Schools, Non-Profit Organizations Distribution Channel: Online Retail, Garden Centers, Supermarkets, Local Farms Seasonal Demand: Pre-Christmas, Post-Christmas, Holiday Events, Decoration Sales |
| Companies Covered | J G Brands, Mr. Jingle's Christmas Trees, Big John's Trees, Tree Towne Christmas Trees, Z & Z Christmas Trees, Santa's Trees, Grobe's Nursery and Garden Centre, Balsam Hill, National Tree Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Christmas Tree Market Evolving Landscape
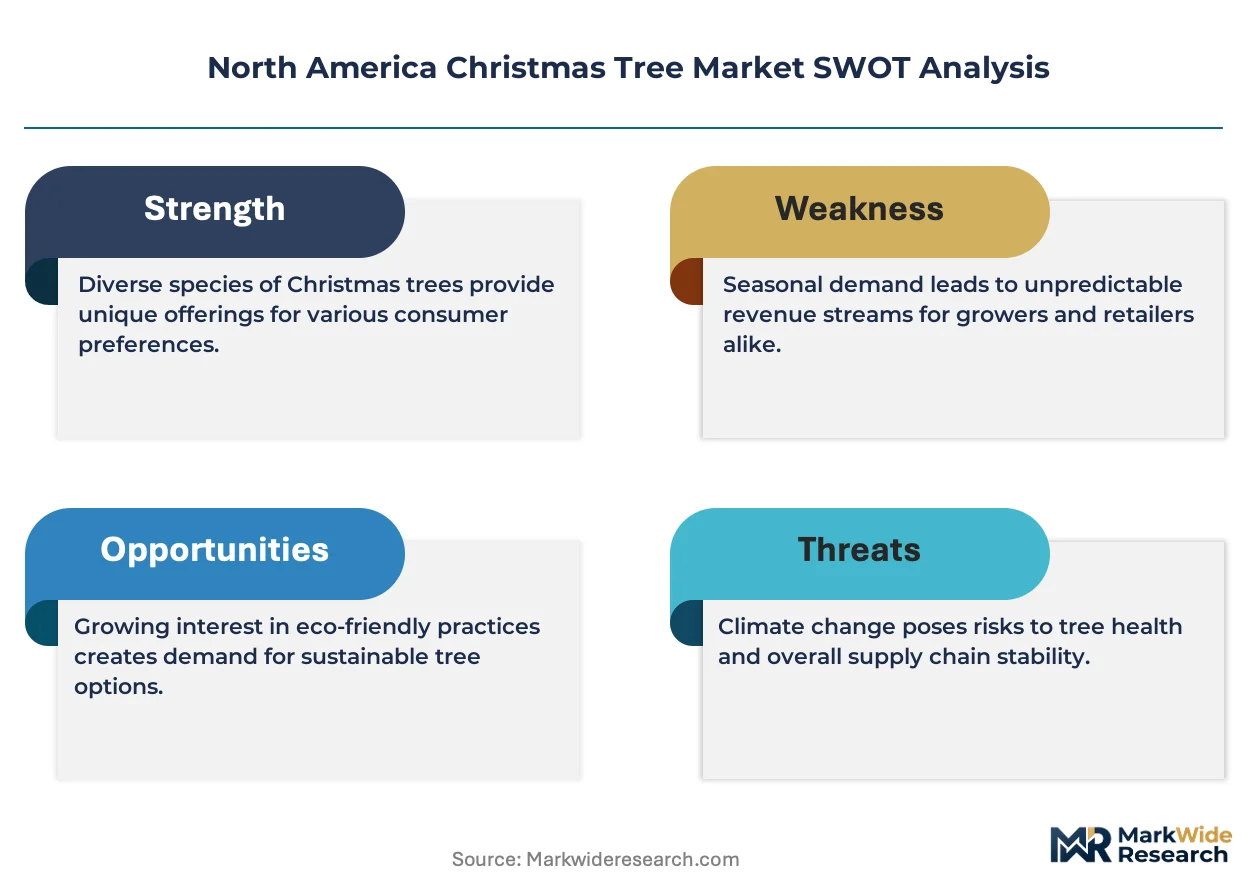
Botanical replication technologies and regulatory disclosure mandates are simultaneously elevating product fidelity expectations and compliance burdens across natural and artificial Christmas tree supply chains.
Polyethylene needle tip formulations paired with steel-hinged frame architectures are virtualizing the tactile and visual experience of Fraser fir specimens. Hotel procurement departments and residential buyers seeking decade-long reuse cycles are adopting these hyper-realistic variants at accelerating rates. This technological convergence is compressing the addressable market for entry-grade PVC-dominant artificial trees and forcing mid-tier assemblers toward PE-PVC blend investments.
California's Proposition 65 mandates explicit flame retardant chemical disclosure on artificial tree packaging, while the EPA maintains phthalate restrictions in PVC formulations. These overlapping frameworks are fragmenting manufacturing compliance requirements and elevating labeling costs for producers serving multi-state distribution. Artificial tree assemblers with California exposure are responding by reformulating resin blends and relocating finishing operations to jurisdictions with aligned chemical safety standards.
Retail garden centers are ceding artificial tree volume to online channels deploying augmented reality visualization tools that reduce tactile selection dependency. Major e-commerce platforms now render lighting effects and branch density in residential room contexts, displacing the traditional showroom experience. This channel rotation is most pronounced in suburban U.S. markets where last-mile delivery density supports compressed fulfillment windows during November procurement peaks.
North America Christmas Tree Market Segmentation
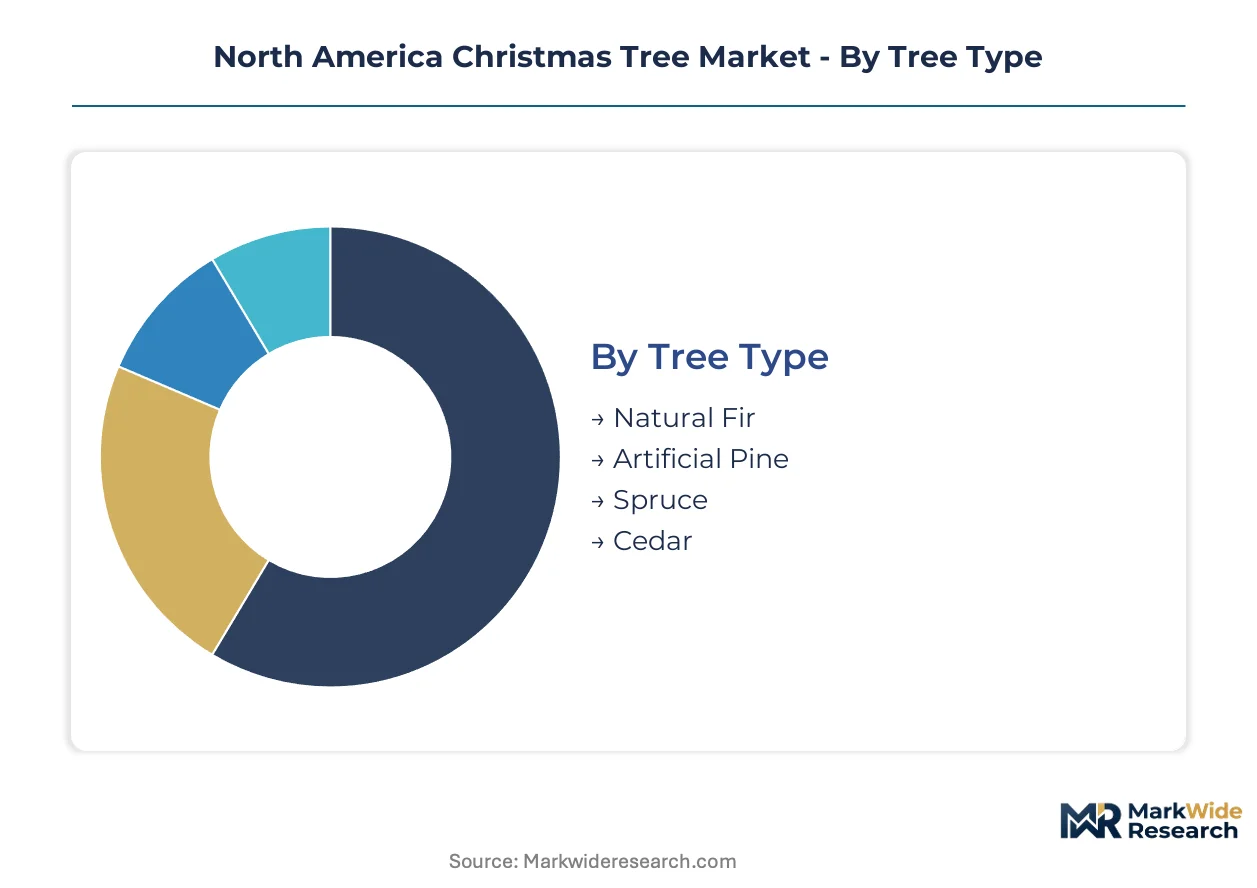
Segmentation in the North America Christmas Tree Market reveals divergent procurement cycles and margin architectures across tree categories and buyer types. Cycle time differentials between single-season natural harvests and decade-long artificial service intervals reshape inventory strategies and working capital requirements for producers and retailers throughout the region.
Tree Type:
Replacement frequency spans from annual harvest cycles for natural specimens to ten-year depreciation schedules for premium artificial architectures, compressing margin capture timing and customer lifetime value calculations across producer portfolios.
- Natural Fir:Managed plantations in Oregon and Washington supply Fraser and Noble fir specimens graded under USDA height, taper, and needle retention standards. Pacific Northwest wholesale auctions command premium pricing for top-tier specimens while lower grades flow to mass-market retail channels.
- Artificial Pine:PE-PVC blend formulations replicate botanical needle density through precision injection molding, with steel-hinged frames rated for compressed storage cycles. Hotel and retail chain procurement departments prioritize these variants to eliminate seasonal labor and disposal logistics.
- Spruce:Colorado blue and white spruce variants serve regional preferences in Rocky Mountain and Midwest markets where plantation proximity reduces freight costs.
- Cedar:Eastern red cedar harvests concentrate in Oklahoma and Texas, supplying aromatic alternatives with shorter needle retention profiles.
Natural Fir anchors the volume base while Artificial Pine gains share at the steepest rate.
End User:
Buyer sophistication and procurement scale fragment across household, institutional, and civic segments, with contract terms and specification requirements dictating margin capture potential for suppliers serving each tier.
- Residential Homes:Individual households drive tactile selection behavior at garden centers for natural specimens, while suburban markets with dense last-mile networks increasingly convert to online artificial tree procurement with augmented reality visualization.
- Commercial Spaces:Hotel lobbies, retail chains, and corporate campuses specify pre-lit artificial architectures with uniform lighting density and rapid assembly requirements, prioritizing decade-long service cycles over botanical authenticity.
- Schools:Educational institutions balance budget constraints against fire safety compliance, often selecting mid-tier artificial variants with documented flame retardant certifications.
- Non-Profit Organizations:Civic and religious groups concentrate procurement in compressed seasonal windows, favoring volume discounts and donation-supported natural tree programs.
Commercial Spaces concentrate procurement scale while Residential Homes fragment across the widest specification range.
Distribution Channel:
Channel economics split between high-touch tactile selection and algorithmic recommendation engines, with fulfillment velocity and return rate differentials reshaping working capital intensity for operators in each pathway.
- Online Retail:E-commerce platforms deploy augmented reality tools that render lighting effects and branch density in residential room contexts, compressing return rates below garden center benchmarks and capturing suburban volume during November procurement peaks.
- Garden Centers:Independent and chain nursery operations sustain natural tree dominance through tactile needle assessment and immediate transport convenience, though foot traffic cedes share to digital channels.
- Supermarkets:Mass-market retail chains stock compact artificial specimens and limited natural tree lots as seasonal traffic drivers, with parking lot distribution handling volume surges.
- Local Farms:U-cut and pre-cut operations in Oregon, Washington, North Carolina, and Michigan capture premium pricing through experience-based differentiation and varietal specialization.
Online Retail climbs the fastest while Local Farms defend margin through geographic specialization.
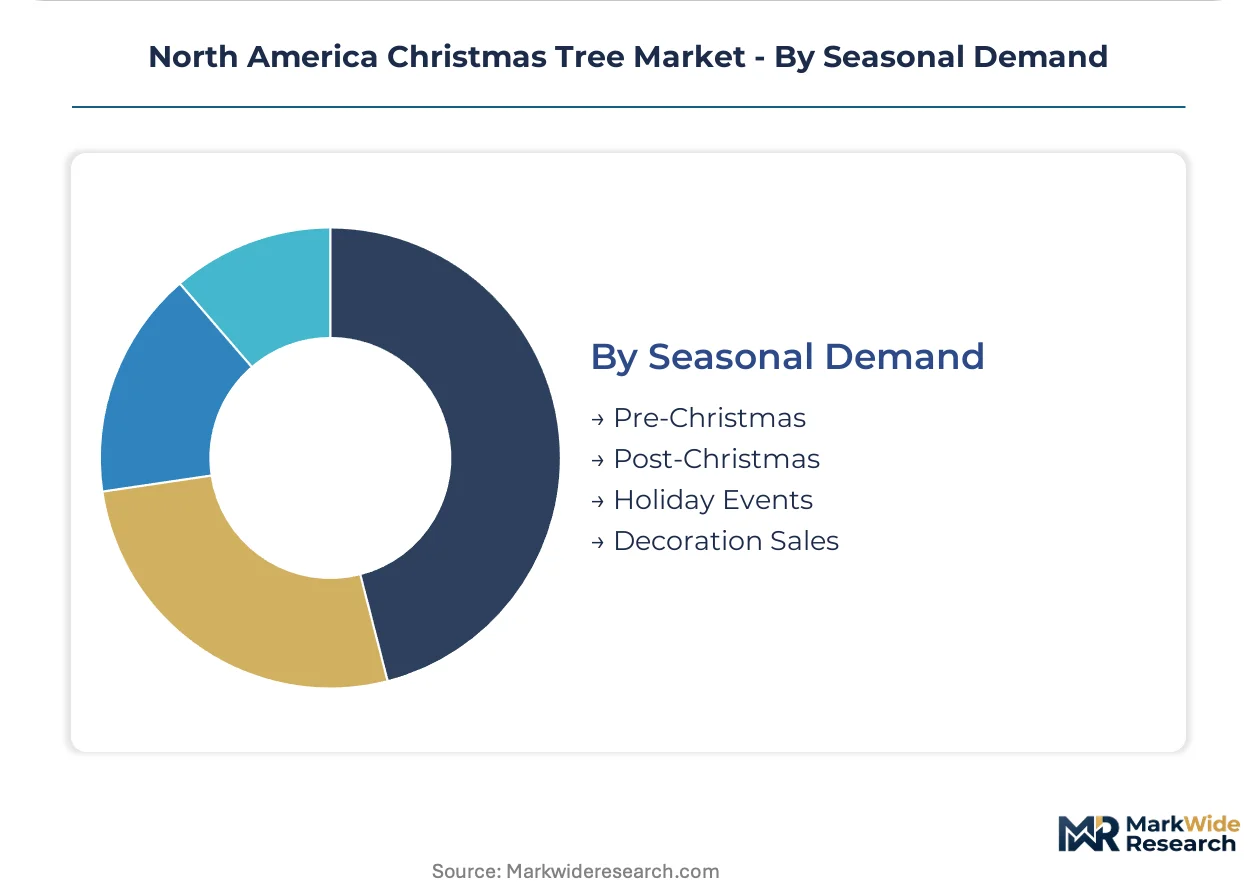
Seasonal Demand:
Demand compression into six-week procurement windows creates inventory risk concentration and labor scarcity premiums, with post-holiday clearance dynamics and event-based secondary cycles extending revenue capture timelines.
- Pre-Christmas:November through mid-December concentrates the majority of natural tree harvest and artificial tree fulfillment, with Pacific Northwest baling operations running at capacity and logistics networks optimizing for 48-hour residential delivery.
- Post-Christmas:Clearance pricing on artificial specimens and municipal composting program coordination for natural tree disposal generate incremental revenue and customer retention touchpoints.
- Holiday Events:Corporate parties, civic lightings, and religious observances outside the core December window sustain limited demand for compact artificial specimens and rental programs.
- Decoration Sales:Ornament, lighting, and accessory procurement extends seasonal engagement for retailers with established artificial tree customer bases.
Pre-Christmas dominates revenue concentration while Decoration Sales extend customer lifetime value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian natural fir exports flow primarily to U.S. wholesale markets in the Pacific Northwest and Northeast corridors, with cross-border logistics networks optimizing for compressed November delivery windows.
United States
Pacific Northwest plantations in Oregon and Washington supply the majority of domestic Fraser and Noble fir production, with USDA grading standards tightening quality benchmarks for height, taper, and needle retention. The EPA enforces phthalate restrictions in PVC-dominant artificial formulations, while California's Proposition 65 mandates flame retardant chemical disclosures. Oregon's Willamette Valley anchors the densest concentration of managed Christmas tree plantations, where baling operations run at capacity during six-week harvest peaks.
Canada
British Columbia and Nova Scotia plantations export premium balsam fir specimens to U.S. Northeast and Midwest markets, leveraging favorable exchange rates and established cross-border cold-chain logistics. Health Canada oversees pesticide residue limits on exported natural trees, aligning with USDA import inspection protocols. British Columbia's Fraser Valley hosts specialized operations targeting the Seattle and Portland metropolitan wholesale corridors.
Mexico
Domestic demand concentrates in Mexico City, Monterrey, and Guadalajara metropolitan areas, with artificial tree imports from China and U.S. border states capturing middle-class household growth. Mexico's national consumer protection agency enforces product safety labeling on imported artificial specimens. Nuevo León's Monterrey metro area serves as the primary distribution hub for northern Mexican retail chains and hospitality procurement.
North America Christmas Tree Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin architectures, with scale-driven assemblers optimizing for decade-long service cycles and boutique operators defending margin through varietal specialization. The vendor base fragments across plantation-based natural growers, PE-PVC blend artificial manufacturers, and direct-to-consumer logistics platforms. Two strategic archetypes dominate: vertically integrated plantation-to-retail operators and asset-light digital-native distributors. Competitive moves center on backward integration into captive resin supply and augmented reality tooling for online channel conversion.
Among U.S.-based operators, Balsam Hill and National Tree Company exemplify the premium artificial tier, while J G Brands anchors direct-to-consumer logistics specialization. These three occupy positions across the realism-versus-convenience spectrum, with proprietary formulation investments separating scale players from commodity assemblers.
| Leading Market Players |
|---|
| J G Brands |
| Mr. Jingle's Christmas Trees |
| Big John's Trees |
| Tree Towne Christmas Trees |
| Z & Z Christmas Trees |
| Santa's Trees |
| Grobe's Nursery and Garden Centre |
| Balsam Hill |
| National Tree Company |
| Others |
Value Network & Pricing Analysis
Oregon and Washington plantation concentration anchors wholesale auction dynamics, translating Pacific Northwest weather volatility into tiered premium capture for USDA-certified specimens while compressing margins for ungraded natural tree operators and entry-grade artificial assemblers.
Pricing Analysis
PE-PVC blend formulations command substantial premiums over legacy PVC-dominant architectures, while next-generation biodegradable needle coatings promise further price stratification. Three-tier pricing structure across premium, standard, and economy levels separates hyper-realistic artificial specimens with decade-long warranties from mid-tier commercial variants and mass-market disposable grades. Price differentiation rests on USDA certification tier for natural specimens and needle density fidelity for artificial variants. Cost compression in entry-grade artificial tiers is intensifying because of steel frame and petroleum-derived polyethylene feedstock volatility. Residential households exhibit highest price sensitivity during November procurement peaks, while hotel procurement departments prioritize total cost of ownership over upfront unit pricing.
Supply Chain Analysis
Contract manufacturing for artificial tree assembly concentrates among specialized PE injection molders in Guangdong province and steel frame fabricators in Zhejiang, with finishing operations increasingly relocating to Mexico to align with California Proposition 65 compliance requirements. Geographic supply concentration spans China for precision molding equipment and resin formulations, Mexico for North American distribution proximity, and the Pacific Northwest for natural fir harvest. Raw material dependencies include petroleum-derived polyethylene pellets, cold-rolled steel for hinged frames, and copper wiring for pre-lit configurations. Single-source vulnerability in Pacific Northwest natural tree supply exposes wholesale buyers to climate-driven yield variance. Distribution runs through garden center networks for natural specimens and dedicated last-mile carriers for artificial tree residential fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision needle injection molding and augmented reality visualization tools are disrupting traditional procurement patterns, creating asymmetric opportunity windows for operators with captive resin supply and digital-native distribution architectures.
For Market Incumbents: Entrench market position through backward integration into captive polyethylene resin supply and certification investment in USDA grading infrastructure for Pacific Northwest plantation operations. Defend against direct-to-consumer logistics platforms by securing exclusive garden center distribution agreements in suburban corridors with dense last-mile delivery economics. Prioritize R&D in biodegradable needle coatings to preempt regulatory pressure on landfill disposal.
For New Entrants and Emerging Players: Mid-market commercial spaces in secondary U.S. metropolitan areas represent the most penetrable entry point for artificial tree operators lacking brand recognition. Secondary Canadian markets with expanding municipal composting programs offer white-space demand for bio-based surface treatment variants. Go-to-market execution should emphasize 48-hour fulfillment guarantees and AR visualization tools to bypass garden center incumbency.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated plantation-to-retail operators with USDA certification infrastructure and established Pacific Northwest land leases. Long-term viability hinges on climate adaptation capabilities and regulatory compliance positioning across phthalate restrictions and flame retardant disclosure mandates. Monitor biodegradable coating adoption rates and carbon footprint labeling penetration as inflection indicators for preference formation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene sourcing insulates margins from petroleum feedstock volatility affecting PE-PVC blend formulations. |
| Biodegradable Needle Coating Development | Bio-based surface treatments align with Canadian municipal composting expansion and California landfill diversion targets. |
| Augmented Reality Visualization Deployment | AR tools compress return rates below garden center benchmarks and capture suburban residential volume during November peaks. |
| USDA Certification Infrastructure Investment | Grading tier transparency commands premium auction pricing at Pacific Northwest wholesale markets. |
| Direct-to-Consumer Logistics Network Buildout | 48-hour fulfillment capability captures artificial tree demand from garden center foot traffic in dense suburban corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing plantation operations managers in Oregon and Washington, procurement directors at hotel and retail chain headquarters, artificial tree manufacturing executives, garden center category buyers, and last-mile logistics coordinators. Secondary validation drew from USDA agricultural statistics, EPA chemical safety filings, California Proposition 65 enforcement databases, customs trade records for polyethylene resin imports, and SEC disclosures from publicly traded retail operators. Bottom-up volume modeling triangulated against top-down expenditure analysis across residential, commercial, institutional, and civic end-use segments.
Calibration approach anchored volume projections to historical harvest yields, plantation acreage under management, and artificial tree replacement cycle surveys. Segmentation dimensions modeled encompassed tree type, end-user category, distribution channel, and seasonal demand window. CAGRs were derived through regression analysis of replacement frequency trends, commercial procurement contract tenors, and channel shift velocity metrics. Industry-specific forecast inputs included Pacific Northwest climate pattern indices and polyethylene resin price series.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices, steel commodity pricing, and cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and plantation labor availability. Quarterly review of USDA grading standard enforcement intensity, biodegradable coating patent filings, and AR visualization adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Pea Market
Vegetables
Acorn Squash Market
Vegetables
Tomato Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Roselle Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Microgreens Market
Vegetables
Sweet Potatoes Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Dry Onion Market
Vegetables
IQF Vegetables Market
Vegetables
Yarrow Market
Vegetables
Garden Cress Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Yam Products Market