
 Africa Peas Market | 2026-2036
Africa Peas Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Peas Market Outlook
Microfinance and warehouse-receipt financing is fragmenting the Africa Peas Market by enabling smallholder cooperatives to bypass traditional trading intermediaries. Kenya Peas Farmers Association leverages collective bargaining to secure better input terms and storage infrastructure. South African Grain Producers Organisation anchors quality certification protocols that shape regional export readiness. Mali Office du Niger dominates irrigated production corridors along the Niger River basin.
Peas comprise edible seeds of Pisum sativum, a cool-season legume containing approximately 20-25% protein and substantial dietary fiber, cultivated for direct human consumption and as a foundational ingredient in processed food systems. Green peas retain dominant volume share across African retail channels due to shorter cooking times and established household familiarity. Yellow peas are gaining traction among food manufacturers targeting split-pea flour and textured protein applications. Frozen peas within the application dimension command premium shelf-space allocations as cold-chain infrastructure deepens in peri-urban markets.
Tanzania Agricultural Produce Export Authority and the Egyptian Agricultural Export Council operate under national phytosanitary frameworks that determine cross-border market access for pea consignments. The Algerian National Office for Food Security enforces strategic reserve policies that directly influence seasonal procurement volumes and price stabilization mechanisms. Stakeholders must monitor evolving national seed registration requirements and regional harmonization protocols under the African Continental Free Trade Area to anticipate tariff and non-tariff barrier adjustments.
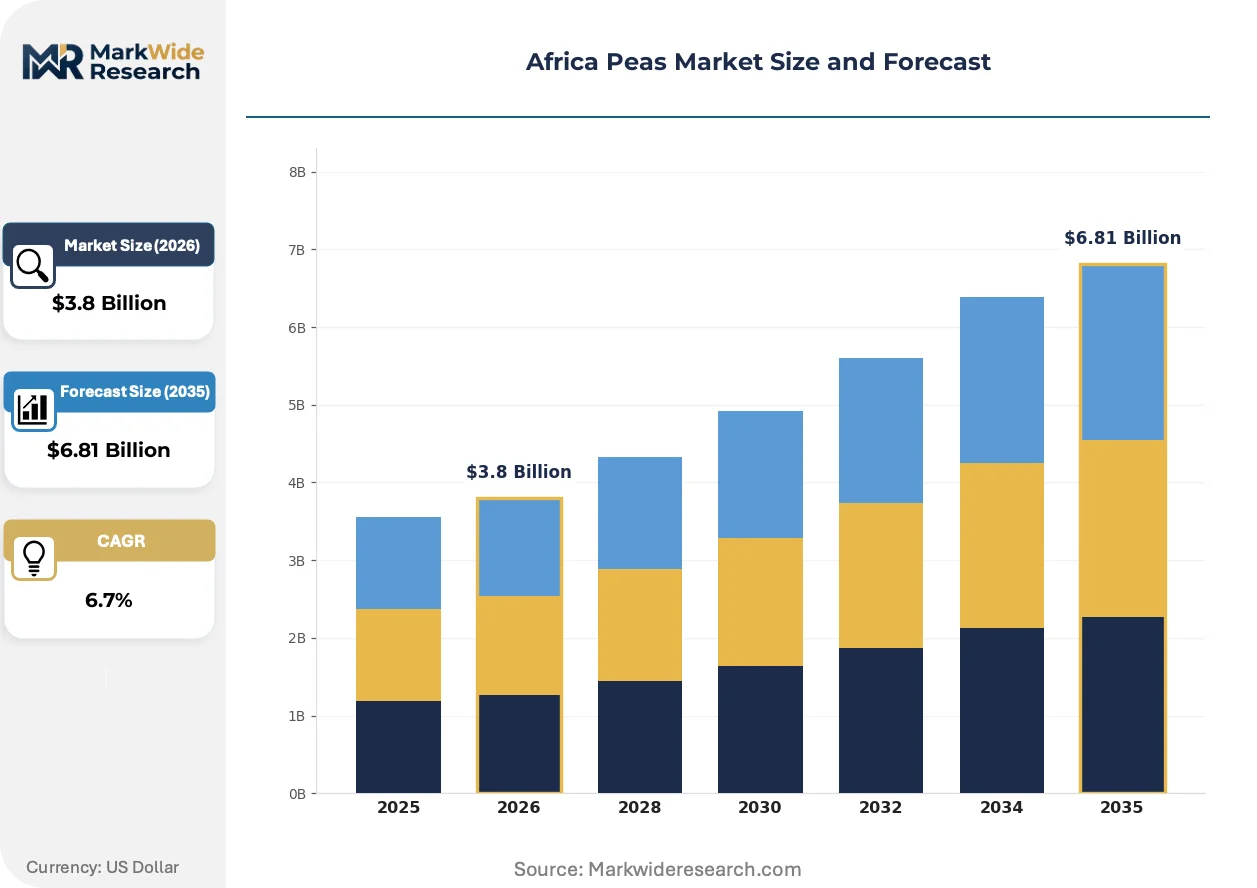
Market Dynamics
Microfinance-enabled warehouse-receipt financing is fragmenting traditional trading intermediaries across African pea supply chains, allowing smallholder cooperatives to capture margin previously lost to layered broker networks. This structural disintermediation is compressing price discovery timelines and reshaping quality certification requirements.
Growth Catalysts
- East African food manufacturing expansion:Plant-based protein formulation demand from Ethiopian and Tanzanian processors is pulling yellow pea volumes into industrial ingredient channels.
- African Continental Free Trade Area protocols:Harmonized seed registration and phytosanitary standards are reducing cross-border friction for pea consignments between member states.
- Urban cold-chain investment:Peri-urban retail infrastructure in Nigeria and Kenya is enabling frozen pea shelf-space expansion previously constrained by temperature control gaps.
Market Restraints
- Input cost volatility:Fertilizer and irrigation equipment price swings concentrate risk among Niger River basin producers dependent on diesel-powered pumping systems.
- Supply concentration in irrigated corridors:Mali Office du Niger-controlled production zones create single-point vulnerability for regional volume stability during climatic stress periods.
- Phytosanitary regulatory friction:Divergent national seed registration requirements between Tanzania Agricultural Produce Export Authority and Egyptian Agricultural Export Council frameworks delay market access for new varieties.
Strategic Opportunities
- Underpenetrated West African retail:Ghana and Senegal urban markets lack established frozen pea distribution, creating first-mover positioning for cold-chain investors.
- Split-pea flour applications:Yellow pea processing into gluten-free bakery inputs addresses emerging dietary preference shifts in North African food service channels.
- National strategic reserve policies:Algerian National Office for Food Security procurement mandates generate predictable offtake volumes for certified producers meeting quality thresholds.
Industry Challenges
- Certification timeline compression:South African Grain Producers Organisation quality protocols require multi-season field trials that delay export readiness for new cooperative entrants.
- Post-harvest handling skill gaps:Smallholder cooperatives in Ethiopia and Tanzania lack trained personnel for moisture management and aflatoxin prevention in warehouse-receipt storage systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Peas Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Peas, Yellow Peas, Processed Peas, Fresh Peas End User: Food Manufacturers, Retail Chains, Exporters, Households Distribution Channel: Online Retail, Supermarkets, Wholesale Markets, Food Service Application: Culinary, Snack Foods, Frozen Foods, Soups |
| Companies Covered | South African Grain Producers Organisation, Kenya Peas Farmers Association, Algerian National Office for Food Security, Egyptian Agricultural Export Council, Moroccan Office Chérifien des Phosphates, Tunisian Company for Export of Agricultural Products, Tanzania Agricultural Produce Export Authority, Mali Office du Niger, Libyan General Authority for Agricultural Development, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Peas Market Strategic Shifts
Processing technology and regulatory harmonization are converging to reshape pea value chains across African markets. Three distinct vectors are compressing traditional arbitrage windows and reconfiguring competitive positioning.
Mechanical sorting and optical grading systems are replacing manual labor in Egyptian and South African pea processing facilities. Mid-scale cooperatives in Kenya and Tanzania are adopting these systems at accelerating rates to meet export certification standards. This capital-intensive automation is rendering obsolete the historical advantage of low-labor-cost manual sorting operations.
Regional harmonization under the African Continental Free Trade Area is eliminating redundant phytosanitary inspections at internal borders. The protocol requires mutual recognition of national seed registration approvals, reducing consignment delays. East African Community member states are responding fastest, with Tanzania and Kenya aligning inspection protocols ahead of West African implementation timelines.
Direct procurement contracts between food manufacturers and smallholder cooperatives are bypassing traditional aggregator networks. Ethiopian and Nigerian processors now source yellow peas through structured agreements with registered farmer groups. This channel disintermediation is most visible in Addis Ababa and Lagos peri-urban zones where manufacturer procurement offices maintain permanent field presence.
Africa Peas Market Segmentation
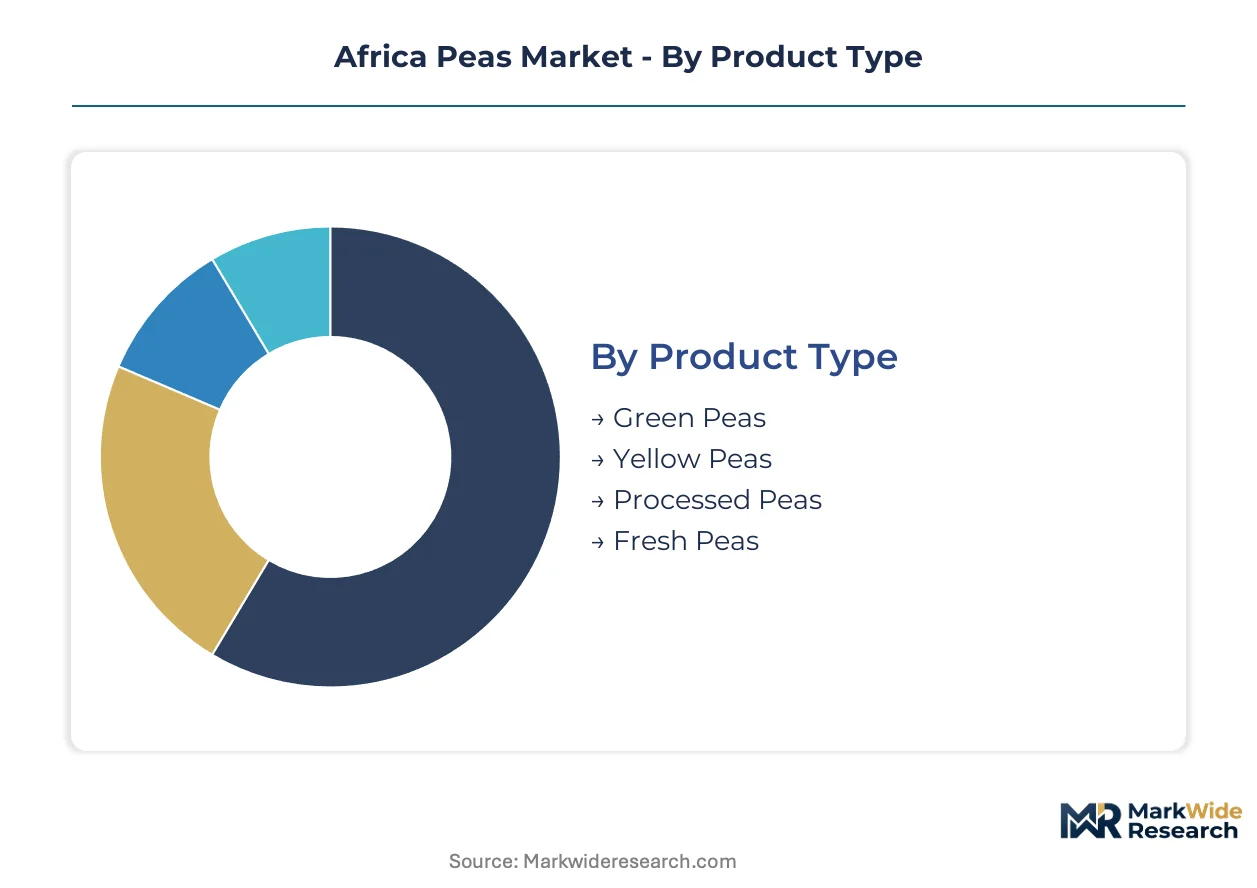
Pea segmentation across African markets reflects divergent shelf-life requirements and infrastructure dependencies. Product type determines procurement cadence while distribution channel selection hinges on cold-chain maturity in specific urban corridors.
Product Type:
Fresh peas rotate through supply chains within days while processed variants sustain months-long inventory cycles, compressing margin structures for perishable handlers.
- Green Peas:These immature seeds retain higher moisture content and shorter storage windows, driving rapid turnover in Lagos and Nairobi wet markets. Ethiopian households favor green peas for reduced cooking time, though spoilage rates exceed processed alternatives.
- Yellow Peas:Mature seeds with lower moisture thresholds suit extended storage and industrial milling. Tanzanian food manufacturers source yellow peas for split-pea flour production, with demand accelerating as gluten-free bakery formulations penetrate Addis Ababa food service channels.
- Processed Peas:Canned and dried variants bypass cold-chain dependencies, enabling distribution into Sahelian markets lacking refrigeration infrastructure.
- Fresh Peas:Pod-intact produce commands premium positioning in peri-urban supermarket formats, constrained by harvest-to-shelf timelines under 72 hours.
Green peas anchors the volume base while yellow peas gains share at the steepest rate.
End User:
Procurement scale separates bulk industrial buyers from fragmented household purchasing, with exporters occupying a intermediate tier demanding certification compliance.
- Food Manufacturers:Ethiopian and Nigerian processors contract directly with farmer cooperatives for standardized yellow pea volumes. These buyers enforce moisture specifications and aflatoxin thresholds that reshape upstream handling protocols.
- Retail Chains:South African supermarket groups and Kenyan formal retailers drive packaged pea SKU expansion, though cold-chain gaps limit frozen product penetration outside major urban nodes.
- Exporters:Egyptian Agricultural Export Council-registered entities concentrate on European and Gulf destination markets, requiring phytosanitary alignment with destination country regulators.
- Households:Traditional open-market purchasing dominates across West Africa, with price sensitivity favoring loose bulk over branded packaging.
Households anchors the volume base while food manufacturers gains share at the steepest rate.
Distribution Channel:
Channel selection tracks refrigeration availability, with temperature-controlled formats commanding margin premiums unavailable to ambient infrastructure.
- Online Retail:Jumia and local platforms pilot pea delivery in Lagos and Nairobi, constrained by last-mile cold-chain gaps for frozen SKUs.
- Supermarkets:Shoprite and Carrefour formats in South Africa and Kenya allocate expanding shelf space to frozen peas as refrigeration penetration deepens.
- Wholesale Markets:Open-air aggregation points in Kano and Dar es Salaam handle the majority of regional pea volume, with price discovery occurring through layered broker networks.
- Food Service:Hotels and restaurants in Cairo and Casablanca source frozen peas through specialized distributors, with procurement specifications tightening around uniformity and defect rates.
Wholesale markets anchors the volume base while supermarkets gains share at the steepest rate.
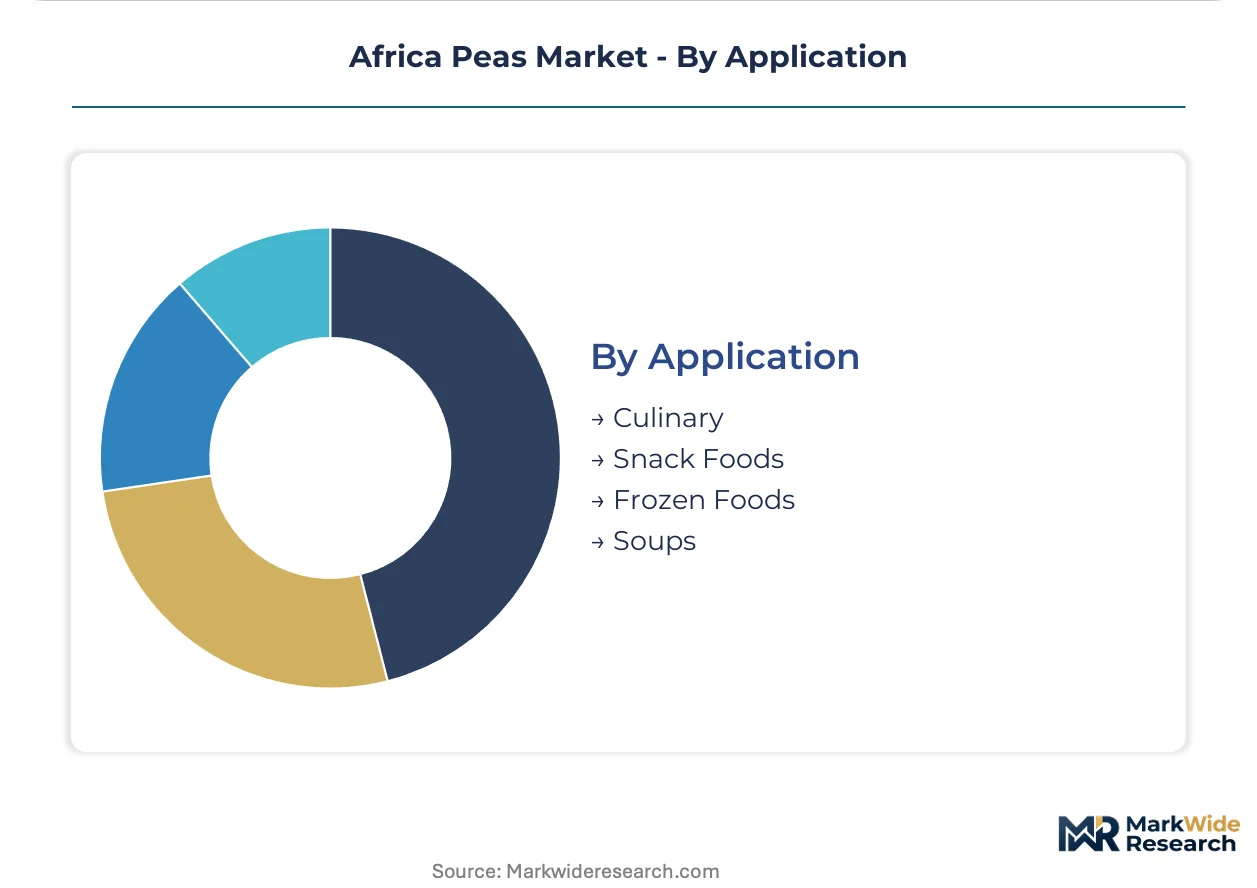
Application:
Processing intensity determines value capture, with minimal-intervention culinary use yielding lower per-kilogram returns than formulated snack and frozen applications.
- Culinary:Whole peas for direct cooking dominate household consumption patterns across East and West Africa, with preparation methods varying by regional preference.
- Snack Foods:Roasted and flavored pea products emerge in South African and Nigerian urban markets, targeting convenience-oriented consumption occasions.
- Frozen Foods:IQF peas command premium positioning in formal retail, with Egyptian and South African processing facilities supplying regional supermarket chains.
- Soups:Split-pea soup bases concentrate demand in North African food manufacturing, with Algerian processors sourcing specific pea grades for consistency in dehydrated formulations.
Culinary anchors the volume base while frozen foods gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers anchor pea procurement across East and West Africa, while government food security programs reshape import substitution and reserve stockpiling patterns in North Africa.
Ethiopia
Urban food processors in Addis Ababa pull yellow pea volumes for plant-based protein formulations. The Ethiopian Agricultural Transformation Agency enforces seed registration protocols that delay new variety commercialization. The Rift Valley corridor concentrates smallholder production where cooperatives deploy warehouse-receipt financing to bypass traditional brokers.
Nigeria
Lagos-based manufacturers contract directly with farmer groups for standardized pea grades. The National Agency for Food and Drug Administration and Control regulates aflatoxin thresholds in processed pea imports. Northern Kaduna and Kano states host open-air wholesale markets where layered broker networks still dominate price discovery.
Tanzania
Dar es Salaam peri-urban retailers expand frozen pea shelf-space as cold-chain infrastructure deepens. The Tanzania Agricultural Produce Export Authority operates phytosanitary frameworks governing cross-border consignments. The Arusha-Moshi corridor supplies fresh pea volumes to Kenyan export channels under East African Community harmonized standards.
Egypt
Cairo food service channels tighten procurement specifications around frozen pea uniformity and defect rates. The Egyptian Agricultural Export Council registers entities for European and Gulf destination markets. Nile Delta processing facilities deploy mechanical sorting systems to replace manual labor and meet certification requirements.
Algeria
National strategic reserve policies generate predictable offtake volumes for certified producers meeting quality thresholds. The Algerian National Office for Food Security enforces procurement mandates that directly influence seasonal price stabilization. Saharan fringe irrigation zones concentrate production where diesel-powered pumping systems expose growers to input cost volatility.
Africa Peas Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement networks. State-affiliated agricultural authorities anchor quality certification and export registration functions, while cooperative associations leverage collective bargaining for input terms and storage infrastructure. Three archetypes dominate: government food security agencies controlling reserve procurement, farmer cooperative federations disintermediating traditional brokers, and export-council-registered entities managing cross-border phytosanitary compliance. Competitive moves concentrate on backward integration into farmer group contracting and cold-chain infrastructure expansion into underpenetrated urban corridors.
Among state-affiliated authorities, the Algerian National Office for Food Security and the Tanzanian Agricultural Produce Export Authority exemplify the regulatory-anchor archetype, while the Kenya Peas Farmers Association represents cooperative federation models. The South African Grain Producers Organisation occupies a position bridging quality protocol development with export readiness certification.
| Leading Market Players |
|---|
| South African Grain Producers Organisation |
| Kenya Peas Farmers Association |
| Algerian National Office for Food Security |
| Egyptian Agricultural Export Council |
| Moroccan Office Chérifien des Phosphates |
| Tunisian Company for Export of Agricultural Products |
| Tanzania Agricultural Produce Export Authority |
| Mali Office du Niger |
| Libyan General Authority for Agricultural Development |
| Others |
Value Chain & Pricing Dynamics
The Niger River basin irrigated corridors around the Office du Niger anchor regional volume stability, with diesel-powered pumping costs feeding directly into farm-gate price floors that cascade through layered broker networks to Lagos and Nairobi wholesale markets.
Pricing Analysis
Certification level creates the primary spread between export-grade and domestic-market peas, with South African Grain Producers Organisation protocols commanding premiums over uncertified Ethiopian cooperative output. Contract-based long-term offtake dominates industrial procurement, while spot trading persists in open-air wholesale channels. Price differentiation rests on moisture specifications and aflatoxin thresholds enforced by Nigerian food manufacturers. Cost compression in the standard tier is intensifying because fertilizer price volatility concentrates risk among smallholders. Household purchasers in West African open markets exhibit highest price sensitivity; export-registered Egyptian entities show least.
Supply Chain Analysis
Extended payment terms through warehouse-receipt financing facilities are displacing traditional broker advances across East African cooperatives. Supply concentrates in Mali, Ethiopia, and Tanzania, with the Niger River basin and Rift Valley corridor anchoring irrigated production. Raw material dependencies include diesel fuel for pumping systems, certified seed stock, and fertilizer blends. Single-source vulnerability concentrates in Office du Niger-controlled irrigation zones during climatic stress periods. Distribution runs through layered broker networks in Kano and Dar es Salaam wholesale markets, with direct procurement contracts bypassing intermediaries in Addis Ababa and Lagos peri-urban zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained personnel for moisture management and aflatoxin prevention represent the critical capability gap constraining cooperative export readiness, with post-harvest handling skill shortages limiting quality certification attainment across Ethiopian and Tanzanian smallholder networks.
For Market Incumbents: Harden quality certification pipelines through multi-season field trial investment with South African Grain Producers Organisation protocols, defending against emerging cooperative entrants leveraging warehouse-receipt financing to capture margin. Anchor cold-chain infrastructure in underpenetrated West African urban corridors to preempt first-mover positioning by regional competitors. Certification investment remains the priority lever for export market retention. For New Entrants and Emerging Players: Build out frozen pea distribution networks in Ghana and Senegal urban markets where refrigeration penetration gaps exclude incumbent supermarket formats. Direct procurement contracting with food manufacturers offers the most penetrable go-to-market angle, bypassing traditional broker layers through structured farmer group agreements in Lagos and Addis Ababa peri-urban zones. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among export-council-registered entities with phytosanitary compliance infrastructure, positioning these archetypes for sustained offtake visibility across the analysis window. Acquisition targets should demonstrate established cold-chain partnerships or cooperative federation relationships. Watch Algerian National Office for Food Security procurement mandate adjustments as inflection indicators for regional price stabilization mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Group Contracting | Ethiopian and Nigerian processors bypass broker networks through direct cooperative agreements. |
| Cold-Chain Infrastructure Expansion | Peri-urban retail in Ghana and Senegal enables frozen pea shelf-space previously constrained by temperature gaps. |
| Quality Certification Investment | South African Grain Producers Organisation protocols unlock European and Gulf destination market access. |
| Split-Pea Flour Processing Capacity | Tanzanian manufacturers address gluten-free bakery demand in North African food service channels. |
| Strategic Reserve Procurement Alignment | Algerian National Office for Food Security mandates generate predictable offtake for certified producers. |
Study Parameters
The analysis maps green pea, yellow pea, processed pea, and fresh pea segments, each validated through cooperative managers, food manufacturer procurement officers, export council registrars, and cold-chain logistics providers. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, national agricultural ministry statistics, African Continental Free Trade Area harmonization protocols, and phytosanitary inspection records. Bottom-up volume triangulation against top-down macroeconomic anchors ensured cross-verification.
Assumptions held fixed include current African Continental Free Trade Area implementation timelines and existing national seed registration requirements, while climatic variability and input cost trajectories were modeled across sensitivity bands. Segmentation dimensions encompassed product type, end user, distribution channel, and application, with regional regulatory clusters as an additional agricultural-specific dimension. CAGRs derived from trend extrapolation adjusted for infrastructure investment cycles and urbanization patterns. Forecast inputs included cold-chain penetration rates and food manufacturer capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by microfinance-enabled cooperatives or state-affiliated reserve procurement agencies would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Okra Seed Market
Seeds
Bangladesh Seed Market
Seeds
Southeast Asia Seed Market
Seeds
India Forage Seed Market
Seeds
United States Vegetable Seed Market
Seeds
Celery Seed Oil Market
Seeds
North America Vegetable Seed Market
Seeds
Sesame Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Poppy Seed Market
Seeds
South America Seed Market
Seeds
Faba Beans Market
Seeds
United States Seed Market