
 Carrots and Turnips Market | 2026-2036
Carrots and Turnips Market Size, Share, and Industry Trends Forecast 2026-2036
Carrots and Turnips Market Outlook
Polymer-based packaging film is consolidating around biodegradable cellulose alternatives across European fresh produce supply chains. Grimmway Farms leverages its integrated California-Arizona growing network to sustain year-round conventional carrot volumes. Bejo Zaden B.V. anchors global seed genetics for hybrid turnip varieties with disease resistance traits. Bolthouse Farms, Inc. dominates North American juice-grade carrot procurement through long-term contract farming arrangements.
Carrots and turnips constitute taproot vegetables harvested for their enlarged storage roots, with carrots containing beta-carotene levels typically exceeding 8,000 micrograms per 100 grams and turnips delivering glucosinolate compounds valued in fermented food applications. The primary commercial purpose spans fresh consumption, industrial processing into purees and juices, and culinary ingredient supply for foodservice operators. Conventional carrots still occupy the largest volume share across wholesale channels, though organic carrots are recording the fastest expansion in direct-to-consumer and online grocery segments where premium positioning supports margin retention. Food Processing represents the most concentrated end-use value pool, particularly for baby food manufacturers and dehydrated ingredient suppliers demanding uniform root specifications.
EU Farm to Fork Strategy targets under the European Commission are tightening maximum residue limits for soil-applied pesticides, directly shaping cultivation protocols across Netherlands and Belgian contract farms. FDA grading standards for root vegetables in the United States enforce diameter and defect tolerances that determine export eligibility for Central American suppliers. USDA organic certification requirements and EU Organic Regulation 2018/848 create dual-compliance burdens for multinational shippers serving both Atlantic markets. Stakeholders must monitor evolving soil carbon measurement methodologies, as these will soon determine preferential sourcing status across major retail procurement frameworks.
Market Dynamics
EU Farm to Fork Strategy pesticide reduction mandates are compressing conventional cultivation margins while accelerating organic certification timelines across Netherlands and Belgian contract farms. This regulatory pressure is restructuring supplier economics and procurement criteria simultaneously.
Growth Catalysts
- EU Green Deal soil health targets:Carbon sequestration incentives are redirecting subsidy flows toward regenerative root vegetable cultivation in Poland's processing corridor.
- Baby food manufacturers:Uniform root specifications demanded by dehydrated ingredient suppliers are consolidating procurement around vertically integrated growers with controlled-environment capabilities.
- Biodegradable cellulose films:Polymer-based packaging substitution is automating compliance with single-use plastic directives across German and French retail chains.
Market Restraints
- Input cost volatility:Nitrogen fertilizer price swings tied to natural gas markets destabilize margin planning for open-field carrot operations in Spain's Murcia belt.
- Supply concentration risk:California-Arizona growing networks dominate year-round conventional volume, creating geographic single-point vulnerability for North American juice-grade procurement.
- Dual-certification burden:USDA organic requirements and EU Organic Regulation 2018/848 impose overlapping audit costs that disqualify smaller Central American exporters from Atlantic market access.
Strategic Opportunities
- Fermented food applications:Glucosinolate compound valorization in turnip varieties is opening functional ingredient channels for Korean and Japanese gut-health product lines.
- Direct-to-consumer platforms:Online grocery segments are capturing premium positioning for organic carrots through subscription box models bypassing wholesale margin compression.
- Soil carbon measurement methodologies:Emerging MRV protocols will determine preferential sourcing status for retail procurement frameworks targeting 2030 Scope 3 reductions.
Industry Challenges
- Integrated pest management expertise:Scarcity of agronomists trained in biocontrol transition protocols slows Farm to Fork compliance across Belgian and Dutch contract operations.
- Legacy cold chain assets:Refrigeration infrastructure designed for synthetic film packaging requires retrofitting to maintain shelf-life performance with breathable cellulose alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrots and Turnips Market |
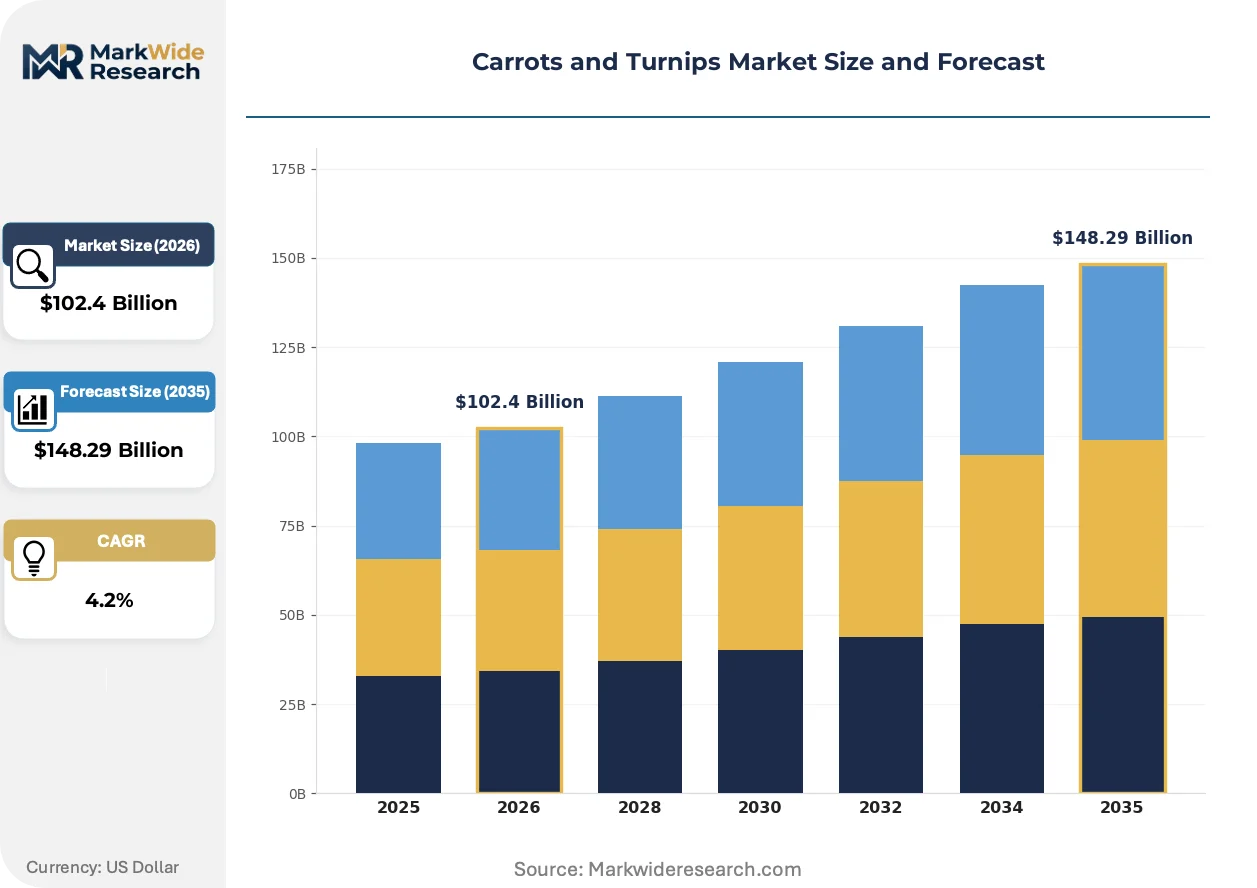
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $148.29 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Carrots, Conventional Carrots, Organic Turnips, Conventional Turnips Distribution Channel: Retail, Wholesale, Direct-to-Consumer, Online Grocery End Use: Food Processing, Fresh Produce, Juice Production, Culinary Uses Packaging Type: Bags, Boxes, Bulk Containers, Retail Packs |
| Companies Covered | Del Monte Pacific Limited, Suttind Seeds, Grimmway Farms, VegPro International, Bejo Zaden B.V., Bolthouse Farms, Inc., Groupe Vegco, AgroFresh, Dole Food Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrots and Turnips Market Strategic Shifts
Automation of root grading and defect detection is compressing labor dependency while reshaping quality consistency benchmarks across processing corridors. These shifts are converging with packaging material transitions and procurement centralization.
Computer vision systems paired with robotic handling arms are automating diameter sorting and surface defect identification at throughput rates exceeding manual inspection capacity. Baby food manufacturers and dehydrated ingredient suppliers are adopting these systems fastest, demanding ISO-grade uniformity that eliminates human variability. This technology is automating the displacement of visual inspection labor while tightening root specification tolerances that determine contract eligibility.
REACH chemical authorization procedures are restricting soil-applied pesticide active ingredients previously standard in conventional carrot cultivation. EFSA residue limit revisions are forcing Dutch and Belgian growers to accelerate biocontrol substitution timelines ahead of 2030 reduction targets. Processing-grade suppliers serving pureed infant food channels face the strictest compliance windows, with Murcia-based operations investing in integrated pest management infrastructure earlier than open-field competitors.
Retail procurement consolidation around sustainability-linked supplier scorecards is rotating volume toward growers with verified soil carbon credentials. German and French fresh produce chains are unbundling traditional wholesale relationships to source directly from certified organic operations with blockchain-tracked field histories. Poland's processing corridor exhibits the fastest scorecard adoption, with cooperatives investing in digital farm management platforms to capture preferential contract terms from multinational baby food manufacturers.
Carrots and Turnips Market Segmentation
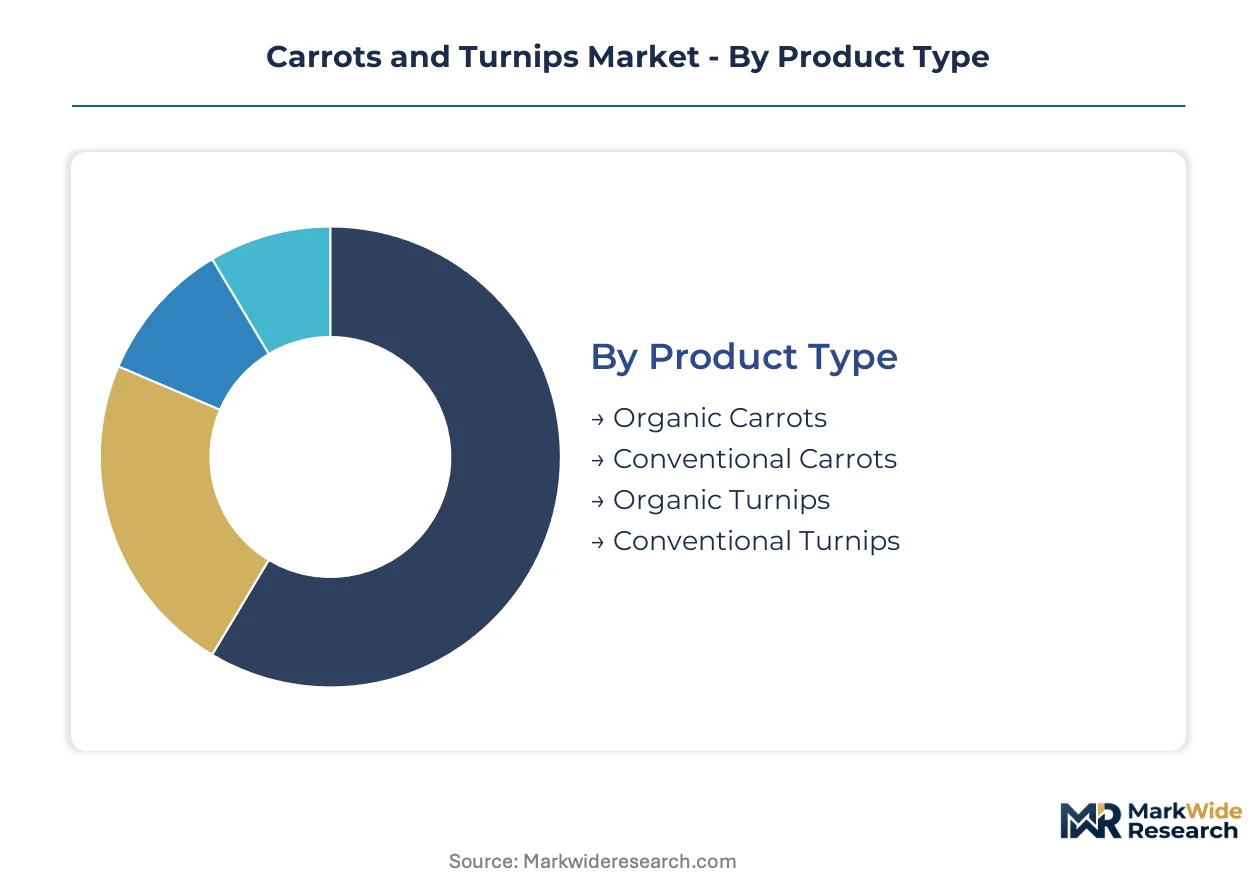
Root vegetable procurement splits across certification tiers, channel strategies, and end-use specifications that reshape margin structures. Buyers prioritize traceability credentials in food processing channels while fresh produce segments trade on shelf-life performance and visual uniformity.
Product Type:
Certification grade determines price realization and contract eligibility across EU and North American procurement frameworks.
- Conventional Carrots:Open-field cultivation with synthetic input protocols dominates volume throughput in Spain's Murcia belt and Poland's processing corridor. California-Arizona growing networks sustain year-round supply for North American juice-grade contracts where diameter uniformity commands premium pricing.
- Organic Carrots:EU Farm to Fork pesticide reduction mandates accelerate farm conversions across Netherlands and Belgian contract operations. Direct-to-consumer subscription models capture margin retention through bypassing wholesale compression, with German and French retail chains expanding dedicated shelf space.
- Conventional Turnips:Standard cultivation protocols serve fermented food processing channels in Korean and Japanese markets where glucosinolate content drives ingredient valuation.
- Organic Turnips:Biocontrol-dependent production faces steeper compliance costs under overlapping USDA and EU Organic Regulation audit requirements, limiting supplier participation in Atlantic market access.
Volume sits with conventional cultivation; growth tilts toward certified organic tiers.
Distribution Channel:
Channel selection reflects buyer scale, frequency requirements, and traceability verification needs.
- Retail:German and French fresh produce chains unbundle traditional wholesale relationships to source directly from certified operations with blockchain-tracked field histories. Shelf-space expansion for root vegetables concentrates procurement around biodegradable cellulose packaging compliance.
- Wholesale:Centralized procurement through Poland's processing corridor serves multinational baby food manufacturers demanding ISO-grade uniformity specifications.
- Direct-to-Consumer:Subscription box models bypass wholesale margin compression for organic carrot positioning.
- Online Grocery:Digital platforms capture premium positioning through convenience-driven repeat purchase patterns.
Procurement centralizes through retail consolidation; fastest channel expansion occurs in direct-to-consumer platforms.
End Use:
Application requirements dictate root specification tolerances and supplier qualification criteria.
- Food Processing:Baby food manufacturers and dehydrated ingredient suppliers enforce the strictest diameter and defect tolerances. Computer vision grading systems automate compliance at throughput rates exceeding manual inspection capacity.
- Fresh Produce:Visual uniformity and shelf-life performance determine contract eligibility for German and French retail chain procurement.
- Juice Production:North American procurement concentrates around California-Arizona supply networks with long-term contract farming arrangements.
- Culinary Uses:Foodservice operators trade on consistent supply availability rather than premium specification tiers.
Value concentrates in food processing; fresh produce captures volume throughput.
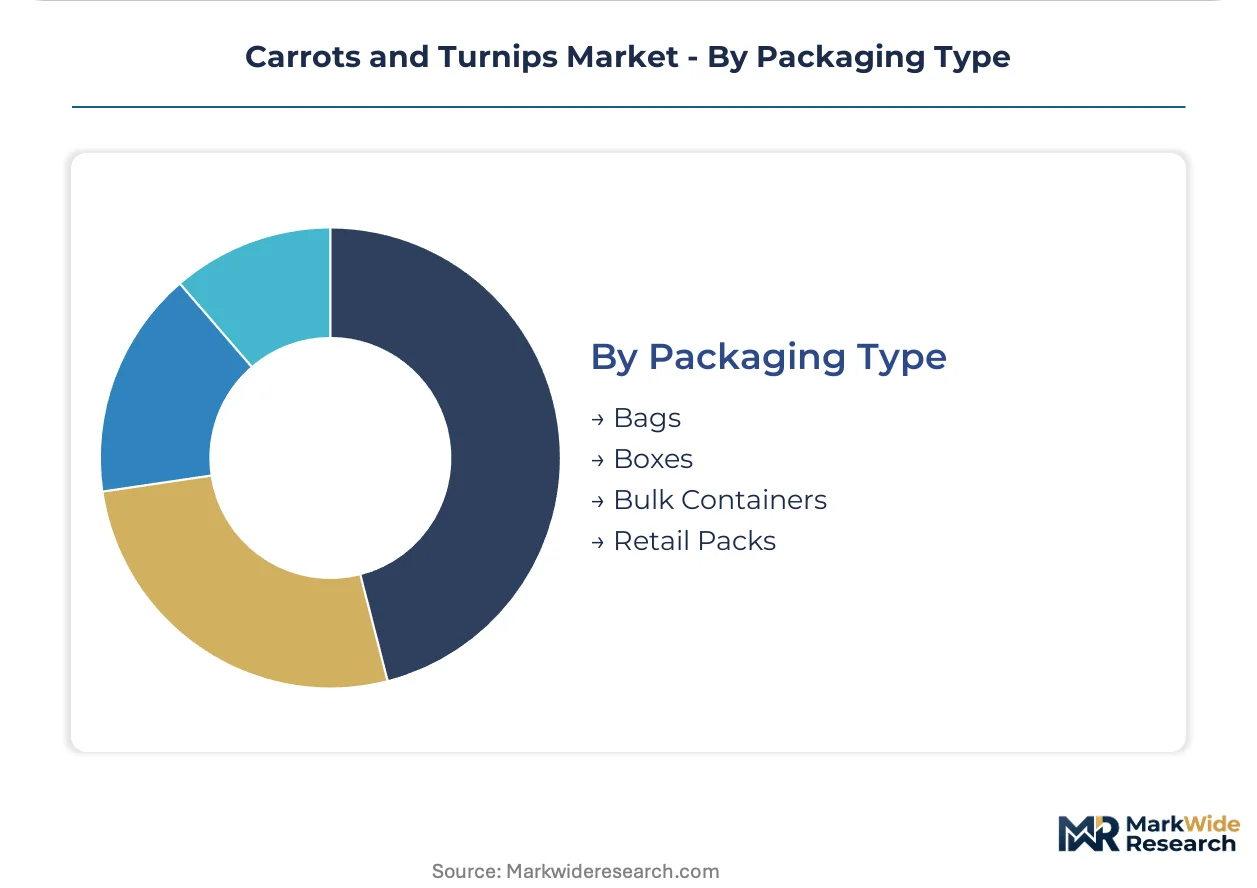
Packaging Type:
Material transitions reshape cold chain infrastructure requirements across supply networks.
- Bulk Containers:Open-field harvest consolidation in Spain's Murcia belt and Poland's processing corridor minimizes handling costs for processing-grade volumes.
- Retail Packs:Biodegradable cellulose film substitution automates compliance with EU single-use plastic directives across German and French chains.
- Bags:Lightweight formats serve high-frequency retail replenishment cycles.
- Boxes:Structural protection for longer-haul distribution to processing facilities.
Processing volume ships through bulk formats; retail-facing growth demands breathable cellulose retrofit investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processing demand concentrates procurement power across specific national corridors where baby food manufacturers and dehydrated ingredient suppliers enforce strict root specifications. Retail consolidation in Western Europe and contract farming networks in North America reshape competitive access. Climate-advantaged growing belts in Southern Europe and controlled-environment operations in the US Southwest anchor year-round supply security.
United States
Juice-grade carrot procurement drives volume concentration through California-Arizona growing networks with long-term contract arrangements. FDA grading standards enforce diameter and defect tolerances that determine export eligibility for Central American suppliers. The Imperial Valley and Yuma growing clusters sustain year-round conventional production through integrated irrigation and harvest coordination.
Germany
Fresh produce retail chains expand dedicated shelf space for organic root vegetables through direct sourcing from certified operations. EU Farm to Fork Strategy pesticide reduction mandates accelerate biocontrol substitution timelines across contract farms. Berlin and Hamburg distribution hubs consolidate procurement around biodegradable cellulose packaging compliance with single-use plastic directives.
Poland
Processing-grade demand from multinational baby food manufacturers concentrates procurement through the country's central processing corridor. EU Green Deal soil health targets redirect subsidy flows toward regenerative cultivation practices. The Łódź and Greater Warsaw regions exhibit fastest adoption of digital farm management platforms for sustainability-linked supplier scorecards.
Spain
Open-field carrot cultivation dominates volume throughput in the Murcia growing belt where nitrogen fertilizer cost volatility destabilizes margin planning. EFSA residue limit revisions force integrated pest management infrastructure investment ahead of 2030 reduction targets. Murcia-based operations lead biocontrol adoption compared to open-field competitors serving pureed infant food channels.
Netherlands
Contract farming operations face compressed conventional cultivation margins under tightening maximum residue limits for soil-applied pesticides. REACH chemical authorization procedures restrict active ingredients previously standard in carrot cultivation. The Flevoland polder region concentrates glasshouse and open-field operations with accelerated organic certification timelines.
Carrots and Turnips Market Competitive Environment
Capacity expansion dominates the current landscape as growers retrofit cold chain infrastructure for breathable cellulose packaging and install computer vision grading systems. The vendor base organizes around three strategic archetypes: vertically integrated growing networks controlling year-round supply, seed genetics specialists anchoring disease resistance trait development, and regional cooperatives aggregating volume for processing-grade contracts. M&A activity concentrates among baby food manufacturers securing captive supply, while strategic partnerships proliferate between retail chains and certified organic operations with blockchain-tracked field histories.
Among integrated growing networks, Grimmway Farms and Bolthouse Farms, Inc. exemplify the scale-driven archetype through their sustained year-round conventional volume positions. Bejo Zaden B.V. occupies a specialist position within the seed genetics tier, anchoring global hybrid variety development. These three entities represent distinct competitive vectors: geographic supply security, downstream juice-grade procurement concentration, and upstream trait control for disease resistance.
| Leading Market Players |
|---|
| Del Monte Pacific Limited |
| Suttind Seeds |
| Grimmway Farms |
| VegPro International |
| Bejo Zaden B.V. |
| Bolthouse Farms, Inc. |
| Groupe Vegco |
| AgroFresh |
| Dole Food Company |
| Others |
Value Chain & Pricing Dynamics
Organic-to-conventional certification gaps bifurcate price realization across EU and North Atlantic procurement corridors, with premium tiers commanding margin retention through direct-to-consumer channels while commodity volumes face wholesale compression. This divergence feeds back into supply chain configuration as growers redirect acreage toward certified operations eligible for sustainability-linked supplier scorecards, abandoning conventional contract structures that cannot absorb dual-certification audit costs.
Pricing Analysis
Volume throughput concentrates in conventional open-field cultivation across Spain's Murcia belt and Poland's processing corridor, where per-unit margins remain thin and sensitive to nitrogen fertilizer cost swings. Three-tier pricing structure across premium organic, standard conventional, and economy processing-grade levels separates baby food manufacturers demanding ISO-grade uniformity from foodservice operators trading on availability. Cost compression in conventional tiers is intensifying because EU Farm to Fork pesticide reduction mandates accelerate biocontrol substitution timelines ahead of compliance windows. Baby food manufacturers exhibit least price sensitivity given specification rigidity, while culinary foodservice channels absorb highest elasticity.
Supply Chain Analysis
EU Organic Regulation 2018/848 and USDA organic certification requirements gate Atlantic market access, disqualifying smaller Central American exporters unable to absorb overlapping audit burdens. Geographic supply concentration centers on California-Arizona growing networks for North American juice-grade procurement, Spain's Murcia belt for European fresh produce, and Poland's processing corridor for multinational baby food contracts. Raw material dependencies draw from nitrogen fertilizer inputs tethered to natural gas markets, biodegradable cellulose film substrates, and hybrid seed genetics. Single-source vulnerability runs through California-Arizona year-round volume dominance. Distribution runs through retail chain consolidation unbundling traditional wholesale relationships for direct certified sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Farm to Fork Strategy pesticide reduction mandates have erected a cost-of-compliance moat that rewards early biocontrol adopters while structurally excluding undercapitalized conventional operators from premium procurement channels.
For Market Incumbents: Anticipate margin compression in open-field conventional segments by accelerating organic certification timelines across Netherlands and Belgian contract operations before 2030 reduction targets tighten further. Prioritize retrofitting legacy cold chain assets for breathable cellulose packaging compatibility to maintain shelf-life performance and retail contract eligibility. Biocontrol expertise scarcity among trained agronomists represents the critical bottleneck threatening compliance velocity. For New Entrants and Emerging Players: Fermented food ingredient buyers in Korean and Japanese gut-health product lines represent an underserved buyer archetype with functional valuation of glucosinolate compounds in turnip varieties that incumbent processors have neglected. Direct-to-consumer subscription box models for organic carrots bypass wholesale margin compression entirely, capturing premium positioning through convenience-driven repeat purchase patterns. White-space entry should anchor on biocontrol-dependent cultivation with blockchain-tracked field histories qualifying for sustainability-linked retail procurement scorecards. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated growing networks controlling year-round supply security given climate volatility threatening geographic single-point vulnerability. Long-term viability favors operators with verified soil carbon credentials as emerging MRV protocols determine preferential sourcing status for Scope 3 reduction targets. The signal to watch is adoption velocity of digital farm management platforms among Poland's processing corridor cooperatives, indicating capture of multinational baby food manufacturer contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acceleration | EU Farm to Fork compliance timelines reward early biocontrol adopters with premium contract eligibility. |
| Cold Chain Retrofit Investment | Breathable cellulose packaging compatibility secures shelf-life performance for German and French retail chains. |
| Computer Vision Grading Deployment | Automated defect detection satisfies ISO-grade uniformity demands from baby food manufacturers at throughput scale. |
| Soil Carbon Measurement Integration | Verified carbon credentials unlock preferential sourcing status under emerging retail procurement frameworks. |
| Direct-to-Consumer Platform Launch | Subscription box models bypass wholesale compression for organic carrot margin retention. |
Study Parameters
Multi-period observation of acreage conversion rates, certification timeline compressions, and retail procurement scorecard adoption anchored the trend analysis, supplemented by interviews with agronomists, baby food manufacturer procurement leads, fresh produce category buyers, and cold chain logistics operators. Secondary validation drew from EU Farm to Fork Strategy implementation reports, EFSA residue limit revision databases, USDA organic certification records, and trade flow customs data across the analysis window. Bottom-up field-level cultivation data triangulated against top-down retail channel volume estimates.
Input-output matrix modeling connected nitrogen fertilizer cost indices, biocontrol input pricing, and packaging material substitution rates to volume and value outputs across the projection horizon. Segmentation dimensions included certification grade, distribution channel, end-use specification tier, and regional growing cluster. CAGRs were derived from curve-fitting historical conversion patterns against regulatory deadline acceleration. Industry-specific forecast inputs incorporated EU Green Deal soil health subsidy redirections and REACH chemical authorization restriction schedules.
Revisions become necessary when EFSA residue limit revisions accelerate ahead of modeled timelines, when nitrogen fertilizer price volatility exceeds historical bands, or when blockchain traceability mandates expand beyond pilot retail chains. Forecasts reflect assumptions about biocontrol substitution feasibility and cellulose packaging cold chain performance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
North America Microgreens Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Vegetable Grader Market
Vegetables
Tomato Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Global Indoor Plant Market
Vegetables
Fresh Vegetables Market
Vegetables
Spain Avocado Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Asparagus Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Qatar Greenhouse Market
Vegetables
Dried Vegetable Market
Vegetables
Yam Products Market