
 Ghana Fruit and Vegetable Market | 2026-2036
Ghana Fruit and Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Fruit and Vegetable Market Analysis
The capital-intensity divergence between large-scale irrigated operators and rain-fed smallholders is rotating competitive advantage toward enterprises with controlled water access and mechanized sorting. Golden Exotics Limited leverages its integrated plantation model to sustain year-round banana and pineapple supply to European retailers. Yara Ghana Limited anchors input distribution networks across the northern savanna zones, competing on fertilizer and crop nutrition advisory reach. Sommalife differentiates through organic shea and dried fruit value chains that command premium positioning in health-food segments.
Ghana fruit and vegetable production encompasses the cultivation, harvesting, and primary processing of tropical and semi-tropical crops including plantain, cassava, okra, and citrus, with post-harvest losses historically exceeding thirty percent due to inadequate cold chain infrastructure. The sector serves domestic food security needs, export revenue generation, and raw material supply to processing industries. Fresh fruits occupy the dominant value share driven by pineapple and banana export volumes to European Union markets, while dried fruits represent the fastest-expanding category as processors invest in solar dehydration to reduce spoilage. Local markets still handle the majority of volume, though supermarket channels are capturing margin pools through standardized grading and traceable sourcing that appeals to urban middle-class buyers.
Ghana's national food regulator enforces pesticide residue limits aligned with EU export requirements, while the Ghana Standards Authority certifies produce grades for cross-border trade. The Planting for Food and Jobs program channels subsidized inputs toward smallholder compliance with phytosanitary protocols that unlock premium market access. Stakeholders must monitor how Accra's emerging wholesale cold hubs reshape price discovery and whether regional Ecowas trade harmonization accelerates formal channel growth at the expense of traditional market structures.
Market Dynamics
The Planting for Food and Jobs program is concentrating input access around certified agro-dealers, tilting competitive advantage toward smallholders who meet Ghana Standards Authority phytosanitary protocols for export eligibility.
Growth Catalysts
- EU-aligned residue standards:Ghana's national food regulator enforces pesticide limits matching European import requirements, unlocking premium market access for compliant producers.
- Urban restaurant procurement:Accra and Kumasi-based chain operators are consolidating fresh produce sourcing through formal contracts with traceable suppliers.
- Solar dehydration:Processors deploying photovoltaic-powered drying systems are cutting post-harvest losses below historical thirty-percent thresholds.
Market Restraints
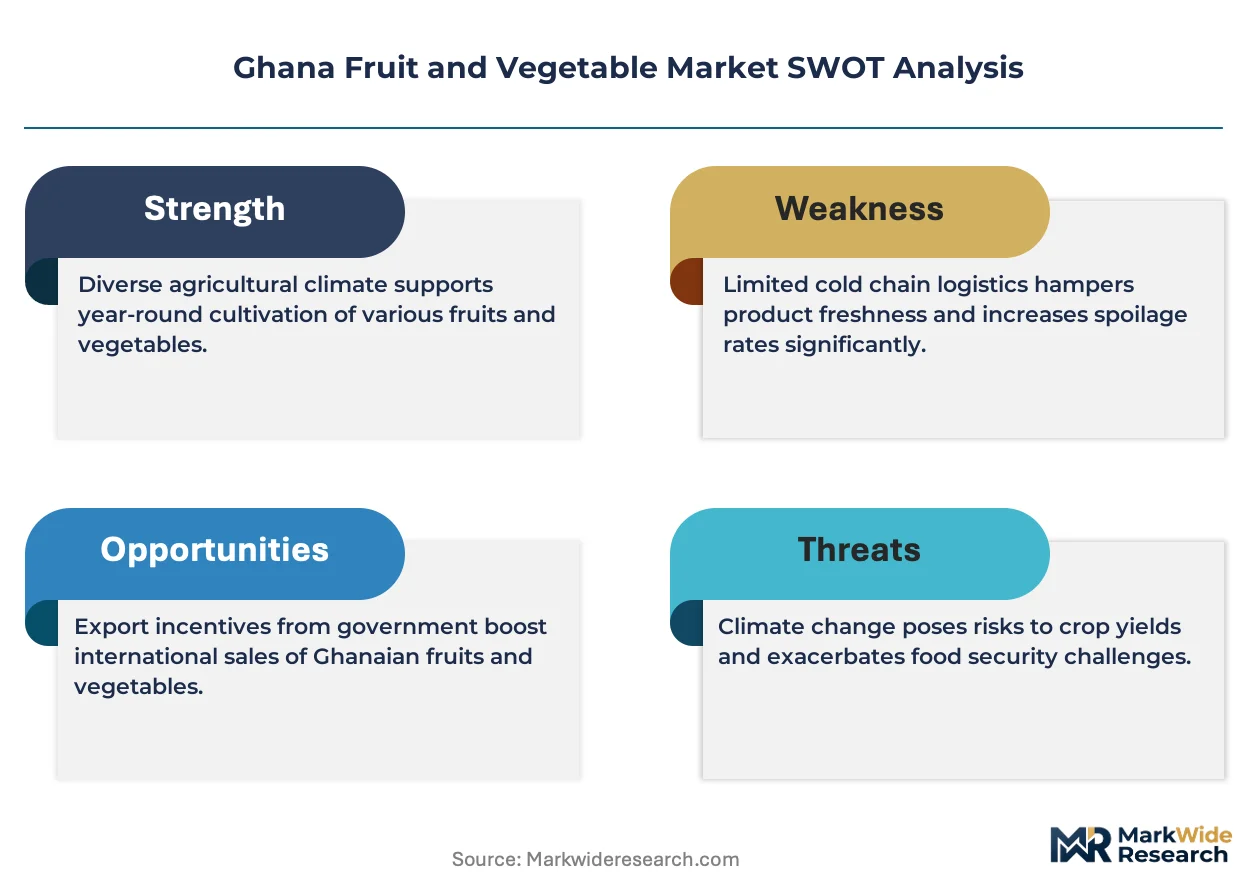
- Fertilizer import dependency:Ghana's northern savanna zones rely on external nitrogen-phosphate supply chains vulnerable to currency fluctuation and maritime logistics disruption.
- Cold storage scarcity:Controlled-atmosphere warehousing concentrates in Greater Accra, leaving Ashanti and Northern Region producers exposed to spoilage during peak harvest windows.
- Rain-fed production dominance:Smallholder operations lacking irrigation infrastructure face yield volatility that undermines contract reliability with formal buyers.
Strategic Opportunities
- ECOWAS trade harmonization:Regional protocol alignment on sanitary standards is creating cross-border market access for Ghanaian exporters into Nigeria and Côte d'Ivoire.
- Organic certification premium:Health-food segment buyers in European markets are paying price premiums for shea and dried fruit carrying EU organic accreditation.
- Wholesale cold hub emergence:Accra's developing temperature-controlled distribution centers are enabling year-round supply contracts previously impossible for seasonal producers.
Industry Challenges
- Phytosanitary compliance timeline:Smallholders face twelve-to-eighteen-month certification cycles with Ghana Standards Authority that delay export market entry.
- Mechanized sorting capex:Automated grading equipment required for supermarket channel access demands capital outlays beyond rain-fed operator capacity.
- Post-harvest handling skill gaps:Cold chain management and controlled-atmosphere storage expertise remains concentrated among large-scale plantation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Fruit and Vegetable Market |
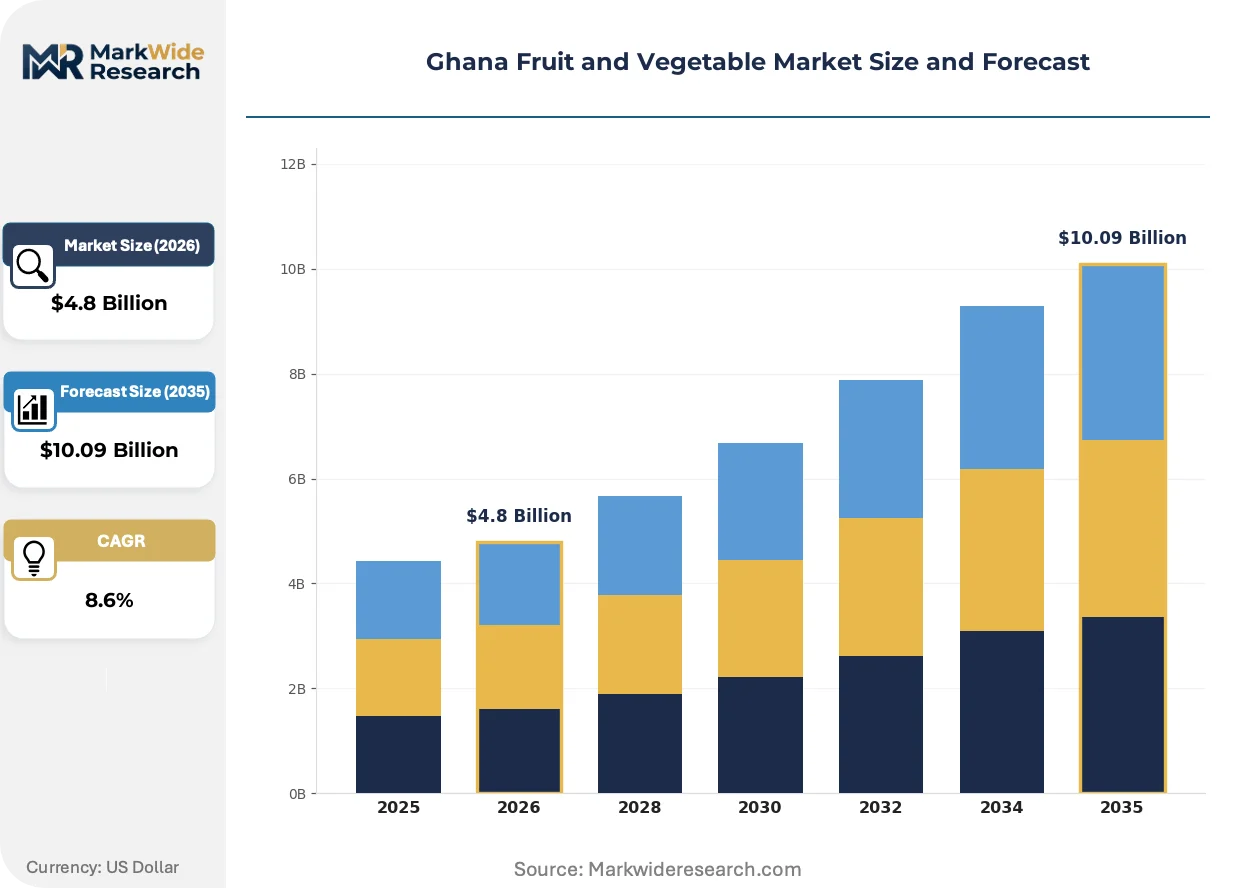
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruits, Fresh Vegetables, Dried Fruits, Frozen Vegetables Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesalers End User: Households, Restaurants, Food Processing, Retailers Packaging Type: Bulk Packaging, Retail Packaging, Reusable Containers, Eco-friendly Packaging |
| Companies Covered | Yara Ghana Limited, Shining Green Farm and Foods, Golden Exotics Limited, Sommalife, Smart Farm Technologies Inc, Elefante Farms, Syngenta Ghana Limited, Mariseth Farms, African Golden Food Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Fruit and Vegetable Market Emerging Trajectories
Technology adoption and regulatory alignment are compressing traditional supply chain margins while opening premium channels for compliant producers. Three forces are actively restructuring competitive positioning.
Solar-powered dehydration technology is displacing open-air sun-drying methods that previously drove thirty-percent post-harvest losses in fruit processing. Mid-scale processors in the Eastern and Central Regions are deploying photovoltaic drying tunnels to supply European health-food retailers with certified organic mango and pineapple products. This capital shift is displacing informal traders who historically dominated dried fruit supply to local markets.
Ghana Standards Authority's phased implementation of EU-equivalent pesticide residue testing is mandating integrated pest management adoption across export-oriented operations. The regulatory tightening is disqualifying smallholders using unregistered agrochemicals from premium European retail contracts. Pineapple and banana exporters to the Netherlands and United Kingdom are consolidating supply relationships with certified plantation operators who maintain residue documentation systems.
Urban supermarket chains in Accra and Kumasi are unbundling traditional wholesale market relationships in favor of direct farmer contracts with traceability requirements. Shoprite and Melcom procurement teams are sourcing graded produce through mobile-enabled logistics platforms that bypass Makola Market intermediaries. This channel migration is most visible in tomato and leafy vegetable categories where shelf-life requirements favor cold-chain-compliant suppliers.
Ghana Fruit and Vegetable Market Segmentation
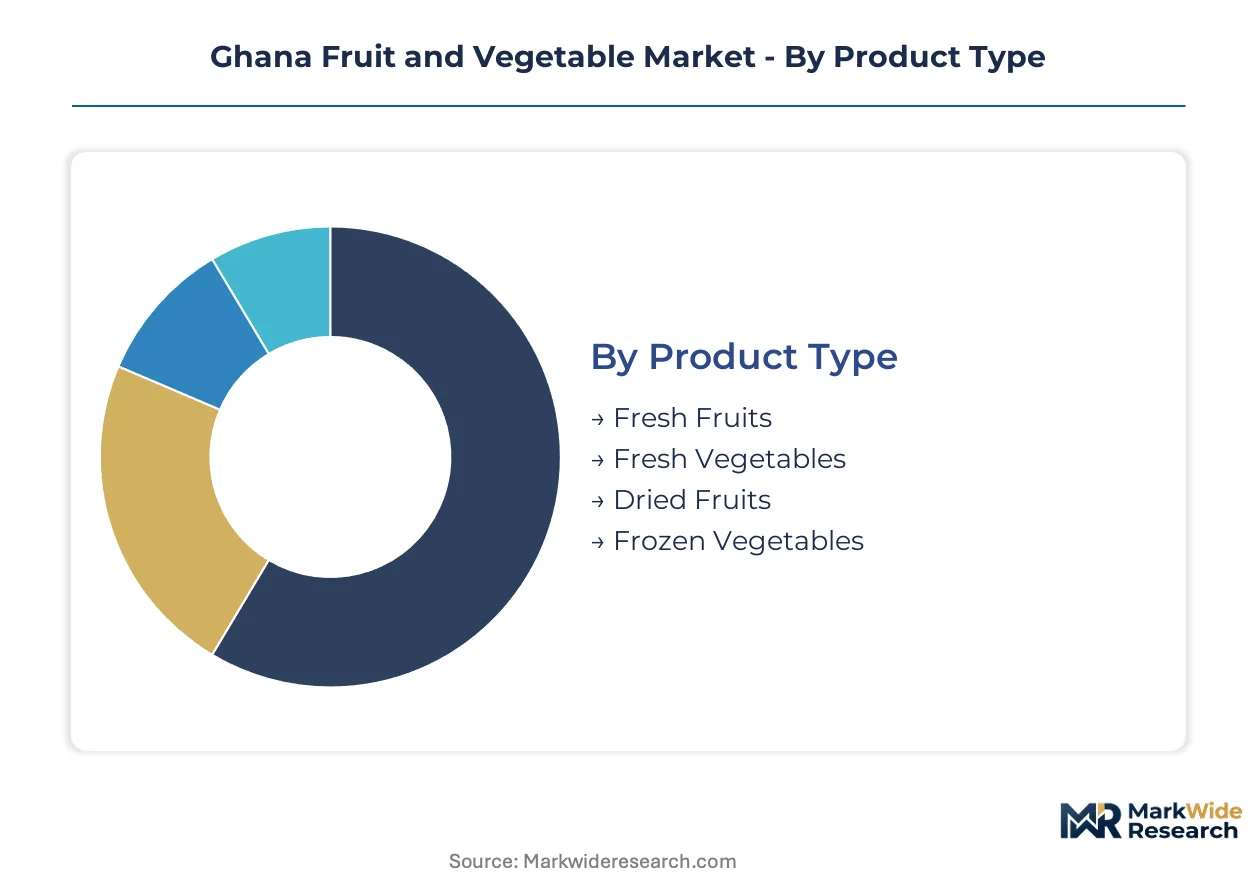
Ghana's fruit and vegetable market segments reflect divergent infrastructure requirements and regulatory exposure. Cold chain capabilities and phytosanitary compliance thresholds determine which segments capture premium pricing versus commodity volume pools.
Product Type:
Ghana Standards Authority certification requirements vary sharply across fresh versus processed formats, creating tiered export eligibility.
- Fresh Fruits:Pineapple and banana exports to European Union markets dominate value concentration. Compliance with EU residue limits enforced by Ghana's national food regulator unlocks premium retail contracts in Netherlands and United Kingdom.
- Dried Fruits:Solar dehydration investments in Eastern and Central Regions are cutting spoilage below historical thresholds. Health-food segment buyers pay premiums for certified organic mango and pineapple products with traceable sourcing documentation.
- Fresh Vegetables:Tomato and leafy greens serve domestic food security needs with limited cold chain penetration.
- Frozen Vegetables:Controlled-atmosphere warehousing scarcity restricts scale to Greater Accra-based processors.
Established volume favors fresh fruits; emerging adoption favors dried fruits.
Distribution Channel:
Channel selection determines margin capture versus infrastructure investment burden for producers.
- Supermarkets:Shoprite and Melcom procurement teams enforce graded produce standards with traceability requirements. Direct farmer contracts bypass traditional Makola Market intermediaries and favor cold-chain-compliant suppliers in tomato and leafy vegetable categories.
- Local Markets:Majority volume still flows through informal wholesale structures with price discovery concentrated in Accra's traditional trading hubs. Post-harvest losses exceed thirty percent due to inadequate temperature control during peak harvest windows.
- Online Retail:Mobile-enabled logistics platforms are emerging for urban middle-class delivery in Greater Accra.
- Wholesalers:Consolidated sourcing relationships concentrate around certified plantation operators with residue documentation systems.
Volume concentration sits with local markets; margin expansion sits with supermarkets.
End User:
Contract reliability requirements separate formal procurement from spot market purchasing.
- Restaurants:Accra and Kumasi-based chain operators are consolidating fresh produce sourcing through formal contracts with traceable suppliers. Year-round supply requirements favor irrigated operators over rain-fed smallholders.
- Households:Domestic food security demand anchors consumption of plantain, cassava, and okra through traditional retail channels.
- Food Processing:Raw material supply to juice and canning operations requires mechanized sorting and standardized grading.
- Retailers:Export-oriented retailers in European markets demand phytosanitary protocols that exclude uncertified smallholders.
Procurement scale favors households; contract formalization favors restaurants.
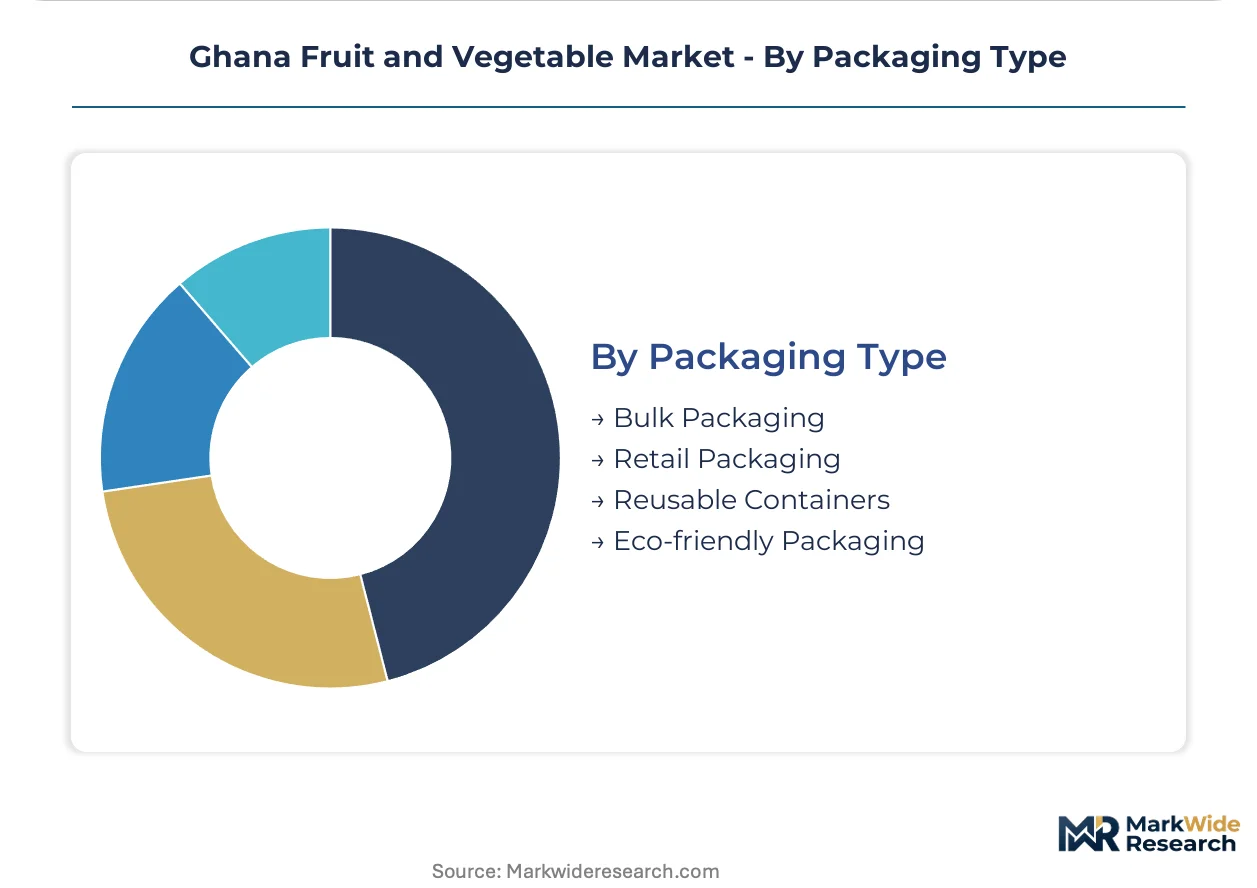
Packaging Type:
Packaging specification tiers align with customer compliance documentation needs.
- Retail Packaging:Standardized grading and barcode traceability enable supermarket channel access. Capital outlays for automated grading equipment exceed rain-fed operator capacity.
- Eco-friendly Packaging:EU organic accreditation requirements drive biodegradable material adoption for health-food segment exports.
- Bulk Packaging:Traditional wholesale and processing supply chains minimize unit packaging costs.
- Reusable Containers:Limited penetration due to reverse logistics infrastructure gaps outside Greater Accra.
Cost efficiency favors bulk packaging; regulatory compliance favors retail packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Ghana's sub-regions, with Greater Accra buyers absorbing cold-chain premiums while Northern Region households face acute sensitivity to transport-inflated produce costs.
Greater Accra
Urban restaurant chains and supermarket procurement teams drive formal contract demand for traceable, graded produce. The Planting for Food and Jobs program channels subsidized inputs toward smallholders meeting Ghana Standards Authority protocols for export eligibility. Cold storage infrastructure and export logistics converge in Tema and Accra, enabling year-round supply contracts for pineapple and banana exporters.
Ashanti Region
Kumasi-based food processors and hospitality operators source tomato and leafy greens through emerging mobile-enabled logistics platforms. National food regulator enforcement of EU-aligned pesticide residue limits is disqualifying uncertified smallholders from premium retail contracts. The region's rain-fed production dominance leaves producers exposed to spoilage during peak harvest windows due to limited controlled-atmosphere warehousing.
Northern Region
Smallholder cassava and okra cultivation serves domestic food security needs with minimal cold chain penetration. Fertilizer import dependency through Yara Ghana Limited's distribution networks creates vulnerability to currency fluctuation and maritime logistics disruption. Tamale's wholesale markets handle majority volume through informal structures with post-harvest losses exceeding historical thresholds.
Eastern Region
Solar dehydration investments are cutting spoilage below thirty-percent benchmarks for mango and pineapple processors supplying European health-food retailers. Ghana Standards Authority phytosanitary certification cycles of twelve-to-eighteen months delay export market entry for uncertified operators. Koforidua's mid-scale processors are deploying photovoltaic drying tunnels to capture organic certification premiums.
Central Region
Pineapple plantation operators leverage irrigated infrastructure to sustain contract reliability with formal buyers year-round. Mechanized sorting capital requirements for supermarket channel access exceed rain-fed operator capacity, consolidating supply relationships around certified enterprises. Cape Coast's emerging temperature-controlled distribution centers are reshaping price discovery for regional produce flows.
Ghana Fruit and Vegetable Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across Ghana's fruit and vegetable sector. Large-scale irrigated plantation operators capture premium export contracts through controlled water access and mechanized sorting capabilities, while rain-fed smallholders compete on volume through informal local market channels. Three archetypes dominate: integrated plantation enterprises with year-round supply reliability, input distribution networks anchoring farmer compliance programs, and organic value chain specialists commanding health-food premiums. Competitive moves concentrate on strategic partnerships with supermarket procurement teams and backward integration into cold storage infrastructure.
Within the integrated plantation tier, Golden Exotics Limited exemplifies the capital-intensive archetype leveraging controlled water access for European retail supply. Yara Ghana Limited anchors input distribution networks across the northern savanna zones, competing on fertilizer and crop nutrition advisory reach. Sommalife occupies a position within the organic certification segment, differentiating through shea and dried fruit value chains that command premium positioning in health-food segments.
| Leading Market Players |
|---|
| Yara Ghana Limited |
| Shining Green Farm and Foods |
| Golden Exotics Limited |
| Sommalife |
| Smart Farm Technologies Inc |
| Elefante Farms |
| Syngenta Ghana Limited |
| Mariseth Farms |
| African Golden Food Ltd |
| Others |
Supply Flow & Price Mechanics
Solar dehydration equipment displacing open-air sun-drying methods simultaneously concentrates processing capacity in Ghana's Eastern and Central Regions and compresses dried fruit price premiums toward European import parity. This capital substitution redraws supply geography away from dispersed smallholder drying plots toward centralized photovoltaic tunnel facilities, eroding the historical thirty-percent spoilage cost buffer that inflated spot market pricing.
Pricing Analysis
After-sales agronomic advisory services drive lifetime value for input distributors competing on farmer retention rather than commodity fertilizer margins. Three-tier pricing structure across premium certified, standard compliant, and economy local-market tiers separates Ghana Standards Authority-exportable produce from domestic-grade and informal-channel supply. Pricing pressure stems from supermarket procurement teams enforcing traceability documentation that disqualifies uncertified smallholders from formal contracts. Rain-fed smallholders in Ghana's Northern Region exhibit acute price sensitivity to transport-inflated input costs, while irrigated plantation operators absorb cold-chain premiums for year-round supply reliability.
Supply Chain Analysis
Inventory cycles compress from seasonal harvest peaks toward year-round availability as Accra's emerging wholesale cold hubs extend holding periods for perishable produce. Supply concentration centers on Greater Accra for cold storage infrastructure, Eastern Region for solar dehydration processing, and Central Region for irrigated pineapple plantation output. Raw material flows draw from northern savanna fertilizer distribution networks, European Union export logistics corridors, and domestic seed multiplication systems. Single-source vulnerability runs through maritime nitrogen-phosphate supply chains exposed to currency fluctuation. Distribution runs through mobile-enabled logistics platforms bypassing traditional Makola Market intermediaries for supermarket channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's fruit and vegetable sector represents a service-attach opportunity where cold-chain logistics and phytosanitary certification services expand faster than raw production volume. Recurring revenue from compliance advisory and temperature-controlled distribution contracts outpaces commodity crop margins for positioned operators.
For Market Incumbents: Secure backward integration into cold storage infrastructure in Greater Accra and Kumasi to defend margin position against emerging wholesale hub competitors. Consolidate supply relationships with Planting for Food and Jobs-certified smallholders before completion of Ghana Standards Authority phytosanitary certification cycles locks in competitor sourcing pools. Channel control through direct farmer contracts offers defensive leverage against supermarket procurement teams disintermediating traditional wholesale structures. For New Entrants and Emerging Players: Anchor in solar dehydration processing for organic mango and pineapple exports to European health-food retailers, the most penetrable premium segment given residue documentation gaps among incumbent operators. Target Eastern Region processing capacity where photovoltaic drying tunnel deployment lags export demand growth. A go-to-market angle through EU organic certification partnerships with established European importers bypasses the twelve-to-eighteen-month Ghana Standards Authority compliance timeline blocking smallholder market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated plantation operators with controlled water access and mechanized sorting capabilities over dispersed rain-fed smallholder networks. Long-term viability across the projection horizon rests on enterprises capturing both production scale and cold-chain infrastructure positioning. Acquisition target archetype: mid-scale processors with solar dehydration assets and pending organic certification. The signal to watch is Ecowas trade harmonization implementation accelerating cross-border market access into Nigeria and Côte d'Ivoire.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Storage Infrastructure Expansion | Accra's temperature-controlled warehousing enables year-round supply contracts previously impossible for seasonal producers. |
| Organic Certification Investment | EU organic accreditation unlocks price premiums for shea and dried fruit in health-food retail channels. |
| Backward Integration into Irrigation | Controlled water access sustains contract reliability with formal buyers against rain-fed yield volatility. |
| Mobile-Enabled Logistics Platform Deployment | Shoprite and Melcom procurement teams source graded produce through digital systems bypassing traditional intermediaries. |
| Phytosanitary Compliance Program | Ghana Standards Authority certification opens premium European retail contracts disqualifying uncertified competitors. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plantation operations managers, agro-dealer network heads, supermarket procurement teams, and Ghana Standards Authority certification officers; and secondary validation through customs export records, Planting for Food and Jobs program disbursement data, and EU pesticide residue compliance databases. Bottom-up farmer survey data triangulated against top-down trade flow estimates to anchor volume assumptions.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning fresh versus processed product formats, supermarket versus traditional channel structures, and irrigated versus rain-fed production systems. CAGRs derived from historical trade momentum, input subsidy program scaling, and cold storage capacity buildout trajectories. Industry-specific forecast inputs incorporated EU residue standard enforcement timelines and solar dehydration technology adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued Planting for Food and Jobs program funding and stable EU market access terms; material deviation in subsidy allocation or phytosanitary protocol alignment would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
India Greenhouse Horticulture Market
Vegetables
Qatar Greenhouse Market
Vegetables
North America Microgreens Market
Vegetables
Europe Christmas Tree Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Asia-Pacific Peas Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
North America Christmas Tree Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Vegetable Grader Market
Vegetables
Global Indoor Plant Market
Vegetables
Dried Mushroom Market