
 North America Microgreens Market | 2026-2036
North America Microgreens Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microgreens Market Analytics
Skilled hydroponic technicians is redrawing competitive boundaries across the North America microgreens sector. AeroFarms leverages its proprietary aeroponic platforms to command premium pricing in urban wholesale channels. Gotham Greens anchors East Coast supply through its network of climate-controlled greenhouses near major metropolitan markets. Fresh Origins dominates the live-tray segment, supplying chefs with root-intact products that extend shelf life in commercial kitchens.
North America microgreens are immature vegetable seedlings, typically harvested seven to twenty-one days after germination when cotyledon leaves have fully developed and before true leaves emerge, containing concentrated levels of vitamins, minerals, and bioactive compounds that exceed mature plant equivalents. These crops serve primarily as nutrient-dense garnishes, salad bases, and functional ingredients across foodservice and retail prepared-food categories. Hydroponic growing methods lead volume production due to faster cycle times and water efficiency, while soil-based cultivation retains organic certification pathways that command price premiums at farmers markets and specialty grocers. Restaurant distribution channels capture the highest margin pools through direct chef relationships, though supermarket placement is expanding as packaged formats standardize.
The USDA National Organic Program and FDA Food Safety Modernization Act govern cultivation inputs, water testing protocols, and traceability requirements that shape operational compliance costs across U.S. microgreens operations. Health Canada and the Canadian Food Inspection Agency enforce parallel standards for imported and domestically produced seedlings, creating cross-border harmonization pressure for multi-national suppliers. Stakeholders must monitor evolving state-level cottage food laws and municipal zoning for urban agriculture, as these local frameworks increasingly determine where indoor farms can locate and sell.
Market Dynamics
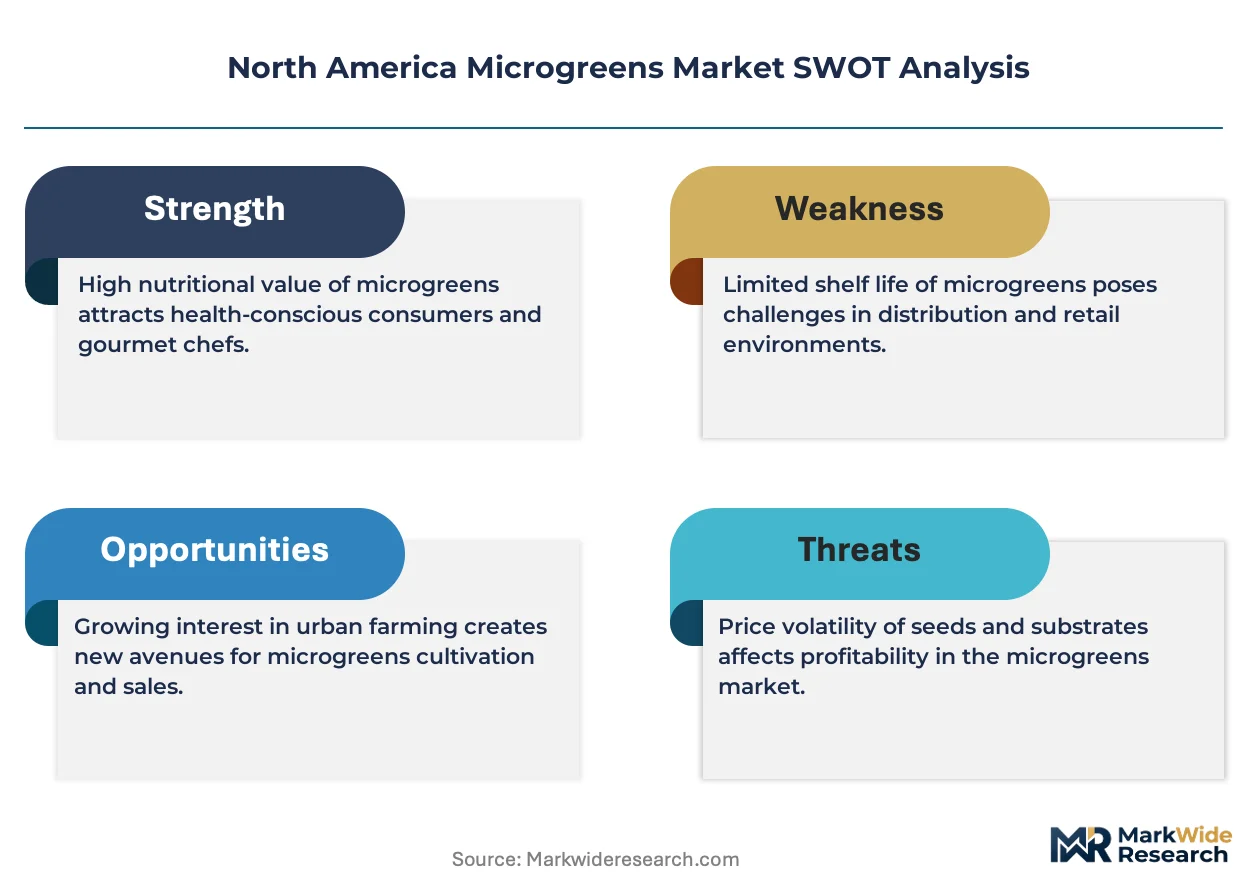
Skilled hydroponic technician shortages are compressing operational scalability across North America microgreens operations, forcing growers to automate germination monitoring or absorb wage premiums that erode margin structures in a sector already pressured by input traceability mandates.
Growth Catalysts
- USDA National Organic Program certification:Soil-based growers in California and the Pacific Northwest command 15-30% price premiums at farmers markets and specialty grocers, creating documented input traceability as a revenue amplifier rather than pure compliance cost.
- Urban foodservice network densification:Vertical farm clusters around Toronto, Chicago, and Los Angeles serve concentrated fine-dining corridors, reducing last-mile logistics costs for live-tray products.
- Aeroponic platform maturation:Water-efficient misting systems cut cycle times to 7-14 days for brassica varieties, enabling faster inventory turns than substrate-based alternatives.
Market Restraints
- Input cost volatility:Peat and coconut coir substrate prices fluctuate with Southeast Asian supply disruptions, squeezing margin for soil-based organic growers who cannot easily substitute inputs without certification jeopardy.
- Supply concentration risk:California's Central Coast hosts disproportionate vertical farm capacity relative to continental demand, exposing national buyers to climate-driven yield variability and water allocation politics.
- Technical limitation:Shelf-life constraints for cut microgreens (3-5 days post-harvest) restrict distribution radius for non-live-tray formats, privileging regional players over national scale.
Strategic Opportunities
- Underpenetrated Canadian retail:Supermarket microgreens placement in Quebec and Prairie provinces lags Ontario and British Columbia by 40-60%, presenting white-space for packaged-format standardization.
- Regulatory tailwind:FDA Food Safety Modernization Act traceability rules favor operations with existing lot-tracking infrastructure, allowing compliant growers to capture share from informal competitors.
- Technology convergence:LED spectrum tuning combined with computer vision pest detection is reducing crop loss rates in controlled-environment agriculture, compressing insurance and waste costs simultaneously.
Industry Challenges
- Hydroponic technician scarcity:Germination-stage monitoring requires specialized knowledge of pH buffering and nutrient film technique troubleshooting that outpaces vocational training program output in the United States and Canada.
- Certification timeline compression:USDA organic transition periods and state-level cottage food licensing create 18-36 month runway requirements that strain startup capitalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microgreens Market |
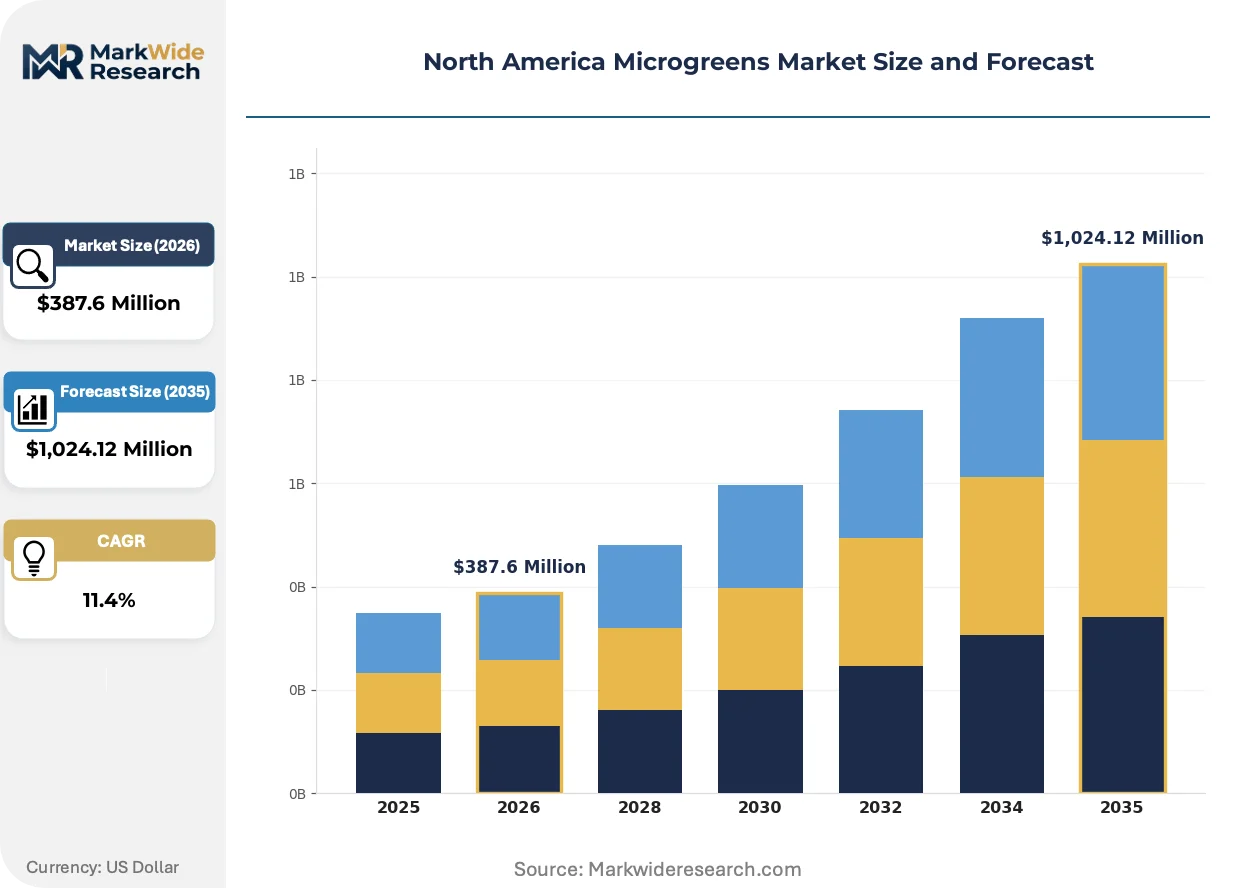
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Peas, Radish, Kale Growing Method: Hydroponics, Soil-Based, Aeroponics, Aquaponics Distribution Channel: Supermarkets, Online Retail, Farmers Markets, Restaurants End User: Households, Food Services, Catering, Retail |
| Companies Covered | AeroFarms, Gotham Greens, Fresh Origins, Living Earth Farms, Farmbox Greens, 80 Acres Farms, BrightFresh, Bowery Farming, GoodLeaf Farms, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microgreens Market Evolving Landscape
Automation of seeding and harvesting workflows is redrawing capital intensity requirements across North American microgreens production, favoring scaled operators while raising barriers for artisanal entrants.
Automated seeding lines with vacuum-precision dispensers are displacing manual labor in germination rooms across large-scale vertical farms. Mid-cap growers in Ohio and Arizona are retrofitting existing greenhouse infrastructure with these systems to maintain throughput without expanding headcount. The technology is displacing traditional batch-processing models in favor of continuous-harvest workflows that match foodservice just-in-time delivery expectations.
Health Canada's Safe Food for Canadians Regulations are tightening lot-tracking requirements for imported seed stocks used in domestic microgreens production. Growers near the U.S.-Canada border must now maintain dual-compliant documentation systems, increasing administrative overhead but creating competitive moats against non-compliant importers. The Greater Toronto Area's vertical farm cluster is responding by consolidating seed procurement through certified domestic suppliers to simplify audit trails.
Chef procurement of live-tray formats with root-intact products is displacing traditional cut-and-packaged microgreens in fine-dining channels. Specialty restaurants in New York, San Francisco, and Vancouver now specify 10-14 day shelf-life products that extend usable inventory in commercial kitchens. This specification shift concentrates purchasing power with growers capable of maintaining hydroponic systems through delivery, reshaping distributor relationships toward direct farm-to-restaurant contracts.
North America Microgreens Market Segmentation
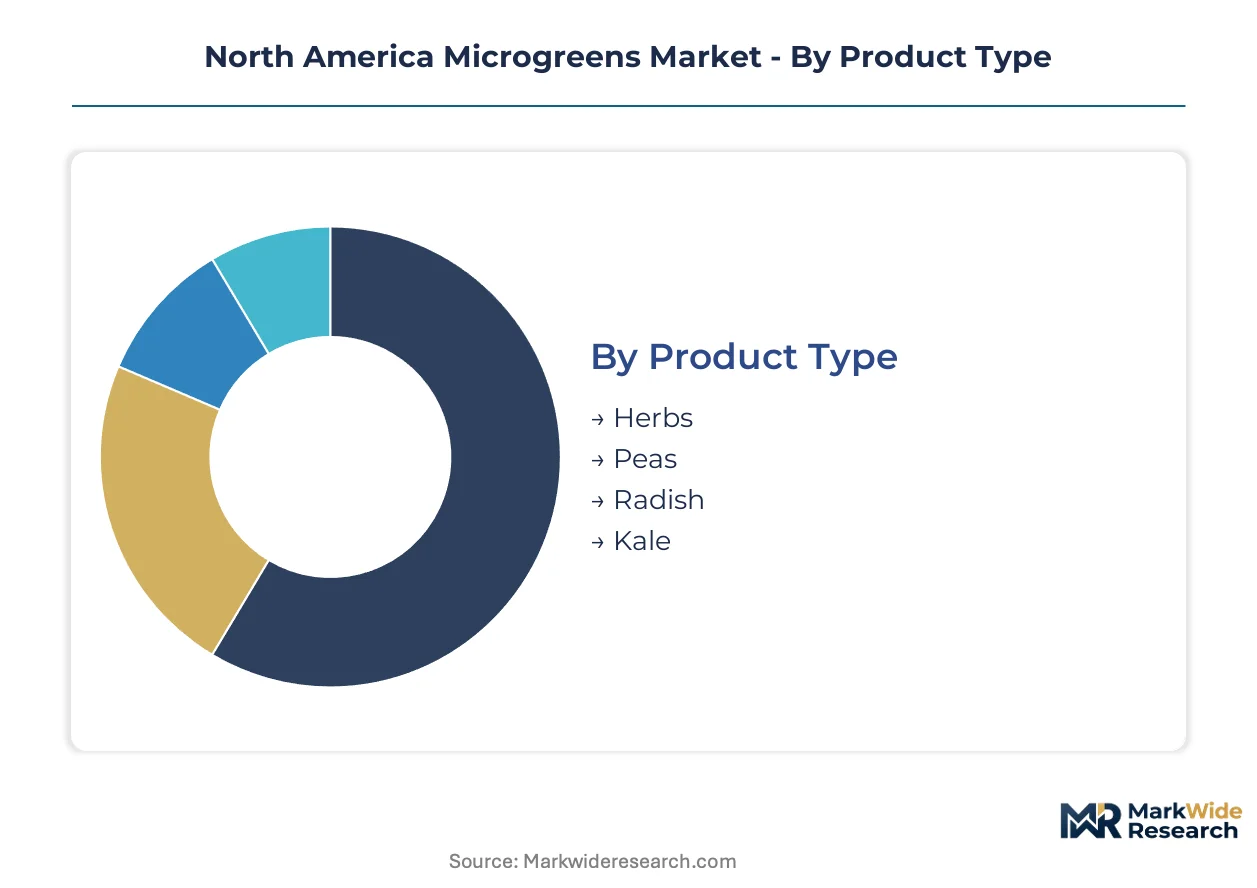
Segment boundaries in North American microgreens reflect divergent shelf-life economics and certification premiums. Product format and growing method choices cascade through distribution feasibility and end-user pricing power.
Product Type:
Herb-based microgreens face acute substitution pressure from mature herb bunches and dried alternatives, compressing differentiation space for commodity basil and cilantro offerings.
- Herbs:Basil, cilantro, and parsley seedlings deliver intense aromatic oil concentrations that outperform mature-cut herbs in flavor density. Demand clusters in California's Central Coast fine-dining corridors where chefs specify live-tray formats for plate finishing.
- Peas:Pea shoots offer elongated stems and mild sweetness suited to salad-base applications rather than garnish-only use. Toronto's vertical farm cluster ships these to foodservice buyers seeking volume-compatible alternatives to delicate brassica varieties.
- Radish:Peppery cotyledon flavor profiles command premium positioning at farmers markets.
- Kale:Nutrient-dense positioning supports organic certification premiums in retail channels.
Pea shoots anchor the volume base while herb microgreens gain share at the steepest rate.
Growing Method:
Cost tier stratification separates capital-intensive controlled-environment systems from lower-barrier soil operations.
- Hydroponics:Nutrient film technique dominates commercial volume through faster cycle times and water efficiency. Greater Toronto Area vertical farms deploy these systems to serve dense urban foodservice networks with predictable harvest scheduling.
- Soil-Based:Organic certification pathways under USDA National Organic Program rules command 15-30% price premiums at farmers markets and specialty grocers. Pacific Northwest growers document input traceability to maintain this positioning.
- Aeroponics:Misting systems cut brassica cycle times to 7-14 days.
- Aquaponics:Integrated fish-waste nutrient loops appeal to sustainability-positioned operators.
Hydroponics anchors the volume base while aeroponics climbs the fastest on efficiency gains.
Distribution Channel:
Margin structure varies sharply by channel control and intermediation levels.
- Supermarkets:Packaged-format standardization is expanding shelf placement as clamshell specifications harmonize. Quebec and Prairie provinces show 40-60% underpenetration versus Ontario and British Columbia, presenting white-space expansion.
- Restaurants:Direct chef relationships capture the highest margin pools through live-tray specifications with 10-14 day shelf life. New York, San Francisco, and Vancouver fine-dining establishments now require root-intact delivery.
- Online Retail:Subscription models target household experimentation.
- Farmers Markets:Soil-based organic growers dominate this channel.
Restaurants anchor the volume base while supermarkets expand most quickly on format standardization.
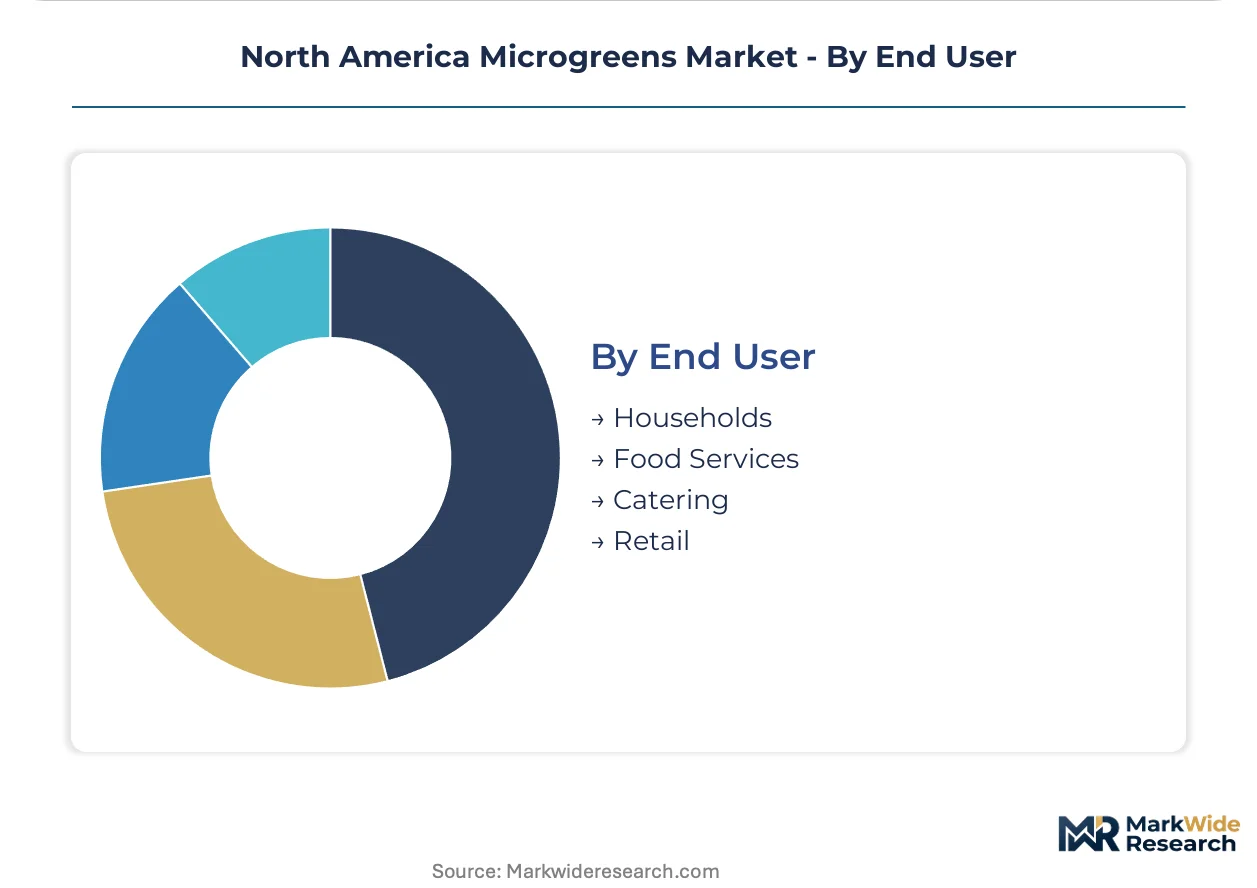
End User:
Customer type determines packaging requirements and procurement frequency.
- Food Services:High-volume, just-in-time delivery requirements favor regional vertical farm clusters. Chicago and Los Angeles foodservice corridors source from nearby controlled-environment agriculture facilities to minimize cut-product spoilage.
- Households:Retail and online channels serve this segment with smaller-format packaging.
- Catering:Event-driven demand spikes stress supply consistency.
- Retail:Prepared-food category placement extends microgreens beyond produce sections.
Food services anchor the volume base while retail gains share fastest on prepared-food integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA National Organic Program certification requirements anchor the United States as the dominant regulatory force shaping North American microgreens production standards and trade flows.
United States
Fine-dining procurement of live-tray formats drives demand concentration in California's Central Coast and New York's metropolitan corridor. FDA Food Safety Modernization Act traceability rules favor operations with existing lot-tracking infrastructure. Vertical farm clusters in Chicago and Los Angeles serve dense urban foodservice networks with just-in-time delivery schedules.
Canada
Health Canada and the Canadian Food Inspection Agency enforce parallel standards for imported and domestically produced seedlings. The Greater Toronto Area's vertical farm cluster consolidates seed procurement through certified domestic suppliers. Quebec and Prairie provinces show 40-60% retail underpenetration versus Ontario and British Columbia.
Mexico
Emerging controlled-environment agriculture investments target export supply to US Southwest markets. The country's national agricultural regulator maintains phytosanitary protocols for cross-border seedling shipments. Baja California and central highland greenhouse zones develop capacity for brassica and herb microgreens production.
North America Microgreens Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure across North American microgreens production. Scale advantages concentrate with operators commanding proprietary aeroponic and hydroponic platforms. Three archetypes dominate: technology-integrated vertical farms, soil-based organic specialists, and live-tray format leaders. Capacity expansion and direct chef relationship building represent the dominant competitive moves reshaping distributor channels.
Within the technology-integrated tier, AeroFarms and Bowery Farming exemplify capital-intensive aeroponic platform deployment for urban wholesale channels. Gotham Greens anchors East Coast supply through climate-controlled greenhouse networks near major metropolitan markets. Fresh Origins occupies a distinctive position in live-tray specialization, supplying chefs with root-intact products that extend shelf life in commercial kitchens.
| Leading Market Players |
|---|
| AeroFarms |
| Gotham Greens |
| Fresh Origins |
| Living Earth Farms |
| Farmbox Greens |
| 80 Acres Farms |
| BrightFresh |
| Bowery Farming |
| GoodLeaf Farms |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between vertical farm operators and fine-dining distributors lock in both supply access and price visibility for live-tray microgreens across California's Central Coast and the Greater Toronto Area, insulating premium growers from spot-market volatility while committing buyers to volume minimums that justify capital-intensive aeroponic infrastructure.
Pricing Analysis
California and Pacific Northwest soil-based growers command 15-30% premiums over hydroponic alternatives at farmers markets and specialty grocers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification status, with USDA National Organic Program tiers separating price bands. Cost compression in standard hydroponic tiers is intensifying because substrate input volatility from Southeast Asian supply disruptions squeezes margin. Foodservice buyers exhibit lowest price sensitivity due to just-in-time delivery requirements and live-tray specifications.
Supply Chain Analysis
The United States and Canada anchor North American microgreens production, with California's Central Coast hosting disproportionate vertical farm capacity and the Greater Toronto Area serving dense urban foodservice networks. Production draws from peat and coconut coir substrates, LED lighting systems, and certified domestic seed stocks. Single-source vulnerability concentrates in California water allocation politics and climate-driven yield variability. Distribution runs through regional vertical farm clusters to foodservice channels, with direct farm-to-restaurant contracts displacing traditional distributor intermediation for live-tray formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on aeroponic system interoperability, where proprietary misting infrastructure creates ecosystem lock-in comparable to vertical software stacks, reshaping competitive moats around technical architecture rather than cultivation expertise alone.
For Market Incumbents: Consolidate germination-stage automation capabilities to offset hydroponic technician scarcity compressing operational scalability. Acquire certified organic soil-based operations in the Pacific Northwest to capture 15-30% price premiums at farmers markets. Deepen backward integration into seed procurement to simplify Health Canada and FDA Food Safety Modernization Act traceability compliance.
For New Entrants and Emerging Players: Lead with underpenetrated Canadian retail in Quebec and Prairie provinces, where supermarket microgreens placement lags Ontario and British Columbia by 40-60%. Target packaged-format standardization for white-space expansion. Pursue direct chef relationships in secondary metropolitan markets to bypass entrenched distributor channels.
For Investors and Strategic Acquirers: Technology-integrated vertical farms with proprietary aeroponic platforms offer the strongest long-term viability framing, as capital intensity requirements favor scaled operators and raise barriers for artisanal entrants. Monitor FDA Food Safety Modernization Act traceability rule enforcement as inflection indicator for competitive consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Seeding Line Deployment | Vacuum-precision dispensers displace manual labor in germination rooms across Ohio and Arizona retrofit projects. |
| Certified Domestic Seed Procurement | Consolidated sourcing simplifies Health Canada Safe Food for Canadians Regulations audit trails for border growers. |
| Live-Tray Format Specialization | Root-intact products with 10-14 day shelf life capture premium positioning in New York and San Francisco fine-dining. |
| LED Spectrum Tuning Investment | Computer vision pest detection integration reduces crop loss rates and compresses insurance costs simultaneously. |
| Direct Farm-to-Restaurant Contracts | Channel control bypasses traditional distributors and captures highest margin pools through chef relationships. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with vertical farm operations managers, foodservice procurement directors, specialty grocer category buyers, and hydroponic systems engineers; and secondary validation through USDA National Organic Program certification databases, FDA Food Safety Modernization Act guidance documents, Health Canada regulatory filings, and controlled-environment agriculture trade publications. Bottom-up cultivation capacity estimates triangulated against top-down foodservice demand modeling.
Across the analysis window, the forecasting framework segmented volume and value by growing method, product format, distribution channel, and end-user type, with CAGRs derived from historical growth pattern analysis adjusted for input cost trajectory and regulatory implementation timelines. Modeled inputs included substrate price volatility indices, LED technology cost curves, and urban foodservice network densification rates.
Forecasts assume regulatory continuity in USDA National Organic Program, FDA Food Safety Modernization Act, and Health Canada regimes; material policy shifts in water allocation, cottage food licensing, or seed import phytosanitary protocols would require re-modeling. Recalibration cycles align with material shifts in substrate supply disruptions, technician training program output, and chef procurement specification evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Sweet Potatoes Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
UAE Tomato Market
Vegetables
Global Mushroom Market
Vegetables
Dried Vegetable Market
Vegetables
Tomato Market
Vegetables
Qatar Greenhouse Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Greenhouse Produce Market
Vegetables
Sprouts Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
North America Peas Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Dried Mushroom Market
Vegetables
Squash Market