
 Dried Mushroom Market | 2026-2036
Dried Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Mushroom Market Analysis
The gap between premium wild-foraged porcini and commodity cultivated shiitake is realigning procurement strategies across the supply chain. Bonduelle Group leverages its European retail network to sustain volume leadership in standardized dried varieties. Monaghan Mushrooms anchors its position through controlled-environment agriculture that competes on consistency against seasonal wild harvests. Sabarot differentiates through heritage French sourcing that dominates specialty channels in Western Europe.
Dried mushrooms are fresh fungi dehydrated to moisture levels below 12 percent through hot-air drying, freeze-drying, or solar methods, yielding shelf-stable products with concentrated umami compounds and extended storage viability for food manufacturing and culinary applications. Shiitake occupies the mature volume tier where margin pools have compressed amid Asian supply abundance, while porcini commands premium positioning in European retail and foodservice channels. The food processor end user segment shows structural expansion as dried powders replace synthetic flavor enhancers in clean-label formulations.
EU EFSA standards for mycotoxin limits and FDA hazard analysis requirements for imported dried foods shape compliance costs and supplier qualification timelines. China's GB standards for agricultural products and SAMR food safety protocols create additional certification layers for export-oriented processors. Stakeholders must monitor evolving organic equivalency agreements between major producing and consuming jurisdictions to anticipate sourcing disruptions.
Market Dynamics
EU EFSA mycotoxin limits and FDA hazard analysis requirements for imported dried foods are compressing supplier qualification timelines and elevating compliance costs for non-European processors seeking Western market access.
Growth Catalysts
- Clean-label reformulation:Food manufacturers are replacing synthetic flavor enhancers with dried mushroom powders in soups, sauces, and savory snacks. This substitution accelerates procurement from processors with certified organic supply chains.
- EU Novel Food Regulation:Standardized safety assessments for novel mushroom species are reducing regulatory uncertainty for innovators introducing lesser-known varieties like lion's mane and maitake into European retail channels.
- Shiitake processing clusters:China's concentration of dehydration infrastructure in Fujian and Zhejiang provinces generates economies of scale that lower input costs for global ingredient buyers.
Market Restraints
- Wild harvest volatility:Porcini and morel yields fluctuate with forest ecosystem conditions in Italy, France, and the Pacific Northwest, creating supply unpredictability that commodity buyers cannot hedge effectively.
- Input energy costs:Hot-air dehydration and freeze-drying are electricity-intensive processes; European processors face margin compression from industrial power tariffs tied to natural gas price volatility.
- Fresh mushroom substitution:Controlled-environment agriculture in the Netherlands and Poland is extending fresh mushroom availability year-round, reducing foodservice reliance on dried alternatives in adjacent categories.
Strategic Opportunities
- US functional food channel:Supplement and nutraceutical brands are formulating with dried lion's mane and reishi extracts for cognitive and immune positioning, creating premium pricing power absent from commodity culinary grades.
- EU organic equivalency expansion:Negotiations between the European Commission and China's certification bodies could streamline access for certified Chinese shiitake processors if mutual recognition agreements advance.
- Direct-to-chef platforms:Specialty distributors are bypassing traditional wholesale layers to connect French and Italian foragers directly with Michelin-starred kitchens, capturing margin that previously accrued to intermediaries.
Industry Challenges
- Mycotoxin testing capacity:Laboratories capable of EU-compliant ochratoxin A and aflatoxin analysis are concentrated in Germany and the Netherlands, creating bottlenecks for suppliers in Eastern Europe and Asia seeking rapid certification turnaround.
- Traceability system integration:Small-scale foraging cooperatives in Italy and Spain lack digital infrastructure to meet batch-level origin documentation requirements from major retail chains and food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Mushroom Market |
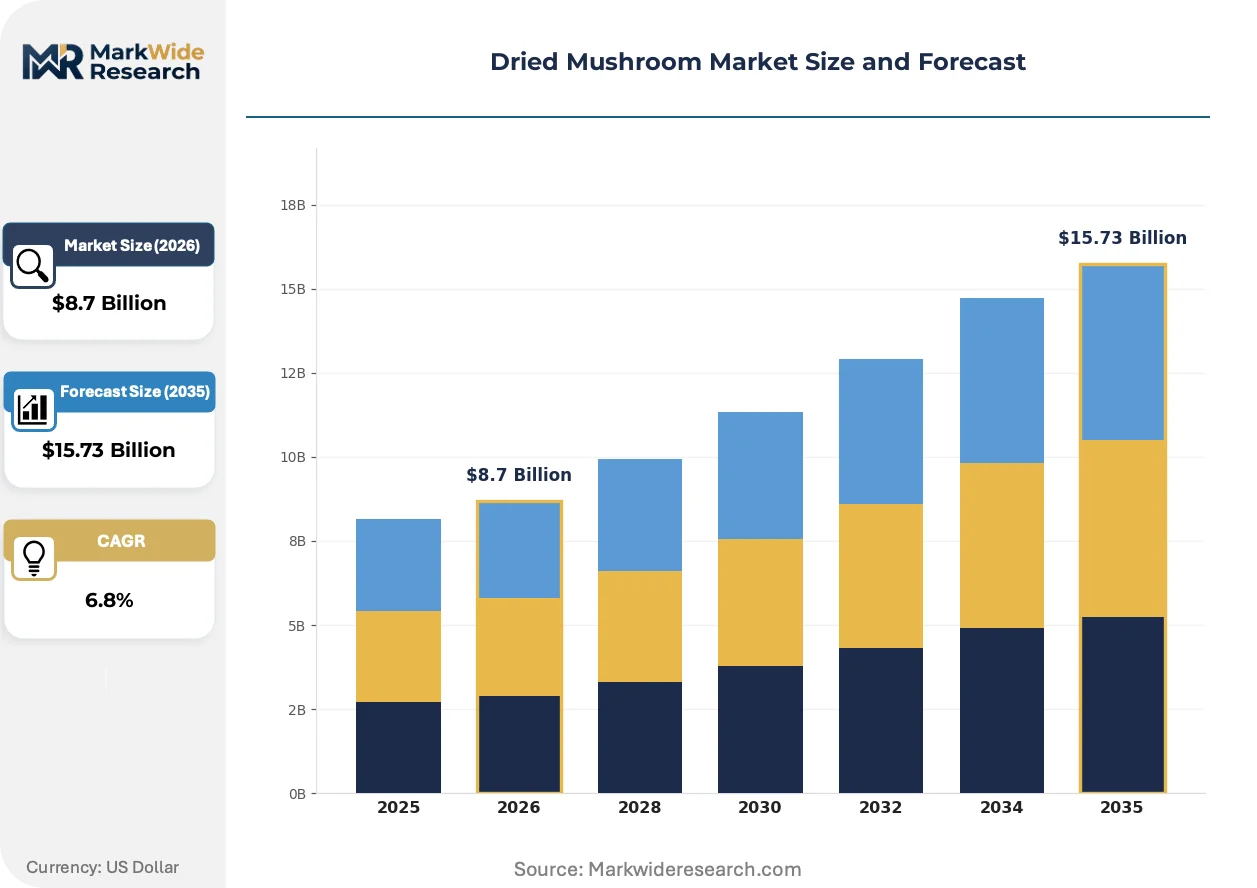
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shiitake, Porcini, Chanterelle, Morel End User: Restaurants, Retailers, Food Processors, Households Packaging Type: Bags, Jars, Sachets, Bulk Packaging Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Bonduelle Group, Monterey Mushrooms, Monaghan Mushrooms, Weikfield Foods, Greenyard NV, ShunDi Foods, Sabarot, Costa Group Holdings, Biofungi GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Mushroom Market Emerging Trajectories
Dehydration technology and supply chain transparency systems are reconfiguring competitive advantage away from simple volume scale toward precision control over moisture content, active compound retention, and provenance verification.
Freeze-drying is consolidating quality-tier supply chains by preserving volatile aromatic compounds and structural integrity that hot-air methods degrade. Premium chocolate manufacturers and high-end spice blenders are specifying freeze-dried porcini for formulations where flavor intensity justifies 3-4x procurement cost premiums over conventional dried grades. This technology compression is forcing mid-tier processors to invest in capital-intensive equipment or retreat to commodity shiitake segments where price competition dominates.
EU EFSA mycotoxin surveillance programs are tightening batch-testing protocols for dried mushrooms entering European retail and food manufacturing channels. Processors must now maintain laboratory partnerships capable of rapid turnaround on ochratoxin A analysis, adding fixed cost burdens that favor scaled operators over artisanal foraging cooperatives. Italian and French suppliers with integrated testing capabilities are capturing shelf space from competitors dependent on third-party certification timelines.
Chef-direct procurement platforms are fragmenting traditional wholesale distribution by connecting specialty foragers in the Italian Alps and French Massif Central with restaurant buyers seeking documented provenance. These digital intermediaries displace conventional importers who previously controlled information asymmetries around origin and harvest timing. The shift is most visible in London, Paris, and New York, where menu transparency requirements and storytelling value have elevated traceability from operational detail to competitive positioning.
Dried Mushroom Market Segmentation
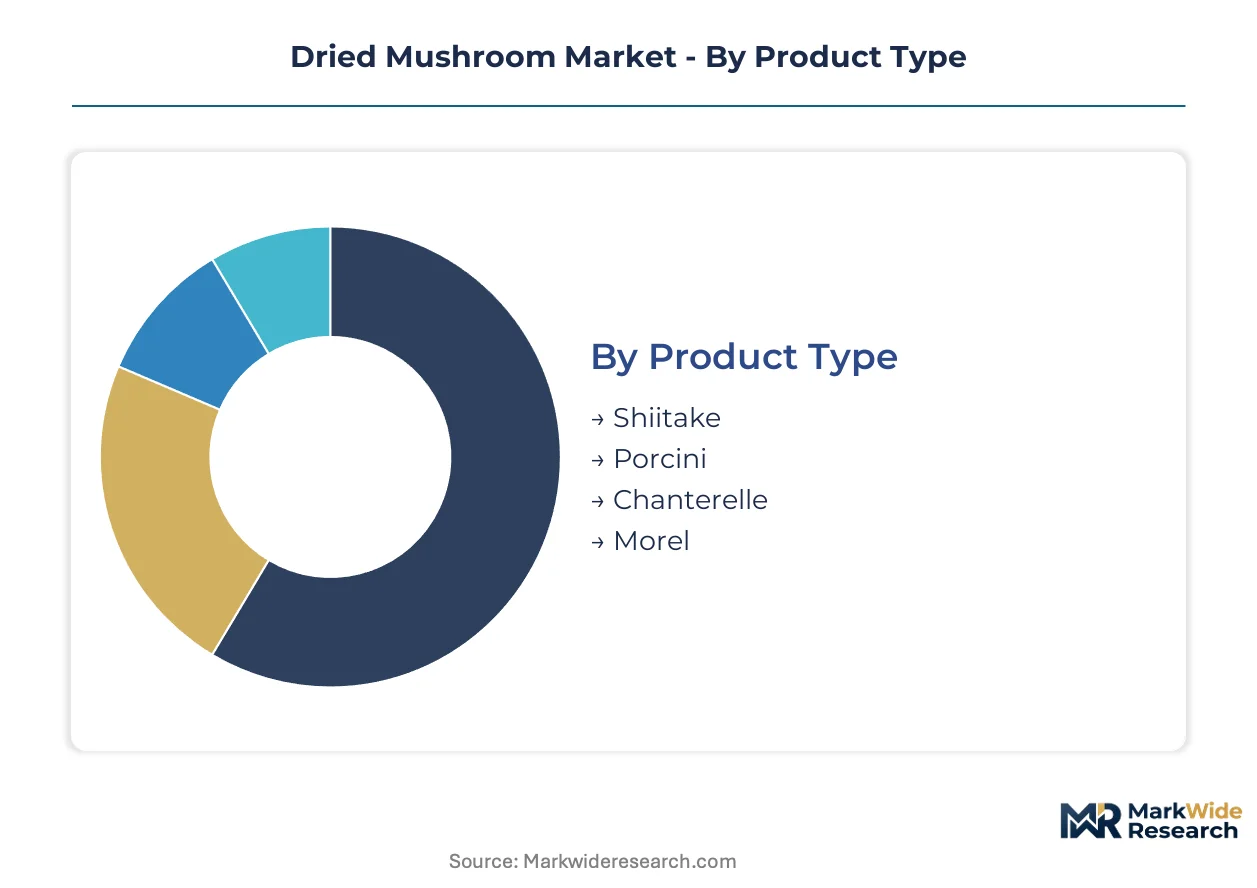
Dried mushroom procurement strategies diverge sharply between commodity-grade shiitake traded on volume metrics and wild-foraged porcini priced on provenance documentation. Understanding segment boundaries helps suppliers align dehydration investment, certification spending, and channel selection with margin capture potential.
Product Type:
Volume concentration separates cultivated Asian supply from European wild harvest premiums.
- Shiitake:Cultivated on oak sawdust substrates across Fujian and Zhejiang provinces, then hot-air dried to moisture levels below 12 percent. Demand concentrates in China's processing hubs where domestic production feeds both local consumption and export manufacturing to North American and European ingredient buyers seeking cost-competitive umami bases.
- Porcini:Wild-foraged in Italian alpine forests and French Massif Central, with freeze-dried grades preserving volatile aromatic compounds that hot-air methods degrade. Procurement concentrates in Michelin-starred kitchens across London, Paris, and New York where menu transparency requirements and storytelling value have elevated traceability from operational detail to competitive positioning.
- Chanterelle:Harvested from Pacific Northwest conifer forests and Eastern European woodlands, prized for apricot-like aroma profiles that command specialty retail positioning.
- Morel:Spring-harvested in fire-disturbed forest ecosystems across Turkey, India, and North America, with extreme supply volatility limiting commercial scale.
Mature deployment sits with Shiitake. Newer deployment is concentrated in Porcini freeze-dried grades.
End User:
Clean-label reformulation is redrawing procurement relationships between ingredient buyers and finished goods manufacturers.
- Food Processors:Dried powders replace synthetic flavor enhancers in soups, sauces, and savory snacks, accelerating procurement from processors with certified organic supply chains that meet EU EFSA mycotoxin limits and FDA hazard analysis requirements.
- Restaurants:Gourmet establishments across North America and Europe expand procurement of specialty varieties through direct-to-chef platforms that bypass traditional wholesale layers and capture margin previously accruing to intermediaries.
- Retailers:European retail networks sustain volume leadership in standardized dried varieties, with organic certification standards in Germany and France tightening entry requirements for non-European suppliers.
- Households:Asian domestic markets absorb significant shiitake volumes for traditional cooking applications, with rehydration convenience driving sachet format preference.
Ingredient-grade supply relationships dominate Food Processors. Direct sourcing platforms are expanding fastest among Restaurants.
Packaging Type:
Format selection tracks moisture sensitivity, resealability requirements, and retail versus foodservice channel economics.
- Bulk Packaging:10-25 kilogram poly-lined cartons serve industrial food manufacturers and restaurant distributors with high-throughput dehydration operations, minimizing per-unit packaging cost.
- Bags:Stand-up pouches with oxygen barrier layers dominate retail shelf presentation for premium wild varieties requiring visible product quality assessment.
- Jars:Glass containers with desiccant seals target gift and specialty segments where packaging aesthetics support price premiums.
- Sachets:Single-serve portions address convenience-oriented household segments and airline catering applications with strict portion control requirements.
Industrial procurement anchors Bulk Packaging. Premium positioning drives fastest expansion in Bags.
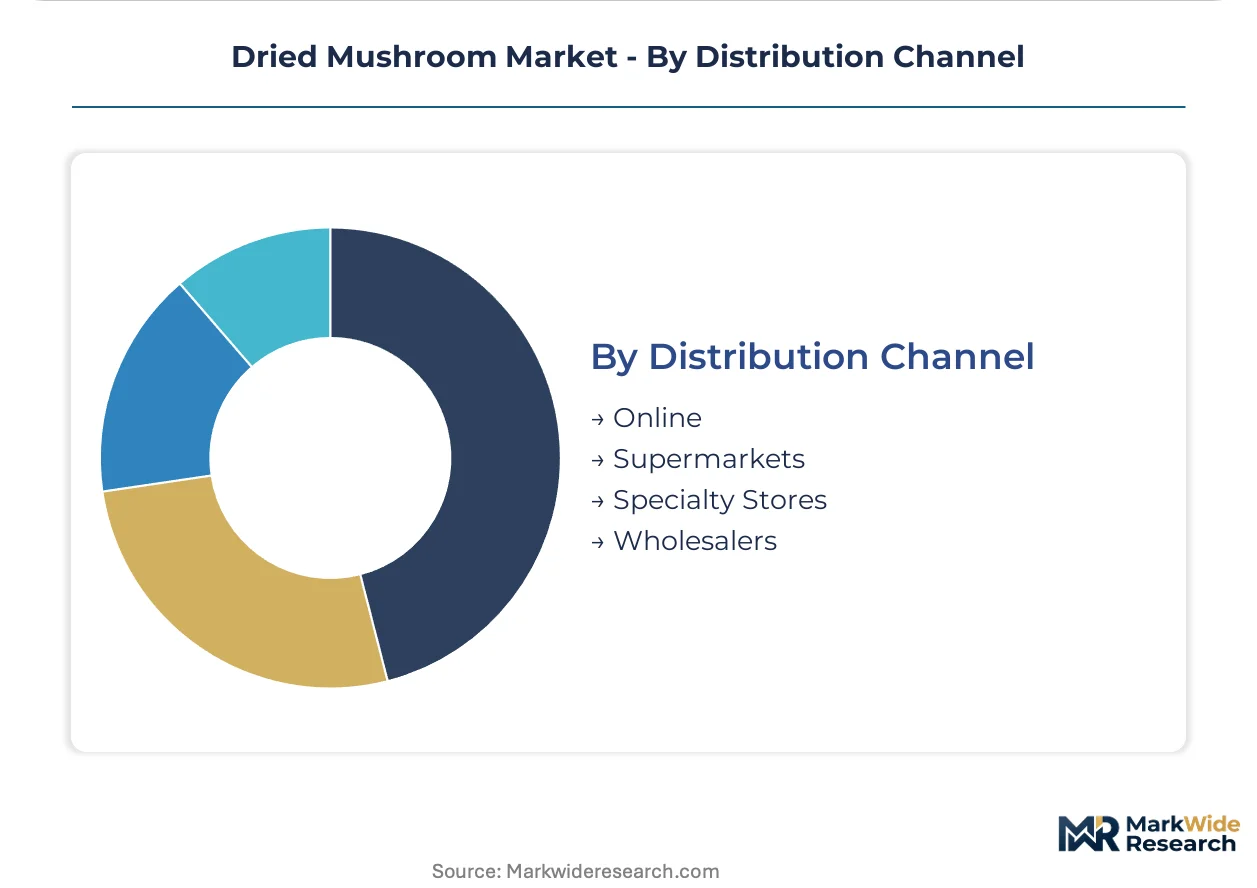
Distribution Channel:
Channel fragmentation reflects the divergence between commodity ingredient procurement and specialty provenance verification.
- Wholesalers:Traditional import-export houses control shiitake volume flows from Chinese dehydration clusters to European and North American ingredient distributors, though margin compression is forcing consolidation.
- Specialty Stores:Italian and French suppliers with integrated mycotoxin testing capabilities capture shelf space from competitors dependent on third-party certification timelines, particularly in urban centers with demanding consumer bases.
- Supermarkets:Controlled-environment agriculture in the Netherlands and Poland is extending fresh mushroom availability year-round, reducing supermarket reliance on dried alternatives in adjacent categories.
- Online:Digital intermediaries connect French and Italian foragers directly with restaurant buyers, displacing conventional importers who previously controlled information asymmetries around origin and harvest timing.
Established volume flows run through Wholesalers. Traceability-verified supply is concentrating fastest in Online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fujian and Zhejiang provinces anchor global dehydration infrastructure, processing shiitake volumes that supply ingredient buyers across North America and Europe. This concentration shapes procurement patterns for commodity-grade dried mushrooms worldwide.
China
Domestic shiitake cultivation on oak sawdust substrates feeds processing clusters in southeastern provinces. SAMR food safety protocols and GB standards for agricultural products create certification layers for export-oriented facilities. Zhejiang dehydration plants supply North American food manufacturers with cost-competitive umami bases.
Italy
Wild porcini foraging in alpine forests supplies Michelin-starred kitchens demanding documented provenance. EFSA mycotoxin surveillance programs tighten batch-testing protocols for ochratoxin A analysis. Piedmont and Emilia-Romagna cooperatives integrate laboratory partnerships to capture retail shelf space from competitors using third-party certification.
United States
Supplement and nutraceutical brands formulate with lion's mane and reishi extracts for cognitive positioning. FDA hazard analysis requirements for imported dried foods elevate compliance costs for non-domestic processors. Pacific Northwest conifer forests yield chanterelle harvests prized by specialty distributors.
France
Gourmet restaurants in Paris expand procurement of heritage-sourced morel and porcini through direct-to-chef platforms. Evolving organic certification standards tighten entry requirements for non-European suppliers. Massif Central foraging cooperatives leverage digital intermediaries to bypass traditional wholesale layers.
Germany
Industrial food manufacturers drive demand for certified organic mushroom powders in clean-label reformulations. EU EFSA standards for mycotoxin limits compress supplier qualification timelines. Bavarian and Baden-Württemberg testing laboratories create bottlenecks for Eastern European suppliers seeking rapid certification turnaround.
Dried Mushroom Market Vendor Landscape
Premium-margin players sit above commodity-margin players across provenance documentation and dehydration technology tiers. The vendor base stratifies between scaled processors with integrated testing capabilities and artisanal foraging cooperatives lacking digital infrastructure. Three archetypes dominate: European heritage sourcers, Asian volume processors, and controlled-environment agriculture specialists. Competitive moves concentrate on M&A for dehydration capacity and strategic partnerships with laboratory testing networks.
Within the heritage sourcing tier, Sabarot represents French alpine provenance specialization, while Bonduelle Group exemplifies European retail network leverage for standardized varieties. Among controlled-environment operators, Monaghan Mushrooms occupies a position competing on consistency against seasonal wild harvests. These three anchors illustrate how geographic origin and supply chain architecture determine margin capture potential across commodity and premium segments.
| Leading Market Players |
|---|
| Bonduelle Group |
| Monterey Mushrooms |
| Monaghan Mushrooms |
| Weikfield Foods |
| Greenyard NV |
| ShunDi Foods |
| Sabarot |
| Costa Group Holdings |
| Biofungi GmbH |
| Others |
Supply Flow & Price Mechanics
Michelin-starred kitchens in London, Paris, and New York anchor pricing power through documented provenance requirements that separate freeze-dried porcini from commodity shiitake. This buyer concentration rewards suppliers with integrated laboratory testing and digital traceability infrastructure while compressing margins for undifferentiated volume processors.
Pricing Analysis
Value-based pricing tied to aromatic compound retention and origin documentation anchors the premium tier, with freeze-dried porcini commanding multiples over hot-air grades. Price differentiation rests on EFSA mycotoxin certification status and harvest region specificity, with Italian alpine sourcing carrying brand premiums. Pricing pressure stems from Chinese shiitake oversupply flooding ingredient markets, eroding contract premiums. Food processors exhibit highest price sensitivity due to reformulation cost targets, while chef-direct buyers prioritize traceability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European retailers mandate qualified suppliers in both China and Italy to hedge harvest volatility and regulatory disruption. Geographic supply concentrates in Fujian and Zhejiang provinces for cultivated shiitake, with Italian alpine regions and French Massif Central anchoring wild porcini. Raw material dependencies include oak sawdust substrates, conifer forest ecosystems, and electricity for dehydration infrastructure. Single-source vulnerability runs through mycotoxin testing laboratories concentrated in Germany and the Netherlands. Distribution runs through specialty wholesalers for commodity grades and digital intermediaries for provenance-verified supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where laboratory testing capabilities and dehydration technology ownership determine margin capture. Players are pursuing upstream control over foraging cooperatives and certification infrastructure to defend positioning.
For Market Incumbents: Anchor market position through backward integration into Italian and French foraging cooperatives with integrated EFSA-compliant testing laboratories. Invest in freeze-drying capacity to escape shiitake commodity compression. Defend against emerging chef-direct platforms by controlling harvest timing information and batch-level origin documentation that intermediaries cannot replicate. For New Entrants and Emerging Players: Launch via direct-to-chef digital platforms connecting Pacific Northwest chanterelle foragers with specialty distributors in New York and San Francisco. Target the US functional food channel where supplement brands seek lion's mane and reishi extracts for cognitive positioning, a segment with limited incumbent penetration and premium pricing tolerance absent from culinary grades. For Investors and Strategic Acquirers: The window for entry favors processors with integrated dehydration and testing infrastructure in European heritage sourcing regions. Long-term viability hinges on regulatory moats around EFSA certification and organic equivalency agreements. Watch for mutual recognition advancement between the European Commission and China's certification bodies as an inflection signal for Chinese processor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Preserves volatile aromatic compounds that hot-air methods degrade, capturing Michelin-tier premiums. |
| Laboratory Testing Integration | EFSA-compliant ochratoxin A analysis capabilities eliminate third-party certification bottlenecks for Italian suppliers. |
| Direct-to-Chef Platform Launch | Digital intermediaries displace conventional importers by connecting French foragers with restaurant buyers. |
| Organic Equivalency Certification | Mutual recognition agreements between the EU and China streamline market access for Zhejiang processors. |
| Foraging Cooperative Acquisition | Upstream control over Italian alpine and Massif Central harvests secures provenance documentation for premium tiers. |
Methodological Framework
Trade databases, EFSA surveillance reports, and customs records formed the secondary backbone, supplemented by primary interviews with dehydration plant managers, specialty distributors, and restaurant procurement heads. Bottom-up and top-down triangulation validated volume estimates across cultivation substrate suppliers and foraging cooperatives.
Bottom-up modeling aggregated segment-level inputs across product type, end user, packaging format, and distribution channel dimensions, with top-down cross-checks against national production statistics. CAGRs were derived from trend extrapolation across the projection horizon, incorporating shiitake cultivation yield data, freeze-drying equipment capacity additions, and organic certification growth trajectories.
Wild harvest volatility, regulatory equivalency negotiation delays, and energy cost fluctuations are the dominant revision risks. Deviation in EFSA mycotoxin limit enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Vegetable Grader Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
North America Peas Market
Vegetables
Carrots and Turnips Market
Vegetables
Global Indoor Plant Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Dry Onion Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Yams Market
Vegetables
Yam Products Market
Vegetables
Garlic Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Sprouts Market
Vegetables
North America Sweet Potatoes Market