
 South America Peas Market | 2026-2036
South America Peas Market Size, Share, and Industry Trends Forecast 2026-2036
South America Peas Market Analytics
Plant-based protein demand from frozen food manufacturers is realigning pea procurement across South America. Cargill Inc. leverages its continental grain handling infrastructure to secure origination advantages in Argentina and Brazil. AGT Food and Ingredients anchors its position through specialty pulse fractionation capabilities that serve export markets. Olam International competes via integrated supply chains linking Andean smallholders to international offtake agreements.
Peas are cool-season leguminous crops yielding seeds with protein content ranging from 20-25% by dry weight, cultivated for direct consumption and fractionation into protein isolates, starches, and fibers. Green peas retain dominant volume share in retail canned and frozen channels, while yellow peas command premium positioning in ingredient manufacturing for plant-based meat analogues. Pouch packaging for ready-to-eat snacks represents the fastest-growing format, though bulk shipments to industrial processors capture the largest margin pool.
ANVISA in Brazil and Argentina's national food safety authority enforce pesticide residue thresholds and labeling standards that determine market access for processed pea products. Brazil's agricultural biotechnology regulator evaluates gene-edited and conventional variety approvals that directly shape seed availability and yield trajectories. Stakeholders must monitor evolving Mercosur sanitary protocols and national bioeconomy frameworks that will determine competitive positioning in protein ingredient trade.
Market Dynamics
Plant-based protein demand from frozen food manufacturers is compressing traditional commodity trading margins and forcing processors toward captive fractionation capacity. Brazil's updated agricultural biotechnology regulations and Argentina's Mercosur trade protocols are accelerating variety approval timelines while reshaping cross-border seed flows.
Growth Catalysts
- Biotechnology frameworks:Brazil's gene-edited variety approvals under CTNBio protocols are expanding seed availability for protein-optimized cultivars. Argentine breeders leverage these regulatory alignments to accelerate field trials.
- Ingredient manufacturing pull:Plant-based meat analogue producers are contracting directly with Pampas processors for yellow pea protein isolates, bypassing commodity exchanges.
- Rotation economics:Southern Brazil's soybean-pea belts are expanding planted area as growers capture nitrogen-fixation benefits and premium protein contracts.
Market Restraints
- Input cost volatility:Fertilizer price swings tied to natural gas markets compress margins for contract growers in Rio Grande do Sul.
- Supply concentration risk:Bulk handling infrastructure for pulse exports concentrates at Rosario and Paranaguá terminals, creating single-point vulnerabilities.
- Technical limitation:Protein extraction yields from South American cultivars lag Canadian benchmarks, constraining isolate competitiveness in export markets.
Strategic Opportunities
- Underpenetrated processing:Colombia's nascent pulse fractionation sector offers first-mover positioning for equipment suppliers and offtake partners.
- Emerging application:Pet food protein fortification is opening specialty contracts for pea fiber and starch co-products from Argentine mills.
- Regulatory tailwind:Brazil's national bioeconomy framework is channeling development finance toward domestic protein ingredient capacity.
Industry Challenges
- Skill gaps in fractionation:Specialized protein extraction technicians remain scarce across the continent, slowing plant commissioning timelines.
- Certification complexity:ANVISA's evolving pesticide residue protocols for processed ingredients are extending product registration cycles by 8-14 months.
- Integration friction:Legacy grain handling systems at Brazilian cooperatives require retrofitting to segregate food-grade pulses from feed channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Peas Market |
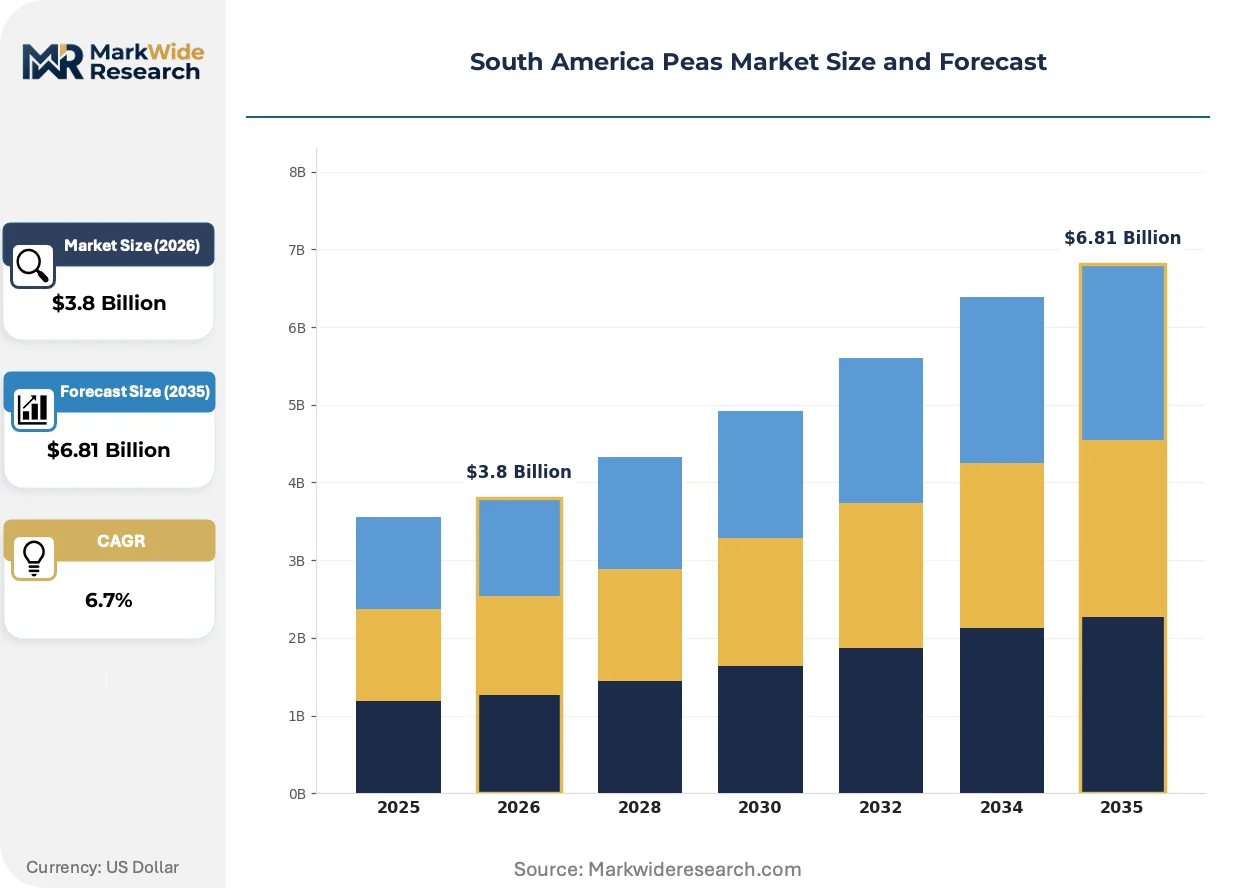
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Peas, Yellow Peas, Snow Peas, Sugar Snap Peas End Use: Canned Goods, Frozen Foods, Snacks, Soups Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Supermarkets, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | Cargill Inc., Olam International, AGT Food and Ingredients, Groupe Limagrain, BASF, Syngenta, Roquette Freres, Glanbia Plc, Cosucra-Groupe Warcoing, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Peas Market Evolving Landscape
Processing technology and regulatory alignment are compressing traditional trading structures while opening new value capture points for integrated operators. Three developments are restructuring competitive positioning across the continent.
Precision fractionation technology is decentralizing protein isolate production away from coastal export terminals. Mid-scale processors in Argentina's Santa Fe province are deploying modular extraction units that co-locate with origination clusters. Food manufacturers in São Paulo's industrial corridor are securing supply through direct tolling arrangements rather than commodity merchants.
ANVISA's updated biotechnology guidelines for gene-edited crops are compressing variety approval timelines from 48 to 18 months. Argentine seed developers are leveraging regulatory reciprocity under Mercosur protocols to synchronize field trials across both markets. Protein-optimized cultivars with enhanced amino acid profiles are reaching commercial scale two growing seasons earlier than anticipated.
Buyer concentration among multinational ingredient purchasers is forcing originators toward long-term offtake structures with embedded quality premiums. Traditional spot-market trading at Rosario terminals is contracting as Brazilian and Argentine processors lock in multi-year protein supply commitments. This shift is most visible in contracts linking Pampas growers directly to European plant-based meat facilities, bypassing historical merchant intermediaries entirely.
South America Peas Market Segmentation
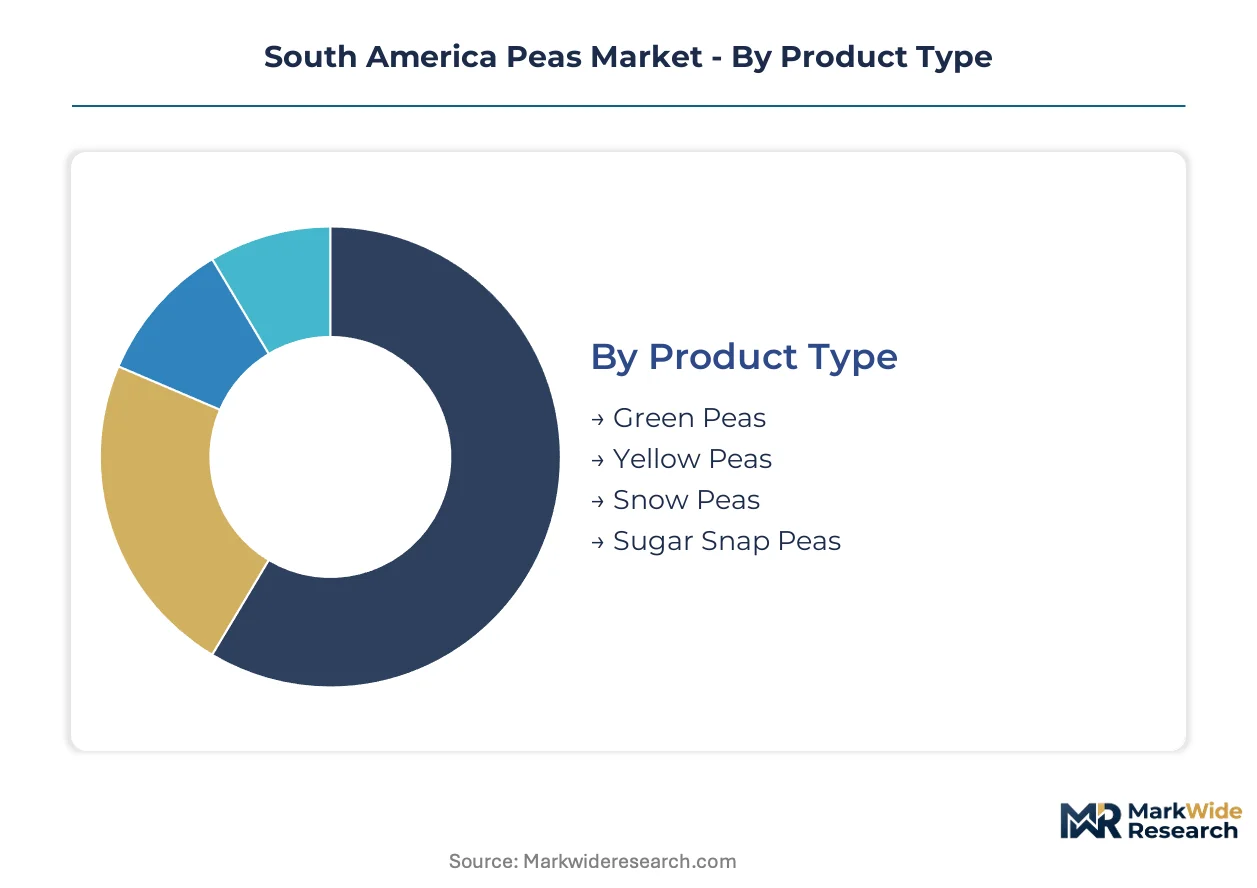
Pea segmentation across South America reflects divergent margin pools between commodity bulk flows and high-value ingredient channels. Understanding these splits enables processors to align fractionation investments with the most profitable demand corridors.
Product Type:
Volume concentrates in commodity cultivars while premium capture shifts toward protein-optimized varieties.
- Green Peas:These retain 20-25% protein by dry weight and dominate retail canned and frozen channels across Brazilian supermarkets. Argentine Pampas processors supply São Paulo's frozen food manufacturers with standardized grades under seasonal contract structures.
- Yellow Peas:Higher starch content and superior fractionation yields position these for plant-based meat analogue production. Brazilian southern soybean-pea rotation belts are expanding planted area specifically to capture premium protein isolate contracts from European offtakers.
- Snow Peas:Edible-pod varieties serve fresh export markets through Chilean and Peruvian air freight corridors to North American retail.
- Sugar Snap Peas:These hybrid cultivars bridge fresh and lightly processed segments, with Colombian highland growers supplying Andean urban markets.
Today's leader: Yellow Peas. Tomorrow's challenger: Green Peas as fractionation technology improves.
End Use:
Application channels separate stable retail volumes from rapidly expanding ingredient manufacturing pull.
- Canned Goods:Mature demand from Brazilian and Argentine retail chains maintains steady offtake for standard green pea grades. ANVISA's updated pesticide residue protocols are extending product registration cycles for new supplier entrants.
- Frozen Foods:IQF processing capacity concentrates in Rio Grande do Sul and Buenos Aires provinces. Plant-based protein demand from frozen food manufacturers is realigning procurement patterns toward direct processor relationships.
- Snacks:Roasted and extruded formats are climbing fastest among urban Brazilian consumers. Pouch packaging for ready-to-eat applications commands margin premiums over traditional formats.
- Soups:Dehydrated and ready-to-serve formulations draw split yellow pea supplies from Argentine mills into Mercosur distribution networks.
Ingredient manufacturing pull is steepest in Frozen Foods; Snacks are gaining share fastest in retail value per kilogram.
Packaging Type:
Format selection tracks the distance between origin clusters and final consumption points.
- Bags:Polyethylene and paper-based retail formats dominate Brazilian supermarket shelves for dried pea varieties. Argentine cooperatives are retrofitting legacy grain handling systems to segregate food-grade bagged product from feed channels.
- Cans:Tinplate and aluminum containers preserve green peas for traditional retail channels across South America. This format maintains stable volume but faces margin compression from flexible alternatives.
- Pouches:Flexible retort and stand-up formats are expanding most quickly in Brazilian snack and ready-to-eat segments. São Paulo-based converters are investing in high-barrier film capacity to capture this shift.
- Bulk:Containerized shipments to industrial processors capture the largest absolute margin pool. Rosario and Paranaguá terminals concentrate bulk handling infrastructure for pulse exports.
Margin concentration favors Bulk for processors; Pouches deliver the steepest growth trajectory in retail-facing formats.
Distribution Channel:
Channel structure determines whether originators capture commodity spreads or ingredient premiums.
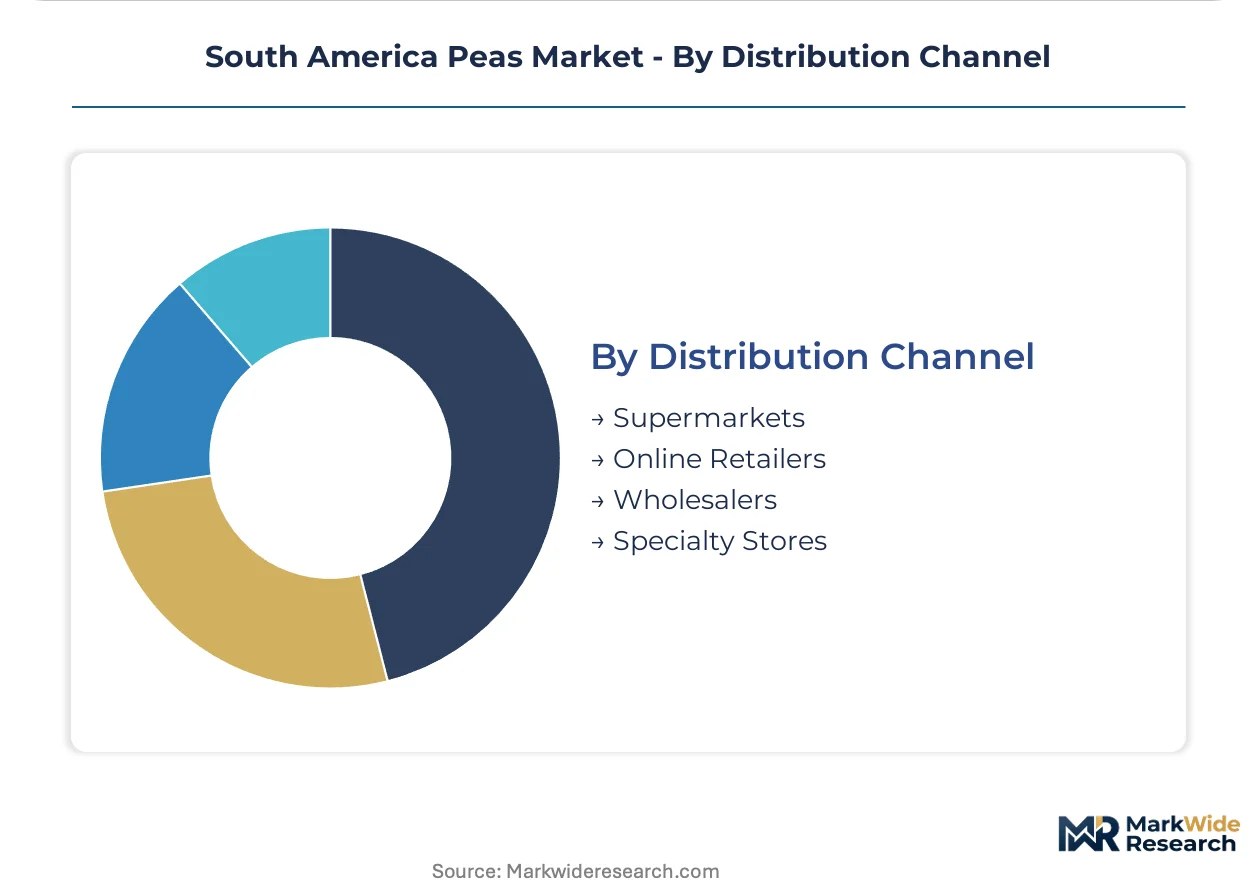
- Supermarkets:Brazilian chains like Carrefour Brasil and GPA dominate packaged pea retail across the continent's largest consumer market. These buyers are consolidating procurement toward fewer, larger suppliers with fractionation capabilities.
- Online Retailers:Mercado Libre and specialized health food platforms are opening specialty channels for organic and protein-fortified pea products. Delivery logistics favor lightweight pouch formats over traditional cans.
- Wholesalers:Traditional merchants at Rosario and São Paulo wholesale terminals are losing share to direct processor-manufacturer contracts. Bulk spot-market trading is contracting as long-term offtake structures embed quality premiums.
- Specialty Stores:Natural product retailers in Buenos Aires and Santiago serve gluten-free and plant-based diet segments with premium-priced imported and domestic pea protein isolates.
Direct contracting is displacing Wholesalers in volume; Online Retailers are expanding most quickly in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southern soybean-pea rotation belts anchor continental production volume, with Argentina's Pampas processing corridor commanding premium protein isolate flows. Cross-border seed movements accelerate under Mercosur regulatory reciprocity. Colombian and Chilean highland clusters are emerging as specialty export origination points.
Brazil
Southern soybean-pea rotation belts in Rio Grande do Sul and Paraná are expanding planted area to capture nitrogen-fixation benefits and premium protein contracts. CTNBio's compressed gene-edited variety approval timelines are accelerating seed availability for protein-optimized cultivars. São Paulo's industrial corridor hosts direct tolling arrangements between processors and food manufacturers, bypassing traditional commodity merchants.
Argentina
Pampas processors are contracting directly with European plant-based meat facilities for yellow pea protein isolates, embedding multi-year quality premiums. The national food safety authority enforces pesticide residue thresholds that determine market access for processed exports. Rosario terminals concentrate bulk handling infrastructure, though spot-market trading contracts as long-term offtake structures displace historical merchant intermediaries.
Colombia
Highland growers in the Andean region are supplying urban markets with sugar snap peas while nascent pulse fractionation capacity offers first-mover positioning. The national bioeconomy framework channels development finance toward domestic protein ingredient capacity. Bogotá-based equipment suppliers are deploying modular extraction units that co-locate with origination clusters.
Chile
Fresh export corridors leverage air freight infrastructure to deliver snow peas to North American retail markets. Specialty stores in Santiago serve gluten-free and plant-based diet segments with premium-priced imported and domestic pea protein isolates. Valparaíso port facilities are retrofitting legacy grain handling systems to segregate food-grade pulses from feed channels.
South America Peas Market Competitive Landscape
Capacity expansion dominates the current landscape as processors build captive fractionation assets to capture ingredient premiums. The vendor base separates into three tiers: multinational grain merchants with continental handling infrastructure, specialty pulse processors with extraction capabilities, and integrated ingredient manufacturers serving plant-based meat channels. Strategic archetypes include origination-heavy traders seeking backward integration into processing, and equipment-led fractionation specialists licensing technology to regional mills. M&A activity and long-term offtake contracting represent the two dominant competitive moves reshaping market structure.
Among multinational grain merchants, Cargill Inc. and Olam International exemplify the origination-to-processing archetype, leveraging continental infrastructure to secure origination advantages while building direct relationships with food manufacturers. AGT Food and Ingredients occupies a position within the specialty pulse processor tier, anchoring its competitive stance through fractionation capabilities that serve export markets. These three entities represent distinct strategic vectors: merchant infrastructure dominance, integrated supply chain control, and ingredient manufacturing specialization.
| Leading Market Players |
|---|
| Cargill Inc. |
| Olam International |
| AGT Food and Ingredients |
| Groupe Limagrain |
| BASF |
| Syngenta |
| Roquette Freres |
| Glanbia Plc |
| Cosucra-Groupe Warcoing |
| Others |
Value Network & Pricing Analysis
Family-owned cooperatives in Rio Grande do Sul and Paraná anchor origination volumes, channeling harvests through Rosario and Paranaguá terminals where bulk handling infrastructure concentrates pricing power among a handful of export merchants. Their collective discipline in withholding supply during price troughs stabilizes farmgate returns while forcing processors toward direct contracting to secure protein-optimized cultivars.
Pricing Analysis
Distributor margins in Brazilian supermarket channels compress farmgate premiums by 35-45% before retail shelf placement, whereas direct-to-processor contracts for yellow pea protein isolates bypass these layers entirely. Pricing stratifies across organic-certified premiums, standard food-grade contracts, and feed-channel discounts, with ANVISA's residue protocols determining tier eligibility. Cost compression in commodity bulk flows intensifies as Argentine Pampas processors compete for European offtake agreements. Frozen food manufacturers exhibit lowest price sensitivity due to embedded protein premiums, while canned goods retailers drive hardest bargain on standard green pea grades.
Supply Chain Analysis
Brazil's national bioeconomy framework channels development finance toward domestic fractionation capacity, reshaping sourcing patterns away from raw export dependency toward captive processing assets. Geographic supply concentration centers on Brazil's southern rotation belts, Argentina's Pampas corridor, and Colombia's emerging Andean clusters. Raw material flows draw from gene-edited seed stocks, nitrogen-fixation inputs, and specialized protein-optimized cultivars. Single-source vulnerability concentrates at Rosario and Paranaguá bulk terminals, where weather disruptions or labor actions cascade through export schedules. Distribution runs through direct tolling arrangements between Santa Fe processors and São Paulo food manufacturers, displacing traditional spot-market merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as plant-based protein demand from frozen food manufacturers locks in multi-year offtake structures that insulate processors from commodity volatility.
For Market Incumbents: Anticipate margin compression from Colombian fractionation entrants by securing backward integration into gene-edited seed development through CTNBio-aligned breeders. Prioritize certification investment for ANVISA's evolving residue protocols to extend registration cycles ahead of competitor product launches. For New Entrants and Emerging Players: E-commerce platforms serving Mercado Libre's health-conscious urban consumers offer lowest customer acquisition cost for organic and protein-fortified pea products. Target Colombia's nascent pulse fractionation sector for equipment supply partnerships, leveraging Bogotá-based modular extraction deployments as reference installations for Andean expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among Argentine Pampas processors lacking direct European offtake relationships but possessing installed fractionation capacity. Five-to-ten-year viability hinges on protein extraction yield convergence with Canadian benchmarks. Monitor CTNBio approval velocity for gene-edited cultivars as inflection indicator for seed-sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Development | CTNBio's compressed approval timelines reward breeders with protein-optimized cultivar pipelines. |
| Modular Fractionation Deployment | Santa Fe processors co-locating extraction units with origination clusters capture tolling premiums. |
| Direct European Offtake Contracting | Pampas processors bypassing Rosario merchants embed multi-year quality premiums. |
| ANVISA Certification Pre-Positioning | Early residue protocol compliance extends product registration cycles against late entrants. |
| Andean Equipment Partnership | Colombian highland deployments create reference architecture for regional fractionation expansion. |
Research Methodology
Direct dialogue with Argentine seed breeders, Brazilian cooperative managers, Colombian equipment suppliers, and European plant-based meat procurement directors grounded qualitative assessments in operational reality. Secondary validation drew from CTNBio variety approval databases, ANVISA pesticide residue bulletins, Mercosur trade flow statistics, and SEC filings of multinational grain merchants. Bottom-up acreage estimates from Rio Grande do Sul farm surveys triangulated against top-down protein demand projections from São Paulo food manufacturers.
Bottom-up modeling segmented volume across green versus yellow cultivars, canned versus frozen versus ingredient manufacturing end uses, and bag versus pouch versus bulk packaging formats. Top-down demand calibration incorporated nitrogen-fixation economics in soybean-pea rotations and protein isolate contract premiums from European offtakers. CAGRs derived from regression analysis of planted area expansion rates against fractionation capacity commissioning timelines across the projection horizon.
The model assumes a particular technology adoption path for precision fractionation; alternative pathways for modular extraction scalability would alter the outlook for mid-scale processor competitiveness. Forecasts reflect assumptions about CTNBio regulatory reciprocity and Mercosur sanitary protocol alignment that geopolitical friction could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dried Peas Market
Vegetables
Global Mushroom Market
Vegetables
Greenhouse Produce Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Squash Market
Vegetables
United States Microgreens Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Fresh Vegetables Market
Vegetables
Microgreens Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Butternut Squash Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Vegetable Grader Market