
 Sprouts Market | 2026-2036
Sprouts Market Size, Share, and Industry Trends Forecast 2026-2036
Sprouts Market Analytics
Buyer concentration across the foodservice and retail landscape is rebalancing as regional grocery cooperatives and specialty chains dilute the historic dominance of conventional supermarkets. Sprouts Farmers Market anchors its position through a produce-centric store format that dedicates disproportionate shelf space to living greens and microgreens. Whole Foods Market differentiates via rigorous sourcing standards that exclude certain sprout varieties from conventional supply chains. Natural Grocers by Vitamin Cottage competes on price transparency and certified organic commitments that resonate with core sprout purchasers.
Sprouts are germinated seeds or very young seedlings harvested before true leaves develop, typically grown in controlled humidity environments of 60-70% and consumed raw or lightly cooked for concentrated nutrient density. The USDA and FDA jointly regulate sprout safety through specific guidance documents addressing Salmonella and E. coli risks inherent to the warm, moist growing conditions. Organic Vegetables and Legumes dominate product type revenue due to established consumer familiarity and versatile culinary applications, while Whole Grains represent the fastest-expanding category as sprouted grain breads and cereals gain shelf space in conventional grocery. Health Food Stores and Grocery Stores capture the majority of volume, though Online Retail channels are accelerating as direct-to-consumer subscription models reduce spoilage risk through rapid fulfillment.
The FDA's Sprout Safety Alliance guidelines mandate hazard analysis and preventive controls for domestic and imported sprout operations, elevating compliance costs for smaller growers. The USDA National Organic Program certification requirements create a dual-track market where certified organic sprouts command persistent premiums over conventional alternatives. Stakeholders must monitor evolving state-level labeling disputes around hydroponic and aeroponic production methods as these techniques capture share from traditional soil-based germination.
Market Dynamics
The EU's Farm to Fork Strategy is compressing pesticide residue thresholds for fresh produce, forcing sprout growers toward controlled-environment agriculture and accelerating capital deployment into vertical farming infrastructure across North America and Europe.
Growth Catalysts
- EU Green Deal agricultural mandates:The Farm to Fork Strategy tightens chemical residue limits, pushing commercial sprout operations into hydroponic and aeroponic systems that bypass soil-borne contamination risks entirely.
- Millennial and Gen Z household meal integration:Health-conscious younger demographics in the United States and Canada are embedding raw sprouts into daily breakfast and lunch routines, expanding addressable consumption occasions beyond traditional garnish applications.
- Controlled-environment agriculture:Vertical farming clusters in California and the Pacific Northwest achieve year-round production consistency, reducing weather-dependent supply volatility that historically constrained sprout availability.
Market Restraints
- Input cost volatility:Organic seed prices fluctuate with commodity grain markets, compressing margins for certified organic sprout producers who cannot substitute conventional seed stocks without losing certification.
- Supply concentration risk:Domestic sprout production clusters heavily in California's Central Valley and the Pacific Northwest, creating geographic vulnerability to drought, wildfire smoke, and regional labor disruptions.
- Regulatory friction:The FDA's Sprout Safety Alliance guidelines mandate hazard analysis and preventive controls that elevate compliance costs disproportionately for smaller growers with limited quality assurance infrastructure.
Strategic Opportunities
- Underpenetrated European markets:Germany and the Netherlands show nascent sprout consumption relative to North American per-capita levels, presenting expansion terrain for controlled-environment producers meeting EU organic certification standards.
- Direct-to-consumer subscription channels:Online retail models with rapid fulfillment networks reduce spoilage risk and capture margin that conventional grocery distribution currently extracts from sprout growers.
- Sprouted grain applications:Whole grain sprouts are displacing conventional flour in artisanal bread and cereal formulations, opening food manufacturing partnerships beyond fresh produce retail.
Industry Challenges
- Microbiological safety expertise gap:The warm, moist conditions optimal for sprout germination create inherent Salmonella and E. coli harboring risks, requiring specialized food safety personnel that smaller operations struggle to recruit and retain.
- Certification timeline compression:USDA National Organic Program certification demands multi-year transition periods for soil-based operations, delaying revenue recognition for growers converting from conventional production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprouts Market |
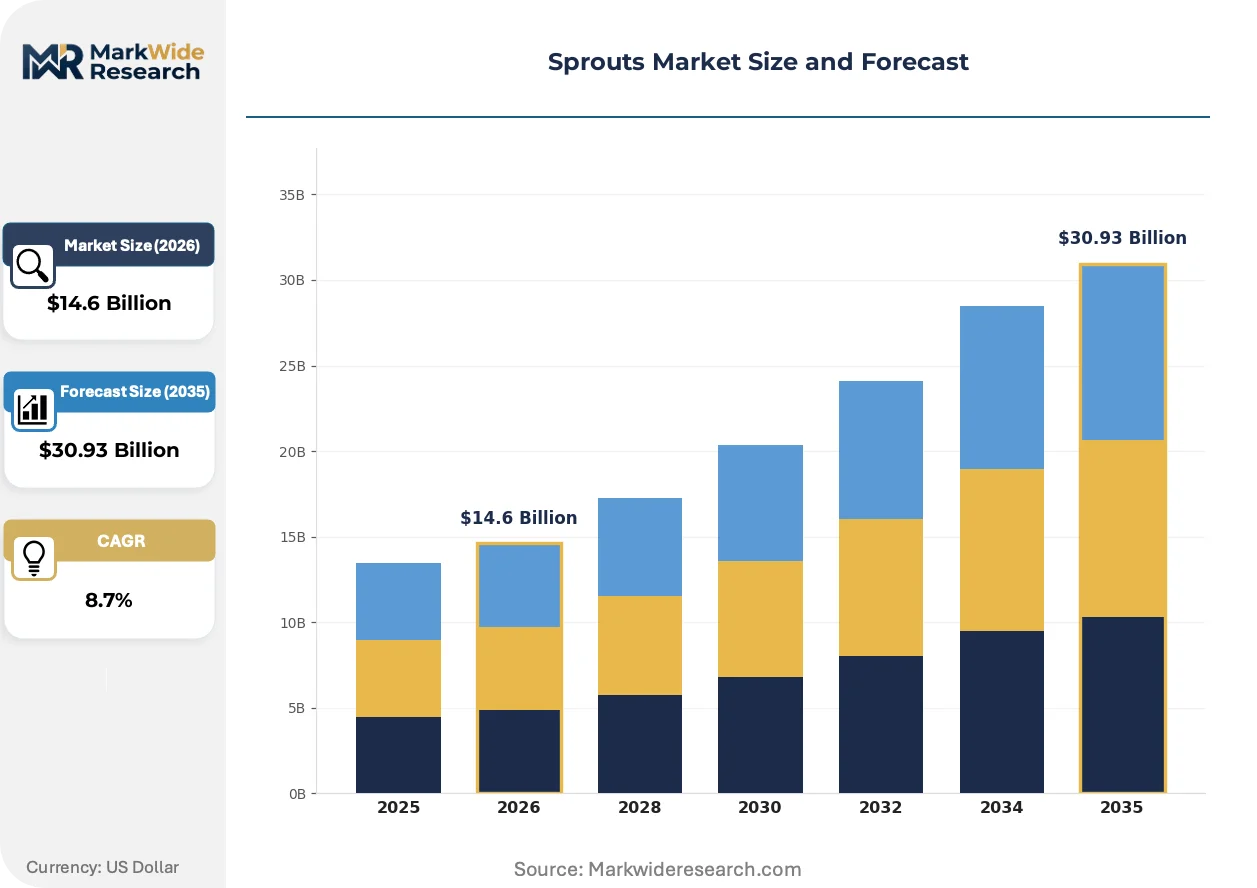
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $30.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Vegetables, Legumes, Whole Grains, Nuts Distribution Channel: Online Retail, Grocery Stores, Farmers' Markets, Health Food Stores Packaging Type: Reusable Bags, Biodegradable Containers, Glass Jars, Eco-Friendly Wraps Customer Type: Health Enthusiasts, Families, Eco-Conscious Consumers, Culinary Professionals |
| Companies Covered | Sprouts Farmers Market, Whole Foods Market, Natural Grocers by Vitamin Cottage, Albertsons Companies, Performance Food Group, The Kraft Heinz Company, Vital Farms, BJ's Wholesale Club, Chewy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprouts Market Evolving Landscape
Technology convergence between automation and controlled-environment agriculture is restructuring how sprout producers achieve scale, while regulatory tightening and shifting procurement models reshape competitive positioning across the value chain.
Automated seeding and harvesting robotics is modularizing production workflows in vertical farming facilities. Mid-scale sprout operations in the United States are deploying these systems to reduce labor dependency and achieve lot-level traceability. The technology is modularizing capital requirements, enabling phased facility expansion without full-scale upfront investment.
The FDA's Sprout Safety Alliance guidelines are elevating preventive control mandates for domestic and imported operations alike. Compliance documentation burdens now consume substantial managerial bandwidth previously directed toward yield optimization. Fresh sprout segments serving foodservice buyers face the steepest audit frequency increases, driving consolidation toward integrated operations with captive laboratory testing capacity.
Buyer concentration among regional grocery cooperatives is fragmenting historical supermarket dominance over sprout distribution. Specialty chains and natural food retailers now capture disproportionate volume growth, particularly in California and Pacific Northwest metropolitan corridors. This channel rotation is most visible in urban wholesale markets where vertical farming clusters maintain direct relationships with institutional buyers, bypassing traditional produce distributors entirely.
Sprouts Market Segmentation
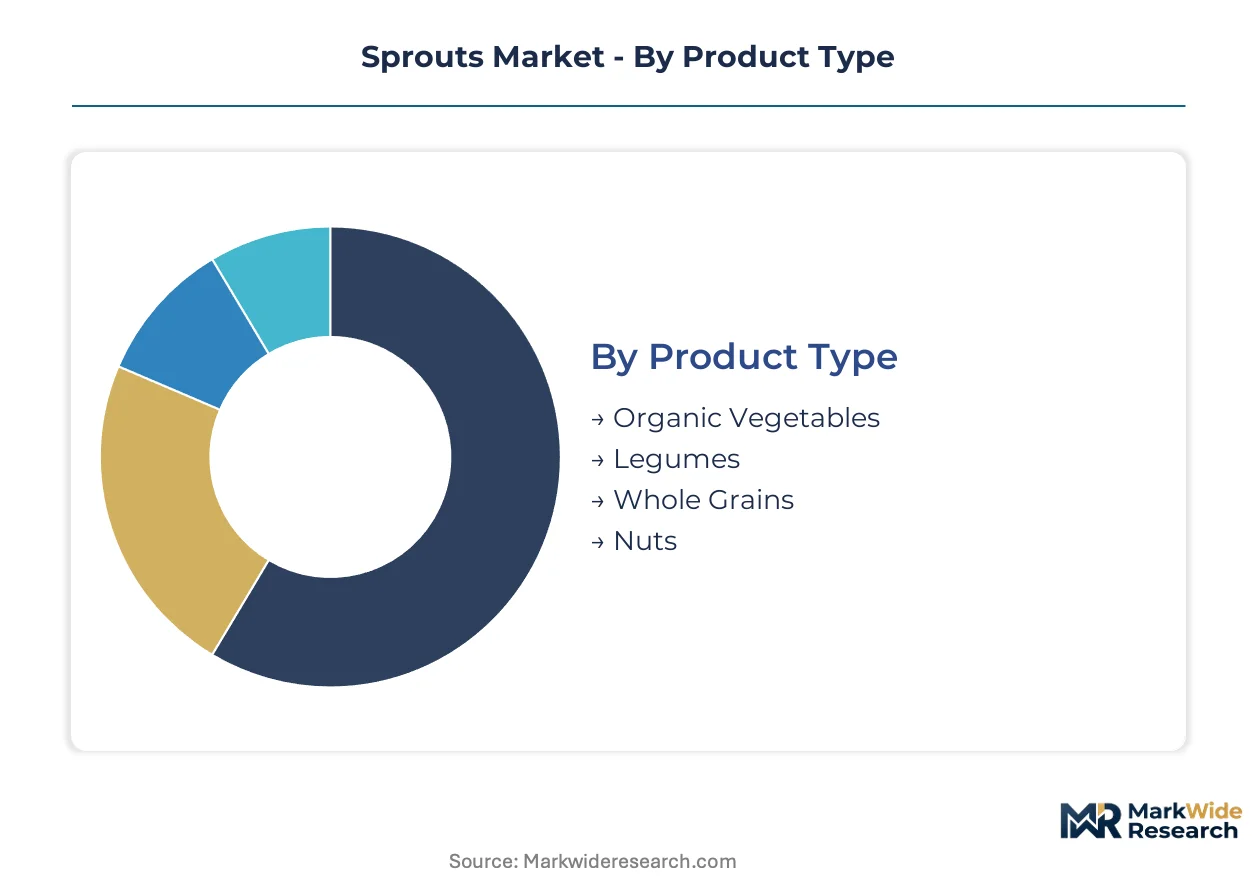
Sprout producers navigate divergent technical specifications across product categories while distribution and packaging choices directly shape spoilage risk and margin capture. Customer segmentation reveals distinct purchasing rhythms between daily-use households and intermittent bulk buyers.
Product Type:
Seed composition and germination protocols define the technical axis, with moisture sensitivity and harvest windows varying substantially across botanical families.
- Organic Vegetables:Broccoli, alfalfa, and radish sprouts dominate commercial output, harvested at 3-5 days when glucosinolate concentrations peak. Demand clusters in California metropolitan wholesale markets where Sprouts Farmers Market and Whole Foods Market maintain direct procurement relationships with vertical farming clusters.
- Legumes:Mung bean and lentil sprouts require extended germination cycles of 5-7 days and higher ambient temperatures, creating distinct Salmonella harboring risks that FDA Sprout Safety Alliance guidelines address through mandatory seed disinfection protocols. Foodservice buyers in the Pacific Northwest anchor volume for this segment.
- Whole Grains:Sprouted wheat, barley, and quinoa serve flour milling and cereal manufacturing applications. Artisanal bread producers in Germany and the Netherlands are expanding offtake as sprouted grain formulations displace conventional flour in premium product lines.
- Nuts:Almond and pumpkin seed sprouts occupy niche positioning due to higher input costs and shorter shelf stability. Raw food practitioners and specialty nutrition retailers in North American urban centers sustain this segment.
Mature deployment sits with Organic Vegetables. Newer deployment is concentrated in Whole Grains.
Distribution Channel:
Channel selection determines temperature control handoff points and traceability documentation burdens, with direct models capturing margin that traditional wholesale extracts.
- Online Retail:Subscription-based direct-to-consumer models with rapid fulfillment networks reduce spoilage risk through compressed delivery windows. These channels capture recurring revenue from health enthusiasts seeking consistent supply of living microgreens.
- Grocery Stores:Conventional supermarket produce sections and specialty chains like Natural Grocers by Vitamin Cottage maintain refrigerated display infrastructure. California and Pacific Northwest retail corridors concentrate volume for this channel.
- Farmers' Markets:Localized same-day harvest sales eliminate cold chain complexity while commanding price premiums from eco-conscious consumers prioritizing provenance verification.
- Health Food Stores:Independent retailers and cooperative buying networks emphasize certified organic provenance and living product formats. These outlets serve culinary professionals and dedicated health enthusiasts with technical product knowledge.
Volume concentrates in Grocery Stores. Margin expansion is climbing the fastest in Online Retail.
Packaging Type:
Material specifications govern moisture retention, gas exchange rates, and end-of-life disposal pathways, with regulatory pressure on single-use plastics reshaping procurement decisions.
- Reusable Bags:Breathable mesh or perforated designs accommodate continued respiration of living sprouts. Zero-waste retail cooperatives in Germany and the Netherlands favor this format for bulk dispensing systems.
- Biodegradable Containers:Molded fiber or PLA-based clamshells serve prepared sprout salads and meal kits. These formats align with EU Green Deal packaging waste directives while meeting FDA food contact substance requirements.
- Glass Jars:Living product presentation in transparent vessels supports premium positioning at farmers' markets and specialty retailers. Higher unit costs limit scale in conventional grocery.
- Eco-Friendly Wraps:Beeswax-coated cloth or cellulose-based films serve artisanal producers emphasizing compostable end-of-life pathways. Limited barrier properties constrain shelf life extension applications.
Scale deployment favors Biodegradable Containers. Emerging adoption clusters in Reusable Bags.
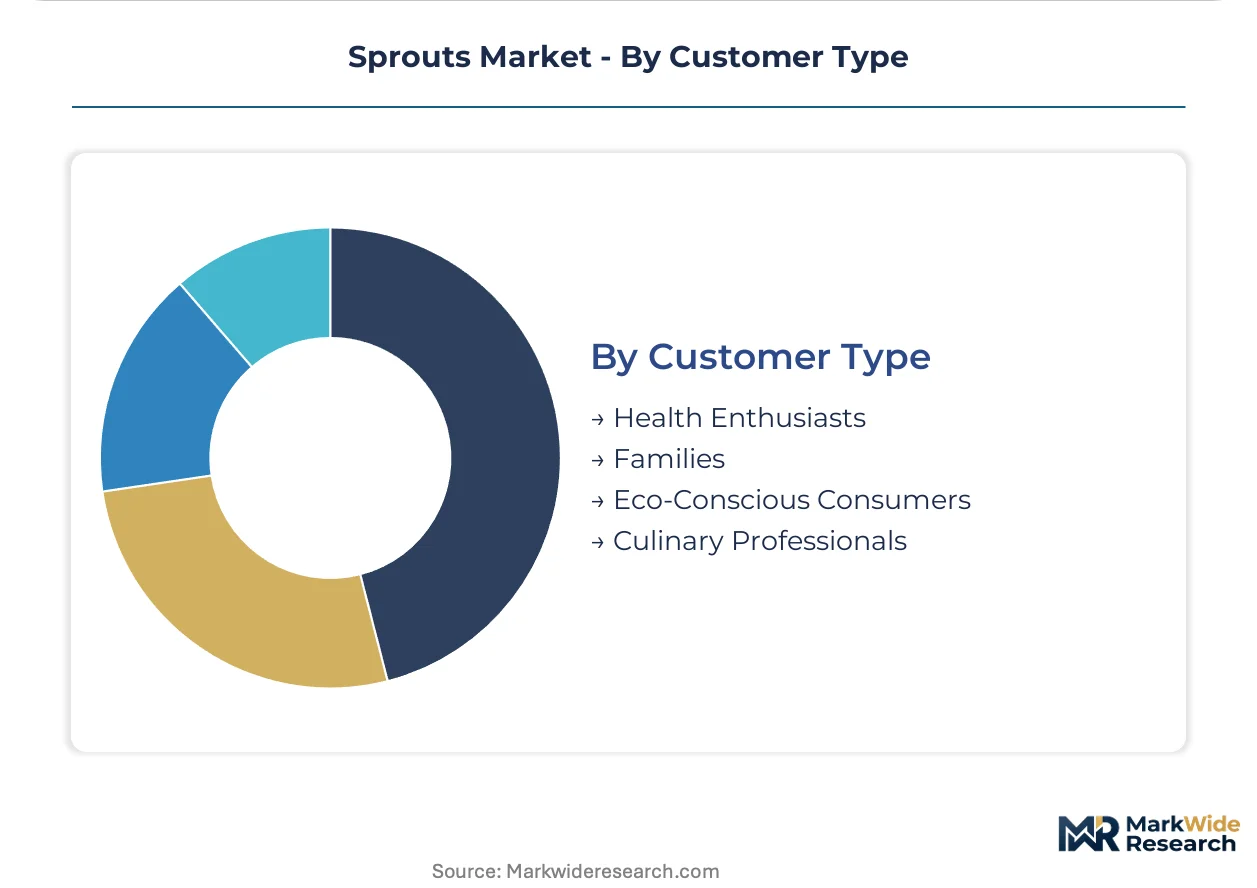
Customer Type:
Purchasing frequency and technical sophistication vary sharply, with professional users demanding lot-level traceability that casual consumers bypass.
- Health Enthusiasts:Daily consumers integrating raw sprouts into breakfast and lunch routines, prioritizing nutrient density metrics and organic certification. Subscription retention rates exceed conventional grocery for this segment.
- Families:Weekly purchasers seeking versatile ingredients for multiple meal applications. Price sensitivity drives private label acceptance in conventional supermarket channels.
- Eco-Conscious Consumers:Provenance-focused buyers evaluating packaging waste, food miles, and growing method transparency. Farmers' market direct sales and zero-waste retail cooperatives serve this segment.
- Culinary Professionals:Restaurants, catering operations, and food manufacturers requiring consistent quality specifications and documented food safety compliance. These buyers anchor contract growing arrangements with vertical farming operations.
Established penetration rests with Health Enthusiasts. Steepest expansion trajectory is occurring among Culinary Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley supplies the seed stock and vertical farming infrastructure that anchors North American sprout production capacity. The state's controlled-environment agriculture clusters serve metropolitan wholesale buyers across the United States and Canada.
United States
Health-conscious millennials and Gen Z households in California and the Pacific Northwest embed raw sprouts into daily meal routines. The FDA's Sprout Safety Alliance guidelines mandate hazard analysis and preventive controls for domestic operations. Vertical farming clusters around Seattle and Portland achieve year-round production consistency for metropolitan wholesale buyers.
Germany
Artisanal bread producers expand offtake of sprouted wheat and barley as formulations displace conventional flour in premium product lines. The EU's Farm to Fork Strategy under the European Green Deal tightens pesticide residue thresholds for fresh produce. Zero-waste retail cooperatives in Berlin and Hamburg favor breathable mesh packaging for bulk dispensing systems.
Netherlands
Nascent per-capita sprout consumption relative to North American levels presents expansion terrain for controlled-environment producers. EFSA regulations on novel food applications govern sprouted grain ingredient approvals for manufacturing. Amsterdam metropolitan wholesale markets maintain direct procurement relationships with vertical farming operations bypassing traditional distributors.
Canada
Health food store cooperatives in Vancouver and Toronto emphasize certified organic provenance and living product formats. Health Canada and the PMRA regulate pesticide residue limits for imported fresh produce. British Columbia's vertical farming infrastructure serves cross-border metropolitan buyers in Seattle and Portland.
France
Specialty nutrition retailers in Paris and Lyon sustain niche demand for almond and pumpkin seed sprouts. The EU Green Deal packaging waste directives accelerate adoption of molded fiber and PLA-based clamshell formats. Île-de-France foodservice buyers anchor contract growing arrangements for consistent quality specifications.
Sprouts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and sprouted grain manufacturing partnerships. The vendor base spans produce-centric retail chains, diversified grocery conglomerates, and controlled-environment agriculture specialists. Three archetypes dominate: vertical farming operators with captive laboratory testing, specialty retailers with rigorous sourcing standards, and diversified food manufacturers extending into sprouted ingredient supply. Competitive moves concentrate on backward integration into seed procurement and geographic expansion into underpenetrated European markets.
Among United States-based retail specialists, Sprouts Farmers Market, Whole Foods Market, and Natural Grocers by Vitamin Cottage exemplify distinct positioning archetypes within the produce-centric segment. Sprouts Farmers Market occupies a position emphasizing living greens and microgreens shelf space allocation. Whole Foods Market represents the rigorous sourcing standards tier that excludes certain varieties from conventional supply chains. Natural Grocers by Vitamin Cottage anchors the price transparency and certified organic commitment vector resonating with core purchasers.
| Leading Market Players |
|---|
| Sprouts Farmers Market |
| Whole Foods Market |
| Natural Grocers by Vitamin Cottage |
| Albertsons Companies |
| Performance Food Group |
| The Kraft Heinz Company |
| Vital Farms |
| BJ's Wholesale Club |
| Chewy |
| Others |
Value Network & Pricing Analysis
Metropolitan wholesale buyers in California and the Pacific Northwest anchor volume procurement, locking pricing power with vertical farming clusters that bypass traditional produce distributors. This buyer concentration compresses margin capture for smaller soil-based growers while rewarding controlled-environment operators with captive laboratory testing capacity.
Pricing Analysis
Volume concentrates in conventional grocery produce sections while margin expansion accelerates through direct-to-consumer subscription channels. Three-tier pricing structure across premium certified organic, standard conventional, and economy private-label levels reflects USDA National Organic Program certification status and seed stock provenance. Pricing pressure stems from organic seed price volatility tied to commodity grain markets, squeezing certified producers unable to substitute conventional inputs. Families purchasing weekly show highest price sensitivity, whereas health enthusiasts in subscription models accept persistent premiums for living microgreen formats.
Supply Chain Analysis
Regional distribution centers in California's Central Valley and Seattle-Portland metropolitan corridors operate on hub-and-spoke patterns serving cross-border Canadian buyers. Seed stock germination draws from domestic organic grain suppliers and imported Dutch hydroponic equipment, with finished sprout distribution running through refrigerated wholesale terminals and rapid-fulfillment direct channels. Single-source vulnerability concentrates in California's Central Valley drought exposure and wildfire smoke disruption. Tariff friction on European seed imports and FDA Sprout Safety Alliance compliance documentation burdens compound logistics complexity for smaller operations lacking integrated quality assurance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Sprout Safety Alliance guidelines erect a cost-of-compliance barrier that favors incumbent players with captive laboratory testing capacity and integrated preventive controls infrastructure.
For Market Incumbents: Lock in procurement relationships with metropolitan wholesale buyers through multi-year contract growing arrangements that guarantee lot-level traceability. Expand backward integration into organic seed procurement to buffer commodity price volatility threatening margin stability. Invest in modular automation systems that reduce labor dependency while satisfying escalating audit frequency demands from foodservice buyers. For New Entrants and Emerging Players: The price-point gap between premium certified organic and economy conventional tiers offers white-space entry for mid-market positioning emphasizing transparent growing method disclosure. Target underpenetrated German and Dutch metropolitan corridors where nascent per-capita consumption lags North American benchmarks. Deploy direct-to-consumer subscription models with rapid fulfillment networks that capture margin extracted by traditional grocery distribution. For Investors and Strategic Acquirers: The window for entry favors controlled-environment agriculture specialists with vertical farming infrastructure and existing USDA National Organic Program certification. Monitor EFSA novel food application approvals for sprouted grain ingredients as inflection indicators for manufacturing partnership expansion. Long-term viability hinges on regulatory compliance moats deepening as EU Farm to Fork Strategy mandates compress pesticide residue thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Captive organic seed supply buffers commodity volatility threatening certified producer margins. |
| Direct-to-Consumer Subscription Launch | Rapid fulfillment networks reduce spoilage risk and extract margin from conventional grocery channels. |
| Automated Seeding and Harvesting Deployment | Modular robotics reduce labor dependency while achieving lot-level traceability for foodservice buyers. |
| EU Organic Certification Pathway | Farm to Fork Strategy compliance opens underpenetrated German and Dutch metropolitan wholesale markets. |
| Sprouted Grain Manufacturing Partnership | Artisanal bread producers in Germany expand offtake displacing conventional flour in premium formulations. |
Research Methodology
Multi-period observation of FDA enforcement patterns, EU Farm to Fork Strategy implementation timelines, and vertical farming capital deployment anchored the trend analysis, supplemented by interviews with sprout operation quality assurance directors, produce category buyers at specialty retail chains, controlled-environment agriculture equipment suppliers, and foodservice procurement managers. Secondary validation drew from FDA Sprout Safety Alliance guidance documents, USDA National Organic Program certification databases, EU Green Deal agricultural policy filings, and customs trade data on organic seed imports. Bottom-up facility capacity modeling and top-down consumption occasion estimation were triangulated against channel shipment data.
Segment-weighting across product type, distribution channel, packaging format, and customer archetype dimensions structured the analytical framework across the projection horizon. CAGRs were derived from trend extrapolation of millennial and Gen Z household meal integration patterns, regulatory compliance cost trajectories, and controlled-environment agriculture yield consistency improvements. Seed stock price volatility curves and metropolitan wholesale buyer concentration indices informed scenario bounds.
Inputs from FDA enforcement disclosures and EU policy implementation trackers were available through the study window; gaps in real-time vertical farming capacity utilization data introduce uncertainty bands around near-term supply projections. Forecasts reflect documented assumptions regarding regulatory timeline adherence and demographic consumption shift persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
UAE Tomato Market
Vegetables
Europe Christmas Tree Market
Vegetables
Garlic Market
Vegetables
Spain Avocado Market
Vegetables
Fresh Mushroom Market
Vegetables
Potato Market
Vegetables
Yam Products Market
Vegetables
Europe Pea Market
Vegetables
Squash Market
Vegetables
North America Microgreens Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Vegetable Chutney Market
Vegetables
Dry Onion Market
Vegetables
North America Sweet Potatoes Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Roselle Market