
 Global Indoor Plant Market | 2026-2036
Global Indoor Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indoor Plant Market Outlook
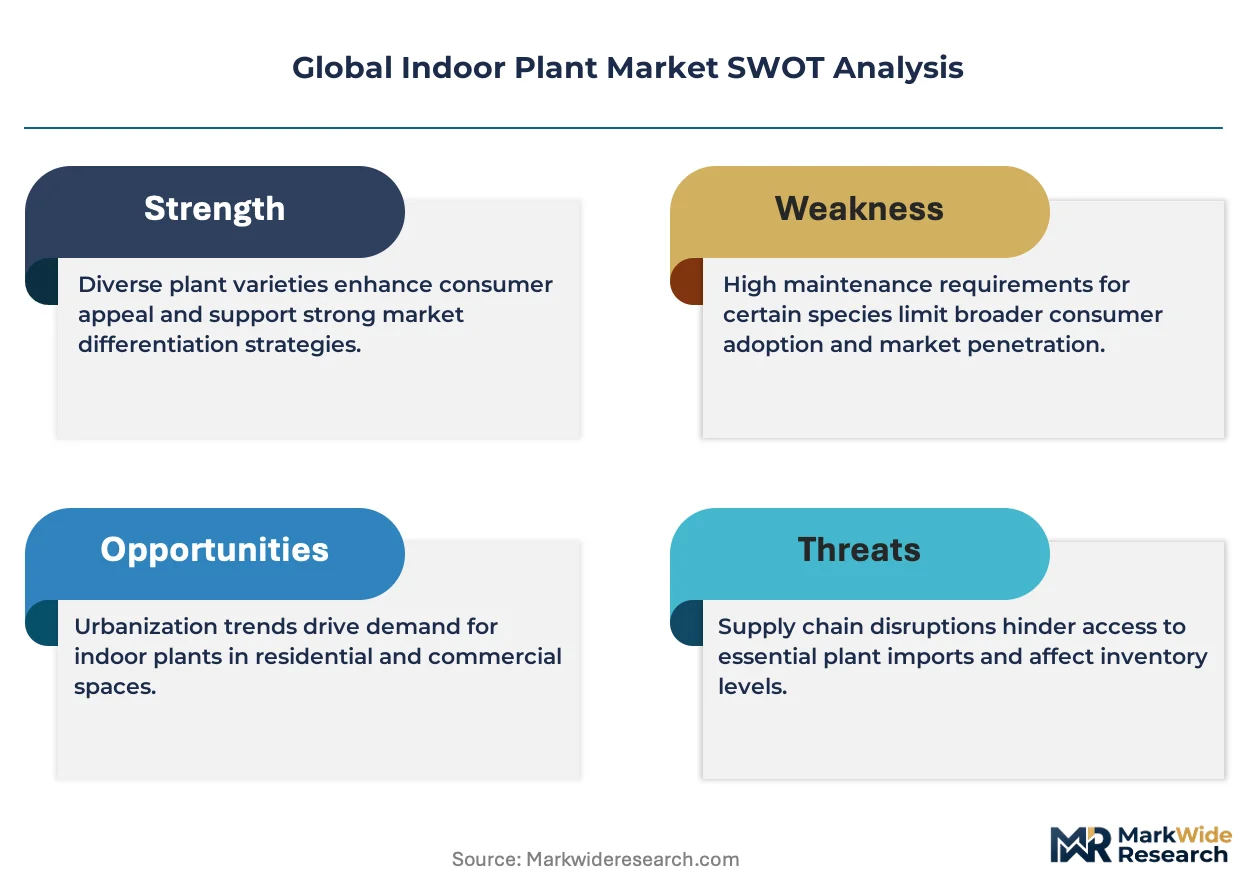
A capital-intensity divergence between automated greenhouse operators and direct-to-consumer digital nurseries is reorganizing competitive dynamics in the Global Indoor Plant Market. Costa Farms LLC leverages large-scale tissue culture labs and climate-controlled propagation facilities across multiple continents to sustain year-round supply consistency. The Sill Inc anchors its position through curated subscription models and educational content that controls customer retention in dense metropolitan corridors. Bloomscape differentiates via proprietary protective packaging that extends plant viability during last-mile delivery.
Indoor plants encompass vascular and non-vascular species cultivated within enclosed environments under artificial or filtered light, typically requiring controlled humidity between 40-60% and substrate pH ranging from 5.5 to 6.5 for optimal root nutrient uptake; their primary commercial purpose spans air quality remediation, psychological well-being enhancement, and spatial aesthetics in built environments. Foliage plants dominate volume flows due to lower light requirements and extended retail shelf life compared to flowering varieties. Succulents occupy a premium margin tier driven by millennial buyer preferences for low-maintenance specimens in compact urban dwellings. Online retail channels are capturing share fastest from garden centers as logistics networks improve live-plant handling protocols.
The EU Green Deal and REACH chemical frameworks constrain pesticide residues on imported ornamental stock, while the USDA's APHIS division enforces phytosanitary certification for cross-border shipments into the United States. Japan's METI promotes biophilic building standards that mandate living plant integration in new commercial construction above specified floor areas. Stakeholders must monitor evolving quarantine protocols and building code amendments that will determine which species gain market access and which distribution channels absorb compliance costs.
Market Dynamics
Biophilic building mandates are compressing procurement cycles for live plant installations across commercial real estate, forcing distributors to reconfigure inventory systems around just-in-time fulfillment rather than seasonal stocking patterns.
Growth Catalysts
- EU Green Deal biodiversity targets:Import requirements for ornamental species are tightening, creating competitive moats for EU-certified propagation facilities that can demonstrate phytosanitary compliance.
- Millennial urbanization patterns:Compact dwelling preferences in dense metropolitan corridors sustain demand for low-maintenance foliage varieties that tolerate artificial light and irregular watering.
- Automated greenhouse technology:Climate-controlled propagation facilities enable year-round supply consistency, reducing price volatility that historically plagued seasonal retail channels.
Market Restraints
- REACH chemical residue limits:Pesticide restrictions on imported ornamental stock force exporters to retest entire propagation cycles, extending time-to-market for new cultivar introductions.
- Live-plant logistics fragility:Temperature excursions during last-mile delivery destroy margin through replacement costs, constraining geographic expansion for direct-to-consumer operators.
- Phytosanitary certification complexity:USDA APHIS documentation requirements for cross-border shipments create administrative overhead that disadvantages smaller nursery operations.
Strategic Opportunities
- Subscription-based plant care models:Curated replacement cycles and educational content lock in metropolitan residential buyers who lack horticultural expertise.
- Japan METI biophilic construction mandates:Living plant integration requirements for new commercial buildings above specified floor areas create captive demand for installation and maintenance services.
- Protective packaging innovation:Proprietary vessel designs that extend plant viability during extended transit open cross-border e-commerce channels previously closed to living goods.
Industry Challenges
- Tissue culture technician scarcity:Large-scale propagation facilities face recruitment gaps for sterile laboratory operations, constraining capacity expansion despite capital availability.
- Quarantine protocol fragmentation:Divergent national inspection standards force exporters to maintain parallel compliance systems, elevating operational complexity for multi-country distribution networks.
- Substrate pH calibration precision:Automated irrigation systems require continuous monitoring to maintain 5.5-6.5 root-zone acidity, demanding sensor infrastructure investments that strain mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indoor Plant Market |
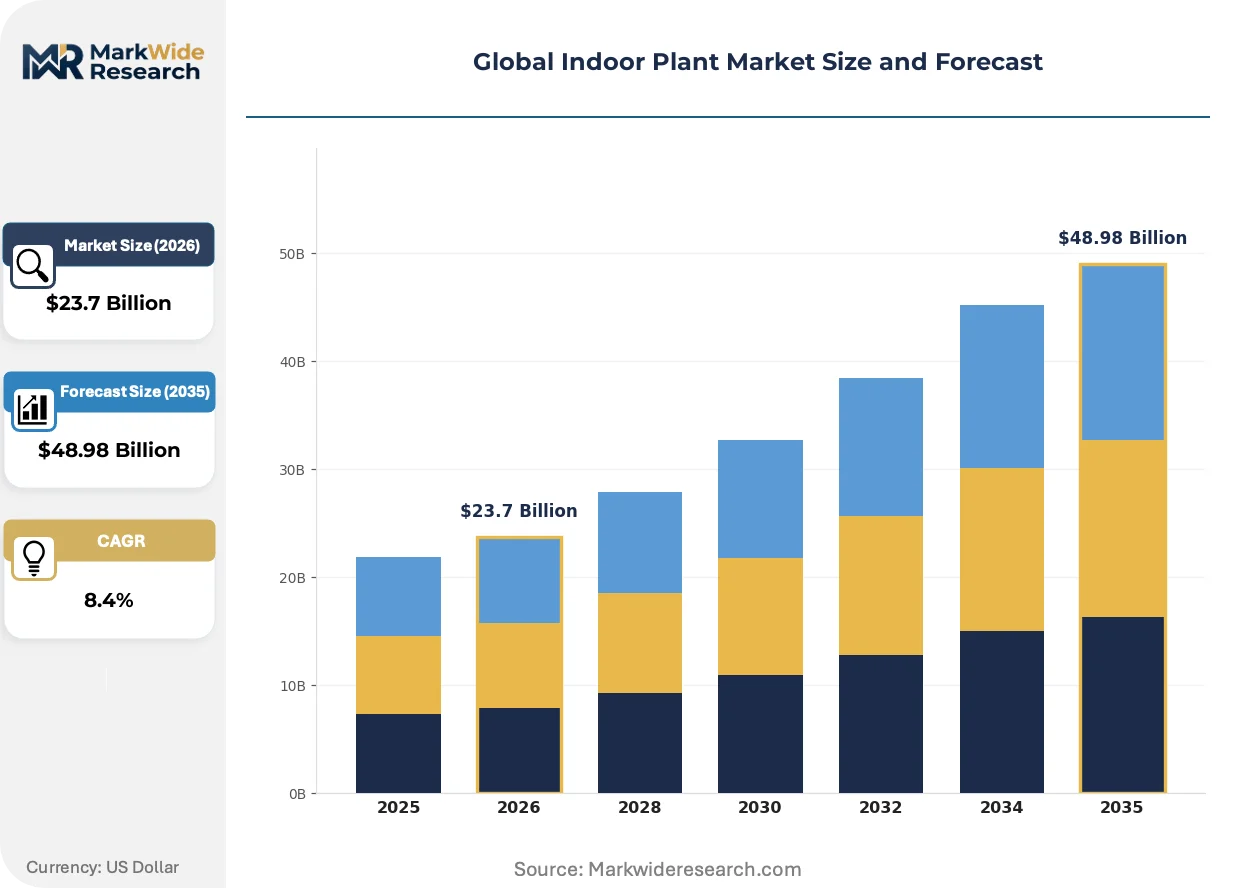
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plant Type: Flowering Plants, Foliage Plants, Succulents, Cacti Usage: Home Decor, Office Spaces, Retail Environments, Urban Gardening Distribution Channel: Online Retail, Garden Centers, Florists, Supermarkets End User: Residential Consumers, Commercial Establishments, Interior Designers, Landscaping Companies |
| Companies Covered | Costa Farms LLC, The Sill Inc, Dümmen Orange, Ambius, Beekenkamp Verpakkingen B.V, Double H Nurseries Ltd., Bloomscape, Premier Planters, Rolling Nature, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indoor Plant Market Strategic Shifts
Sensor-enabled cultivation systems are compressing the expertise gap between commercial greenhouse operators and amateur collectors, democratizing access to previously specialist-grade environmental control.
Internet-of-Things soil monitoring is supplanting calendar-based watering schedules among residential buyers. Apartment dwellers in Frankfurt, Munich, and Hamburg deploy capacitance probes that transmit moisture data to mobile applications, triggering automated irrigation or alert notifications. This technology is supplanting the traditional garden center advice model, shifting repurchase loyalty toward digital platforms that aggregate plant health telemetry.
Japan's METI biophilic building standards now mandate living plant integration in new commercial construction above specified floor areas. Property developers in Tokyo and Osaka must contract specialized horticultural maintenance firms to satisfy occupancy permits. Commercial real estate investment trusts are responding by pre-negotiating multi-year service agreements with certified installation providers.
Direct procurement from tissue culture laboratories is displacing wholesale nursery intermediaries for large-scale commercial projects. Facility managers in German office complexes now source specified cultivar volumes directly from propagation facilities, bypassing traditional distribution tiers. This pattern is most visible in Frankfurt's banking district, where standardized biophilic design specifications enable bulk purchasing contracts.
Global Indoor Plant Market Segmentation
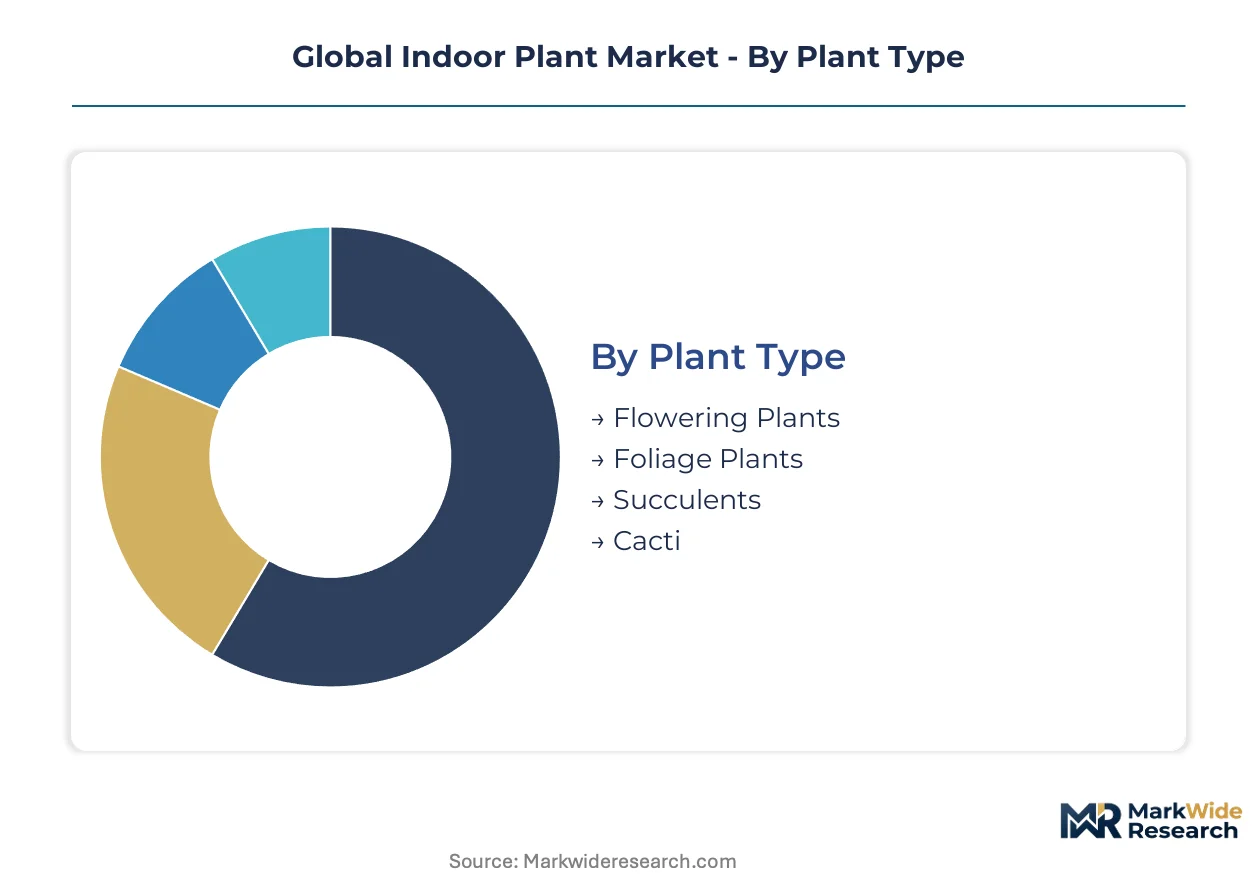
Segmentation in the Global Indoor Plant Market reveals how regulatory frameworks, distribution economics, and buyer sophistication create divergent margin structures across parallel channels. Understanding these divisions enables stakeholders to align propagation investments with the compliance and logistics requirements of specific buyer categories.
Plant Type:
REACH chemical residue limits and phytosanitary certification requirements from the USDA's APHIS division impose asymmetric compliance burdens across biological categories, favoring segments with shorter propagation cycles and lower pesticide dependency.
- Foliage Plants:These vascular species tolerate artificial light and irregular watering schedules, making them the default choice for millennial apartment dwellers in Frankfurt, Munich, and Hamburg where biophilic design standards are tightening. Demand concentrates in German commercial real estate as facility managers seek low-maintenance specimens that satisfy METI-equivalent building codes spreading across the EU.
- Succulents:Water-storing tissues enable extended retail shelf life and reduced shipping mortality, supporting premium positioning in direct-to-consumer channels. Compact urban dwellings in dense metropolitan corridors sustain demand for these low-maintenance specimens that tolerate the temperature excursions common in last-mile delivery networks.
- Flowering Plants:Higher light requirements and shorter bloom cycles constrain commercial viability outside specialized greenhouse operations.
- Cacti:Desert-adapted morphology aligns with minimalist aesthetic preferences in Japanese and German residential segments.
Foliage plants handle the majority of throughput; succulents are the fastest mover on share.
Usage:
Cost tier differentiation separates high-frequency replacement cycles in commercial installations from one-time purchases in residential settings.
- Office Spaces:Biophilic building mandates in Japan and Germany compress procurement cycles for live plant installations, forcing distributors toward just-in-time fulfillment. Property developers in Tokyo, Osaka, Frankfurt, and Hamburg pre-negotiate multi-year service agreements with certified horticultural maintenance firms to satisfy occupancy permits.
- Home Decor:Internet-of-Things soil monitoring is supplanting calendar-based watering schedules among residential buyers in dense metropolitan corridors. Capacitance probes transmitting moisture data to mobile applications shift repurchase loyalty toward digital platforms that aggregate plant health telemetry.
- Retail Environments:Visual merchandising applications demand consistent specimen quality across seasonal inventory turns.
- Urban Gardening:Space-constrained cultivation in apartment balconies and windowsills favors compact varieties with minimal substrate requirements.
Office spaces absorb the largest contract values; home decor is expanding most quickly as sensor-enabled cultivation democratizes expertise.
Distribution Channel:
Volume concentration in traditional retail is giving way to margin capture in digital channels as logistics networks improve live-plant handling protocols.
- Online Retail:Proprietary protective packaging that extends plant viability during last-mile delivery opens cross-border e-commerce channels previously closed to living goods. Curated subscription models and educational content lock in metropolitan residential buyers who lack horticultural expertise.
- Garden Centers:Traditional advice-based selling models face displacement as IoT-enabled residential buyers bypass expert consultation.
- Florists:Gift-oriented transactions sustain higher per-unit margins but limited repeat purchase frequency.
- Supermarkets:High-volume, low-margin positioning depends on centralized distribution infrastructure and rapid inventory turnover.
Online retail is climbing the fastest; garden centers still process the largest absolute volumes.
End User:
Customer type determines whether procurement emphasizes aesthetic specification or operational reliability.
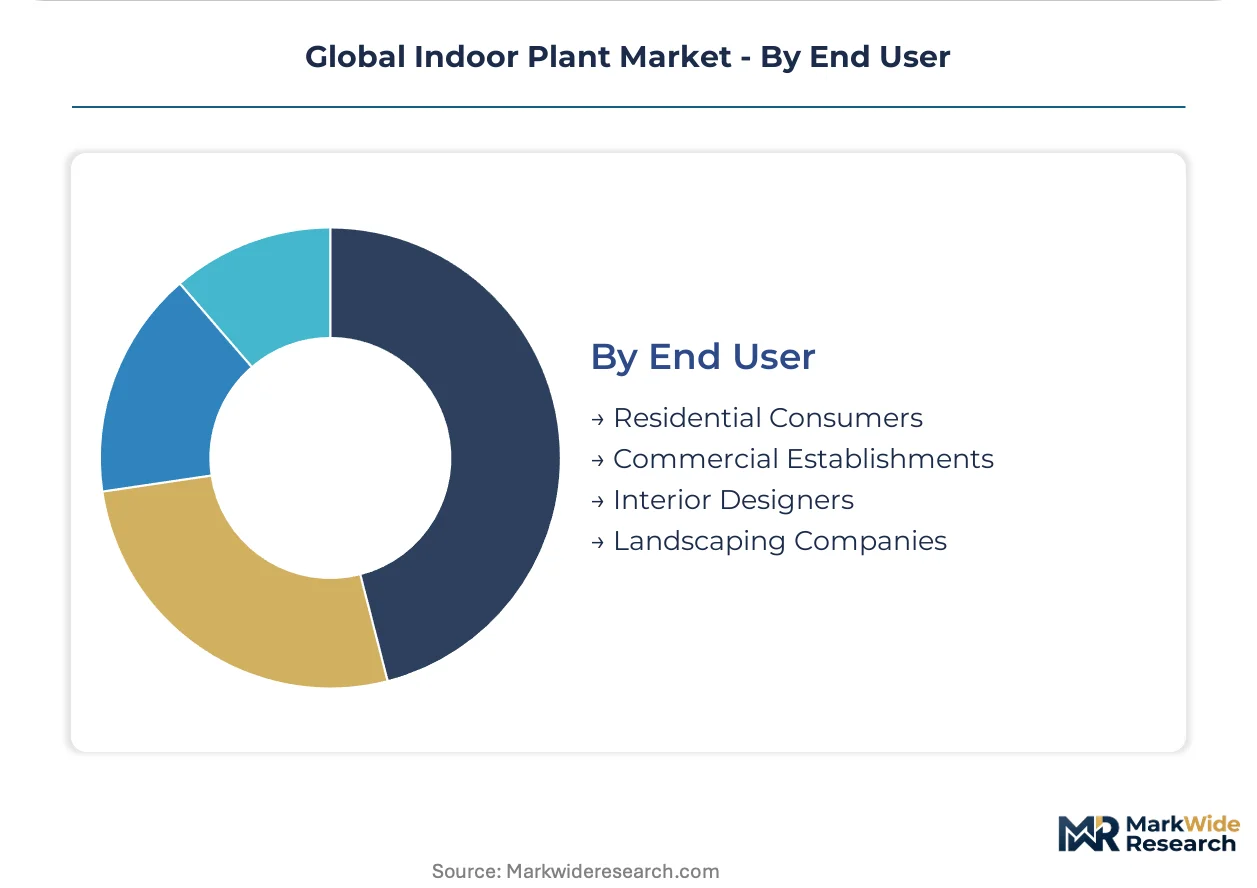
- Commercial Establishments:Facility managers in German office complexes source specified cultivar volumes directly from propagation facilities, bypassing traditional distribution tiers. Standardized biophilic design specifications in Frankfurt's banking district enable bulk purchasing contracts with tissue culture laboratories.
- Residential Consumers:Urban apartment complexes represent a rapidly expanding buyer segment as millennial preferences concentrate demand in dense metropolitan corridors. Subscription-based plant care models with curated replacement cycles address the expertise gap that limits cultivation success.
- Interior Designers:Project-based procurement requires consistent specimen quality across large installation footprints.
- Landscaping Companies:Maintenance service bundling creates recurring revenue streams distinct from one-time plant sales.
Commercial establishments dominate contract value; residential consumers are gaining share fastest as digital platforms reduce friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German commercial real estate corridors, while cost-sensitive residential volume aggregates in Chinese e-commerce channels. Japanese biophilic mandates compress procurement cycles, and US direct-to-consumer operators capture margin through proprietary logistics. Dutch propagation facilities anchor EU supply security under tightening phytosanitary regimes.
Germany
Facility managers in Frankfurt's banking district source foliage cultivars directly from tissue culture laboratories, bypassing wholesale intermediaries. EU Green Deal biodiversity targets tighten import documentation for ornamental species entering through Rotterdam and Hamburg ports. Munich and Hamburg office complexes deploy standardized biophilic specifications that enable multi-year maintenance contracts.
Japan
Property developers in Tokyo and Osaka pre-negotiate horticultural service agreements to satisfy METI biophilic construction mandates for commercial buildings above specified floor areas. Japan's national building code amendments now require living plant integration for occupancy permits in new construction. Kanto region facility managers contract specialized maintenance firms for compliance documentation.
United States
USDA APHIS phytosanitary certification requirements create administrative overhead that disadvantages smaller nursery operations seeking cross-border expansion. Dense metropolitan corridors in New York and Los Angeles sustain direct-to-consumer subscription models with curated replacement cycles. California propagation facilities leverage climate-controlled infrastructure for year-round supply consistency.
China
Domestic e-commerce platforms aggregate residential demand from millennial apartment dwellers in Shanghai and Beijing seeking low-maintenance succulents. The country's national agricultural regulator enforces phytosanitary standards on imported ornamental stock entering through major port facilities. Pearl River Delta greenhouse operators deploy automated climate systems to reduce propagation cycle variability.
Netherlands
Rotterdam and Aalsmeer logistics hubs coordinate EU-certified propagation output for distribution across German and French commercial channels. REACH chemical residue limits on pesticide applications force retesting of entire cultivation cycles before export authorization. Dutch tissue culture laboratories supply standardized cultivar volumes to Frankfurt and Munich facility managers under long-term procurement agreements.
Global Indoor Plant Market Competitive Environment
Concentration sits with large-scale automated greenhouse operators that control climate-controlled propagation infrastructure across multiple continents. The vendor base organizes around three strategic archetypes: tissue culture laboratories supplying commercial real estate direct, curated digital platforms locking in metropolitan residential subscribers, and specialized logistics innovators extending plant viability through protective packaging. Dominant competitive moves include backward integration into sterile laboratory operations and geographic expansion through cross-border e-commerce channel development.
Among North American direct-to-consumer specialists, Bloomscape and The Sill Inc exemplify the subscription-platform archetype, while Costa Farms LLC anchors the large-scale propagation tier with multi-continent greenhouse infrastructure. Dümmen Orange occupies a position within the EU-certified laboratory supply chain serving commercial biophilic installations.
| Leading Market Players |
|---|
| Costa Farms LLC |
| The Sill Inc |
| Dümmen Orange |
| Ambius |
| Beekenkamp Verpakkingen B.V |
| Double H Nurseries Ltd. |
| Bloomscape |
| Premier Planters |
| Rolling Nature |
| Others |
Value Chain & Pricing Dynamics
Large-scale tissue culture capacity in the Netherlands and Germany anchors price floors for commercial-grade foliage specimens, compressing margins for mid-scale operators unable to match sterile laboratory throughput. Automated greenhouse utilization rates above threshold levels enable just-in-time fulfillment contracts that standardize pricing across Frankfurt and Munich banking corridors, while smaller propagation facilities absorb residual spot demand at volatile premiums.
Pricing Analysis
The customization-premium spread separates bulk cultivar contracts for German facility managers from curated subscription tiers targeting metropolitan residential buyers. Three-tier pricing structure across premium, standard, and economy levels stratifies by phytosanitary certification grade and after-sales maintenance bundling. Cost compression in the standard tier intensifies as Dutch propagation facilities extend direct procurement agreements, bypassing wholesale intermediaries. Commercial establishments exhibit lowest price sensitivity due to compliance-driven specification requirements, while residential consumers in Chinese e-commerce channels drive hardest bargain hunting.
Supply Chain Analysis
Inventory-strategy preferences bifurcate between just-in-time fulfillment for Japanese and German commercial installations and strategic stockpiling of tissue culture starter material in Dutch propagation hubs. Geographic supply concentration centers on the Netherlands, Germany, and China, with Rotterdam and Aalsmeer logistics hubs coordinating EU-certified output. Raw material dependencies encompass peat-based substrates, controlled-release fertilizers, and sterile laboratory consumables. Single-source vulnerability in specialized substrate formulations threatens propagation cycle continuity. Distribution runs through direct laboratory-to-facility channels for commercial buyers and platform-aggregated last-mile networks for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German facility managers and Japanese property developers who pre-negotiate multi-year service agreements, fragmenting pricing leverage for smaller nursery operations. This consolidation among institutional procurement desks favors scale-backed propagation facilities with certified compliance documentation.
For Market Incumbents: Secure EU Green Deal certification moats through backward integration into sterile tissue culture operations, insulating against REACH chemical residue enforcement that threatens imported ornamental stock. Lock in multi-year maintenance contracts with Frankfurt and Munich commercial real estate investment trusts before biophilic design specifications standardize procurement. Channel control through proprietary protective packaging technology defends margin position against direct-to-consumer entrants. For New Entrants and Emerging Players: Anchor in Japanese metropolitan corridors where METI biophilic mandates create captive demand for installation and maintenance services with limited incumbent penetration. Target residential subscription models in dense urban apartment complexes where horticultural expertise gaps sustain curated replacement cycles. Deploy sensor-enabled cultivation platforms as the go-to-market angle, aggregating plant health telemetry to shift repurchase loyalty from traditional garden centers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated greenhouse operators with climate-controlled propagation infrastructure across multiple continents. Long-term viability rests on capacity to serve institutional procurement desks standardizing biophilic specifications. Acquisition target archetype: EU-certified tissue culture laboratories with existing direct supply relationships to German banking district facility managers. Watch for divergence in national quarantine protocols as the inflection indicator forcing parallel compliance system investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tissue Culture | Sterile laboratory control secures year-round supply consistency under REACH chemical frameworks. |
| Subscription Platform Launch | Curated replacement cycles lock in metropolitan residential buyers lacking horticultural expertise. |
| Protective Packaging Patent Development | Proprietary vessel designs extend plant viability for cross-border e-commerce channel expansion. |
| Multi-Year Service Agreement Pre-negotiation | Japanese property developers contract specialized maintenance firms to satisfy METI occupancy permits. |
| Sensor-Enabled Cultivation Platform Deployment | IoT soil monitoring aggregates telemetry that shifts repurchase loyalty toward digital platforms. |
Study Parameters
Cross-validation between primary interviews with greenhouse operations directors, facility managers at German commercial real estate investment trusts, and horticultural maintenance firm executives anchors the qualitative findings. Secondary validation draws from EU customs trade data, USDA APHIS phytosanitary certification records, Japanese METI building code amendments, and SEC filings of publicly traded propagation facilities. Bottom-up cultivar volume aggregation triangulates against top-down regional demand modeling for residential and commercial segments.
Sensitivity analysis on propagation cycle duration, phytosanitary compliance cost trajectories, and last-mile logistics mortality rates informs the analytical framework across the projection horizon. Segmentation dimensions encompass plant type, usage category, distribution channel, and end-user archetype with regional regulatory cluster overlays. CAGRs derive from installed base growth in commercial square footage subject to biophilic mandates and residential subscriber acquisition curves in metropolitan corridors. Forecast inputs include tissue culture technician recruitment gaps and divergent national quarantine protocol evolution.
Underlying assumptions cover stable REACH chemical residue enforcement, sustained METI biophilic mandate expansion, and gradual improvement in live-plant handling protocols, with deviation risk concentrated in regulatory acceleration or logistics network disruption scenarios. Practitioners should keep alternative scenarios live as EU Green Deal biodiversity targets and phytosanitary certification complexity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
North America Microgreens Market
Vegetables
Peas Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Qatar Greenhouse Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
South America Peas Market
Vegetables
Microgreens Market
Vegetables
Artichokes Market
Vegetables
Europe Pea Market
Vegetables
North America Peas Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Yarrow Market
Vegetables
Air Dried Vegetables Market
Vegetables
Squash Market
Vegetables
Dried Vegetable Market