
 Plant Based Ingredients Market | 2026-2036
Plant Based Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Ingredients Market Analysis
Soy protein concentrate is decoupling from traditional commodity pricing as functional performance premiums widen. Cargill Incorporated leverages its North American oilseed processing network to anchor supply security for food manufacturers. Archer-Daniels-Midland Company sustains R&D intensity across fermentation-derived protein platforms. Kerry Group differentiates through flavor-mask technologies that broaden application scope for bitter-tasting legume isolates.
Plant based ingredients comprise extracted, refined, or fractionated botanical compounds—typically achieving protein concentrations of 80-90% in isolate form through aqueous or enzymatic processing—serving as functional replacements for animal-derived inputs across formulated goods. Proteins command the largest value pool among product types due to formulation complexity and performance premiums in meat analogs. Oils within the application dimension are gaining fastest in personal care as cosmetic brands phase out petrochemical emollients. Powder form dominates manufacturing economics because of shelf stability and transport efficiency, though liquid concentrates are capturing share in beverage systems.
The FDA maintains GRAS notification requirements for novel plant proteins entering the US food supply, while the USDA enforces organic certification standards that command price premiums in retail channels. EFSA allergen labeling rules under EU regulation 1169/2011 reshape formulation choices for exporters serving European manufacturers. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to recalibrate cost competitiveness between regional supply bases.
Market Dynamics
Carbon border adjustment mechanisms under the EU Green Deal are recalibrating sourcing economics for North American and Asian suppliers serving European food manufacturers. F-Gas Regulation compliance costs are compressing margins on refrigerated protein isolates while accelerating regional processing investments.
Growth Catalysts
- EU Green Deal carbon accounting mandates:German retailers now require Scope 3 documentation for plant protein imports, forcing upstream suppliers to certify low-emission processing methods.
- Pea protein isolate functional performance:Meat analog manufacturers in the Netherlands and Denmark are reformulating with 90% protein concentrates to achieve fibrous textures previously requiring soy.
- Clean-label retail gatekeeping:Supermarket chains in France and Belgium have banned artificial additives in private-label plant-based products, expanding addressable market for minimally processed isolates.
Market Restraints
- Yellow pea supply concentration:Canadian Prairie provinces supply over 70% of global yellow pea protein feedstock, exposing processors to weather-driven harvest volatility and rail logistics bottlenecks.
- Enzymatic hydrolysis capex intensity:Fractionation facilities require membrane filtration systems costing $40-60 million per production line, limiting entry to well-capitalized processors.
- EFSA novel food approval timelines:Fermentation-derived proteins face 18-24 month safety evaluation periods under EU regulation 2015/2283, delaying commercialization for precision fermentation startups.
Strategic Opportunities
- Personal care oil applications:Cosmetic formulators in Italy and Spain are substituting petrochemical emollients with oat and hemp seed oils, opening premium pricing tiers for cosmetic-grade isolates.
- USDA organic certification arbitrage:Organic plant proteins command 35-50% price premiums in US natural retail channels, incentivizing European processors to obtain dual EU-US organic accreditation.
- Beverage system liquid concentrates:Ready-to-drink protein beverage manufacturers are shifting from powder reconstitution to aseptic liquid concentrates, reducing formulation complexity and clean-up costs.
Industry Challenges
- Flavor chemist talent scarcity:Masking bitter saponins and grassy off-notes in legume isolates requires specialized sensory science expertise concentrated at flavor houses in Switzerland and the Netherlands.
- Allergen cross-contamination protocols:Shared production lines for soy and peanut processing trigger EFSA precautionary labeling requirements under regulation 1169/2011, complicating multi-product facility economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Ingredients Market |
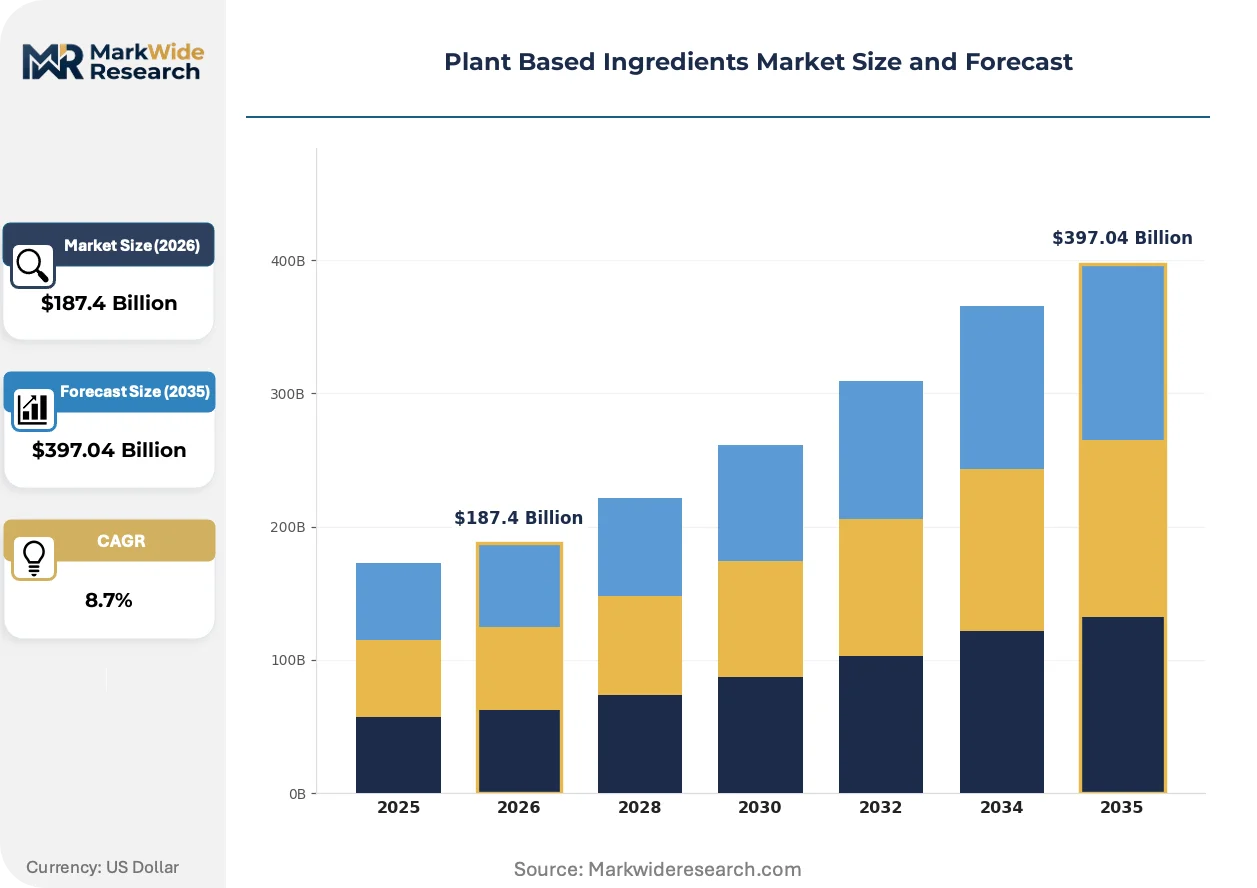
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Starches, Oils, Fiber Application: Food & Beverage, Personal Care, Animal Feed, Pharmaceuticals Form: Powder, Liquid, Granule, Paste End User: Manufacturers, Retailers, Food Service, Distributors |
| Companies Covered | Cargill Incorporated, Archer-Daniels-Midland Company, Ingredion Incorporated, DuPont de Nemours, Kerry Group, Bunge Limited, Olam International, Glanbia PLC, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Ingredients Market Emerging Trajectories
Fermentation-derived protein platforms are diverging from conventional extraction methods, creating parallel technology tracks with distinct regulatory pathways and end-use suitability profiles.
Precision fermentation using microbial hosts is expanding into dairy protein analog production. Perfect Day and Remilk have demonstrated commercial-scale whey protein expression without lactose or bovine inputs. This technology is compressing the addressable market for traditional soy and pea isolates in premium ice cream and sports nutrition applications.
REACH authorization requirements for processing aids are tightening solvent recovery standards in European protein fractionation facilities. ECHA's 2024 updates to Annex XVII restrict hexane residues in food-grade isolates below 5 ppm. German and Dutch processors are retrofitting facilities with supercritical CO2 extraction systems to maintain market access.
Direct-to-manufacturer procurement contracts are displacing spot market purchases for high-volume pea protein users. Nestlé and Unilever have established three-year offtake agreements with Canadian processors, securing volume commitments in exchange for price stability. This pattern is most visible in Germany, where meat analog production capacity has tripled since 2022.
Plant Based Ingredients Market Segmentation
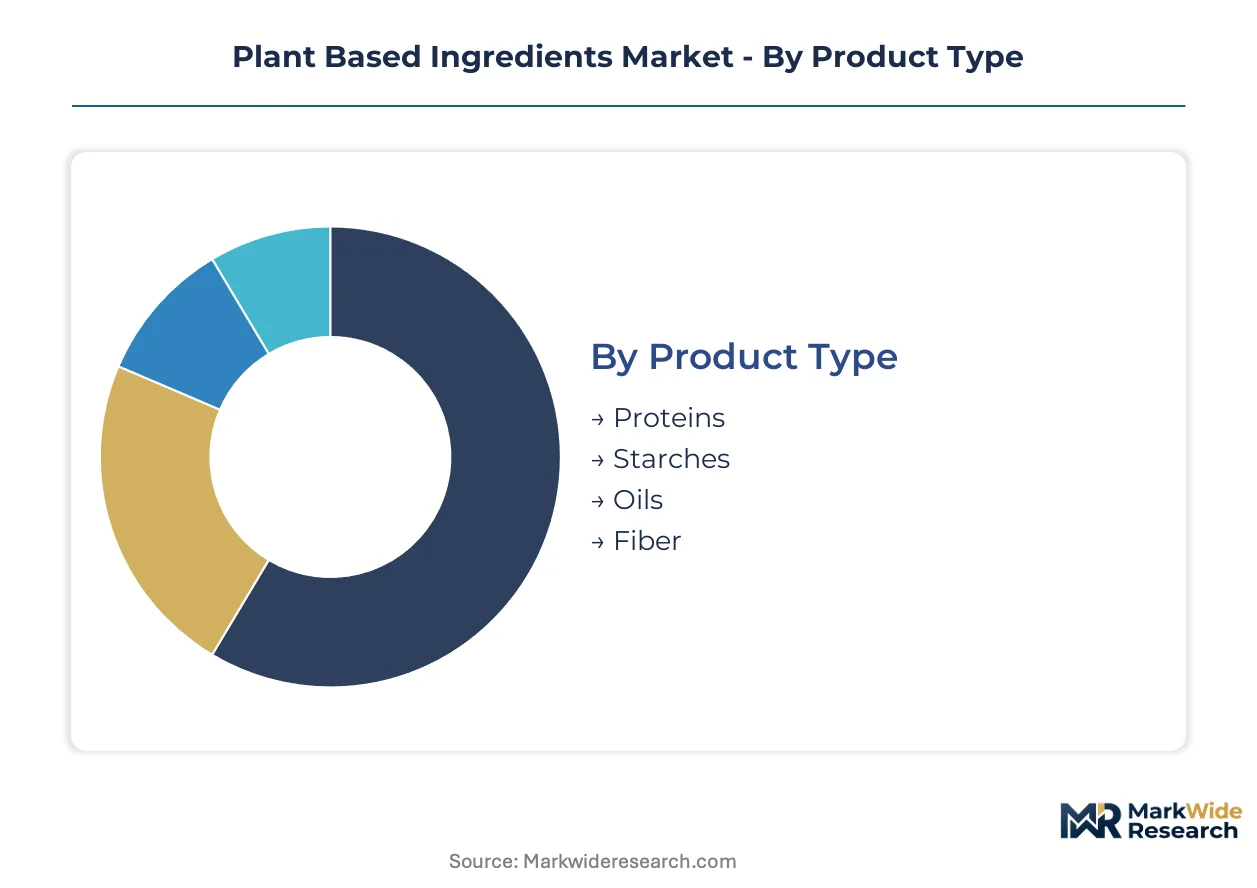
Plant based ingredients fragment across four intersecting dimensions that determine pricing power, regulatory exposure, and formulation complexity. Product type governs margin structure, while application and form dictate processing investments and shelf-life engineering.
Product Type:
Proteins capture volume leadership through meat analog demand, while oils command premium pricing in cosmetic applications where petrochemical substitution drives reformulation budgets.
- Proteins:Isolates achieving 80-90% concentration through aqueous or enzymatic extraction serve as functional replacements for animal-derived inputs across meat analogs and sports nutrition. German and Dutch manufacturers are reformulating with 90% pea protein concentrates to achieve fibrous textures previously requiring soy, tightening feedstock competition with Canadian Prairie suppliers.
- Oils:Cosmetic-grade oat and hemp seed oils are displacing petrochemical emollients in Italian and Spanish personal care formulations, opening premium pricing tiers for processors with supercritical CO2 extraction capabilities under REACH Annex XVII compliance.
- Starches:Texturizing agents from potato and tapioca sources support clean-label thickening in sauces and bakery applications.
- Fiber:Insoluble and soluble fractions from pea hulls and oat bran fortify digestive health positioning in retail packaged goods.
Today's leader: Proteins. Tomorrow's challenger: Oils.
Application:
Food and beverage absorbs the majority of volume, though personal care is climbing the fastest as cosmetic brands phase out synthetic ingredients under EU Green Deal procurement standards.
- Food & Beverage:Meat analog manufacturers in the Netherlands and Denmark drive pea protein concentrate uptake, while ready-to-drink beverage formulators shift from powder reconstitution to aseptic liquid concentrates to reduce clean-up costs.
- Personal Care:Italian and Spanish cosmetic formulators are substituting petrochemical emollients with botanical oils, creating demand for cosmetic-grade isolates with documented carbon footprints.
- Animal Feed:Protein-rich co-products from fractionation processes supplement livestock nutrition, though this segment faces margin pressure from feed-grade commodity competition.
- Pharmaceuticals:Excipient and active ingredient applications require EFSA novel food approval timelines that delay commercialization for emerging botanical sources.
Food and beverage anchors current procurement volumes; personal care is gaining share fastest through premium pricing acceptance.
Form:
Powder dominates transport economics and shelf stability, while liquid concentrates are capturing beverage system share through formulation efficiency gains.
- Powder:Dominates manufacturing economics through shelf stability and transport efficiency, with 80-90% protein isolates standardizing on powder delivery for meat analog rehydration.
- Liquid:Aseptic concentrates reduce formulation complexity for ready-to-drink protein beverages, eliminating powder reconstitution steps and clean-up costs.
- Granule:Intermediate moisture formats suit specific bakery and extrusion applications requiring controlled hydration rates.
- Paste:High-moisture protein preparations serve niche fermented and cultured product applications with limited scale.
Powder retains cost advantage at scale; liquid is expanding most quickly in beverage manufacturing.
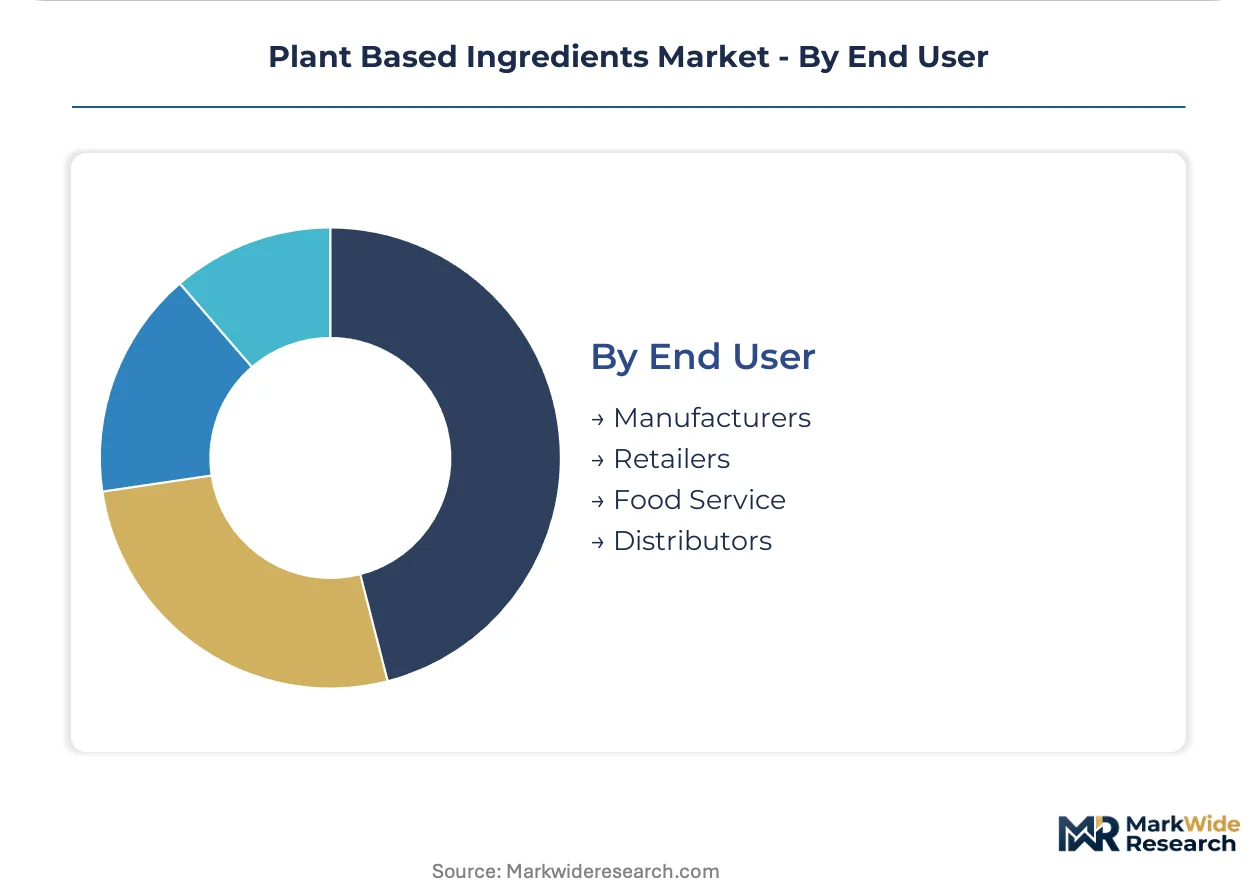
End User:
Manufacturers concentrate procurement volume through direct contracts, while retailers increasingly gatekeep formulation standards through private-label specifications.
- Manufacturers:Nestlé and Unilever have established three-year offtake agreements with Canadian processors, securing volume commitments in exchange for price stability as meat analog production capacity triples in Germany.
- Retailers:Supermarket chains in France and Belgium have banned artificial additives in private-label plant-based products, expanding addressable market for minimally processed isolates.
- Food Service:Restaurant and institutional procurement favors cost-optimized blends with lower protein concentrations than retail packaged goods.
- Distributors:Intermediate stocking roles face margin compression as direct-to-manufacturer procurement displaces spot market purchases for high-volume users.
Manufacturers control volume flows today; retailers are reshaping specification standards fastest through clean-label mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat analog manufacturers anchor procurement volume for high-concentration pea protein isolates, with Rotterdam and Hamburg serving as the primary European entry points for North American feedstock. Regulatory pressure from Brussels reshapes processing investments across the continent.
United States
Midwest oilseed processors expand fractionation capacity to serve domestic meat analog brands and sports nutrition formulators. FDA GRAS notification requirements govern novel protein entry pathways, while USDA organic certification commands price premiums in natural retail channels. Chicago and Minneapolis-St. Paul clusters concentrate oilseed crushing and protein isolation infrastructure.
Germany
Meat analog production capacity has tripled since 2022, with manufacturers reformulating for fibrous textures using 90% pea protein concentrates. EU Green Deal carbon accounting mandates require Scope 3 documentation for imports, forcing suppliers to certify low-emission processing. Cologne-Düsseldorf and Berlin-Brandenburg regions host the densest concentration of clean-label R&D facilities.
Netherlands
Rotterdam port logistics and Wageningen University research clusters support precision fermentation startups developing dairy protein analogs. EFSA novel food approval timelines under EU regulation 2015/2283 delay commercialization, extending safety evaluation periods to 18-24 months. Dutch processors retrofit facilities with supercritical CO2 extraction to meet REACH Annex XVII hexane residue limits.
Canada
Prairie provinces supply over 70% of global yellow pea protein feedstock, exposing processors to weather-driven harvest volatility and rail logistics bottlenecks. Direct-to-manufacturer procurement contracts with European food manufacturers displace spot market purchases. Saskatchewan and Manitoba crushing facilities anchor North American export capacity.
Italy
Cosmetic formulators in Milan and Bologna substitute petrochemical emollients with oat and hemp seed oils, opening premium pricing tiers for cosmetic-grade isolates. REACH authorization requirements tighten solvent recovery standards in protein fractionation. Northern Italian personal care clusters drive fastest-growing demand outside food applications.
Plant Based Ingredients Market Vendor Landscape
Global majors compete with regional champions across supply security and formulation technology dimensions. The vendor base separates into three tiers: North American agribusiness conglomerates with captive oilseed networks, European flavor and nutrition specialists with sensory masking capabilities, and Asian trading houses with origination scale. Strategic moves concentrate on backward integration into feedstock sourcing and fermentation platform licensing.
Within the agribusiness archetype, Cargill Incorporated and Archer-Daniels-Midland Company represent North American supply security anchors, while Kerry Group exemplifies European formulation technology specialists. These three occupy positions spanning raw material procurement through finished ingredient delivery, with each representing distinct competitive vectors: oilseed processing scale, fermentation R&D intensity, and flavor-mask technology respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| DuPont de Nemours |
| Kerry Group |
| Bunge Limited |
| Olam International |
| Glanbia PLC |
| International Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting mandates gate qualified supply and premium-tier pricing access by requiring Scope 3 documentation for plant protein imports. German retailers enforce this standard as a procurement precondition, bifurcating the market between certified low-emission processors commanding performance premiums and uncertified suppliers facing exclusion.
Pricing Analysis
Input-cost pass-through from Canadian Prairie yellow pea harvest volatility flows directly into isolate pricing, with rail logistics bottlenecks amplifying seasonal swings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and protein concentration, with 90% isolates holding firmer than lower grades. Cost compression in standard-tier concentrates is intensifying because enzymatic hydrolysis capex burdens concentrate production among well-capitalized processors. Food and beverage manufacturers show least price sensitivity due to reformulation lock-in, while animal feed co-product buyers exit when spreads tighten.
Supply Chain Analysis
Single-source vulnerability sits with Canadian Prairie provinces, which anchor over 70% of global yellow pea protein feedstock. Germany and the Netherlands draw from this concentration for meat analog production, with Italy and Spain sourcing cosmetic-grade oat and hemp seed oils from distinct European origination points. Rail logistics chokepoints across the Canadian export corridor threaten delivery reliability during peak harvest windows. Distribution runs through Rotterdam and Hamburg as primary European entry points for North American feedstock, with direct-to-manufacturer procurement contracts displacing spot market purchases for high-volume users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant based ingredients constitute a late-cycle quality story as German meat analog manufacturers shift demand toward 90% protein concentrates with documented carbon footprints. Premium specification adherence now determines supplier viability more than scale economies alone.
For Market Incumbents: Acquire fermentation platform capabilities to counter precision fermentation startups compressing the addressable market for traditional isolates. Secure backward integration into Prairie province yellow pea origination to buffer weather-driven harvest volatility. Anchor supply security through three-year offtake structures matching Nestlé and Unilever contract templates.
For New Entrants and Emerging Players: The premium-economy price-point gap in cosmetic-grade isolates offers entry terrain. Italian and Spanish personal care formulators present the most penetrable demand cluster, with REACH Annex XVII compliance creating qualification barriers that favor nimble supercritical CO2 extraction investments. Lead with carbon footprint documentation as the go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap flavor-mask technology specialists because sensory science expertise concentrates at Swiss and Dutch flavor houses with limited replication. The 5-10 year viability window favors processors with dual EU-US organic accreditation. Watch EFSA novel food approval timeline compression as the inflection signal for fermentation-derived protein platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Origination | Prairie province crushing capacity anchors supply security for European meat analog manufacturers. |
| Supercritical CO2 Extraction Retrofit | German and Dutch processors maintain REACH Annex XVII market access against hexane residue limits. |
| Dual EU-US Organic Certification | European processors capture 35-50% price premiums in US natural retail channels. |
| Flavor-Mask Technology Acquisition | Sensory science capabilities broaden application scope for bitter-tasting legume isolates. |
| Precision Fermentation Platform Licensing | Dairy protein analog production compresses traditional isolate demand in premium ice cream segments. |
Methodological Framework
Multiple input streams — primary interviews with protein processing executives, regulatory affairs leads at EFSA and FDA, and procurement managers at German meat analog manufacturers — were reconciled against secondary validation from customs trade data, EU Green Deal implementation filings, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling across product type, application, form, and end user dimensions was triangulated with top-down macroeconomic anchors.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning protein concentration tiers, clean-label certification levels, and regional carbon accounting compliance clusters. CAGRs were derived from trend extrapolation of formulation budget allocations and regulatory mandate implementation schedules, with pea protein isolate functional performance curves and F-Gas Regulation compliance cost trajectories serving as industry-specific forecast inputs.
Caveats apply where EFSA novel food approval timeline compression, Canadian rail logistics disruptions, or EU carbon border adjustment mechanism expansion could materially shift the outlook. Forecasts reflect documented assumptions about regulatory implementation pace and feedstock harvest stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Tomato Concentrate Market
Ingredients
Cocoa Derivatives Market
Ingredients
Rose Extract Market
Ingredients
Global Amaranth Oil Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Seaweed Extracts Market
Ingredients
Europe Phytosterols Market
Ingredients
Truffle Oil Market
Ingredients
Corn Gluten Meal Market
Ingredients
Ximenia Oil Market
Ingredients
Liquid Egg Market
Ingredients
Edible Oils and Fats Market
Ingredients
Pork Skin Gelatin Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Clean Label Flour Market
Ingredients
Spain Sodium Reduction Ingredient Market