
 US Choline Bitartrate Market | 2026-2036
US Choline Bitartrate Market Size, Share, and Industry Trends Forecast 2026-2036
US Choline Bitartrate Market Insights
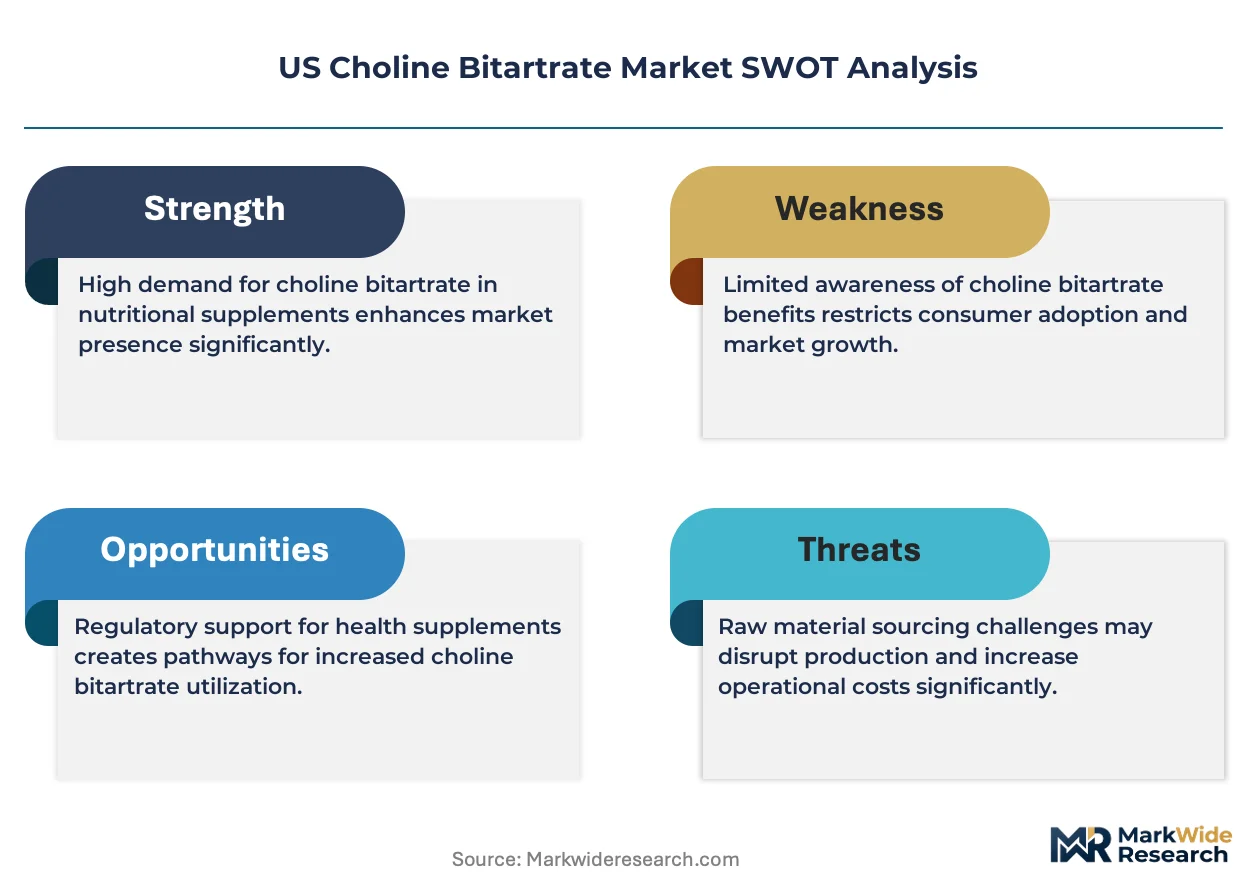
US specialty chemical producers is pivoting toward pharmaceutical-grade choline bitartrate output to capture premium contract manufacturing demand. Balchem Corporation leverages its encapsulated nutrient technology to sustain leadership in human nutrition applications. Eastman Chemical Company anchors its position through backward integration into acetic acid and trimethylamine supply chains. BASF SE competes via its global vitamin and precursor distribution network, while NutriScience Innovations differentiates through custom formulation services for regional supplement brands.
Choline bitartrate is the hydrogen tartrate salt of choline, typically supplied as a white crystalline powder with assay specifications of 98-101% and choline content of approximately 41% by weight, manufactured through controlled reaction of trimethylamine with ethylene oxide followed by tartaric acid neutralization. The compound serves primarily as a choline source in dietary supplements supporting liver function, neural transmission, and lipid metabolism. Powder formulations occupy the largest volume share due to bulk manufacturing economies and blend flexibility, while liquid formats represent the fastest-growing category as beverage fortification expands. Sports nutrition applications generate above-average margins compared to general consumer segments, with healthcare providers channeling demand toward USP-grade material for clinical enteral nutrition protocols.
FDA oversight through 21 CFR 101.36 governs nutrient content claims and labeling disclosures for choline-fortified products, while DSHEA compliance requirements shape new entrant market access timelines. The USDA National Organic Program influences raw material sourcing for certified supplement lines, and cGMP inspections by FDA district offices determine manufacturing eligibility. Stakeholders must monitor evolving FDA enforcement priorities around NDI substantiation and state-level prop 65 litigation exposure for heavy metal contaminants.
Market Dynamics
FDA's New Dietary Ingredient notification requirements are compressing product development timelines and forcing reformulation investments across US supplement portfolios. This regulatory pressure is reshaping how manufacturers source pharmaceutical-grade choline bitartrate and validate supply chain documentation.
Growth Catalysts
- DSHEA Compliance Pathways:The Dietary Supplement Health and Education Act creates structured market access for validated choline formulations, with USP-grade material commanding premium positioning in clinical nutrition channels.
- Cognitive Health Prioritization:Consumer neuroscience research is accelerating demand for acetylcholine precursors among aging populations and biohacking segments in California and the Northeast corridor.
- Beverage Fortification Expansion:Liquid choline bitartrate formats are displacing powder in functional drink applications, with sports nutrition brands driving formulation innovation.
Market Restraints
- Trimethylamine Supply Concentration:Domestic production of this critical feedstock clusters near Gulf Coast petrochemical hubs, exposing manufacturers to hurricane disruption and force majeure events.
- Prop 65 Litigation Exposure:California's Safe Drinking Water and Toxic Enforcement Act generates contingent liability for heavy metal trace contaminants, elevating insurance and testing costs for national distribution.
- Choline Chloride Substitution:Lower-cost choline salts in animal nutrition applications compress price ceilings for food-grade bitartrate specifications.
Strategic Opportunities
- Enteral Nutrition Protocol Expansion:Hospital formulary adoption of USP-grade choline for hepatic support in ICU settings opens clinical reimbursement pathways.
- USDA Organic Certification:National Organic Program compliance for tartaric acid sourcing enables premium positioning in natural products channel.
- Direct-to-Practitioner Distribution:Functional medicine clinicians represent an underpenetrated channel with higher margin tolerance than mass retail.
Industry Challenges
- cGMP Inspection Backlogs:FDA district office capacity constraints delay manufacturing eligibility determinations, freezing new entrant capacity additions for 18-24 month cycles.
- Analytical Method Harmonization:Discrepancies between USP monograph specifications and AOAC official methods create lot release disputes between contract manufacturers and brand holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Choline Bitartrate Market |
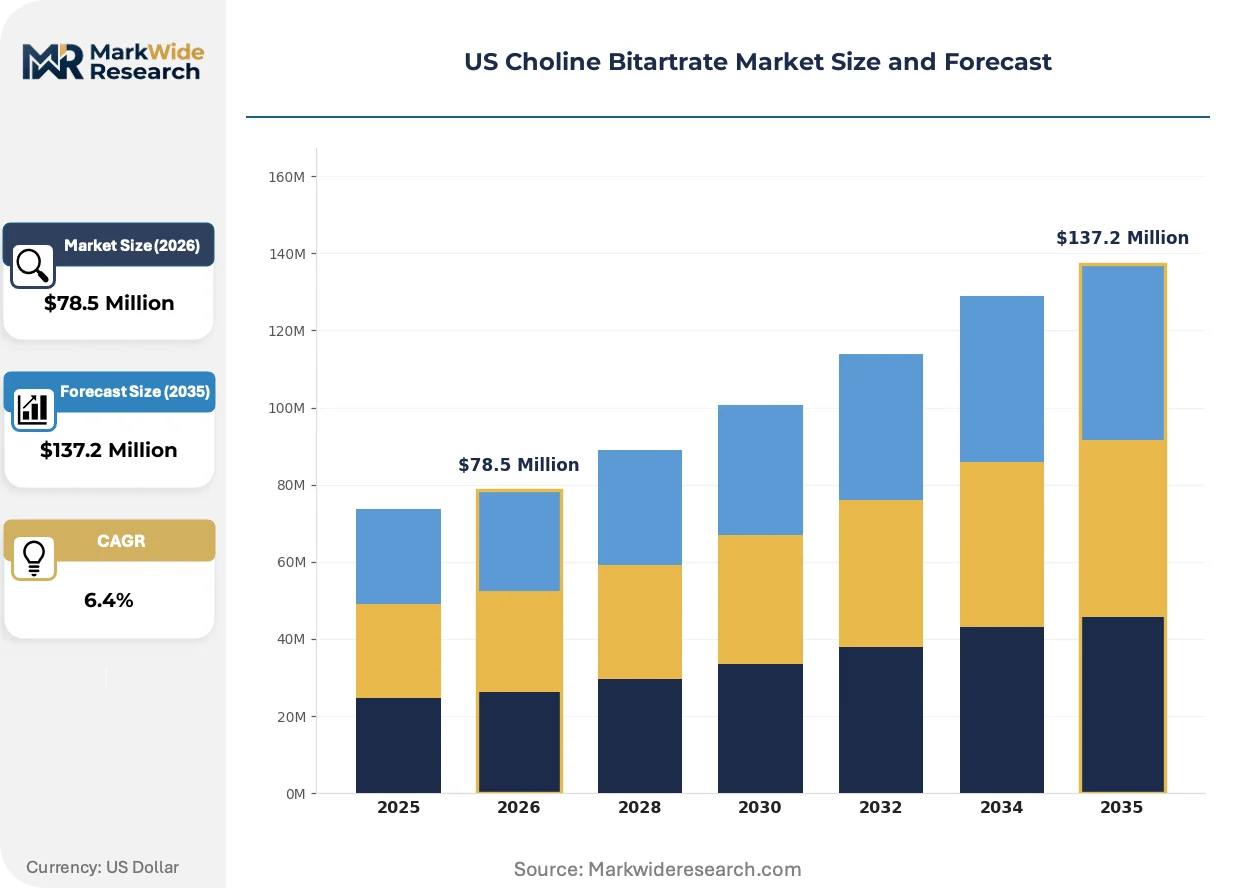
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $137.2 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powder, Capsules, Liquid Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Sports Nutrition End User: Healthcare Providers, Fitness Enthusiasts, General Consumers, Athletes Distribution Channel: Online, Retail Stores, Pharmacies, Direct Sales |
| Companies Covered | Balchem Corporation, Eastman Chemical Company, BASF SE, Cepham Life Sciences, NutriScience Innovations, LLC, Jubilant Life Sciences, Kemin Industries, Glentham Life Sciences Limited, Alfa Aesar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Choline Bitartrate Market Trends and Innovations
Encapsulation technologies and precision delivery systems are redefining bioavailability benchmarks in choline supplementation. These advances are compressing differentiation cycles and forcing ingredient suppliers to demonstrate clinical validation beyond standard assay compliance.
Liposomal encapsulation technology is converging with choline bitartrate formulations to enhance blood-brain barrier penetration. Sports nutrition manufacturers in the Mountain West region are adopting these formats at accelerated pace. This convergence is compressing margins for conventional powder suppliers while creating premium pricing tiers for validated delivery systems.
FDA enforcement priorities around NDI substantiation are tightening evidentiary requirements for structure-function claims. The agency's 2023 guidance on chemical alteration thresholds is forcing retrospective safety dossier reviews. Dietary supplement brands with legacy choline products are responding with third-party toxicology studies to preempt warning letters.
Healthcare practitioner channels are displacing mass-market retail as the primary volume driver for high-potency choline formulations. Functional medicine clinics and registered dietitians now specify USP-grade material with certificate of analysis documentation. This shift concentrates demand in the Northeast pharmaceutical corridor and Southern California wellness clusters.
US Choline Bitartrate Market Segmentation
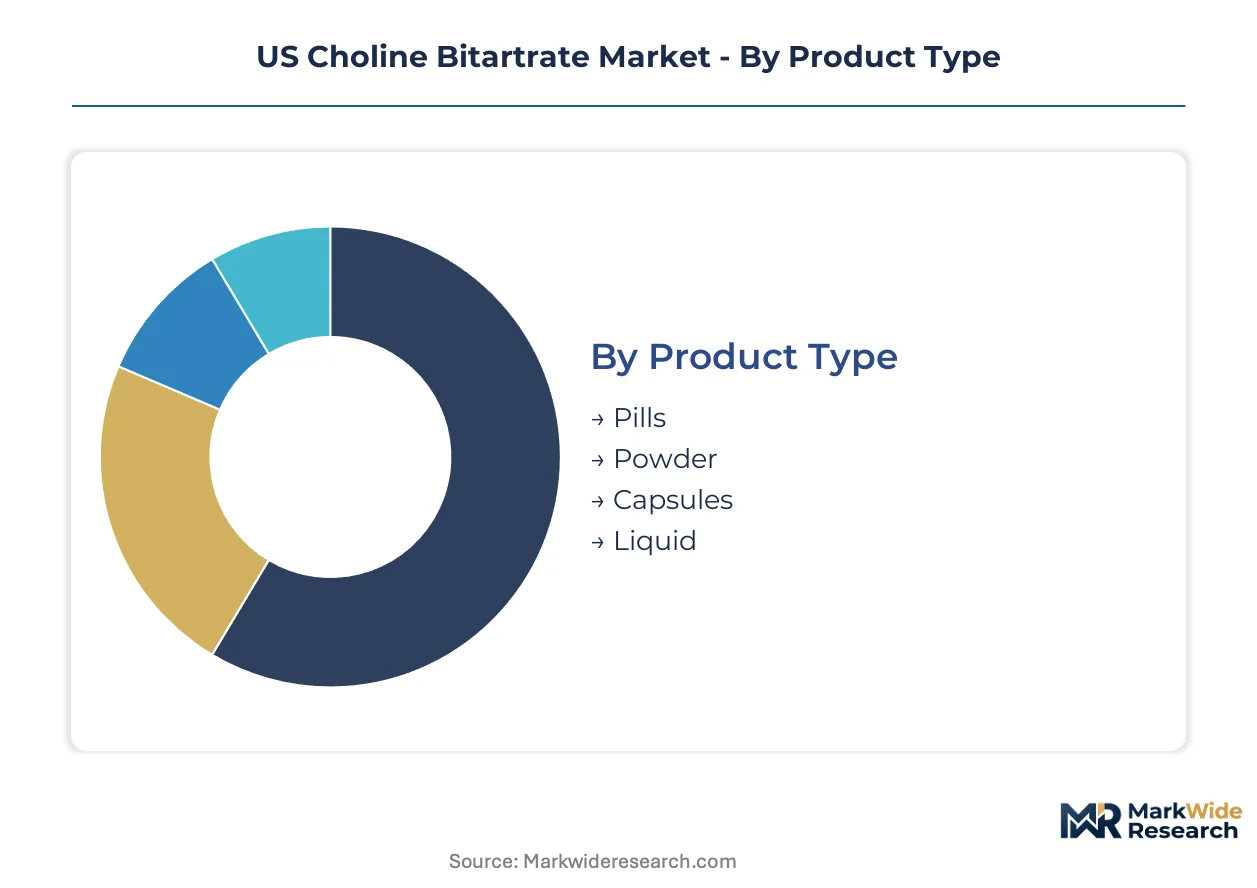
Choline bitartrate formulations fragment across four distinct dimensions, each imposing unique capital requirements and margin structures. Manufacturers must align production assets with specific segment demands to avoid stranded capacity in this specialized ingredient market.
Product Type:
Capital intensity varies sharply across production formats, with liquid manufacturing requiring sterile processing infrastructure while powder operations leverage conventional blending equipment.
- Powder:White crystalline material with 98-101% assay specification dominates bulk manufacturing due to blend flexibility and economies of scale in California's nutrition cluster. Contract manufacturers prioritize this format for multivitamin premix integration.
- Liquid:Aqueous solutions and concentrates demand aseptic filling lines and stability testing protocols, but sports nutrition brands in the Mountain West are adopting these formats for beverage fortification at accelerated pace.
- Capsules:Encapsulation equipment and shell material sourcing add processing layers suited to premium positioning in practitioner channels.
- Pills:Tablet compression and coating infrastructure serve mass-market retail with standardized dosing convenience.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Regulatory burden and certification requirements create tiered entry barriers, with pharmaceutical applications demanding USP-grade validation while food fortification operates under less stringent GRAS frameworks.
- Dietary Supplements:DSHEA compliance pathways structure market access for choline formulations, with FDA's NDI notification requirements compressing product development timelines and forcing reformulation investments across US portfolios.
- Pharmaceuticals:USP-grade material commands premium positioning in clinical nutrition channels, particularly for hepatic support protocols in ICU settings where healthcare providers mandate certificate of analysis documentation.
- Sports Nutrition:Above-average margins attract formulation innovation, though prop 65 litigation exposure elevates insurance costs for California-distributed products.
- Functional Foods:Beverage fortification applications are displacing traditional powder delivery as consumers prioritize convenience in the Northeast corridor.
Dietary supplements command the largest revenue pool; sports nutrition delivers the steepest expansion trajectory.
End User:
Purchasing sophistication and specification rigor separate professional channels from consumer-directed segments, with healthcare providers dictating analytical standards that cascade through supply chains.
- Healthcare Providers:Hospital formulary adoption and functional medicine clinics specify USP-grade material with full traceability documentation, concentrating demand in the Northeast pharmaceutical corridor.
- General Consumers:Mass-market retail purchasers drive volume through cost-sensitive positioning, though cognitive health prioritization among aging populations is elevating quality expectations.
- Fitness Enthusiasts:Biohacking segments in California wellness clusters seek enhanced bioavailability formats and precision delivery systems.
- Athletes:Competitive sports organizations demand batch-tested material free from banned substance contamination, adding third-party certification costs.
General consumers generate the highest absolute volume; healthcare providers are gaining share fastest.
Distribution Channel:
Channel economics reflect working capital intensity and customer acquisition cost structures, with direct sales requiring relationship infrastructure while online platforms demand digital marketing expenditure.
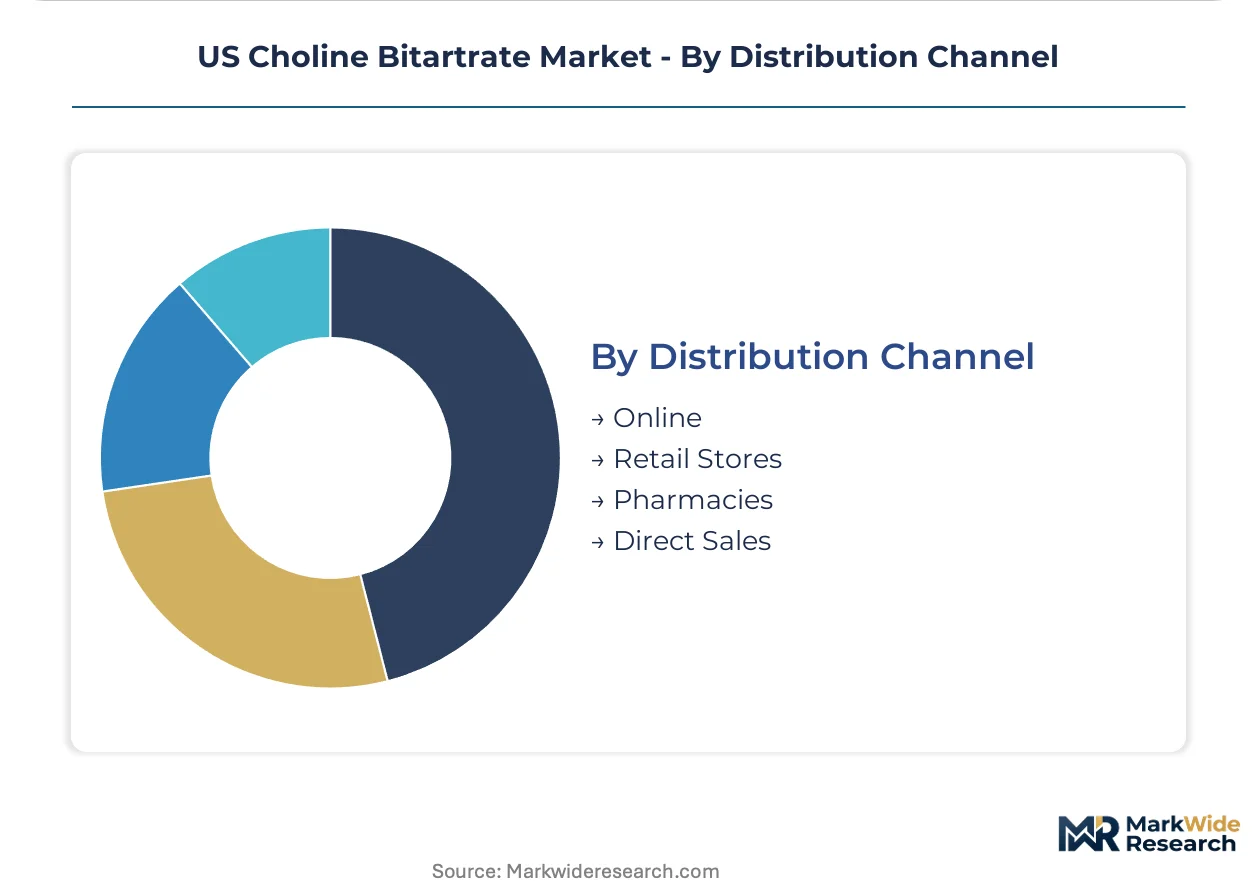
- Online:E-commerce platforms enable direct-to-practitioner distribution for regional supplement brands, bypassing traditional wholesale markups.
- Retail Stores:Mass-market shelf placement requires slotting fees and promotional support, favoring scaled manufacturers with marketing budgets.
- Pharmacies:Behind-the-counter positioning and pharmacist recommendation protocols suit clinical-grade formulations with reimbursement potential.
- Direct Sales:Functional medicine clinician networks and registered dietitian relationships support premium pricing with higher margin tolerance than mass retail.
Retail stores maintain the broadest physical footprint; direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trimethylamine production clusters along the Gulf Coast petrochemical corridor anchor domestic choline bitartrate manufacturing, with hurricane exposure creating supply vulnerability that shapes regional sourcing strategies across the contiguous United States.
California
Los Angeles and San Diego nutrition clusters drive formulation demand for cognitive health supplements, with Prop 65 litigation exposure elevating testing costs for heavy metal contaminants. FDA district office oversight through the San Francisco-based Pacific Region shapes cGMP compliance timelines. San Francisco Bay Area biotech incubators are pioneering liposomal encapsulation partnerships with ingredient suppliers.
Northeast Corridor
New Jersey pharmaceutical corridors and Greater Boston biotech clusters specify USP-grade material for clinical enteral nutrition protocols. FDA's New England District Office inspection backlogs delay manufacturing eligibility determinations for new entrants. New York City's functional medicine practitioner networks concentrate demand for certificate of analysis documentation.
Mountain West
Colorado and Utah sports nutrition brands accelerate beverage fortification adoption of liquid choline formats. State-level dietary supplement registration requirements in Colorado create compliance layering beyond federal DSHEA frameworks. Denver-Boulder wellness clusters drive biohacking segment demand for precision delivery systems.
Southeast
Florida's aging demographic prioritizes cognitive health supplementation through direct-to-practitioner channels. State pharmacy board regulations on compounding pharmacies influence clinical-grade material distribution pathways. Atlanta's contract manufacturing hubs serve regional supplement brands with powder formulation capabilities.
Texas Gulf Coast
Houston-area petrochemical facilities supply trimethylamine feedstock for domestic choline bitartrate synthesis. Hurricane disruption risk exposes manufacturers to force majeure events during Atlantic storm seasons. Corpus Christi chemical processing infrastructure supports backward integration strategies for acetic acid supply security.
US Choline Bitartrate Market Competitive Landscape
Global majors compete with regional champions across pharmaceutical-grade certification and encapsulated nutrient technology. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive feedstock supply, mid-cap nutrition specialists with formulation partnerships, and regional distributors serving practitioner channels. Two strategic archetypes dominate: backward-integrated producers controlling trimethylamine-to-bitartrate conversion, and technology licensors monetizing encapsulation IP. Capacity expansion in sterile liquid processing and M&A targeting regional supplement distributors represent the dominant competitive moves.
Within the multinational chemical tier, Balchem Corporation and Eastman Chemical Company exemplify divergent strategic postures. Balchem occupies a position anchored in encapsulated nutrient technology for human nutrition applications. Eastman Chemical sits within the feedstock-integrated archetype, with company name geography indicating Tennessee-based chemical manufacturing heritage. BASF SE represents the European-headquartered competitor competing through global vitamin and precursor distribution networks. NutriScience Innovations, LLC exemplifies the regional specialist archetype, with corporate structure suggesting limited liability partnership formation serving custom formulation demand.
| Leading Market Players |
|---|
| Balchem Corporation |
| Eastman Chemical Company |
| BASF SE |
| Cepham Life Sciences |
| NutriScience Innovations, LLC |
| Jubilant Life Sciences |
| Kemin Industries |
| Glentham Life Sciences Limited |
| Alfa Aesar |
| Others |
Pricing and Supply Chain Analysis
USP-grade certification against food-grade commodity specifications creates a bifurcated pricing architecture that simultaneously rewards backward-integrated producers with captive trimethylamine supply and penalizes toll manufacturers exposed to Gulf Coast feedstock volatility. This divergence manifests in procurement contracts where pharmaceutical channels demand certificate-of-analysis documentation and long-term offtake guarantees, while sports nutrition buyers negotiate spot-market powder deliveries with minimal warranty terms.
Pricing Analysis
Warranty and documentation bundling separates pharmaceutical-grade contracts from unbundled commodity transactions. Three-tier pricing structure across USP-certified, food-grade, and feed-grade specifications tracks certification investment and analytical rigor. Pricing pressure stems from choline chloride substitution in adjacent animal nutrition markets compressing bitartrate ceilings. Healthcare providers exhibit lowest price sensitivity due to reimbursement protocols, while mass-market supplement brands drive hard volume discounts.
Supply Chain Analysis
Direct-to-contract-manufacturer channels handle bulk powder demand from California and Northeast nutrition clusters, while direct-to-practitioner distribution captures premium liquid formats. Domestic production draws from Texas Gulf Coast trimethylamine supply and Tennessee acetic acid corridors. Supply chain risk centers on hurricane disruption to petrochemical feedstock infrastructure. Distribution runs through regional supplement distributors with cGMP-certified warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trimethylamine supply concentration and FDA cGMP inspection backlogs constrain effective capacity expansion, propping pricing power for qualified incumbents while extending new entrant timelines.
For Market Incumbents: Acquire sterile liquid processing assets to capture beverage fortification growth and defend against encapsulation technology licensors. Secure backward integration into tartaric acid supply through National Organic Program-certified sourcing partnerships. Channel control through direct-to-practitioner relationships protects margin against retail price erosion. For New Entrants and Emerging Players: The premium-to-commodity price spread in liposomal delivery formats offers entry for technology licensors without capital-intensive powder manufacturing. Target Mountain West sports nutrition brands with unmet demand for validated bioavailability claims. Functional medicine clinician networks in Southern California represent the most penetrable channel with higher margin tolerance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational chemical conglomerates seeking human nutrition diversification. Five-to-ten year viability hinges on NDI notification compliance infrastructure and clinical validation capabilities. Watch FDA enforcement priorities around chemical alteration thresholds as the critical inflection signal for portfolio risk reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trimethylamine | Captive feedstock supply insulates margin from Gulf Coast force majeure events. |
| USP-Grade Certification Investment | FDA compliance opens clinical reimbursement pathways in Northeast hospital systems. |
| Liposomal Encapsulation Partnership | Technology licensing enables premium positioning without sterile processing capex. |
| Direct-to-Practitioner Channel Buildout | Functional medicine networks in California tolerate higher pricing than mass retail. |
| USDA Organic Tartaric Acid Sourcing | NOP compliance unlocks natural products channel premium in certified supplement lines. |
Research Methodology
Independent corroboration across FDA warning letter databases, USDA National Organic Program certification records, and SEC 10-K filings underwrites the qualitative findings. Primary interviews with dietary supplement brand managers, contract manufacturing executives, and functional medicine clinicians combined with secondary validation from customs trade data and cGMP inspection records. Bottom-up capacity modeling and top-down demand estimation triangulate volume figures.
Rate-of-change decomposition across the analysis window segments volume by product format, application tier, end-user sophistication, and distribution channel structure. CAGRs derive from regression analysis against cognitive health supplement demand indices and beverage fortification adoption curves. Forecast inputs incorporate DSHEA compliance timeline distributions and NDI notification approval rates.
Inputs from FDA district office inspection schedules and petrochemical force majeure records were available through the study window; gaps in proprietary contract pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and feedstock supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
US Ingredients Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Shortening Powder Market
Ingredients
Isoamyl Laurate Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Specialty Malt Market
Ingredients
Edible Oils and Fats Market
Ingredients
Gum Arabic Market
Ingredients
Corn Oil Cake Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
South America Lipid Market
Ingredients
Dark Yeast Extract Market
Ingredients
White Wheat Malt Market
Ingredients
Sodium Alginate Market
Ingredients
Clean Label Starch Market