
 United States Protein Market | 2026-2036
United States Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Protein Market Analytics
Fitness enthusiasts and athletes are rebalancing demand away from conventional food applications toward targeted sports nutrition formats. Cargill Inc. leverages its grain processing network to supply plant protein isolates at industrial scale. Kerry Group PLC specializes in flavor-masked protein systems that anchor premium positioning in functional beverages. Glanbia PLC dominates whey protein concentrate production from its Idaho dairy processing base.
United States Protein encompasses nitrogenous organic compounds built from amino acid chains, with complete proteins delivering all nine essential amino acids in ratios matching human metabolic requirements. These macronutrients serve as structural tissue precursors, enzymatic catalysts, and caloric inputs across human nutrition, animal husbandry, and microbial fermentation systems. Animal Protein maintains mature volume leadership but faces margin compression from feed cost volatility. Plant Protein captures the fastest expansion trajectory as pea and fava bean extraction yields improve. Dairy Protein retains the deepest margin pools through isolate and hydrolysate grades targeting clinical nutrition and infant formula.
FDA nutrition labeling standards and USDA organic certification requirements shape protein content claims, amino acid scoring methodology, and ingredient sourcing disclosures across interstate commerce. The EPA regulates rendering facility emissions and wastewater discharge from animal protein processing plants, particularly in Nebraska and Iowa. State-level California Proposition 65 enforcement adds contaminant testing burdens for imported protein concentrates. Stakeholders must monitor pending FDA guidance on fermented and cultivated protein novel food status determinations.
Market Dynamics
The FDA's updated nutrition labeling rules for protein content claims are compressing quality thresholds nationwide, forcing reformulation investments across conventional food processing and sports nutrition channels simultaneously.
Growth Catalysts
- California Proposition 65 enforcement:Contaminant testing burdens for imported protein concentrates are accelerating domestic sourcing investments. Food manufacturers are redirecting procurement toward Idaho and Nebraska processing facilities.
- Sports nutrition channel expansion:Fitness enthusiasts and athletes are pulling volume from traditional food applications toward targeted functional formats. Powder and ready-to-drink systems capture disproportionate margin pools.
- Pea protein extraction yield improvements:Wet fractionation advances are compressing unit costs for plant isolates. Industrial-scale facilities in North Dakota and Montana are achieving parity with soy processing economics.
Market Restraints
- Feed cost volatility:Animal protein margins compress when corn and soybean meal prices spike. Dairy and livestock processors in the Midwest face working capital strain during commodity cycles.
- Rendering facility concentration:EPA-regulated emissions controls and wastewater discharge limits cluster processing in Nebraska and Iowa. Supply disruption risk elevates when regional weather events idle capacity.
- Flavor masking limitations:Pea and fava bean proteins carry persistent off-notes that restrict application in neutral-flavor beverages. Hydrolysate grades require premium positioning to justify sensory investment.
Strategic Opportunities
- Texas livestock processing belt expansion:Underutilized rendering and fractionation infrastructure offers captive supply integration for emerging cultivated protein ventures. Regional feedstock abundance supports backward integration plays.
- Fermented protein novel food status:Pending FDA guidance creates first-mover advantage for biomass-derived ingredients. Fungal and algal protein systems target clinical nutrition and infant formula applications.
- Direct-to-consumer functional food channels:E-commerce subscription models bypass conventional retail slotting constraints. California's functional food corridor anchors brand building with influencer-driven trial.
Industry Challenges
- Amino acid scoring methodology expertise:FDA-compliant protein content claims require analytical chemistry capabilities scarce in mid-tier ingredient suppliers. Certification timelines extend six to eighteen months.
- Organic certification compliance:USDA requirements for ingredient sourcing disclosures create documentation burdens across interstate supply chains. Traceability systems demand IT infrastructure investment.
- Isolate-hydrolysate grade reconfiguration:Legacy spray-drying assets require retrofit for clinical nutrition and infant formula specifications. Capex intensity compresses returns for processors below threshold scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Protein Market |
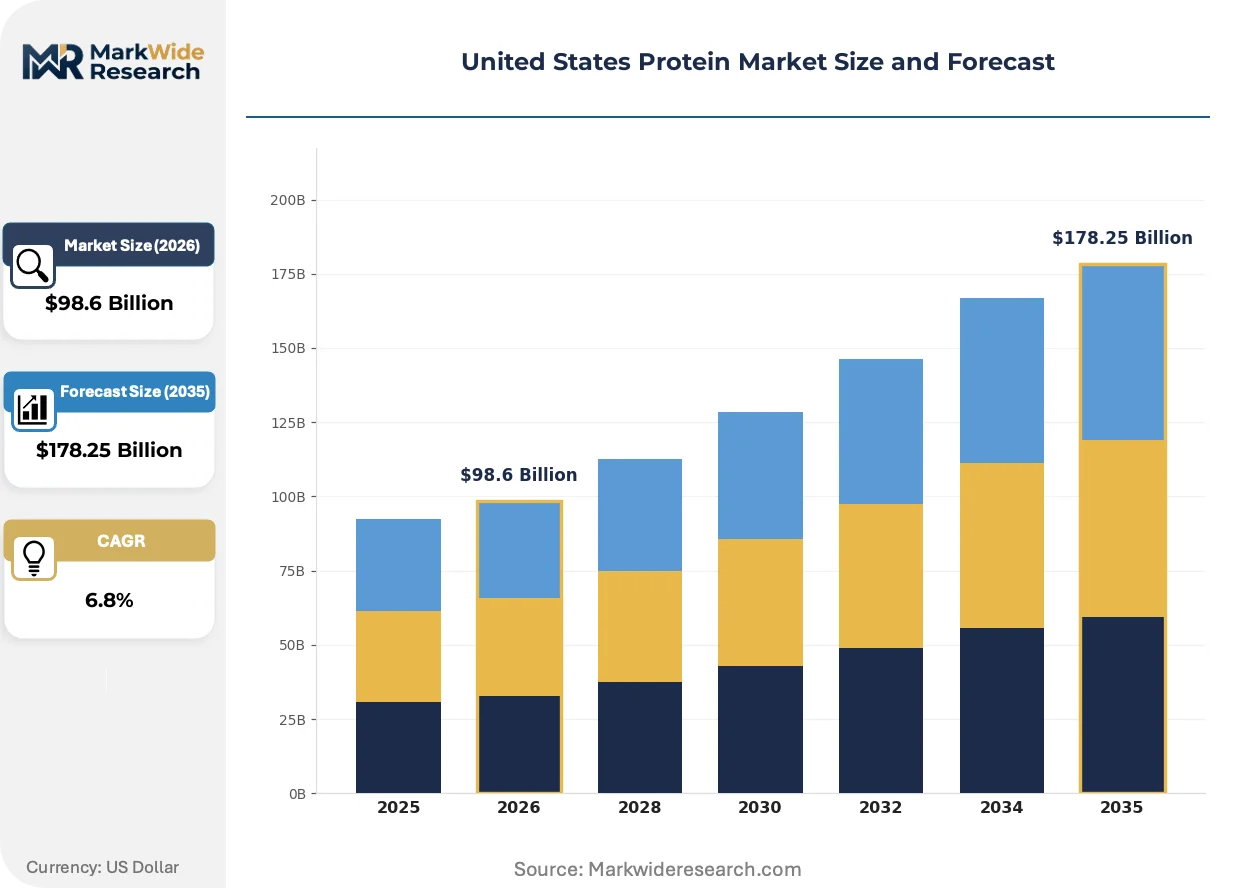
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Protein, Plant Protein, Dairy Protein, Protein Isolates End User: Fitness Enthusiasts, Athletes, Health-conscious Consumers, Nutritional Supplements Application: Food & Beverages, Dietary Supplements, Animal Feed, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., Glanbia PLC, Darling Ingredients Inc., International Flavors & Fragrances Inc., Kerry Group PLC, Ingredion Inc., Roquette Frères, Nestlé S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Protein Market Evolving Landscape
Precision fermentation and biomass cultivation are compressing the innovation cycle for novel protein sources, while regulatory clarity and extraction yield improvements reshape competitive positioning across animal, dairy, and plant segments.
Precision fermentation for whey protein identicals is converging with traditional dairy processing infrastructure. Biotech startups and established ingredient suppliers are deploying capital toward commercial-scale facilities in the Midwest. This technology is converging with conventional margin pools by eliminating feedstock dependency and lactose-containing co-products.
The FDA's pending novel food status determination for fermented and cultivated proteins is forcing pre-market notification investments. Biomass-derived ingredients face amino acid scoring validation requirements that extend approval timelines. Sports nutrition and clinical nutrition segments are front-loading regulatory affairs capacity to secure first-mover positioning.
Subscription-based direct procurement is displacing conventional foodservice distribution for premium protein systems. Functional beverage brands are bypassing retail slotting fees through influencer-driven digital channels. California and Texas metropolitan markets exhibit the highest concentration of digitally native protein brands.
United States Protein Market Segmentation
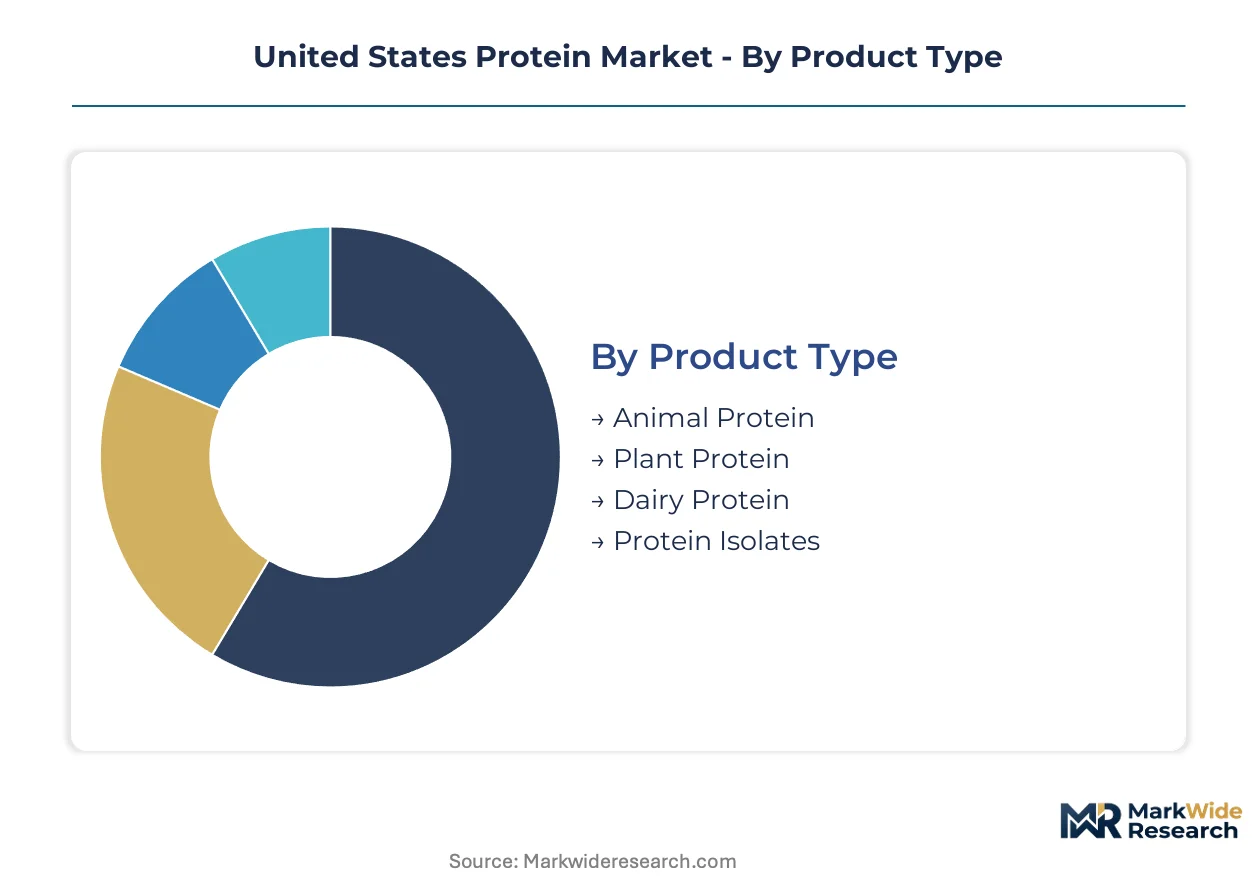
Protein purchasing decisions diverge sharply across user profiles and application contexts, with formulation specifications and channel economics creating distinct competitive arenas. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows commoditize.
Product Type:
Buyers prioritize amino acid completeness and bioavailability scores when selecting protein sources for functional applications.
- Animal Protein:Complete amino acid profiles from rendered meat and poultry byproducts deliver PDCAAS scores near 1.0. Demand concentrates in Nebraska and Iowa processing corridors where EPA-regulated rendering infrastructure clusters, though feed cost volatility compresses margins during commodity spikes.
- Plant Protein:Pea and fava bean isolates achieve expanding application scope as wet fractionation yields improve. North Dakota and Montana industrial facilities are achieving cost parity with soy economics, pulling formulation share from Midwest dairy processors.
- Dairy Protein:Whey concentrates and isolates from Idaho dairy bases retain premium positioning through clinical nutrition and infant formula specifications.
- Protein Isolates:Highly refined fractions with 90%+ protein content command formulation precision in medical and performance nutrition.
Volume sits with Animal Protein; growth tilts toward Plant Protein.
End User:
Usage intensity and nutritional literacy determine willingness to pay for advanced protein formats versus commodity grades.
- Fitness Enthusiasts:Recreational lifters and gym-regulars purchasing powder and ready-to-drink systems through subscription channels. California's functional food corridor anchors influencer-driven trial and brand loyalty formation.
- Athletes:Competitive and professional performers requiring batch-tested, NSF-certified products with documented amino acid profiles. Procurement runs through team nutritionists and institutional buyers with specification authority.
- Health-conscious Consumers:Mainstream shoppers integrating protein fortification into daily diets via conventional retail.
- Nutritional Supplements:Clinical and therapeutic applications including medical foods and meal replacements.
Mass volume flows through Health-conscious Consumers; steepest expansion trajectory belongs to Athletes as certification requirements professionalize purchasing.
Application:
Formulation complexity and regulatory scrutiny separate commodity feed applications from premium human nutrition systems.
- Food & Beverages:Bakery, dairy, and meat processing channels integrating protein fortification into mainstream products. FDA nutrition labeling rules for protein content claims are tightening quality thresholds, forcing reformulation investments across conventional manufacturing.
- Sports Nutrition:Powder, bar, and ready-to-drink formats capturing disproportionate margin pools through targeted functional positioning. Texas and California metropolitan markets exhibit highest concentration of digitally native brands bypassing retail slotting fees.
- Dietary Supplements:Capsule, tablet, and bulk powder formats for wellness-oriented consumption.
- Animal Feed:Rendered protein meals and oilseed meals for livestock and aquaculture nutrition.
Revenue concentrates in Sports Nutrition; volume scale belongs to Food & Beverages.
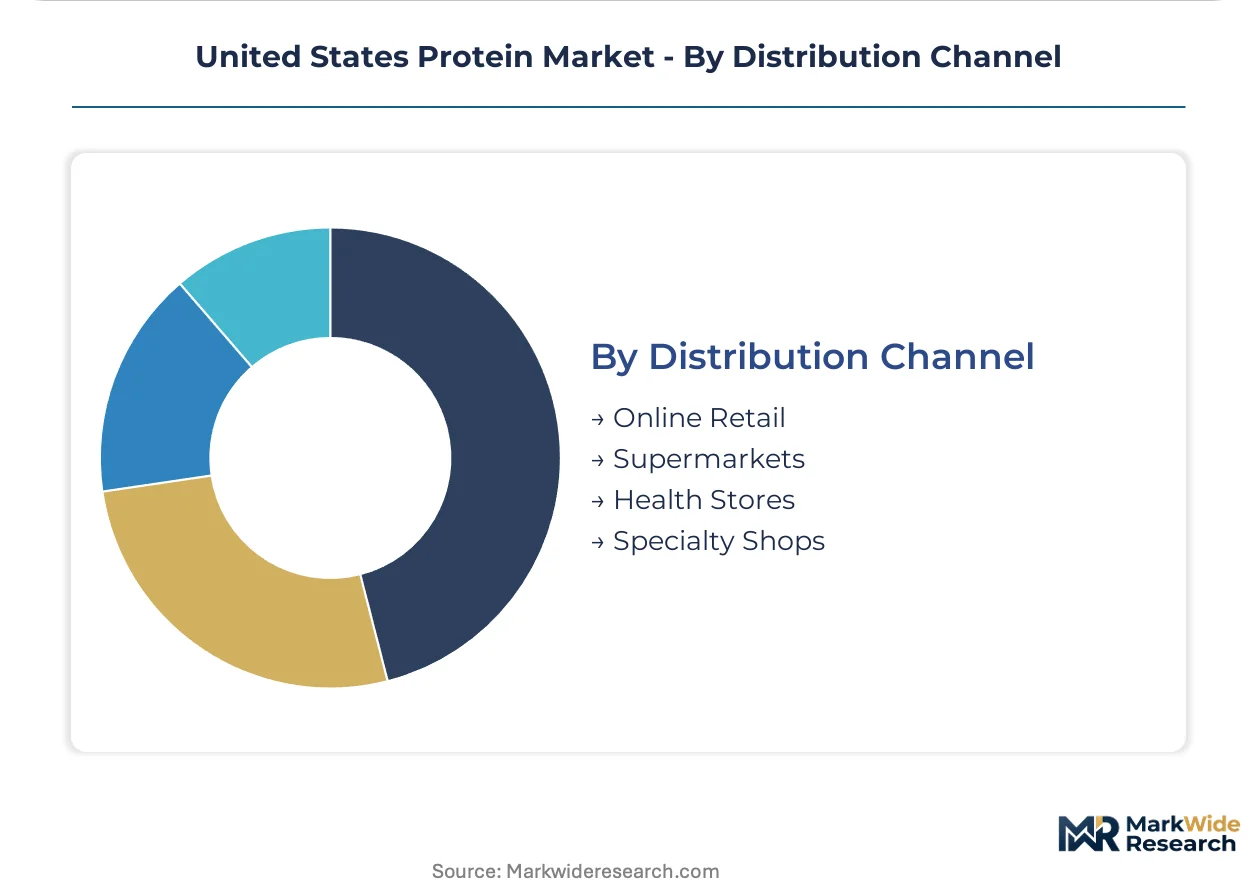
Distribution Channel:
Channel economics and customer acquisition costs determine viable protein price points and brand positioning strategies.
- Online Retail:Direct-to-consumer subscription models capturing lifetime value through automated replenishment. E-commerce infrastructure enables premium protein systems to bypass conventional retail slotting constraints and margin stacking.
- Supermarkets:Mass-market penetration requiring trade promotion investment and shelf-stable formulation compromises.
- Health Stores:Specialty retail with educated staff driving premium product discovery and trial conversion.
- Specialty Shops:Independent fitness and nutrition boutiques serving localized enthusiast communities.
Unit economics favor Online Retail for premium tiers; Supermarkets retain volume dominance for commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production concentrates in livestock processing belts while coastal demand clusters pull supply toward functional food corridors. California and Texas anchor consumption growth through sports nutrition channels. Midwest rendering infrastructure processes the majority of animal-derived inputs.
California
Fitness enthusiasts and health-conscious consumers drive powder and ready-to-drink demand through subscription channels. Proposition 65 enforcement creates contaminant testing burdens for imported concentrates. The San Francisco-Los Angeles functional food corridor anchors influencer-driven brand building and direct-to-consumer trial.
Texas
Livestock processing abundance supports rendering and fractionation infrastructure expansion. EPA emissions controls apply to rendering facility operations statewide. The Dallas-Houston metropolitan belt offers underutilized capacity for emerging cultivated protein ventures seeking backward integration.
Idaho
Dairy protein concentrate production serves clinical nutrition and infant formula specifications. USDA organic certification requirements shape ingredient sourcing disclosures for exported materials. The Magic Valley dairy processing base retains premium positioning through whey isolate and hydrolysate grades.
Nebraska and Iowa
Animal protein rendering clusters face EPA wastewater discharge and emissions regulation concentration. Feed cost volatility from corn and soybean meal price spikes compresses processor margins. The Omaha-Des Moines corridor hosts the densest rendering infrastructure in the nation.
North Dakota and Montana
Pea and fava bean wet fractionation advances are achieving cost parity with soy processing economics. State-level agricultural extension programs support pulse crop expansion for protein isolate feedstock. Industrial-scale facilities in the Northern Plains are pulling formulation share from Midwest dairy processors.
United States Protein Market Competitive Landscape
Top-tier vendors anchor integrated supply chains from grain processing through finished ingredient systems, while mid-tier specialists concentrate on flavor-masked formulations and certification-grade isolates. The market structure tilts toward scale-driven consolidation in animal and dairy segments, with plant protein exhibiting more fragmented entry patterns. Three archetypes dominate: agricultural conglomerates with captive raw material access, dairy cooperatives with clinical-grade fractionation assets, and biotech-enabled precision fermentation ventures. Competitive moves center on capacity expansion in pea protein wet fractionation and strategic partnerships bridging conventional rendering with novel biomass cultivation.
Within the agricultural conglomerate tier, Cargill Inc. and Archer Daniels Midland Company exemplify scale-driven supply integration from field to isolate. Glanbia PLC occupies a position representing dairy cooperative evolution toward clinical nutrition and sports nutrition premium tiers. Kerry Group PLC sits within the formulation specialist archetype, anchoring flavor-system expertise that enables neutral-beverage applications for plant-derived inputs.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| Glanbia PLC |
| Darling Ingredients Inc. |
| International Flavors & Fragrances Inc. |
| Kerry Group PLC |
| Ingredion Inc. |
| Roquette Frères |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Fitness enthusiasts and athletes purchasing through subscription channels concentrate demand-pull in premium isolate and hydrolysate grades, anchoring a three-tier pricing structure across premium, standard, and economy levels that reflects certification burden and extraction complexity differentials.
Pricing Analysis
Margin tightening in clinical-grade whey isolates reflects FDA amino acid scoring compliance costs and extended certification timelines. Pricing stratifies across premium, standard, and economy tiers based on PDCAAS validation status and organic certification level. Cost-down pressure on commodity animal protein accelerates because feed cost volatility compresses processor margins during corn and soybean meal spikes. Health-conscious consumers in conventional retail channels exhibit highest price sensitivity, while athletes purchasing NSF-certified products show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Nebraska and Iowa rendering infrastructure clustering under EPA emissions and wastewater discharge regulation. Raw material flows draw from Idaho dairy bases, North Dakota pulse crops, and Texas livestock processing belts. Supply chain risk centers on regional weather events idling concentrated rendering capacity. Distribution runs through direct-to-consumer subscription models bypassing conventional retail slotting constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
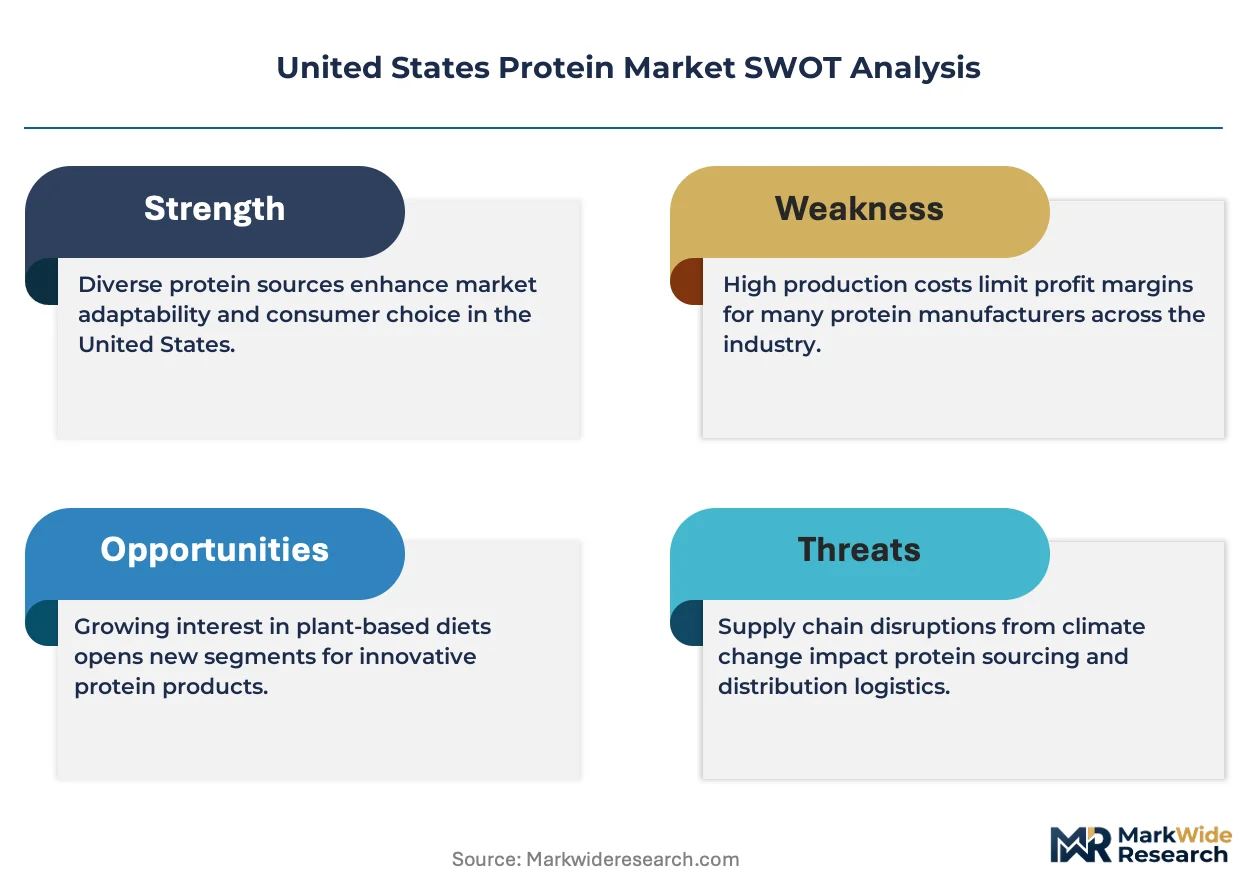
The United States Protein Market operates as a cost-of-compliance story where FDA's pending novel food status determination for fermented and cultivated proteins creates a barrier-to-entry moat for players with pre-market notification investments and regulatory affairs capacity.
For Market Incumbents: Anchor premium positioning through backward integration into Idaho dairy fractionation assets and Nebraska rendering infrastructure to secure captive supply against feed cost volatility. Defend market share by accelerating clinical-grade isolate-hydrolysate retrofit investments before threshold scale requirements harden. Prioritize regulatory affairs capacity buildout to secure first-mover positioning in fermented protein novel food status determinations. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route to bypass retail slotting fees and margin stacking incumbent food manufacturers face. Target California's functional food corridor for influencer-driven brand building and Texas metropolitan markets for sports nutrition trial conversion. Pursue white-space positioning in flavor-masked plant protein systems for neutral-beverage applications where sensory limitations restrict incumbent formulation scope. For Investors and Strategic Acquirers: The window for entry favors precision fermentation ventures with commercial-scale facility commitments in the Midwest and biomass cultivation players targeting clinical nutrition specifications. Long-term viability hinges on regulatory clarity timelines and extraction yield improvements compressing unit economics. Watch FDA guidance publication on fermented protein novel food status as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pea Protein Wet Fractionation Capacity Expansion | North Dakota and Montana facilities achieving soy parity economics pull formulation share from dairy processors. |
| Clinical-Grade Isolate-Hydrolysate Retrofit | Legacy spray-drying assets require capex intensity that compresses returns below threshold scale. |
| Direct-to-Consumer Subscription Launch | California and Texas digitally native brands bypass retail slotting fees through influencer-driven trial. |
| Precision Fermentation Commercial Scale-Up | Midwest facilities eliminate feedstock dependency and lactose-containing co-products from whey production. |
| Regulatory Affairs Capacity Buildout | FDA pre-market notification investments secure first-mover positioning in pending novel food status determinations. |
Research Methodology
Document review covered FDA guidance publications, EPA emissions filings, and USDA organic certification databases, complemented by interviews with protein processing plant managers, sports nutrition brand executives, clinical nutrition procurement leads, and agricultural cooperative technical directors. Secondary validation drew from SEC 10-K filings, customs trade data, and state agricultural extension reports. Bottom-up capacity modeling and top-down demand segmentation were triangulated against industry stakeholder inputs.
Segmentation outputs reflect product type, end user profile, application context, and distribution channel dynamics across the analysis window. CAGRs were derived from historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs incorporated wet fractionation yield improvement curves and regulatory approval timeline assumptions for novel protein sources.
Inputs from FDA pre-submission meetings and state-level agricultural extension programs were available through the study window; gaps in pending novel food status determination timelines introduce uncertainty bands around fermented protein adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Ingredients Market
Ingredients
Stock Cubes Market
Ingredients
Plant Based Thickener Market
Ingredients
Malted Wheat Flour Market
Ingredients
Malted Barley Flour Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Bouillon Cubes Market
Ingredients
Caramel Ingredient Market
Ingredients
Specialty Starch Market
Ingredients
Yeast Derivatives Market
Ingredients
Non-GMO Oil Market
Ingredients
Pomace Olive Oil Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Orange Powder Market
Ingredients
Germany Protein Market