
 Renal Drugs Market | 2026-2036
Renal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Drugs Market Analytics
Project finance partnerships between specialty pharmaceutical firms and dialysis chains is rewriting capital deployment across nephrology care networks. Amgen Inc. leverages its biologics manufacturing scale to maintain supply security for erythropoiesis-stimulating agents. AstraZeneca anchors its position through deep clinical investment in sodium-glucose cotransporter 2 inhibitors. Pfizer Inc. competes by extending its hospital formulary relationships into outpatient renal care settings.
Renal drugs comprise pharmaceutical agents engineered to modulate kidney function, electrolyte balance, and hematologic parameters in patients with impaired renal physiology; these therapies typically require dose adjustment based on glomerular filtration rate and are manufactured under sterile conditions for parenteral formats. Their primary purpose centers on delaying disease progression, managing complications of uremia, and reducing cardiovascular mortality in chronic kidney disease populations. Erythropoiesis-stimulating agents retain the largest revenue share due to their entrenched position in anemia management protocols, while sodium-glucose cotransporter 2 inhibitors represent the fastest-expanding category as cardiorenal protective indications broaden. Injectable delivery modes command premium pricing relative to oral formulations, reflecting the complexity of biologic stabilization and cold-chain logistics.
The FDA maintains stringent bioequivalence requirements for generic renal therapies, while the EMA's MDR framework elevates clinical evidence standards for dialysis-associated devices and companion diagnostics. The EU Green Deal's pharmaceutical waste directives are pressuring manufacturers to reformulate phosphate binders with reduced environmental persistence. Stakeholders must monitor how reimbursement shifts toward value-based kidney care models reshape prescribing incentives and product mix across integrated delivery networks.
Market Dynamics
Medicare reimbursement compression is forcing dialysis chains to consolidate formularies around value-proven therapies, creating winner-take-all dynamics for agents with robust cardiovascular outcome data.
Growth Catalysts
- Cardiorenal protective labeling expansion:Sodium-glucose cotransporter 2 inhibitors now carry indications spanning heart failure and chronic kidney disease progression, triggering protocol updates across integrated care networks.
- EU Green Deal pharmaceutical waste mandates:Reformulation requirements for phosphate binders are accelerating biodegradable excipient innovation, opening premium positioning for compliant manufacturers.
- Dialysis center outpatient expansion:Freestanding clinic networks are extending nephrology management beyond acute settings, creating pull-through demand for subcutaneous administration formats.
Market Restraints
- Biologic cold-chain cost inflation:Erythropoiesis-stimulating agents require continuous temperature-controlled logistics, with energy and specialized transport costs compressing margins on parenteral formulations.
- FDA bioequivalence stringency for generics:Complex pharmacokinetic requirements for renal-adjusted dosing create multi-year approval timelines, limiting price competition in established therapeutic classes.
- Single-source plasma protein dependency:Albumin and immunoglobulin supply concentrates among fractionators in the United States, exposing formularies to batch contamination or viral screening disruption risks.
Strategic Opportunities
- Home dialysis penetration gaps:Peritoneal dialysis remains underutilized relative to hemodialysis in the United States, creating white space for portable drug delivery systems and patient-administered therapies.
- Companion diagnostic integration:Pharmacogenomic testing for drug metabolism variants is converging with nephrology protocols, enabling personalized erythropoietin dosing and premium pricing capture.
- IRA Medicare price negotiation carve-outs:Small-molecule renal therapies face delayed negotiation timelines relative to biologics, preserving pricing flexibility for oral agents through mid-decade.
Industry Challenges
- Nephrology clinical trial recruitment scarcity:Chronic kidney disease populations carry high comorbidity burden, slowing enrollment for novel mechanism studies and extending development timelines.
- Legacy electronic health record interoperability:Glomerular filtration rate calculation protocols vary across Epic, Cerner, and Meditech installations, complicating automated dose adjustment algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Drugs Market |
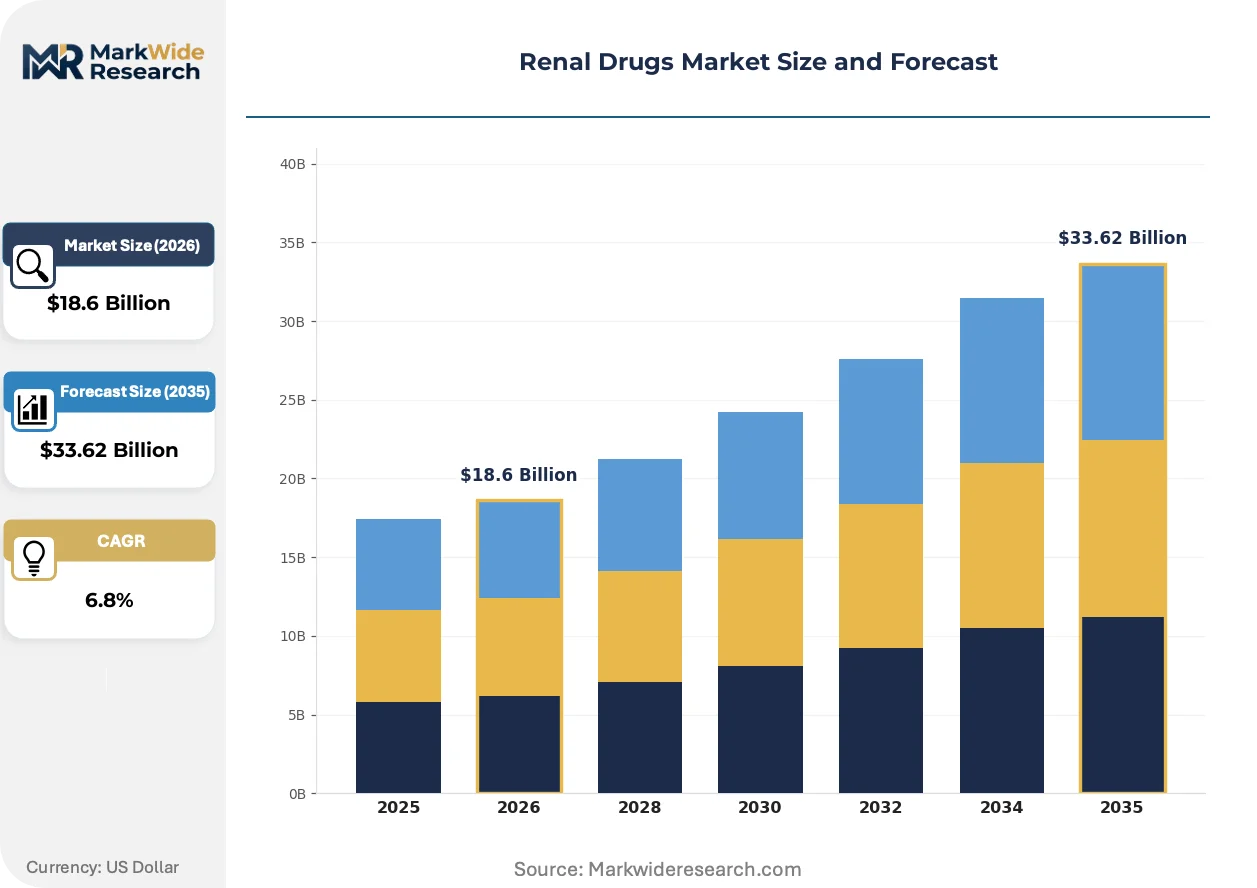
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angiotensin Receptor Blockers, Phosphate Binders, Erythropoiesis-Stimulating Agents, Sodium-Glucose Cotransporter 2 Inhibitors Therapy Area: Chronic Kidney Disease, Acute Kidney Injury, Nephrotic Syndrome, Hypertension Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Home Care, Dialysis Centers |
| Companies Covered | AstraZeneca, Amgen Inc., Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Sanofi, Merck & Co. Inc., Johnson & Johnson, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Drugs Market Evolving Landscape
Renal therapeutics are converging around precision dosing platforms and care setting migration, with technology vendors and pharmaceutical developers racing to capture value from kidney disease management decentralization.
Continuous glucose monitoring sensors are hybridizing with renal function biomarker detection, creating dual-parameter wearable devices that track glycemic control and early kidney injury indicators simultaneously. Dialysis chains in the United States are piloting these integrated monitors for high-risk diabetic nephropathy populations. The convergence is compressing acute event detection timelines and enabling preemptive intervention protocols that reduce hospitalization rates.
The EMA's Medical Device Regulation framework is elevating clinical evidence requirements for dialysis-associated companion diagnostics, mandating prospective outcome studies for algorithm-based dosing tools. European manufacturers are restructuring regulatory submissions to incorporate real-world evidence from nephrology registries. This policy shift is favoring established diagnostic platforms with existing clinical databases while raising capital barriers for point-of-care testing entrants.
Integrated delivery networks are consolidating formulary decision authority into centralized pharmacy and therapeutics committees, displacing individual nephrologist prescribing autonomy. United States-based health systems are deploying value-based kidney care contracts that tie pharmaceutical reimbursement to composite quality metrics. This behavioral shift concentrates demand among formulary winners and accelerates generic substitution for therapies without differentiated outcome data.
Renal Drugs Market Segmentation
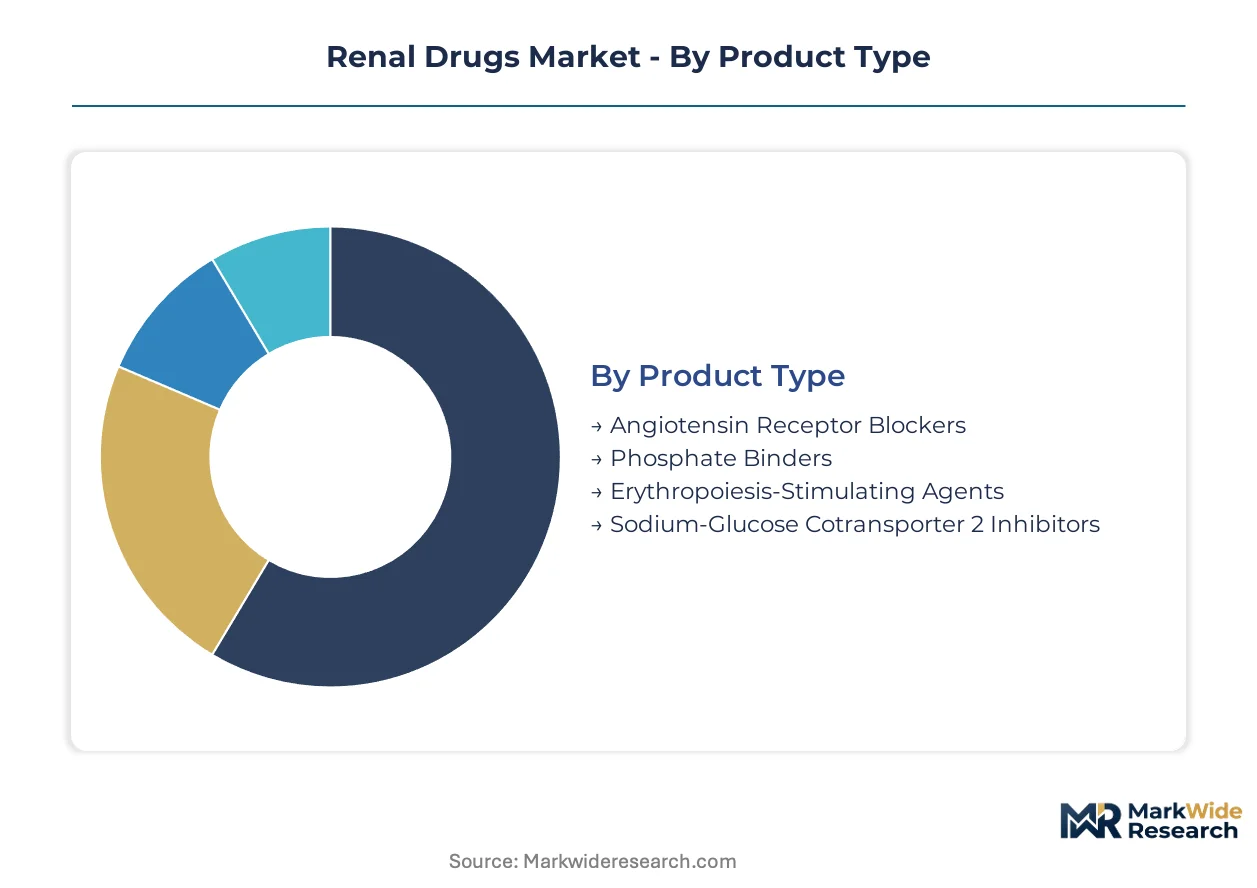
Renal drug segmentation reveals how therapy selection maps to disease severity, care setting economics, and administration logistics. Manufacturers align portfolio investments with the highest-margin delivery modes and fastest-expanding therapy areas.
Product Type:
The use-case spectrum spans cardiovascular comorbidity management to mineral bone disorder correction, with each class carrying distinct reimbursement and manufacturing profiles.
- Erythropoiesis-Stimulating Agents:Recombinant proteins stimulating red blood cell production in bone marrow; demand concentrates in United States dialysis centers where Medicare bundled payments incentivize anemia control. Cold-chain distribution requirements sustain premium pricing against oral alternatives.
- Sodium-Glucose Cotransporter 2 Inhibitors:Small-molecule oral agents blocking renal glucose reabsorption; cardiorenal protective labeling expansion is pulling demand from endocrinology into nephrology protocols across integrated delivery networks. IRA Medicare negotiation timelines favor these agents through mid-decade.
- Phosphate Binders:Polymeric or metallic compounds reducing intestinal phosphate absorption; EU Green Deal waste mandates are forcing excipient reformulation toward biodegradable alternatives.
- Angiotensin Receptor Blockers:Antihypertensive agents modulating renin-angiotensin-aldosterone system; generic competition has compressed margins, though fixed-dose combinations with SGLT2 inhibitors preserve value.
The dominant share belongs to Erythropoiesis-Stimulating Agents, while Sodium-Glucose Cotransporter 2 Inhibitors is closing the gap fastest.
Therapy Area:
Cost tier differentiation separates chronic maintenance populations from acute intervention cases, with reimbursement intensity varying by disease progression stage.
- Chronic Kidney Disease:Progressive renal function decline requiring long-term pharmaceutical management; United States Medicare Advantage plans are deploying value-based kidney care contracts that tie drug reimbursement to composite quality metrics including hospitalization avoidance.
- Acute Kidney Injury:Sudden renal function deterioration often requiring inpatient intervention; demand clusters in hospital intensive care units where continuous renal replacement therapy protocols drive intravenous drug utilization.
- Hypertension:Elevated blood pressure frequently preceding or accompanying renal impairment; protocol standardization around combination therapies is reducing single-agent prescribing autonomy.
- Nephrotic Syndrome:Glomerular filtration barrier dysfunction marked by proteinuria; corticosteroid-sparing immunosuppressant demand concentrates in pediatric and steroid-resistant adult populations.
Chronic Kidney Disease commands the largest patient volume, though Acute Kidney Injury exhibits the steepest per-episode pharmaceutical intensity.
Delivery Mode:
Volume concentration favors oral formats, while margin capture concentrates in parenteral administration requiring specialized manufacturing and logistics infrastructure.
- Injectable:Parenteral formulations including pre-filled syringes and auto-injectors; dialysis center outpatient expansion is creating pull-through demand for subcutaneous erythropoiesis-stimulating agent administration.
- Oral:Tablet and capsule formulations enabling patient self-administration; SGLT2 inhibitor growth is expanding this segment's share within nephrology formularies.
- Intravenous:Direct vascular administration in supervised clinical settings; iron supplementation and emergency hyperkalemia management sustain demand in hospital infusion centers.
- Subcutaneous:Tissue-layer injection enabling home administration; peritoneal dialysis penetration gaps in the United States are limiting expansion relative to hemodialysis-linked intravenous routes.
Oral delivery maintains volume leadership, yet Injectable formats sustain the highest revenue per dose administered.
End User:
Customer type fragmentation reflects care migration from acute hospitals toward outpatient and home settings, with procurement authority consolidating into centralized pharmacy committees.
- Dialysis Centers:Freestanding clinics providing chronic renal replacement therapy; United States-based chains are consolidating formularies around value-proven therapies with robust cardiovascular outcome data.
- Hospitals:Acute care facilities managing inpatient nephrology consultations; formulary relationships are extending into outpatient renal care settings through integrated delivery network structures.
- Home Care:Patient-administered therapy in residential settings; portable drug delivery systems are targeting underutilized peritoneal dialysis populations.
- Clinics:Physician office-based nephrology practices; reimbursement compression is displacing individual prescriber autonomy toward centralized pharmacy and therapeutics committee control.
Dialysis Centers capture the dominant prescription volume, while Home Care is gaining share fastest as care decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement policies concentrate purchasing power among United States dialysis chains, while EU regulatory frameworks reshape manufacturing standards for phosphate binders. Japan's aging demographics sustain demand for erythropoiesis-stimulating agents, and India's domestic production capacity expands to serve chronic kidney disease populations across South Asia.
United States
Dialysis center consolidation around value-proven therapies with cardiovascular outcome data drives formulary decision-making. The IRA Medicare price negotiation program creates differentiated timelines for small-molecule versus biologic therapies. Boston's clinical research corridor anchors nephrology trial infrastructure, with Massachusetts General Hospital and Brigham and Women's Hospital enrolling substantial chronic kidney disease cohorts.
Germany
Integrated care contracts for kidney disease management concentrate pharmaceutical procurement within sickness fund networks. The EMA's Medical Device Regulation elevates evidence requirements for dialysis companion diagnostics. Baden-Württemberg's medical technology cluster around Tübingen and Freiburg hosts manufacturers developing real-world evidence platforms for algorithm-based dosing tools.
Japan
Super-aging demographics expand the chronic kidney disease patient pool requiring long-term pharmaceutical management. PMDA's streamlined review pathways for designated orphan drugs accelerate access for rare nephropathy therapies. The Kansai region's pharmaceutical manufacturing base around Osaka supplies domestic demand while exporting to Southeast Asian markets.
China
Urbanization-linked diabetes prevalence generates expanding cardiorenal protective therapy demand. NMPA's priority review channels for breakthrough therapies compress approval timelines for novel mechanism drugs. The Yangtze River Delta's biopharma corridor around Shanghai and Suzhou attracts multinational renal drug manufacturing investments.
India
Rising hypertension and diabetes incidence drives chronic kidney disease pharmaceutical consumption across tier-1 and tier-2 cities. CDSCO's accelerated approval pathways for drugs addressing unmet medical needs facilitate market entry for innovative therapies. Hyderabad's active pharmaceutical ingredient manufacturing cluster supplies generic renal drug precursors to formulation facilities in Maharashtra and Gujarat.
Renal Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across nephrology formularies, with dialysis chain procurement consolidation favoring scale-backed suppliers over niche entrants. The market structure exhibits tiered concentration: multinational biopharmaceuticals with integrated manufacturing and distribution infrastructure occupy premium positions, while regional generic manufacturers capture volume in mature therapeutic classes. Three archetypes dominate: cardiovascular outcome data leaders, cold-chain logistics specialists, and phosphate binder reformulation innovators. Competitive dynamics center on Medicare bundling contract capture and EU Green Deal compliance positioning for environmental sustainability credentials.
Among the multinational biopharmaceutical tier, AstraZeneca exemplifies the cardiovascular outcome data archetype through deep clinical investment in sodium-glucose cotransporter 2 inhibitors, while Amgen Inc. occupies a position anchored in biologics manufacturing scale for erythropoiesis-stimulating agents. Pfizer Inc. represents the hospital formulary extension strategy, leveraging acute care relationships into outpatient renal care settings. These three companies illustrate how divergent capability bases—clinical trial infrastructure, manufacturing scale, and institutional distribution—create distinct competitive positions within the same therapeutic landscape.
| Leading Market Players |
|---|
| AstraZeneca |
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Hyderabad's active pharmaceutical ingredient manufacturing cluster anchors global supply for generic renal drug precursors, with capacity utilization rates directly transmitting into downstream formulation pricing power across Indian and export markets.
Pricing Analysis
Certification level creates the primary spread between FDA-grade biologics and regional-standard generics in this market. Injectable erythropoiesis-stimulating agents command premium positioning against oral alternatives due to cold-chain complexity and sterile manufacturing requirements. Cost compression in phosphate binders is intensifying because EU Green Deal waste mandates force excipient reformulation investments. Dialysis chains exhibit lowest price sensitivity for cardiovascular outcome-proven therapies, while clinic-based nephrologists face highest sensitivity under Medicare reimbursement compression.
Supply Chain Analysis
Extended payment terms from dialysis chain procurement departments are reshaping supplier working capital requirements across the value chain. Manufacturing concentration rests on the United States for biologic fractionation, India for generic API synthesis, and China for intermediate chemical production. Plasma protein supply draws from single-source fractionators, creating batch contamination exposure. Tariff exposure on Chinese-sourced raw materials presents structural vulnerability. Distribution runs through cold-chain logistics specialists serving dialysis center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renal drugs sector represents high-growth disruption as cardiorenal protective labeling expansion triggers protocol updates across integrated care networks.
For Market Incumbents: Build cardiovascular outcome data moats through continued investment in sodium-glucose cotransporter 2 inhibitor trials. Consolidate formulary relationships with United States dialysis chains before Medicare price negotiation timelines compress. Address biologic cold-chain cost inflation through manufacturing scale efficiencies. Leverage hospital formulary extensions into outpatient renal care settings. For New Entrants and Emerging Players: Establish a beachhead in home dialysis drug delivery systems where peritoneal dialysis penetration gaps create white space. Target portable subcutaneous administration formats for patient-administered therapies in residential settings. Pursue companion diagnostic integration for pharmacogenomic-enabled erythropoietin dosing as premium pricing capture mechanism. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors phosphate binder reformulation innovators with EU Green Deal compliance credentials. Five-to-ten year viability hinges on value-based kidney care contract capture rather than volume-based dispensing. Monitor Medicare bundling contract awards as inflection indicator for formulary consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcome studies for SGLT2 inhibitors secure nephrology protocol inclusion. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses timelines for novel mechanism renal drugs. |
| Manufacturing Scale-Up | Biologics capacity expansion secures supply security for erythropoiesis-stimulating agents. |
| Pipeline Diversification | Companion diagnostic development enables personalized dosing premium capture. |
| Strategic Partnership | Project finance alliances with dialysis chains rewrite capital deployment across networks. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare reimbursement data, dialysis chain financial disclosures, and nephrology registry publications. Bottom-up prescription volume modeling and top-down pharmaceutical spending analysis were triangulated for convergence.
Assumptions held fixed include current Medicare bundling contract structures and IRA price negotiation timelines, while variables included SGLT2 inhibitor labeling expansion rates and home dialysis penetration trajectories. Segmentation dimensions spanned product type, therapy area, delivery mode, and end-user setting across the projection horizon. CAGRs were derived from patient population growth, therapy adoption curves, and pricing trajectory modeling informed by reimbursement policy shifts.
Sensitivities concentrate around FDA bioequivalence stringency changes, EU Green Deal implementation pace, and dialysis center consolidation velocity. Forecasts reflect documented assumptions regarding regulatory pathway stability and care setting migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Global Diphenhydramine Market