
 Global PD-1 and PD-L1 Inhibitors Market | 2026-2036
Global PD-1 and PD-L1 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global PD-1 and PD-L1 Inhibitors Market Foresight
Next-generation biologics manufacturing standards are reorganizing competitive dynamics across the PD-1 and PD-L1 landscape. Merck & Co. leverages its pembrolizumab franchise to sustain manufacturing scale advantages in intravenous formulations. Bristol-Myers Squibb anchors its position through nivolumab specialization across solid tumor indications. Roche differentiates via atezolizumab development in combination regimens for hematology applications.
PD-1 and PD-L1 inhibitors constitute monoclonal antibodies engineered to block programmed cell death protein 1 or its ligand, restoring T-cell mediated anti-tumor immune response through checkpoint blockade. These agents require cold-chain distribution, sterile fill-finish capabilities, and glycosylation-controlled bioreactor production to maintain binding affinity and pharmacokinetic stability. Pembrolizumab and nivolumab command the largest revenue pools within product type segmentation, while subcutaneous delivery modes represent the fastest-growing administration category as patient convenience drives formulation investment. Oncology dominates therapy area allocation, though immunology applications are expanding into checkpoint inhibitor adjuvant settings.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines while demanding confirmatory trial commitments. China's NMPA has expanded its breakthrough therapy designation to prioritize domestic PD-1 filings, altering market access sequencing for multinational sponsors. Japan's PMDA maintains stringent GMP inspection protocols that filter manufacturing site eligibility. Stakeholders must monitor evolving FDA confirmatory trial enforcement patterns and NMPA localization incentives to calibrate portfolio and partnership decisions.
Market Dynamics
Subcutaneous formulation development is fragmenting the intravenous-dominated administration paradigm, forcing manufacturers to reconfigure fill-finish investments and cold-chain logistics around patient convenience metrics rather than hospital infusion center economics.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-market timelines for breakthrough-designated checkpoint inhibitors, enabling earlier revenue recognition contingent on confirmatory trial execution.
- China NMPA Localization Incentives:Domestic breakthrough therapy designations prioritize local PD-1 filings, redirecting multinational partnership strategies toward joint ventures with Chinese biologics manufacturers.
- Adjuvant Oncology Expansion:Early-stage tumor settings are absorbing checkpoint inhibitors previously restricted to metastatic lines, multiplying addressable patient populations per approved molecule.
Market Restraints
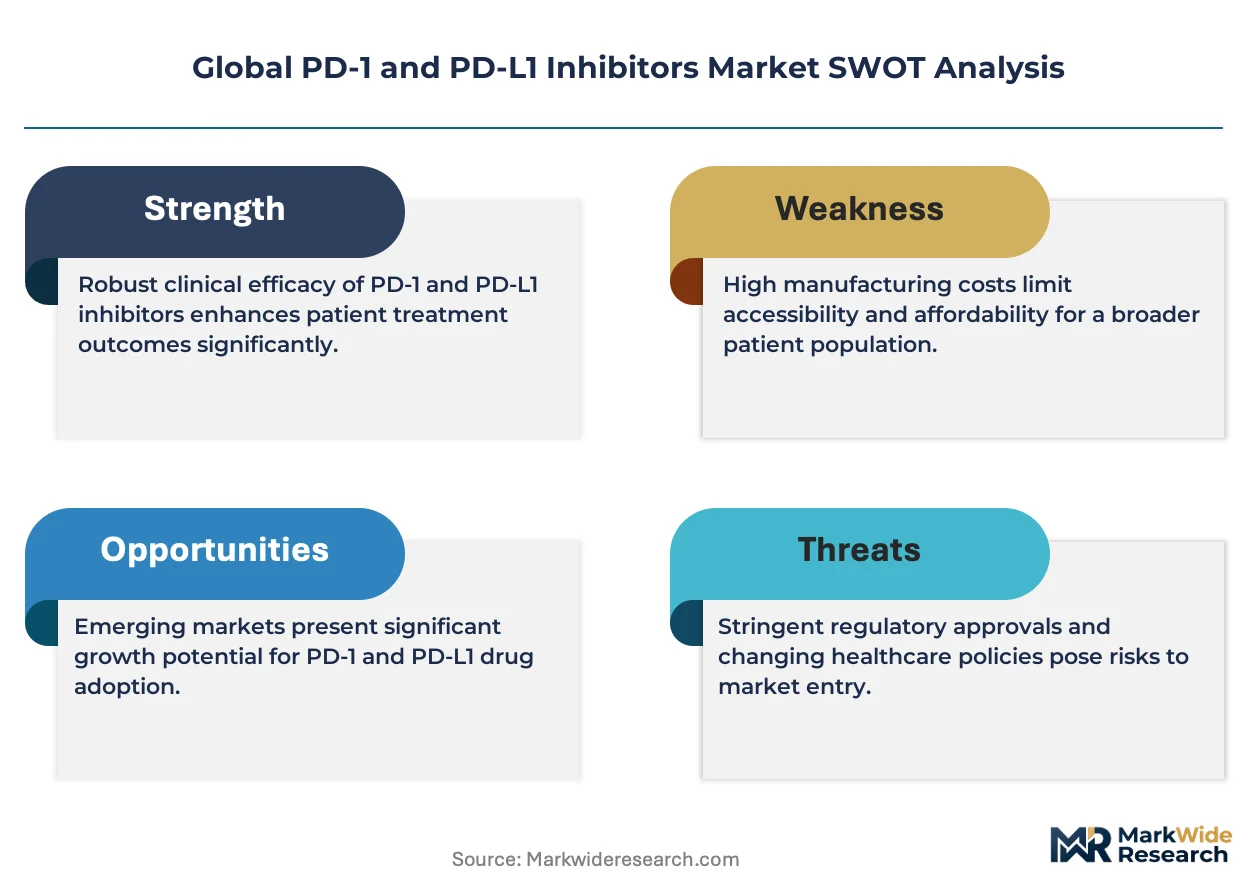
- Bioreactor Capacity Concentration:Glycosylation-controlled mammalian cell production concentrates among a limited contract manufacturing base in Switzerland and Singapore, creating single-source vulnerability for sterile drug substance.
- EMA Conditional Marketing Authorization Enforcement:Confirmatory trial failure risks trigger withdrawal mechanisms that destabilize revenue forecasting for conditionally approved combination regimens.
- Biosimilar Pipeline Maturation:Patent cliff proximity for first-generation PD-1 antibodies enables substitutable follow-on biologics that compress pricing power ahead of loss-of-exclusivity dates.
Strategic Opportunities
- Japan PMDA GMP Inspection Arbitrage:Manufacturers achieving PMDA-certified sterile fill-finish status gain preferred supplier positioning across Asia-Pacific hospital networks requiring Japanese regulatory equivalency.
- Immunology Adjuvant Settings:Autoimmune applications beyond oncology represent unpenetrated demand pools where checkpoint modulation could redefine standard-of-care in lupus and rheumatoid arthritis.
- Dual Carbon Goals in China:NMPA-aligned sustainability mandates for biologics manufacturing create first-mover advantage for facilities deploying energy-efficient single-use bioreactor systems.
Industry Challenges
- Cold-Chain Distribution Integrity:Temperature excursion risks during last-mile delivery to outpatient clinics demand redundant monitoring infrastructure that elevates operational complexity.
- Confirmatory Trial Recruitment Velocity:Patient accrual bottlenecks in competitive immuno-oncology trials delay regulatory confirmation and jeopardize accelerated approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PD-1 and PD-L1 Inhibitors Market |
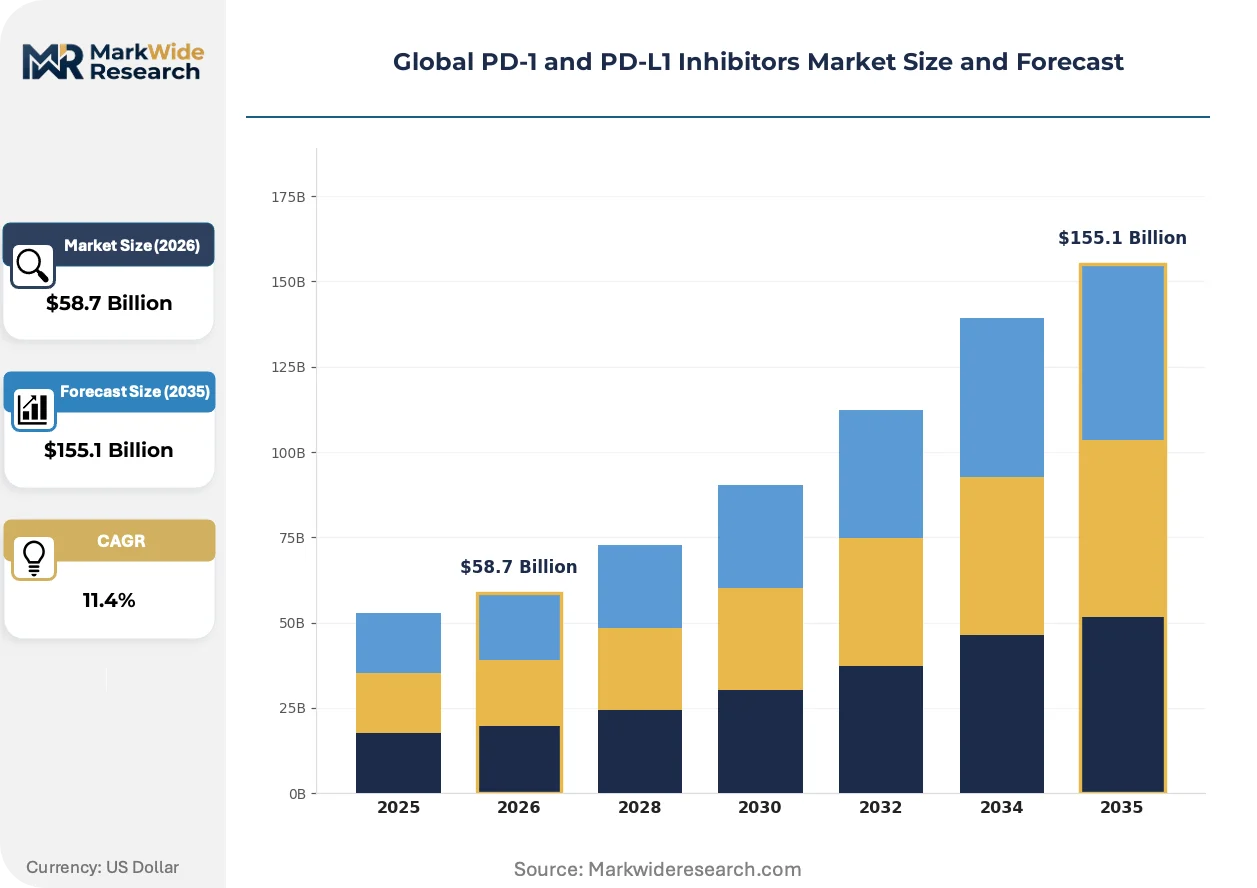
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pembrolizumab, Nivolumab, Atezolizumab, Durvalumab Therapy Area: Oncology, Hematology, Immunology, Dermatology Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Clinics, Research Laboratories, Cancer Treatment Centers |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, Roche, AstraZeneca, Pfizer, Ono Pharmaceutical, Regeneron Pharmaceuticals, GlaxoSmithKline, Jiangsu Hengrui Medicine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PD-1 and PD-L1 Inhibitors Market Shifts & Advancements
Biologics manufacturing modalities and regulatory submission pathways are undergoing parallel transformation, with formulation science and real-world evidence requirements converging to redefine competitive differentiation.
Subcutaneous delivery technologies are fragmenting the historical intravenous monopoly in checkpoint inhibitor administration. Oncology outpatient centers in Germany and the United States are adopting prefilled syringe and autoinjector formats to reduce chair time and infusion center overhead. This shift is compressing the addressable market for traditional hospital-based infusion services while expanding community clinic and home administration channels.
EMA's expanded real-world evidence guidance for conditional marketing authorization renewals is reshaping post-approval data collection obligations. Manufacturers must now integrate electronic health record networks and patient registries into pharmacovigilance infrastructure from launch rather than retrofitting compliance systems. Hematology combination regimens face the steepest evidence generation requirements under this framework.
Hospital procurement consolidation across France and the Netherlands is compressing vendor panels and demanding outcome-based contracting mechanisms. Single-source agreements for checkpoint inhibitor portfolios are displacing multi-supplier arrangements that previously segmented indications across competing antibodies. This concentration is most visible in academic medical center networks where pharmacy and therapeutics committees wield centralized formulary authority.
Global PD-1 and PD-L1 Inhibitors Market Segmentation
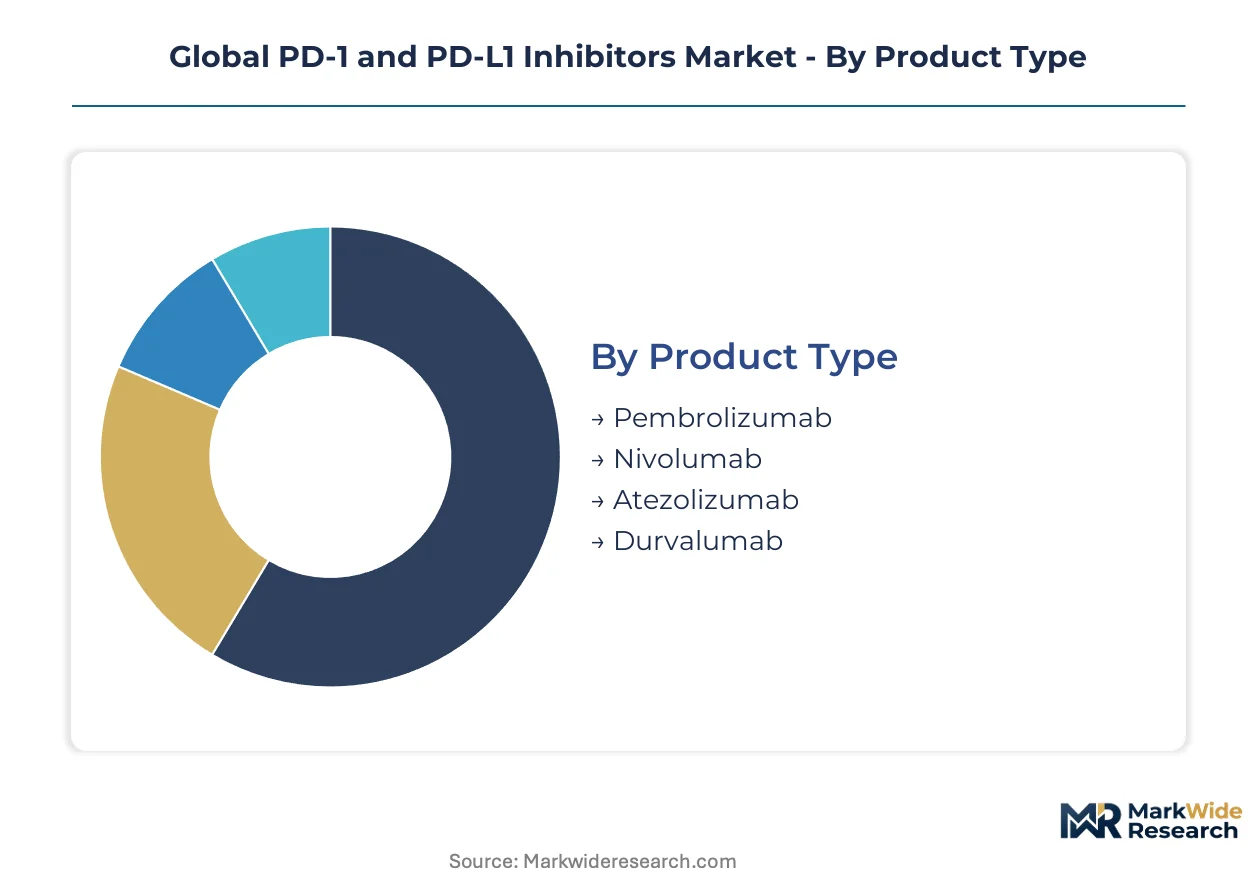
Checkpoint inhibitor commercialization demands precise segment targeting. Formulation technology, clinical setting, and reimbursement pathways create divergent margin profiles across the value chain.
Product Type:
Pembrolizumab and nivolumab anchor the highest-margin revenue pools, while newer entrants compete on combination regimen positioning.
- Pembrolizumab:A humanized monoclonal antibody targeting PD-1 with established efficacy across melanoma, NSCLC, and head and neck squamous cell carcinoma. Merck & Co. commands premium positioning through first-line oncology approvals in the United States and Japan, where reimbursement rates support intravenous infusion economics.
- Nivolumab:Bristol-Myers Squibb's fully human PD-1 antibody with differentiated renal cell carcinoma and Hodgkin lymphoma indications. Manufacturing scale advantages in Singapore-based bioreactor facilities supply hospital networks across Germany and France with cold-chain reliability.
- Atezolizumab:Roche's PD-L1 inhibitor engineered for bladder cancer and triple-negative breast cancer combinations. Demand concentrates in academic medical centers pursuing biomarker-driven patient selection.
- Durvalumab:AstraZeneca's PD-L1 antibody positioned for unresectable stage III NSCLC consolidation therapy. Post-chemoradiation protocols in United Kingdom cancer centers drive prescription volume.
The dominant share belongs to pembrolizumab, while durvalumab is closing the gap fastest through stage III lung cancer penetration.
Therapy Area:
Oncology absorbs the majority of clinical development investment, though immunology adjuvant applications are attracting pipeline reallocation.
- Oncology:Solid tumor and hematologic malignancy indications dominate regulatory submissions. FDA accelerated approvals in metastatic melanoma and NSCLC established the commercial template replicated across Japan's PMDA and China's NMPA pathways.
- Hematology:Classical Hodgkin lymphoma and diffuse large B-cell lymphoma represent high-value combination targets. EMA conditional marketing authorizations in this category demand rigorous confirmatory trial commitments.
- Immunology:Systemic lupus erythematosus and rheumatoid arthritis trials are expanding checkpoint modulation beyond oncology. Mechanism-of-action validation in United States academic centers precedes broader indication pursuit.
- Dermatology:Merkel cell carcinoma and cutaneous squamous cell carcinoma address smaller patient populations with unmet need. Swissmedic and Health Canada have prioritized review timelines for these orphan-designated indications.
Oncology maintains absolute volume leadership, though immunology applications are expanding most quickly into adjuvant settings.
Delivery Mode:
Administration economics are restructuring around patient convenience metrics, compressing traditional hospital infusion center revenue models.
- Intravenous:Hospital and cancer treatment center administration dominates current prescribing. Infusion center capacity constraints in France and the Netherlands are forcing scheduling optimization and dose-interval modifications.
- Subcutaneous:Prefilled syringe and autoinjector formats reduce chair time and enable community clinic administration. German outpatient oncology networks are adopting these technologies to decompress hospital capacity.
- Oral:Small-molecule checkpoint modulators remain investigational, with early-phase trials evaluating bioavailability and hepatic metabolism profiles.
- Intramuscular:Depot formulations for extended-release kinetics are in preclinical development, targeting rural clinic access limitations in Australia and Canada.
Intravenous delivery still commands the largest installed base, while subcutaneous options are gaining share fastest through outpatient migration.
End User:
Procurement concentration among integrated hospital networks is displacing fragmented purchasing patterns.
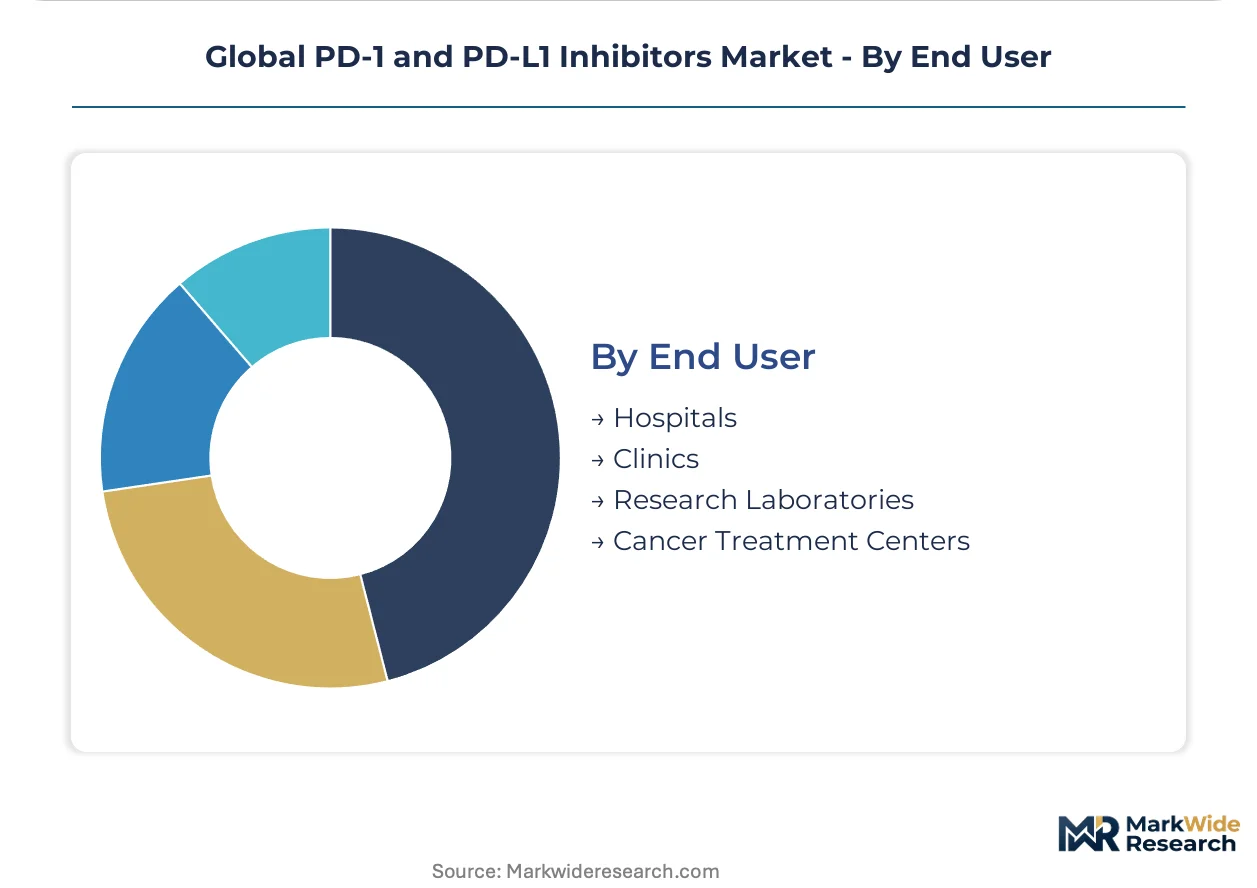
- Hospitals:Academic medical centers and tertiary care institutions manage complex combination regimens requiring intensive monitoring. Pharmacy and therapeutics committees in United States health systems wield centralized formulary authority over checkpoint inhibitor selection.
- Clinics:Community oncology practices are absorbing subcutaneous-enabled administration shifts. United Kingdom NHS Clinical Commissioning Groups are consolidating prescribing rights to specialized cancer centers.
- Research Laboratories:Translational medicine facilities support biomarker discovery and mechanism-of-action studies. China's National Cancer Center and Japan's National Cancer Research Institute anchor regional research infrastructure.
- Cancer Treatment Centers:Dedicated oncology facilities concentrate infusion capacity and specialized nursing expertise. South Korea's MFDS-designated cancer centers and Australia's TGA-recognized comprehensive cancer networks serve as regional referral hubs.
Hospitals retain the dominant procurement position, though cancer treatment centers are climbing the fastest through specialization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor capacity for glycosylation-controlled mammalian cell production clusters in Switzerland and Singapore, creating supply-side dependencies that shape regional market access sequencing. Hospital procurement consolidation and regulatory pathway differentiation concentrate commercial opportunity across five national markets.
United States
Oncology departments in academic medical center networks drive intravenous pembrolizumab and nivolumab adoption through centralized formulary authority. FDA accelerated approval pathways compress Phase II-to-market timelines, enabling earlier revenue recognition contingent on confirmatory trial execution. The Greater Boston and San Francisco Bay Area biotech clusters anchor translational research infrastructure supporting biomarker-driven patient selection.
China
Domestic breakthrough therapy designations from NMPA prioritize local PD-1 filings, redirecting multinational partnership strategies toward joint ventures with Chinese biologics manufacturers. Dual carbon goals for biologics manufacturing create first-mover advantage for facilities deploying energy-efficient single-use bioreactor systems. Shanghai and Suzhou industrial parks concentrate sterile fill-finish capacity serving Asia-Pacific distribution networks.
Japan
PMDA GMP inspection protocols filter manufacturing site eligibility, with certified facilities gaining preferred supplier positioning across Asia-Pacific hospital networks requiring Japanese regulatory equivalency. Reimbursement structures support premium positioning for first-line oncology approvals. The Kanto region around Tokyo hosts concentrated cancer center networks managing complex combination regimens.
Germany
Outpatient oncology networks adopt subcutaneous autoinjector formats to decompress hospital infusion center capacity and reduce chair time. EMA conditional marketing authorization frameworks demand rigorous confirmatory trial commitments for hematology combination regimens. The Munich and Heidelberg cancer clusters specialize in biomarker-driven checkpoint inhibitor protocols.
Switzerland
Contract manufacturing organizations in Basel and Zug control glycosylation-controlled bioreactor production for sterile drug substance supply to European and Asian markets. Swissmedic prioritizes review timelines for orphan-designated dermatology indications including Merkel cell carcinoma. The country's GMP-certified facilities serve as single-source vulnerability points for global supply continuity.
Global PD-1 and PD-L1 Inhibitors Market Competitive Landscape
Concentration sits with integrated pharmaceutical conglomerates commanding manufacturing scale and first-mover regulatory approvals. Three archetypes define competitive positioning: multinational innovators with pembrolizumab or nivolumab franchises, regional biotech specialists leveraging NMPA localization incentives, and emerging biosimilar developers preparing for patent cliff transitions. Dominant competitive moves include strategic partnerships for Chinese market access and subcutaneous formulation investments to capture outpatient administration shifts.
Among multinational innovators, Merck & Co., Bristol-Myers Squibb, and Roche occupy positions exemplifying the premium-tier archetype through established PD-1 and PD-L1 antibody franchises. These entities represent manufacturing scale advantages and regulatory pathway expertise across FDA, EMA, and PMDA jurisdictions. Jiangsu Hengrui Medicine anchors the China-based specialist tier, illustrating NMPA-aligned domestic filing strategies. The competitive terrain rewards entities achieving PMDA-certified sterile fill-finish status and those integrating real-world evidence infrastructure from launch.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| Roche |
| AstraZeneca |
| Pfizer |
| Ono Pharmaceutical |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| Jiangsu Hengrui Medicine |
| Others |
Supply & Pricing Matrix
Bioreactor capacity utilization rates exceeding 85% in Swiss and Singaporean facilities establish minimum viable scale thresholds that filter sub-scale entrants and sustain price floors for sterile drug substance. This concentration of glycosylation-controlled mammalian cell production creates asymmetric bargaining power where contract manufacturers command premium unit economics, while hospital procurement consolidation in France and the Netherlands compresses downstream margin capture for finished dose forms.
Pricing Analysis
FDA accelerated approval pathways dictate the pricing tier structure across the PD-1 and PD-L1 landscape, with confirmatory trial commitments separating premium first-line oncology indications from conditional hematology authorizations. Three-tier pricing structure across premium intravenous formulations, standard subcutaneous alternatives, and economy-oriented biosimilar entrants reflects brand longevity and manufacturing complexity. Cost compression in the biosimilar-ready tier is intensifying as patent cliff proximity for pembrolizumab and nivolumab approaches. Community oncology practices in Germany exhibit highest price sensitivity due to reimbursement rate compression, while academic medical centers in the United States demonstrate lowest sensitivity given outcome-based contracting insulation.
Supply Chain Analysis
Cold-chain integrity requirements at Swiss and Singaporean sterile fill-finish sites underwrite global supply continuity for checkpoint inhibitors requiring 2-8°C distribution. Glycosylation-controlled bioreactor production draws from Chinese hamster ovary cell banks, single-use bioreactor systems, and purified water for injection infrastructure. Single-source vulnerability concentrates at PMDA-certified facilities serving Asia-Pacific hospital networks requiring Japanese regulatory equivalency. Distribution runs through hospital pharmacy and therapeutics committees in integrated health systems, with direct-to-clinic channels expanding for subcutaneous autoinjector formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PD-1 and PD-L1 inhibitor market exhibits cyclical recovery characteristics as adjuvant oncology expansion absorbs pipeline assets previously directed toward saturated metastatic lines, with patient population multiplication in early-stage settings driving volume-based revenue normalization.
For Market Incumbents: Compound manufacturing scale advantages in intravenous formulations by securing PMDA-certified sterile fill-finish capacity ahead of Asia-Pacific hospital network procurement consolidation. Deepen backward integration into glycosylation-controlled bioreactor production to offset single-source vulnerability at Swiss contract manufacturing sites. Prioritize subcutaneous formulation investments to capture outpatient administration shifts decompressing German and United States infusion center capacity. For New Entrants and Emerging Players: Subcutaneous delivery technology gaps in community oncology practices create service-layer entry points where incumbents under-serve patient convenience metrics. Penetrate United Kingdom NHS Clinical Commissioning Groups consolidating prescribing rights to specialized cancer centers, where formulary access barriers remain lower than United States academic medical center networks. Pursue joint venture structures with NMPA-aligned Chinese biologics manufacturers to leverage domestic breakthrough therapy designation prioritization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among entities with PMDA-certified manufacturing footprints and established real-world evidence infrastructure from launch. Long-term viability over the projection horizon favors integrated pharmaceutical conglomerates with confirmatory trial execution track records across FDA, EMA, and PMDA jurisdictions. Monitor EMA conditional marketing authorization enforcement patterns as the critical inflection indicator for revenue destabilization risk in hematology combination regimens.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Patient convenience metrics in German outpatient networks are displacing hospital infusion center economics. |
| PMDA GMP Certification | Japanese regulatory equivalency unlocks preferred supplier positioning across Asia-Pacific hospital procurement. |
| NMPA Localization Partnership | Domestic breakthrough therapy designations redirect multinational strategies toward Chinese joint ventures. |
| Real-World Evidence Infrastructure | EMA expanded guidance demands electronic health record integration from launch rather than retrofit. |
| Biosimilar Manufacturing Scale-Up | Patent cliff proximity for first-generation PD-1 antibodies enables substitutable follow-on biologics positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation converged on segment-level estimates across the analysis window.
Across the projection horizon, the analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs were derived from patient volume trajectories and pricing elasticity assumptions calibrated to reimbursement rate evolution in United States, China, and Japan. Forecast inputs incorporated adjuvant oncology expansion velocity and subcutaneous formulation adoption curves.
Forecasts assume regulatory continuity in FDA accelerated approval, EMA conditional marketing authorization, and NMPA breakthrough therapy designation regimes; material policy shifts would require re-modeling. Biosimilar substitution rates and confirmatory trial failure frequencies represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as PMDA GMP inspection protocols and EMA real-world evidence requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Latin America FMD Vaccine Market