
 Infrastructure Solution Integration Service Market | 2026-2036
Infrastructure Solution Integration Service Market Size, Share, and Industry Trends Forecast 2026-2036
Infrastructure Solution Integration Service Market Foresight
ISO/IEC 27001 certification is redrawing competitive boundaries for infrastructure integration contracts. IBM Corporation leverages its Red Hat OpenShift portfolio to anchor hybrid cloud deployments for regulated clients. Accenture sustains market presence through deep industry vertical expertise in financial services and healthcare systems.
Infrastructure solution integration service encompasses the engineering, orchestration, and lifecycle management of heterogeneous hardware, software, and network components into cohesive operational environments, typically requiring API gateways with sub-100-millisecond latency thresholds and zero-downtime failover architectures to maintain business continuity. Cloud integration services now capture the largest revenue share as enterprises retire legacy data centers, while API integration segments exhibit the fastest expansion driven by real-time data exchange requirements across distributed supply chains. Managed services delivery models are maturing into multi-year annuity relationships, whereas on-premise deployments retain margin concentration in defense and classified government installations.
The EU AI Act and GDPR impose algorithmic transparency and data residency constraints that European integration vendors must architect around, while the US Federal Risk and Authorization Management Program (FedRAMP) gates access to federal cloud contracts. India's BIS and the country's national data protection framework are tightening localization requirements for cross-border data flows. Stakeholders must monitor how divergent sovereignty rules fragment integration architectures and force region-specific compliance investments.
Market Dynamics
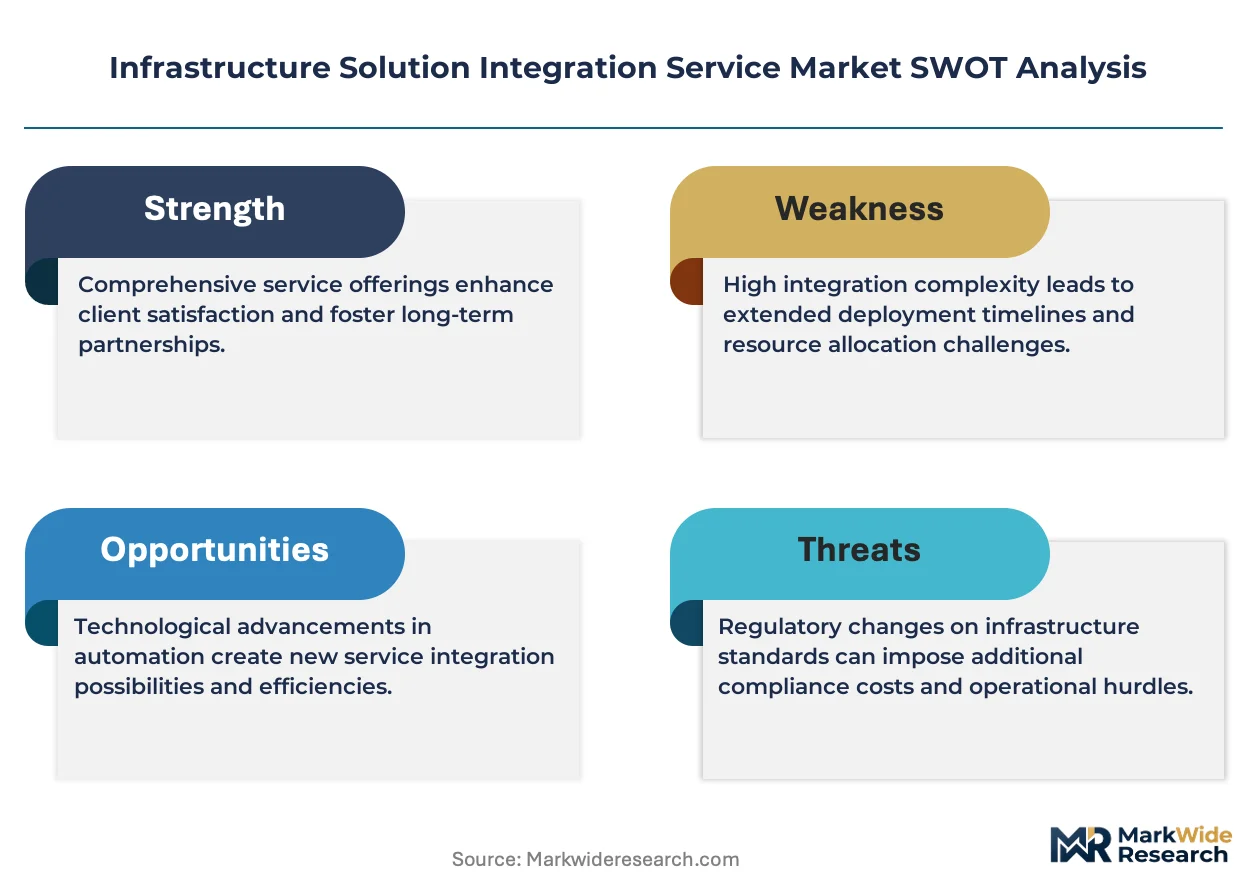
Enterprise cloud migration is compressing integration timelines while EU AI Act and GDPR mandates force architectural redesigns across European deployments, creating dual pressure on vendor certification portfolios and delivery capacity.
Growth Catalysts
- Healthcare Cloud Migration:Hospital systems are retiring on-premise data centers and procuring managed integration services to maintain HIPAA-compliant data flows during infrastructure transitions.
- FedRAMP Authorization:US federal IT modernization programs are channeling cloud integration contracts exclusively through certified systems integrators, creating gated demand pools.
- API-First Architectures:Real-time supply chain visibility requirements are driving procurement of sub-100-millisecond latency gateway solutions across distributed manufacturing networks.
Market Restraints
- Certified Talent Scarcity:ISO/IEC 27001 and FedRAMP authorization processes limit the pool of qualified integration engineers, inflating project staffing costs.
- Data Localization Mandates:India's BIS framework and emerging national data protection rules are fragmenting cross-border integration architectures and duplicating infrastructure investments.
- Legacy System Entrenchment:Defense and classified government installations maintain margin concentration in on-premise deployments, resisting cloud migration economics.
Strategic Opportunities
- Edge Computing Convergence:Integration of 5G network slicing with containerized microservices is opening new service categories for industrial IoT deployments.
- EU Regulatory Tailwind:CSRD sustainability reporting mandates are creating demand for carbon-aware infrastructure monitoring and ESG-integrated managed services.
- Multi-Cloud Orchestration:Enterprises are abandoning single-vendor cloud strategies and procuring neutral integration layers to prevent vendor lock-in.
Industry Challenges
- Zero-Downtime Migration Complexity:Financial services institutions demand failover architectures that maintain transaction continuity during core system replacements.
- Algorithmic Transparency Requirements:EU AI Act compliance is forcing integration vendors to document decision logic across automated orchestration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrastructure Solution Integration Service Market |
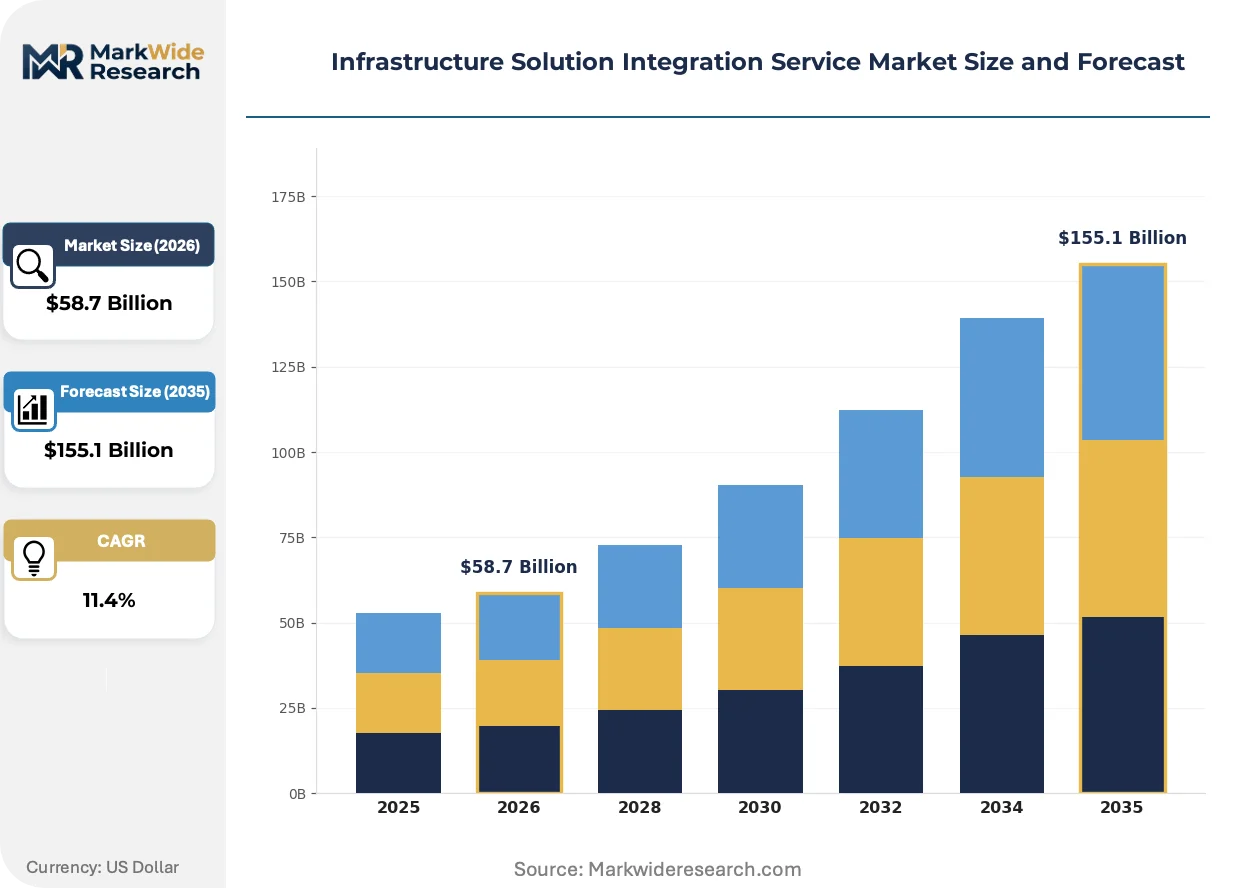
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Integration, Data Migration, System Deployment, Cloud Integration End User: Healthcare, Telecom, BFSI, Manufacturing Technology: IoT, Cloud Computing, AI, Machine Learning Delivery Model: On-Premise, Managed Services, SaaS, Hybrid |
| Companies Covered | Accenture, IBM Corporation, Oracle Corporation, Microsoft Corporation, Tata Consultancy Services, Capgemini, Cisco Systems, Cognizant, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrastructure Solution Integration Service Market Shifts & Advancements
Container orchestration and policy-driven automation are displacing manual configuration approaches, while sovereignty-compliant architectures reshape how vendors design multi-tenant platforms.
Service mesh technology is miniaturizing network management functions into sidecar proxies that handle traffic routing, security policies, and observability without modifying application code. Healthcare and financial services buyers are deploying Istio and Linkerd meshes at production scale within eighteen-month adoption windows. This topology is miniaturizing the traditional network operations center into distributed, self-healing control planes that reduce mean-time-to-recovery metrics.
EU AI Act algorithmic transparency requirements are mandating documentation trails for automated infrastructure decisions in European deployments. Vendors must now maintain explainable logs for scaling actions, failover triggers, and resource allocation algorithms. Healthcare integration projects in Germany and France are experiencing extended procurement cycles as legal teams vet compliance architectures.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based pricing tied to uptime SLAs rather than time-and-materials billing. Systems integrators are responding with multi-year annuity contracts that bundle design, deployment, and managed operations. This restructuring is most visible in United States federal and healthcare verticals where budget predictability outweighs capital flexibility.
Infrastructure Solution Integration Service Market Segmentation
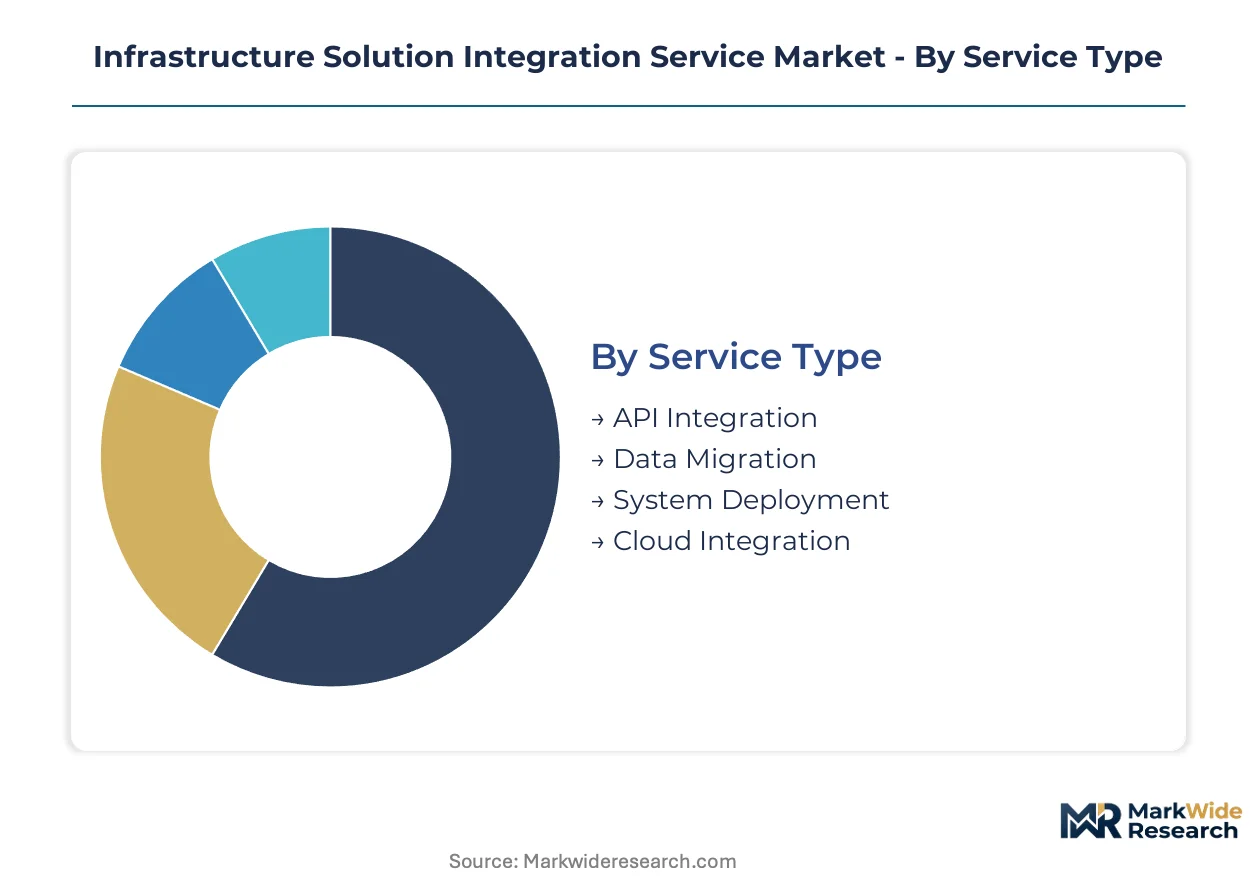
Segmentation in infrastructure solution integration services reveals distinct procurement patterns across service types, end users, and delivery models. Buyers prioritize certification depth over cost minimization when selecting integration partners for regulated workloads.
Service Type:
API Integration faces the most acute substitution pressure from low-code platforms and vendor-native connectors, forcing providers to differentiate through sub-100-millisecond latency guarantees and zero-downtime failover architectures.
- Cloud Integration:Orchestrates heterogeneous compute, storage, and network resources across multi-tenant environments. Healthcare systems in the United States are retiring legacy data centers and procuring FedRAMP-authorized managed services to maintain HIPAA-compliant data flows during infrastructure transitions.
- API Integration:Engineering of gateway solutions with traffic routing, security policies, and observability functions. Manufacturing networks across distributed supply chains are driving procurement of sub-100-millisecond latency gateway solutions for real-time visibility requirements.
- Data Migration:Structured transfer of enterprise datasets between storage architectures with integrity validation protocols.
- System Deployment:Physical and virtual provisioning of hardware and software components into production environments.
Cloud Integration anchors the volume base while API Integration gains share at the steepest rate.
End User:
Cost tier stratification separates defense-grade on-premise deployments from commercial cloud migrations, with healthcare and BFSI commanding premium pricing for compliance-heavy integration architectures.
- Healthcare:Hospital systems demand ISO/IEC 27001-certified integration partners for patient data orchestration across hybrid environments. German and French healthcare integration projects are experiencing extended procurement cycles as legal teams vet EU AI Act algorithmic transparency architectures.
- BFSI:Financial services institutions require failover architectures that maintain transaction continuity during core system replacements. Zero-downtime migration complexity drives multi-year annuity contracts with outcome-based pricing tied to uptime SLAs.
- Telecom:5G network slicing integration with containerized microservices for industrial IoT deployments.
- Manufacturing:Real-time supply chain visibility through distributed sensor networks and edge computing convergence.
BFSI commands the highest margin tier while Healthcare delivers the most predictable contract renewal rates.
Technology:
Volume concentration sits with mature infrastructure layers, though AI and Machine Learning are climbing fastest as buyers demand automated orchestration with explainable decision trails.
- Cloud Computing:Foundational virtualization and container orchestration for elastic resource allocation. Enterprise buyers are abandoning single-vendor cloud strategies and procuring neutral integration layers to prevent vendor lock-in across multi-cloud estates.
- AI:Automated infrastructure decisions requiring documented scaling actions, failover triggers, and resource allocation algorithms. EU AI Act compliance is forcing integration vendors to maintain explainable logs for algorithmic transparency in European deployments.
- IoT:Sensor network integration with edge computing for industrial asset monitoring.
- Machine Learning:Predictive analytics for capacity planning and anomaly detection in distributed systems.
Cloud Computing carries the installed base while AI expands most quickly through policy-driven automation mandates.
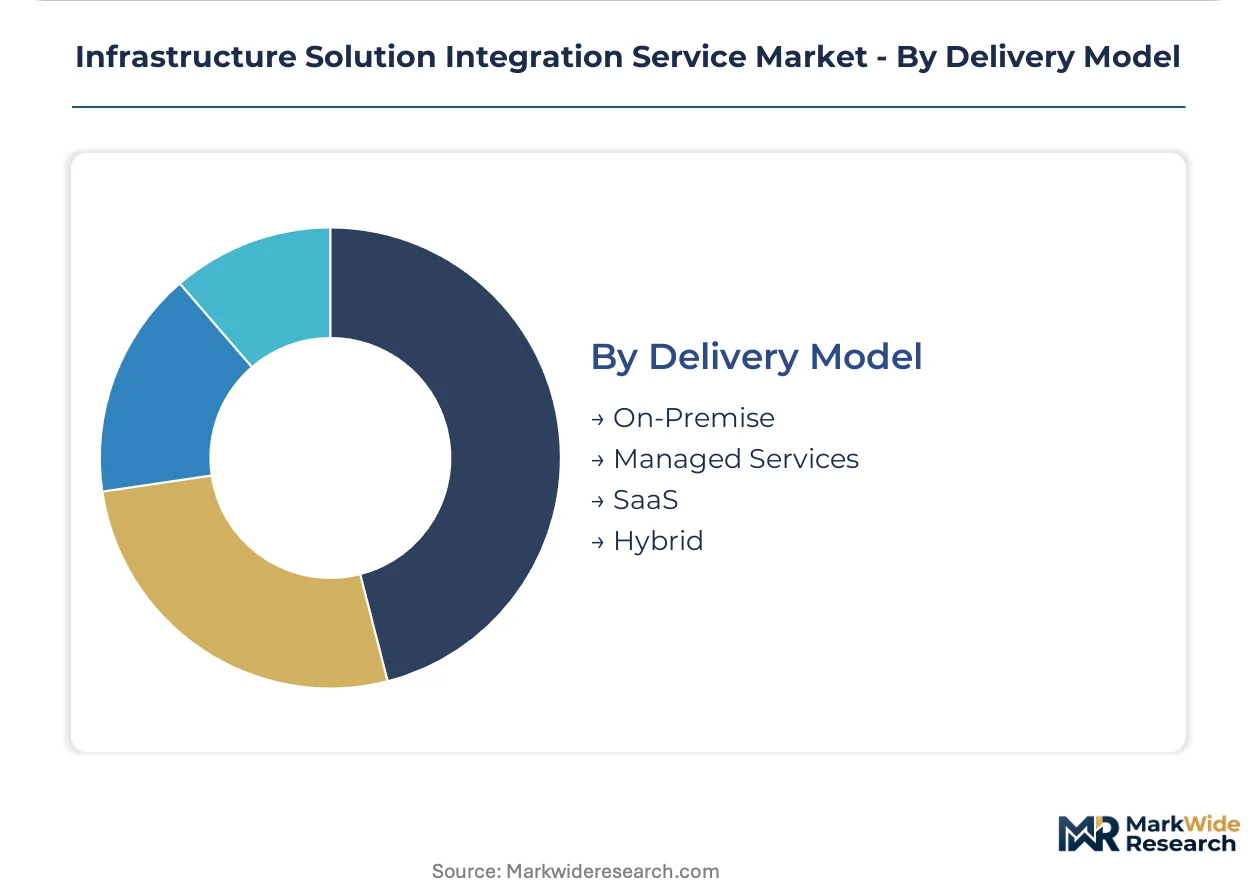
Delivery Model:
Maturity gradients separate legacy on-premise installations from annuity-based managed services, with hybrid architectures capturing the broadest addressable market as enterprises stage cloud migrations.
- Managed Services:Multi-year annuity relationships bundling design, deployment, and lifecycle operations. United States federal IT modernization programs are channeling cloud integration contracts exclusively through FedRAMP-certified systems integrators.
- Hybrid:Coordinated on-premise and cloud resource pools with unified orchestration planes. Enterprises are procuring neutral integration layers to prevent vendor lock-in while maintaining sovereignty-compliant data residency.
- On-Premise:Defense and classified government installations resisting cloud migration economics.
- SaaS:Pre-configured integration platforms with subscription-based access to standardized connectors.
Managed Services locks in recurring revenue while Hybrid captures the widest buyer segment across transition-stage enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedRAMP authorization requirements and EU AI Act compliance mandates are reshaping procurement patterns across national boundaries. Sovereignty rules fragment integration architectures and force region-specific certification investments.
United States
Federal IT modernization programs channel cloud integration contracts exclusively through certified systems integrators. HIPAA compliance mandates drive hospital systems toward FedRAMP-authorized managed services during data center retirements. The Washington DC-Boston corridor concentrates defense-grade integration demand for classified government installations.
Germany
Automotive and industrial manufacturing networks require sub-100-millisecond latency gateway solutions for real-time supply chain visibility. EU AI Act algorithmic transparency rules extend procurement cycles as legal teams vet automated orchestration workflows. Munich and Stuttgart anchor Industry 4.0 integration clusters for smart factory deployments.
India
Enterprise cloud migration accelerates procurement of managed integration services across banking and telecom verticals. BIS framework and emerging national data protection rules tighten localization requirements for cross-border data flows. Bengaluru and Hyderabad concentrate API-first architecture development for global delivery centers.
United Kingdom
Financial services institutions demand zero-downtime failover architectures maintaining transaction continuity during core system replacements. GDPR data residency constraints reshape vendor qualification requirements for European-facing deployments. London anchors multi-cloud orchestration demand as enterprises abandon single-vendor cloud strategies.
France
Healthcare integration projects experience extended procurement cycles under EU AI Act compliance vetting. CSRD sustainability reporting mandates create demand for carbon-aware infrastructure monitoring and ESG-integrated managed services. Paris and Lyon concentrate pharmaceutical and healthcare systems integration expertise.
Infrastructure Solution Integration Service Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with established certification portfolios. Market structure concentrates around tier-one integrators possessing ISO/IEC 27001 and FedRAMP credentials. Three archetypes dominate: full-service consultancies with vertical specialization, cloud-native platform vendors with managed services arms, and telecom-cable integrators with network infrastructure heritage. Competitive moves center on multi-year annuity contract capture and sovereignty-compliant architecture development.
Within the full-service consultancy tier, Accenture and Deloitte exemplify players leveraging deep industry vertical expertise to sustain market presence. IBM Corporation anchors the cloud-native platform segment through hybrid deployment capabilities. Tata Consultancy Services represents the global delivery model archetype, occupying a position shaped by scale-driven cost optimization and cross-border talent deployment. These three patterns illustrate how certification depth outweighs price competition in regulated procurement environments.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| Tata Consultancy Services |
| Capgemini |
| Cisco Systems |
| Cognizant |
| Deloitte |
| Others |
Supply & Pricing Matrix
Containerized microservices displacing legacy middleware stacks simultaneously redistributes supply geography toward India and Eastern European delivery centers while compressing implementation pricing through standardized deployment playbooks. This substitution dynamic fragments traditional systems integrator margins across tiered certification levels.
Pricing Analysis
Cost-plus contracts with labor rate indexation to Bureau of Labor Statistics IT occupational categories dominate federal and healthcare procurement. Three-tier pricing structure across FedRAMP-authorized premium, ISO-certified standard, and uncertified economy levels separates compliance-heavy buyers from cost-optimized mid-market adopters. Price differentiation hinges on certification depth and geographic delivery cost, with Indian delivery centers undercutting US-based rates. Cost compression in the economy tier intensifies as low-code platforms substitute professional services hours. Healthcare systems exhibit lowest price sensitivity due to HIPAA liability exposure, while manufacturing verticals drive hardest bargain negotiations.
Supply Chain Analysis
FedRAMP authorization queues at the General Services Administration create a credentialing chokepoint that gates vendor participation in federal contract pools. Engineering talent supply concentrates in India, Poland, and the United States, with Bengaluru and Krakow anchoring offshore delivery capacity. Raw material dependencies span cloud hyperscaler compute instances, API gateway software licenses, and cybersecurity certification audit services. Single-source vulnerability runs through AWS, Azure, and Google Cloud infrastructure commitments that lock integrators into specific architectural patterns. Distribution runs through direct enterprise sales teams supplemented by hyperscaler marketplace listings and federal contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise cloud migration sits at an early-cycle expansion phase where FedRAMP certification scarcity creates asymmetric returns for authorized vendors. Healthcare and federal verticals drive penetration tailwinds through compliance-mandated procurement.
For Market Incumbents: Fortify certification moats through ISO/IEC 27001 and FedRAMP reauthorization investments ahead of EU AI Act algorithmic transparency rulemaking. Defensive consolidation moves center on acquiring boutique healthcare integrators with established HIPAA compliance architectures and captive supply of cleared personnel for classified government installations. Threat substitution from low-code platforms demands channel control through exclusive hyperscaler partnership tiers. For New Entrants and Emerging Players: Anchor in EU regulatory advisory services as legal teams extend procurement cycles vetting algorithmic transparency architectures. White-space targets span carbon-aware infrastructure monitoring for CSRD compliance and edge computing convergence for industrial IoT deployments. Manufacturing verticals in Germany offer most penetrable entry point through sub-100-millisecond latency gateway specialization. Go-to-market angle leads with explainable automation documentation trails that preempt EU AI Act vetting delays. For Investors and Strategic Acquirers: The market sits at a certification-scarcity phase that favors vertical specialists with established credential portfolios over undifferentiated generalists. Long-term viability over the coming decade rests on multi-cloud orchestration capabilities that prevent vendor lock-in across hybrid estates. Acquisition target archetype: boutique integrators with deep healthcare or defense vertical expertise and cleared personnel rosters. Signal to watch as inflection indicator: hyperscaler marketplace revenue share crossing threshold where direct sales teams lose pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Gates access to federal IT modernization contract pools worth billions in recurring revenue. |
| EU Regulatory Advisory Service Launch | Captures extended procurement cycle spending as legal teams vet algorithmic transparency compliance. |
| Healthcare Vertical Acquisition | Secures HIPAA-compliant data flow expertise and predictable contract renewal rate profiles. |
| Multi-Cloud Orchestration Platform Development | Prevents vendor lock-in while maintaining sovereignty-compliant data residency architectures. |
| Edge Computing Convergence Partnership | Opens industrial IoT service categories through 5G network slicing integration capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, federal contract award databases, and EU regulatory filings. Primary interviews engaged cloud architects, federal procurement officers, healthcare IT directors, and integration program managers across the United States, Germany, India, and the United Kingdom. Secondary validation drew from FedRAMP authorization records, GSA contract vehicle data, and SEC 10-K infrastructure service disclosures. Bottom-up project pipeline analysis triangulates against top-down addressable market sizing by vertical.
Segmentation dimensions modeled span service type, end-user vertical, technology layer, and delivery model across the projection horizon. Cloud integration, API integration, data migration, and system deployment categories anchor volume estimates. Healthcare, BFSI, telecom, and manufacturing verticals stratify demand by compliance intensity. Deployment model segmentation separates managed services annuity streams from hybrid transition architectures and residual on-premise installations. CAGRs derive from weighted average of vertical penetration curves and certification-constrained supply elasticity.
Material uncertainties — regulatory timeline slippage for EU AI Act implementation, FedRAMP authorization queue congestion, and hyperscaler pricing volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued federal IT modernization funding and healthcare data center retirement velocity. Practitioners should keep alternative scenarios live as sovereignty rule fragmentation and algorithmic transparency enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Big Data in Construction Market