
 Construction Materials Testing Equipment Market | 2026-2036
Construction Materials Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Materials Testing Equipment Market Analysis
Market Context
Government infrastructure procurement is collapsing toward private laboratory certification chains as the dominant buyer archetype across developed markets. ELE International leverages its British standards heritage to anchor European public works compliance programs. Shimadzu Corporation dominates East Asian markets through precision instrumentation for high-performance concrete analysis. Controls S.p.A. specializes in automated asphalt testing lines that sustain margins in Mediterranean infrastructure renewal cycles.
Technical Definition and Segment Structure
Construction materials testing equipment encompasses mechanical, electromechanical, and electronic systems designed to measure compressive strength, permeability, density, and deformation characteristics of concrete, soil, asphalt, and aggregate specimens under standardized load conditions. These instruments enforce structural integrity protocols across civil engineering projects by verifying that raw and finished materials meet specified performance thresholds before incorporation into buildings, roads, bridges, and rail systems. Non-destructive testing methods now lead investment flows as infrastructure owners prioritize in-service evaluation over destructive sampling that interrupts active construction schedules. Concrete testing equipment occupies the largest revenue pool due to universal building code requirements, while soil testing apparatus represents the fastest-growing category as geotechnical investigation intensifies for foundation work in seismic zones and coastal development.
Regulatory Framework and Outlook
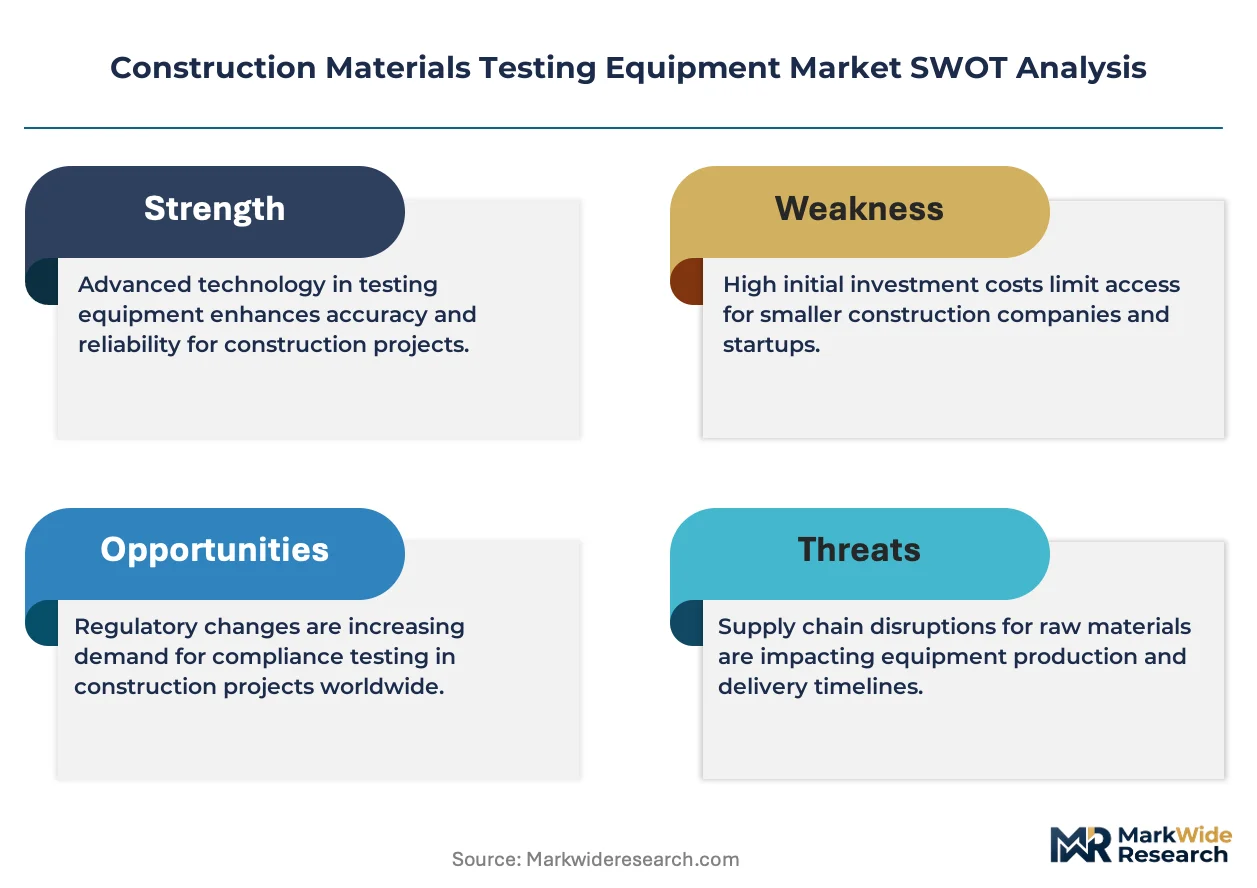
ASTM International and AASHTO standards govern product certification and test methodology across North American jurisdictions, with OSHA workplace safety rules mandating calibration intervals that sustain replacement demand. The EU Construction Products Regulation and CE marking requirements enforce harmonized performance declarations, while China's GB standards and SAMR quality supervision create parallel compliance tracks for equipment sold domestically versus exported. Stakeholders must monitor how digital twin integration and IoT-enabled continuous monitoring reshape the boundary between laboratory certification and real-time site validation.
Market Dynamics
The transition from laboratory-based certification to IoT-enabled continuous site monitoring is restructuring equipment procurement patterns, compressing replacement cycles for static testing benches while elevating demand for portable, connected instrumentation.
Growth Catalysts
- ASTM E329 compliance mandates:United States infrastructure agencies now require third-party laboratory accreditation for every federal highway project, institutionalizing recurring equipment audits and calibration service contracts.
- High-performance concrete specifications:Ultra-high-strength mix designs for supertall construction in seismic zones demand precision rheology and shrinkage testing capabilities that legacy analog systems cannot deliver.
- Coastal urban densification:Foundation work across reclaimed land and liquefaction-prone zones in East Asian megacities drives geotechnical investigation intensity and automated soil testing line deployment.
Market Restraints
- Specialized alloy input volatility:Load frame manufacturing depends on high-grade steel and precision sensor components whose spot pricing fluctuates with energy and rare earth supply disruptions.
- Calibration equipment import dependence:Primary metrology standards for force and pressure verification concentrate among a narrow base of German and Japanese national laboratories, creating certification bottlenecks.
- Destructive sampling substitution:Ground-penetrating radar and ultrasonic pulse velocity methods for in-situ concrete assessment reduce specimen extraction requirements for certain quality assurance protocols.
Strategic Opportunities
- Digital twin integration:Real-time material performance data feeds into predictive infrastructure lifecycle models, creating subscription revenue streams beyond equipment sale margins.
- India's National Infrastructure Pipeline:The country's $1.4 trillion project portfolio lacks indigenous advanced testing capacity, opening import substitution and joint venture pathways for compliant equipment suppliers.
- EU Green Deal embodied carbon tracking:Construction product environmental declarations mandate standardized material characterization, expanding demand for automated aggregate and cement content analysis systems.
Industry Challenges
- Metrology technician scarcity:Precision instrument calibration and repair functions require specialized training pipelines that vocational programs have failed to replenish across aging workforces in Western Europe and North America.
- Multi-standard certification complexity:Equipment vendors must simultaneously maintain ASTM, AASHTO, EN, and GB standard compliance documentation, extending product development timelines and testing expenditure.
- Legacy system interoperability:Site laboratories operate mixed-vendor instrument fleets with incompatible data formats, complicating centralized quality management system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Materials Testing Equipment Market |
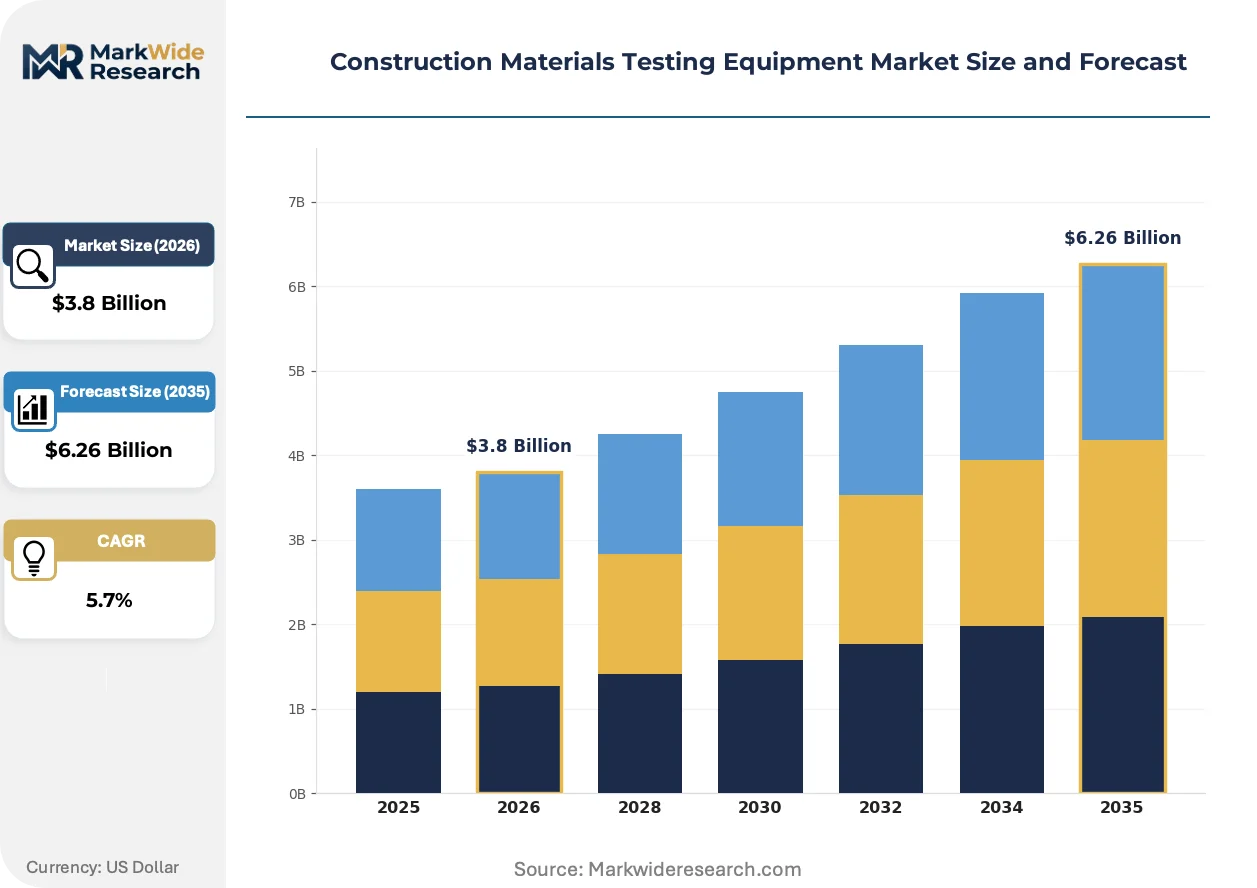
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Testing Equipment, Soil Testing Apparatus, Asphalt Testing Devices, Aggregate Testing Instruments Testing Method: Non-Destructive Testing, Destructive Testing, In-Situ Testing, Laboratory Testing End User: Construction Companies, Engineering Firms, Laboratories, Educational Institutions Application: Site Evaluation, Quality Control, Research & Development, Compliance Testing |
| Companies Covered | ELE International, Applied Test Systems, Inc., Aimil Ltd., Olson Instruments, Inc., Shimadzu Corporation, Controls S.p.A., Humboldt Mfg. Co., Canopus Instruments, Matest S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Materials Testing Equipment Market Emerging Trajectories
Sensor miniaturization and edge computing capabilities are dissolving the boundary between laboratory precision and field portability, enabling real-time decision-making at construction sites previously dependent on off-site specimen transport.
Wireless embedded strain monitoring is decomposing the traditional compressive strength testing workflow. Bridge and tunnel constructors in Japan and South Korea now deploy fiber-optic and MEMS-based sensors within pour sequences, capturing curing dynamics continuously rather than awaiting 28-day cylinder breaks. This distributed sensing architecture compresses project schedules and reduces material overdesign margins.
REACH substance restrictions on heavy metals and persistent organic compounds are reformulating sensor and coating chemistries in European-manufactured equipment. The regulation's SVHC candidate list expansion forces redesign of load cell potting compounds and protective enclosures, accelerating transition to halogen-free polymer alternatives. German and Italian producers face compressed redesign timelines to maintain CE marking validity.
Rental and managed service models are displacing capital purchase for intermittent-use applications. Regional contractor consortia in Australia and the United Arab Emirates now pool automated asphalt analyzer access through third-party logistics providers, unbundling maintenance and calibration from equipment ownership. This preference shift concentrates fleet investment among specialized rental intermediaries rather than dispersing it across fragmented contractor balance sheets.
Construction Materials Testing Equipment Market Segmentation
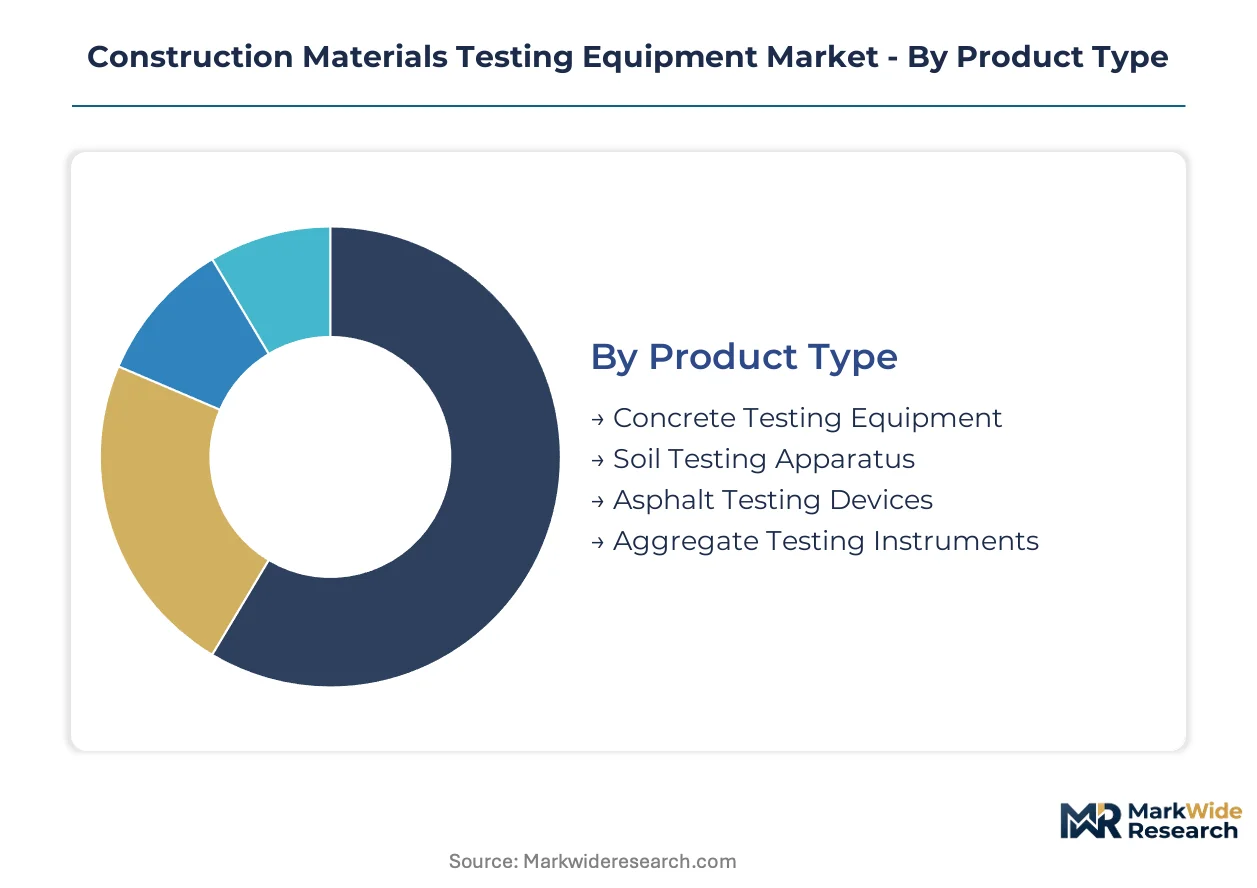
Segmentation in construction materials testing equipment reveals how procurement authority, technical specifications, and regulatory compliance requirements reshape vendor priorities. Equipment categories with the tightest certification windows command premium pricing and service attachment rates.
Product Type:
Margin pools concentrate in systems that automate multi-parameter analysis for high-volume commercial laboratories serving infrastructure agencies.
- Concrete Testing Equipment:Compressive strength testers, slump cones, air meters, and maturity monitoring systems verify structural integrity before pour completion. Demand concentrates in China's high-speed rail corridors and supertall construction clusters where GB standard compliance mandates automated curing analysis. Equipment precision requirements tighten as ultra-high-performance mix designs proliferate in seismic zones.
- Soil Testing Apparatus:Triaxial chambers, direct shear machines, and consolidation cells characterize geotechnical properties for foundation design. Coastal urban densification across East Asian megacities drives automated soil line deployment where liquefaction risk assessment is mandatory. Procurement accelerates for continuous consolidation monitoring systems that compress investigation timelines.
- Asphalt Testing Devices:Marshall stability testers, binder analyzers, and wheel-tracking rigs evaluate pavement performance under thermal and mechanical stress.
- Aggregate Testing Instruments:Sieve shakers, abrasion machines, and specific gravity apparatus verify gradation and durability for concrete and asphalt production.
The dominant share belongs to Concrete Testing Equipment, while Soil Testing Apparatus is closing the gap fastest.
Testing Method:
Customer procurement patterns split between capital-intensive laboratory infrastructure and portable field instrumentation based on project phase and regulatory acceptance.
- Non-Destructive Testing:Ultrasonic pulse velocity, ground-penetrating radar, and rebound hammer methods assess material properties without specimen extraction. Bridge and tunnel constructors in Japan deploy fiber-optic sensors within pour sequences to capture curing dynamics continuously rather than awaiting 28-day cylinder breaks.
- Destructive Testing:Core drilling, compression to failure, and split tensile methods remain the certification standard for structural acceptance protocols. United States federal highway projects require ASTM E329 compliant destructive verification that institutionalizes recurring equipment audits.
- In-Situ Testing:Field penetration tests, plate load tests, and pressuremeter measurements evaluate subsurface conditions without laboratory transport delays.
- Laboratory Testing:Controlled environment specimen preparation and standardized load application provide the definitive data for contractual disputes and warranty claims.
Non-Destructive Testing commands the steepest expansion trajectory as infrastructure owners prioritize schedule compression over absolute precision.
End User:
Equipment specification authority migrates from general contractors toward specialized certification chains as quality assurance liability concentrates.
- Construction Companies:Large contractors maintain field laboratories for real-time mix adjustment and submittal preparation on major projects. Rental and managed service models now displace capital purchases for intermittent-use applications among regional consortia.
- Engineering Firms:Geotechnical and structural consultants specify equipment performance tiers in their investigation scopes. Firms with in-house testing capability capture higher-margin design-build contracts.
- Laboratories:Third-party certification chains anchor procurement volume as government infrastructure collapses toward private laboratory accreditation.
- Educational Institutions:University civil engineering programs sustain demand for training-grade equipment with simplified automation.
Laboratories hold the dominant share, while Engineering Firms are gaining procurement authority fastest through design-build integration.
Application:
Revenue attachment rates vary sharply between one-time site investigations and recurring compliance contracts with multi-year calibration obligations.
- Site Evaluation:Pre-construction geotechnical investigation and existing structure assessment requires portable, rapid-deployment instrumentation. Foundation work across reclaimed land drives automated soil testing line deployment.
- Quality Control:Continuous production monitoring for ready-mix concrete and hot-mix asphalt sustains the highest equipment utilization rates. ASTM and AASHTO compliance verification on every major project tightens quality assurance protocols.
- Research & Development:Novel material characterization for ultra-high-performance concrete and recycled aggregate applications demands research-grade precision.
- Compliance Testing:Regulatory submission and contractual dispute resolution requires documented traceability to national metrology standards.
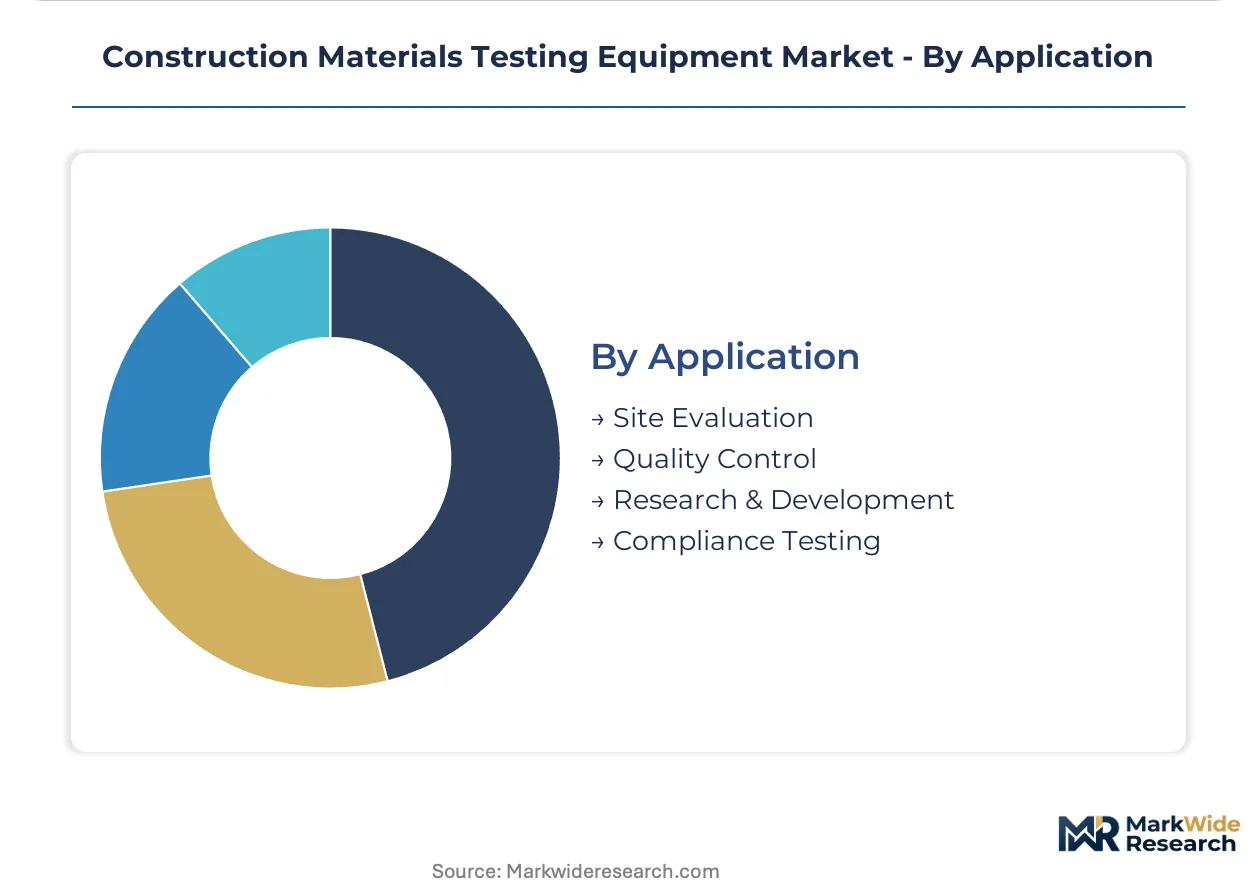
Quality Control captures the dominant share, while Site Evaluation is expanding most quickly through IoT-enabled continuous monitoring adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail corridors anchor the largest equipment procurement volumes, while Germany's autobahn rehabilitation programs and the United States' federal highway trust fund disbursements sustain premium-tier demand across distinct regulatory environments.
United States
Federal highway rehabilitation and supertall construction in seismic zones drive precision testing demand. OSHA workplace safety rules mandate calibration intervals that sustain replacement cycles for load frame systems. Texas and California DOTs anchor procurement volume through multi-year laboratory accreditation contracts.
Germany
Autobahn concrete bridge replacement and wind turbine foundation work intensify geotechnical investigation requirements. The Federal Highway Research Institute mandates accelerated pavement testing for national road rehabilitation programs. Bavarian engineering clusters concentrate automated asphalt analyzer deployment for EU Green Deal compliance verification.
China
High-speed rail expansion and urban densification across reclaimed coastal zones consume advanced soil and concrete testing systems. GB standards and SAMR quality supervision create parallel compliance tracks for domestic versus export equipment. Yangtze River Delta megacities drive automated curing analysis adoption for ultra-high-performance mix designs.
India
The National Infrastructure Pipeline's $1.4 trillion project portfolio lacks indigenous advanced testing capacity, opening import substitution pathways. BIS certification requirements tighten for construction product imports. Maharashtra and Gujarat infrastructure corridors anchor demand for portable field instrumentation serving design-build contracts.
Japan
Bridge and tunnel constructors deploy fiber-optic sensors within pour sequences for continuous curing monitoring. METI standards govern precision instrumentation for high-performance concrete analysis. Kanto and Kansai metropolitan areas concentrate non-destructive testing adoption for schedule compression in dense urban construction.
Construction Materials Testing Equipment Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The vendor base separates into three tiers: precision instrumentation multinationals, regional compliance specialists, and rental-service intermediaries. Consolidation pressure concentrates among automated system providers serving high-volume commercial laboratories. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships for digital twin platform integration.
Within the precision instrumentation tier, Shimadzu Corporation and Controls S.p.A. exemplify divergent regional anchoring strategies. ELE International occupies a position bridging British standards heritage with European public works compliance programs. Humboldt Mfg. Co. represents the North American specialist archetype focused on ASTM and AASHTO certification workflows.
| Leading Market Players |
|---|
| ELE International |
| Applied Test Systems, Inc. |
| Aimil Ltd. |
| Olson Instruments, Inc. |
| Shimadzu Corporation |
| Controls S.p.A. |
| Humboldt Mfg. Co. |
| Canopus Instruments |
| Matest S.p.A. |
| Others |
Supply Flow & Price Mechanics
Long-term calibration service contracts lock in both supply access and price visibility for construction materials testing equipment vendors serving United States infrastructure agencies under ASTM E329 mandates. These multi-year agreements compress spot market exposure while embedding maintenance revenue that stabilizes margin pools across volatile alloy input cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automated multi-parameter systems from manual bench units and rental-service intermediaries. Certification grade under ASTM, AASHTO, and GB standards commands substantial premiums, while volume scale discounts concentrate among third-party laboratory chains. Pricing pressure stems from rental and managed service models displacing capital purchases among regional contractor consortia. Engineering firms demonstrate highest price sensitivity due to intermittent utilization patterns, whereas commercial laboratories exhibit lowest sensitivity given compliance-driven procurement authority.
Supply Chain Analysis
German and Japanese national laboratory certification bottlenecks concentrate primary metrology standards for force and pressure verification, constraining calibration equipment availability worldwide. Load frame manufacturing draws from high-grade steel suppliers in Germany and precision sensor component sources in Japan and South Korea. Tariff exposure runs through rare earth supply disruptions affecting sensor fabrication. Distribution runs through specialized rental intermediaries and direct sales forces serving commercial laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction materials testing equipment is approaching a platform-economics inflection where digital twin integration and IoT-enabled continuous monitoring dissolve boundaries between laboratory certification and real-time site validation. Interoperability standards for mixed-vendor instrument fleets will determine which vendors capture subscription revenue beyond equipment sale margins.
For Market Incumbents: Shield installed base relationships by backward integration into sensor manufacturing and captive calibration service networks. Consolidate around automated system providers serving high-volume commercial laboratories before emerging entrants capture digital twin platform integration partnerships. Certification investment in multi-standard compliance documentation defends against margin compression from specialized regional competitors.
For New Entrants and Emerging Players: Managed service gaps in India's National Infrastructure Pipeline offer white-space entry where indigenous advanced testing capacity remains underdeveloped. Portable field instrumentation for design-build contracts in Maharashtra and Gujarat infrastructure corridors presents the most penetrable segment. Pursue joint venture pathways with domestic distributors to navigate BIS certification requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrumentation specialists with embedded software capabilities and recurring calibration revenue streams. Long-term viability favors vendors positioned at the intersection of laboratory precision and field portability. Monitor fiber-optic sensor deployment rates in Japanese bridge and tunnel construction as inflection indicator for distributed sensing architecture adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of load cells and strain gauges insulates margin pools from rare earth price volatility. |
| Digital Twin Platform Integration | Real-time material performance data feeds create subscription revenue beyond equipment sale margins. |
| Multi-Standard Certification Investment | Simultaneous ASTM, AASHTO, EN, and GB compliance opens procurement access across infrastructure agencies. |
| Rental and Managed Service Expansion | Third-party logistics partnerships capture fleet investment concentrating among specialized intermediaries. |
| Geographic Expansion into India | National Infrastructure Pipeline demand exceeds indigenous capacity, enabling import substitution pathways. |
Methodological Framework
Initial hypotheses were tested against primary input from commercial laboratory directors, geotechnical engineering consultants, equipment calibration technicians, and infrastructure agency procurement officers and refined through secondary validation. Construction materials testing equipment analysis combined ASTM and AASHTO regulatory filings, EU Construction Products Regulation documentation, SAMR quality supervision records, and customs trade data with SEC filings from precision instrumentation multinationals. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Variance decomposition across product type, testing method, end user, and application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate blending and cross-referenced against infrastructure spending trajectories and regulatory compliance mandate timelines. Modeled inputs incorporated high-speed rail construction intensity in China, autobahn rehabilitation cycles in Germany, and federal highway trust fund disbursement patterns in the United States.
Underlying assumptions cover sustained infrastructure agency procurement authority migration toward private laboratory certification chains, with deviation risk concentrated in metrology technician scarcity compressing calibration service capacity. Practitioners should keep alternative scenarios live as digital twin integration standards and IoT-enabled continuous monitoring adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Hardbanding Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Remote Construction Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Grease Trap Service Market
Construction Services
NDT and Inspection Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Train Contractor Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
North America Repair and Rehabilitation Market