
 Middle-East and Africa Hemodynamic Monitoring Market | 2026-2036
Middle-East and Africa Hemodynamic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Hemodynamic Monitoring Market Foresight
The divergence between premium and commodity tiers in hemodynamic monitoring is hardening as Gulf health systems demand integrated ICU platforms while cost-constrained African facilities prioritize basic bedside monitors. Koninklijke Philips NV anchors the premium segment through its centralized monitoring architectures. GE Healthcare competes with modular systems designed for scalable deployment. Edwards Lifesciences Corporation specializes in advanced arterial line technologies for cardiac surgery suites.
Hemodynamic monitoring encompasses the continuous or intermittent measurement of blood flow, pressure, and oxygen delivery parameters through invasive catheters, non-invasive sensors, or hybrid systems incorporating pulse contour analysis and bioreactance algorithms. These systems serve the primary commercial purpose of guiding fluid therapy, vasoactive drug titration, and early shock detection in perioperative and critical care settings. Non-invasive monitors are gaining fastest in the Middle-East and Africa region as health ministries seek to reduce catheter-related infection burdens. Invasive monitors retain margin concentration in tertiary cardiac centers across Saudi Arabia and the United Arab Emirates. Application demand skews heavily toward critical care management rather than trauma care given the region's hospital infrastructure profile.
Saudi Arabia's SFDA, South Africa's national health regulator, and the UAE's MOHAP collectively shape device registration timelines, reimbursement codes, and clinical evidence requirements for market entry. The EU MDR equivalence pathway influences Gulf quality standards even where direct jurisdiction does not apply. Stakeholders must monitor how national health insurance expansion in Nigeria and Egypt alters procurement specifications for public hospital tenders.
Market Dynamics
The Middle-East and Africa hemodynamic monitoring market is bifurcating along infrastructure capability lines, with Gulf Cooperation Council health systems demanding integrated ICU platforms while Sub-Saharan facilities prioritize basic bedside monitors due to capital constraints.
Growth Catalysts
- SFDA Streamlined Registration:Saudi Arabia's medical device approval pathway accelerates market entry for hemodynamic monitoring systems, reducing regulatory friction for manufacturers targeting the Kingdom's tertiary cardiac centers.
- Catheter-Related Infection Reduction Mandates:Health ministries across the Gulf Cooperation Council are prioritizing non-invasive monitoring alternatives to lower hospital-acquired infection rates in critical care settings.
- Cardiac Surgery Volume Concentration:Tertiary referral hospitals in the United Arab Emirates and Saudi Arabia are expanding cardiac surgery suites, driving demand for advanced arterial line monitoring capabilities.
Market Restraints
- Import Dependency for Precision Sensors:The region lacks domestic manufacturing capacity for pressure transducers and fiber-optic catheters, exposing procurement to currency volatility and shipping disruptions.
- Bioreactance Algorithm Limitations:Non-invasive cardiac output monitoring using thoracic electrical bioimpedance demonstrates reduced accuracy in patients with significant lung pathology or obesity.
- EU MDR Equivalence Documentation Burden:Gulf regulators increasingly require European Medical Device Regulation-aligned clinical evidence packages, extending registration timelines for manufacturers without existing EU certifications.
Strategic Opportunities
- National Health Insurance Expansion:Egypt and Nigeria are extending coverage to surgical procedures, creating reimbursement pathways for hemodynamic monitoring in previously out-of-pocket segments.
- Pulse Contour-Bioreactance Hybrid Convergence:Next-generation platforms combining arterial waveform analysis with non-invasive sensors offer calibration-free monitoring for intermediate-acuity wards.
- Tele-ICU Distribution Models:Remote monitoring partnerships between Gulf hub hospitals and African spoke facilities enable technology transfer without full capital deployment.
Industry Challenges
- Critical Care Specialist Shortage:The region faces acute scarcity of intensivists trained in advanced hemodynamic interpretation, limiting utilization of sophisticated monitoring platforms even where installed.
- Legacy Device Interoperability:African public hospitals operate mixed-vendor monitoring ecosystems from decades of fragmented procurement, complicating centralized data integration for new platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Hemodynamic Monitoring Market |
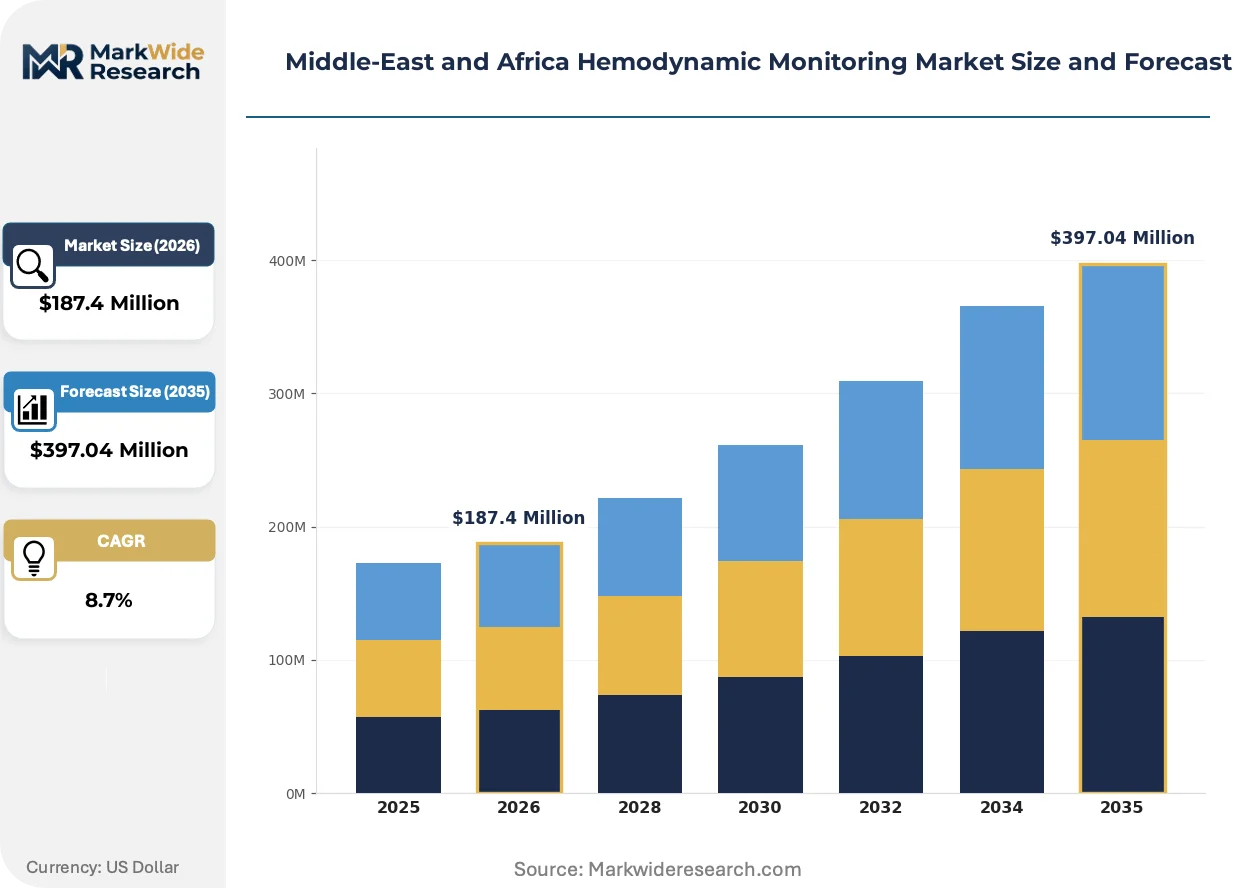
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-Invasive Monitors, Continuous Monitors, Bedside Monitors End User: Hospitals, Cardiac Care Units, Intensive Care Units, Emergency Departments Technology: Pulse Contour Analysis, Bioreactance, Doppler Ultrasound, Arterial Line Application: Cardiac Surgery, Trauma Care, Critical Care Management, Postoperative Monitoring |
| Companies Covered | Getinge Group, Koninklijke Philips NV, GE Healthcare, LiDCO Group PLC, Cheetah Medical Inc, Edwards Lifesciences Corporation, Deltex Medical Group plc, ICU Medical, Inc., Osypka Medical GmbH, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Hemodynamic Monitoring Market Shifts & Advancements
Technology convergence and regulatory alignment are compressing product lifecycles across the Middle-East and Africa hemodynamic monitoring landscape, with vendors racing to deliver platforms that satisfy both Gulf precision requirements and African cost constraints.
Multi-parameter monitoring platforms incorporating pulse contour analysis, capnography, and tissue oxygenation sensing are modularizing into configurable chassis systems. Saudi Arabian and Emirati hospital procurement departments are specifying scalable architectures that accommodate future sensor additions without full system replacement. This modularization is compressing replacement cycles for standalone monitors while extending platform lifecycles through software-enabled feature expansion.
EU Medical Device Regulation equivalence pathways are reshaping Gulf quality assurance expectations even absent direct jurisdiction. SFDA and MOHAP now routinely request clinical performance data structured to MDR Annex XIV standards, particularly for class III invasive monitoring devices. Manufacturers with existing EU notified body certifications are securing faster Gulf approvals, while regional distributors without MDR-aligned documentation face extended technical file preparation periods.
Public hospital tender specifications across Nigeria, Egypt, and South Africa are unbundelling after-sales service from capital equipment pricing. Procurement officers are negotiating multi-year service contracts separately from device acquisition, with payment contingent on uptime guarantees and training completion metrics. This unbundling is most visible in South Africa's national health department centralized purchasing, where service-level agreements now constitute 25-40 percent of total contract value over equipment lifetime.
Middle-East and Africa Hemodynamic Monitoring Market Segmentation
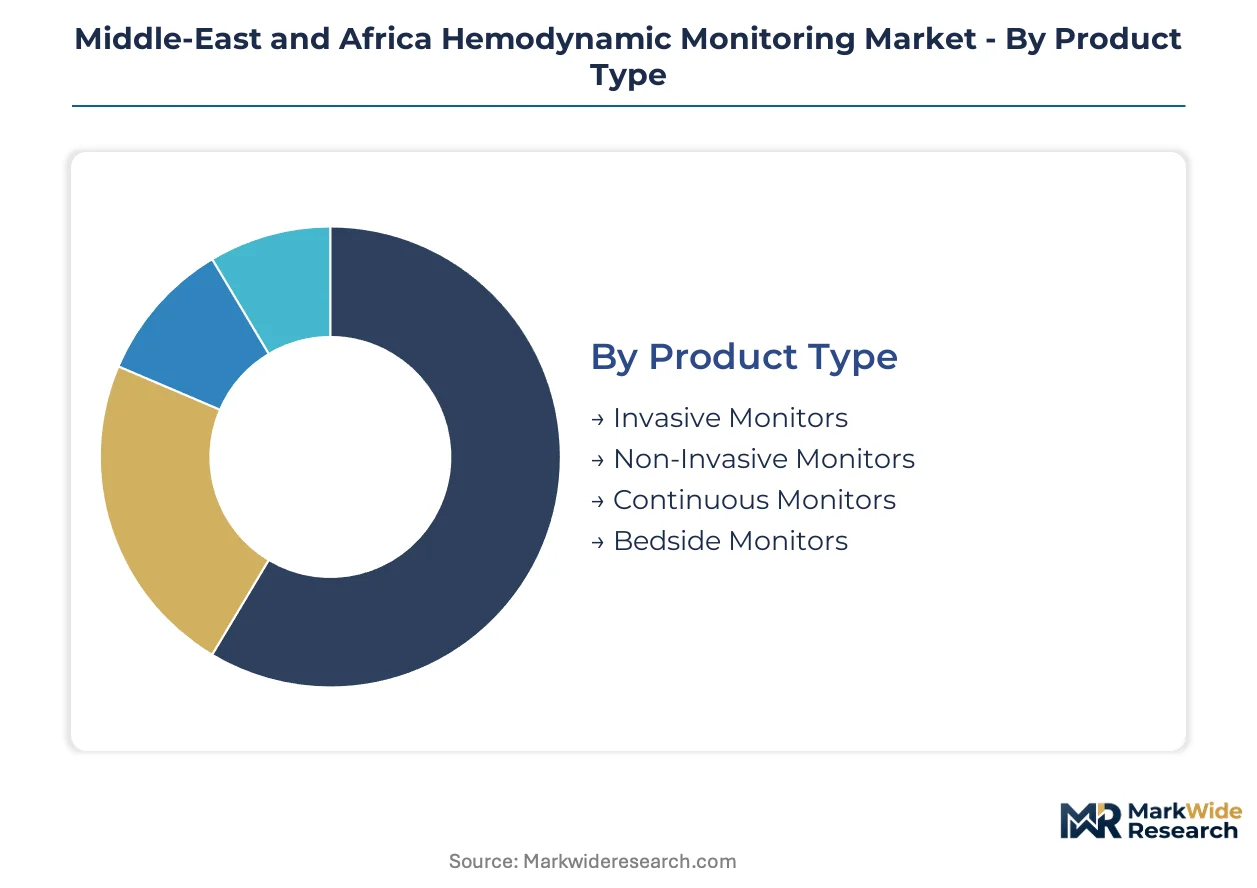
The Middle-East and Africa hemodynamic monitoring market fragments across four analytical dimensions. Each segmentation axis reveals distinct procurement patterns between Gulf Cooperation Council health systems and Sub-Saharan facilities with divergent infrastructure capabilities.
Product Type:
Supply concentration for hemodynamic monitors clusters around manufacturers with dual invasive-non-invasive portfolios serving the region's bifurcated demand profile.
- Invasive Monitors:These systems deploy pressure transducer-tipped catheters and arterial lines for direct blood flow measurement in cardiac surgery suites. Tertiary hospitals in Saudi Arabia and the United Arab Emirates concentrate procurement for these devices, driven by expanding cardiac surgery volumes and SFDA-mandated precision standards for class III devices.
- Non-Invasive Monitors:Thoracic electrical bioimpedance and pulse oximetry-based systems eliminate catheter-related infection risks. South African public hospitals and Gulf Cooperation Council ministries prioritize these alternatives to reduce hospital-acquired infection burdens and shorten ICU stays.
- Continuous Monitors:Real-time hemodynamic parameter tracking systems integrate with hospital information networks for automated alarm generation.
- Bedside Monitors:Standalone units with limited networking capabilities serve cost-constrained facilities across Nigeria and Egypt.
Invasive monitors absorb the bulk of installed capacity in tertiary cardiac centers; non-invasive monitors are expanding most quickly across intermediate-acuity wards.
End User:
Procurement authority concentrates at the national health ministry level for public hospital networks, while private hospital groups exercise independent purchasing discretion.
- Hospitals:General acute care facilities across the Middle-East and Africa deploy hemodynamic monitoring for perioperative and emergency applications. Egypt's national health insurance expansion is creating new reimbursement pathways for these devices in previously uncovered surgical procedures.
- Cardiac Care Units:Dedicated cardiovascular departments in Saudi Arabian and Emirati tertiary centers require advanced arterial line monitoring with pulse contour analysis capabilities.
- Intensive Care Units:Critical care departments represent the primary demand concentration for multi-parameter monitoring platforms with modular sensor expansion.
- Emergency Departments:Trauma receiving facilities prioritize rapid-deployment non-invasive monitors for shock detection in hemodynamically unstable patients.
Intensive care units command the largest share of device installations; cardiac care units are climbing the fastest as Gulf states expand specialized cardiovascular infrastructure.
Technology:
Technology selection follows a precision-cost tradeoff, with algorithm accuracy determining adoption in high-acuity settings versus cost sensitivity driving choices elsewhere.
- Pulse Contour Analysis:Arterial waveform interpretation algorithms calculate stroke volume and cardiac output without thermodilution. This technology dominates Saudi Arabian and Emirati cardiac surgery suites where calibration-free monitoring reduces procedural complexity.
- Bioreactance:Thoracic electrical bioimpedance measures phase shifts in alternating current across the chest to derive cardiac output. South African hospitals favor this approach for intermediate-acuity wards, though accuracy limitations in patients with lung pathology constrain deployment in respiratory ICUs.
- Doppler Ultrasound:Transcutaneous or transesophageal ultrasound probes measure blood flow velocity for cardiac output estimation.
- Arterial Line:Invasive pressure monitoring through radial or femoral artery cannulation remains the reference standard for high-precision hemodynamic assessment.
Arterial line technology retains margin concentration in premium-tier installations; bioreactance systems are gaining share fastest as infection reduction mandates spread.
Application:
Application demand skews toward perioperative and critical care settings rather than trauma given the region's hospital infrastructure concentration in urban tertiary centers.
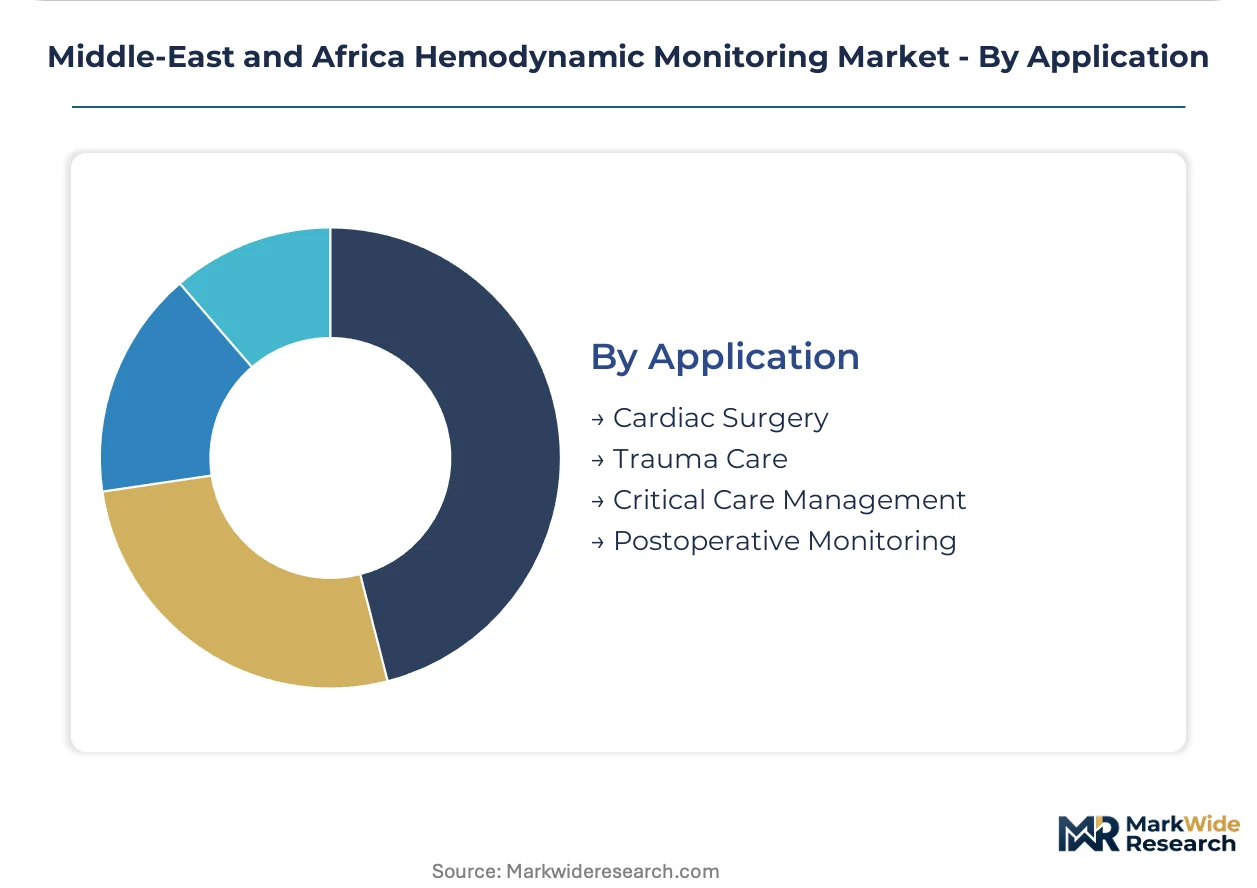
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures require continuous cardiac output monitoring and mixed venous oxygen saturation tracking. The United Arab Emirates and Saudi Arabia are expanding cardiac surgery suite capacity, directly stimulating demand for advanced invasive monitoring platforms.
- Trauma Care:Hemorrhagic shock detection in emergency settings favors rapid non-invasive assessment tools. Limited penetration reflects infrastructure gaps in pre-hospital systems across Sub-Saharan Africa rather than technology limitations.
- Critical Care Management:Sepsis, acute respiratory distress syndrome, and multi-organ failure monitoring drive the majority of hemodynamic device utilization across the region.
- Postoperative Monitoring:Surgical recovery wards employ intermediate-acuity monitoring for early detection of hemodynamic deterioration.
Critical care management absorbs the dominant share of monitoring hours; cardiac surgery is expanding most quickly as Gulf states develop cardiovascular referral capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's King Faisal Specialist Hospital corridor anchors hemodynamic monitoring procurement across the Gulf Cooperation Council, with tertiary cardiac centers in the Saudi capital driving demand for invasive arterial line systems.
Saudi Arabia
SFDA streamlined registration protocols accelerate device approvals for cardiac surgery suites. The Kingdom's national health transformation program mandates infection reduction protocols favoring hybrid monitoring platforms. Eastern Province petrochemical industry clusters are expanding occupational health ICU capacity.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi concentrate demand for premium multi-parameter platforms. MOHAP's medical device quality standards align with EU MDR equivalence pathways for class III devices. Tertiary cardiac referral capacity is expanding across Emirati teaching hospitals.
South Africa
Public hospital networks in Gauteng and Western Cape prioritize non-invasive monitors for ICU infection control. The national health department's centralized tender system unbundles service contracts from capital equipment pricing. Cape Town's private hospital groups are deploying modular monitoring architectures.
Egypt
National health insurance expansion is creating reimbursement pathways for surgical hemodynamic monitoring previously paid out-of-pocket. The country's medical device regulatory authority is harmonizing standards with Gulf Cooperation Council technical requirements. Cairo's university hospitals are upgrading cardiac surgery infrastructure.
Nigeria
Lagos and Abuja private hospital groups represent the primary addressable market given public sector procurement constraints. The national health insurance scheme extension is altering tender specifications for federal medical centers. Imported precision sensor dependency exposes procurement to currency volatility.
Middle-East and Africa Hemodynamic Monitoring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as integrated platform vendors face modular system specialists across the Middle-East and Africa hemodynamic monitoring landscape. Market structure concentrates around three to five multinational medical technology conglomerates with established Gulf distribution networks, complemented by mid-cap specialists in non-invasive sensor technologies. Strategic archetypes include premium-tier integrated ICU platform providers, scalable modular system vendors, and bioreactance algorithm specialists. Dominant competitive moves encompass service contract unbundling from capital sales and tele-ICU partnership models enabling remote technology transfer.
Within the premium-tier integrated platform segment, Koninklijke Philips NV and GE Healthcare occupy positions exemplifying centralized monitoring architecture capabilities. Edwards Lifesciences Corporation represents the specialized invasive monitoring archetype focused on arterial line technologies. These three entities anchor the competitive structure through differentiated approaches to Gulf Cooperation Council procurement specifications and African cost-constrained market development.
| Leading Market Players |
|---|
| Getinge Group |
| Koninklijke Philips NV |
| GE Healthcare |
| LiDCO Group PLC |
| Cheetah Medical Inc |
| Edwards Lifesciences Corporation |
| Deltex Medical Group plc |
| ICU Medical, Inc. |
| Osypka Medical GmbH |
| Others |
Supply & Pricing Matrix
Gulf hospital procurement departments specifying EU MDR-aligned clinical evidence packages are forcing manufacturers to absorb documentation costs or cede share to EU-certified competitors, compressing margins on non-invasive monitor sales while elevating pricing power for invasive platform vendors with existing notified body certifications.
Pricing Analysis
Uptime-guaranteed service contracts now anchor pricing structures across South Africa's national health department tenders, with multi-year SLAs constituting 25-40 percent of total lifetime contract value. Price differentiation separates premium-tier integrated ICU platforms with modular sensor expansion from basic bedside monitors serving Egyptian and Nigerian public hospitals. Pricing pressure stems from currency volatility exposing import-dependent precision sensor procurement in Sub-Saharan markets. Cost-constrained African facilities exhibit highest price sensitivity, while Saudi tertiary cardiac centers prioritize precision over acquisition cost.
Supply Chain Analysis
Pressure transducer and fiber-optic catheter production rests on German, Japanese, and US specialty component manufacturers, with no domestic manufacturing capacity across the Middle-East and Africa region. Hemodynamic monitoring systems draw from precision sensors, biocompatible catheter materials, and signal processing chipsets. Single-source vulnerability concentrates in pressure transducer supply, where shipping disruptions and currency fluctuations propagate directly to procurement timelines. Distribution runs through authorized Gulf distributors with MOHAP and SFDA registration credentials, extending to African spoke facilities via tele-ICU hub partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's streamlined registration protocols and EU MDR equivalence requirements are erecting compliance barriers that favor manufacturers with existing notified body certifications, creating sustainable moats against undercapitalized regional distributors lacking technical file preparation capabilities.
For Market Incumbents: Hedge against bioreactance algorithm displacement by securing pulse contour-bioreactance hybrid platforms for intermediate-acuity ward expansion. Deepen backward integration into sensor calibration services to capture unbundled service contract value in South African centralized tenders. SFDA's accelerating approval timelines threaten first-mover advantage erosion; counter through exclusive hospital system partnerships locking in modular platform refresh cycles. For New Entrants and Emerging Players: Egypt's national health insurance expansion opens a window for non-invasive monitor penetration in previously out-of-pocket surgical segments. Target Lagos and Abuja private hospital groups with rapid-deployment bioreactance systems bypassing public procurement constraints. Partner with established Gulf distributors possessing existing MOHAP registration credentials rather than building direct regulatory infrastructure. For Investors and Strategic Acquirers: The window for entry favors modular system vendors with scalable deployment architectures serving both Gulf precision requirements and African cost constraints. Long-term viability centers on platforms accommodating software-enabled feature expansion without hardware replacement. Monitor SFDA registration queue velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Streamlined approvals compress time-to-revenue for cardiac surgery suite vendors in Riyadh corridor. |
| Tele-ICU Hub Partnership | Remote monitoring alliances enable technology transfer to African spoke facilities without capital deployment. |
| Service Contract Unbundling | Separate SLAs with uptime guarantees capture 25-40 percent of lifetime value in South African tenders. |
| Pulse Contour-Bioreactance Convergence | Hybrid platforms address infection reduction mandates while maintaining precision for Gulf cardiac centers. |
| EU MDR Technical File Alignment | Pre-aligned clinical evidence packages secure faster Gulf approvals against non-certified competitors. |
Research Methodology
SFDA device registration databases, MOHAP quality standards documentation, and South African national health department tender records formed the secondary backbone, cross-referenced with primary interviews involving ICU clinicians, hospital biomedical engineers, GPO contracts managers, and Gulf distributor regulatory affairs leads. Bottom-up and top-down triangulation validated installed base estimates against procurement pipeline data.
The analytical lens combined bottom-up facility-level demand aggregation with top-down health ministry budget allocation analysis across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, technology platform, and application acuity level, with CAGRs derived from regression against cardiac surgery volume expansion and infection reduction mandate implementation timelines. Non-invasive monitor adoption curves and hybrid platform replacement cycles served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for bioreactance algorithm accuracy improvement would alter the outlook for invasive monitor retention in intermediate-acuity settings. Forecasts reflect assumptions regarding SFDA registration velocity, currency stability in Nigerian and Egyptian procurement, and EU MDR equivalence pathway continuity. A small set of triggers—national health insurance expansion pace, tele-ICU partnership model viability, and critical care specialist training program scale—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Asia Pacific Wireless Healthcare Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
US Remote Patient Monitoring and Care Market