
 Acute Care Hospital Bed and Stretcher Market | 2026-2036
Acute Care Hospital Bed and Stretcher Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Care Hospital Bed and Stretcher Market Analytics
Premium electric bed specifications with integrated pressure relief and smart monitoring is unwinding across hospital procurement budgets. Stryker Corporation leverages its vertical manufacturing depth to control component supply for ICU-grade beds. Hill-Rom Holdings Inc. anchors North American distribution through direct hospital contracting networks. Paramount Bed Holdings Co., Ltd. dominates Japanese acute care installations with localized regulatory compliance.
Acute care hospital beds and stretchers constitute motorized and manually adjustable patient support platforms built from steel frames, antimicrobial surfaces, and hydraulic or electric lift mechanisms designed for clinical transport and inpatient positioning. Electric beds with embedded sensor arrays now lead product category investment, while specialized stretchers for surgical and emergency applications capture expanding margin pools as hospitals prioritize throughput efficiency. Smart bed technology with automated patient monitoring represents the fastest-growing segment, though manual beds retain volume dominance in cost-constrained clinics and long-term care facilities.
The FDA enforces 21 CFR bed rail entrapment standards that directly shape product design and hospital purchasing criteria, while the EU Medical Device Regulation (MDR) and CE marking requirements govern European market access for powered patient handling equipment. Japan's Ministry of Health, Labour and Welfare (MHLW) and PMDA maintain distinct electromagnetic compatibility and safety testing protocols that filter import competition. Stakeholders must monitor how evolving cybersecurity standards for connected hospital devices reshape R&D allocation and certification timelines for smart bed platforms.
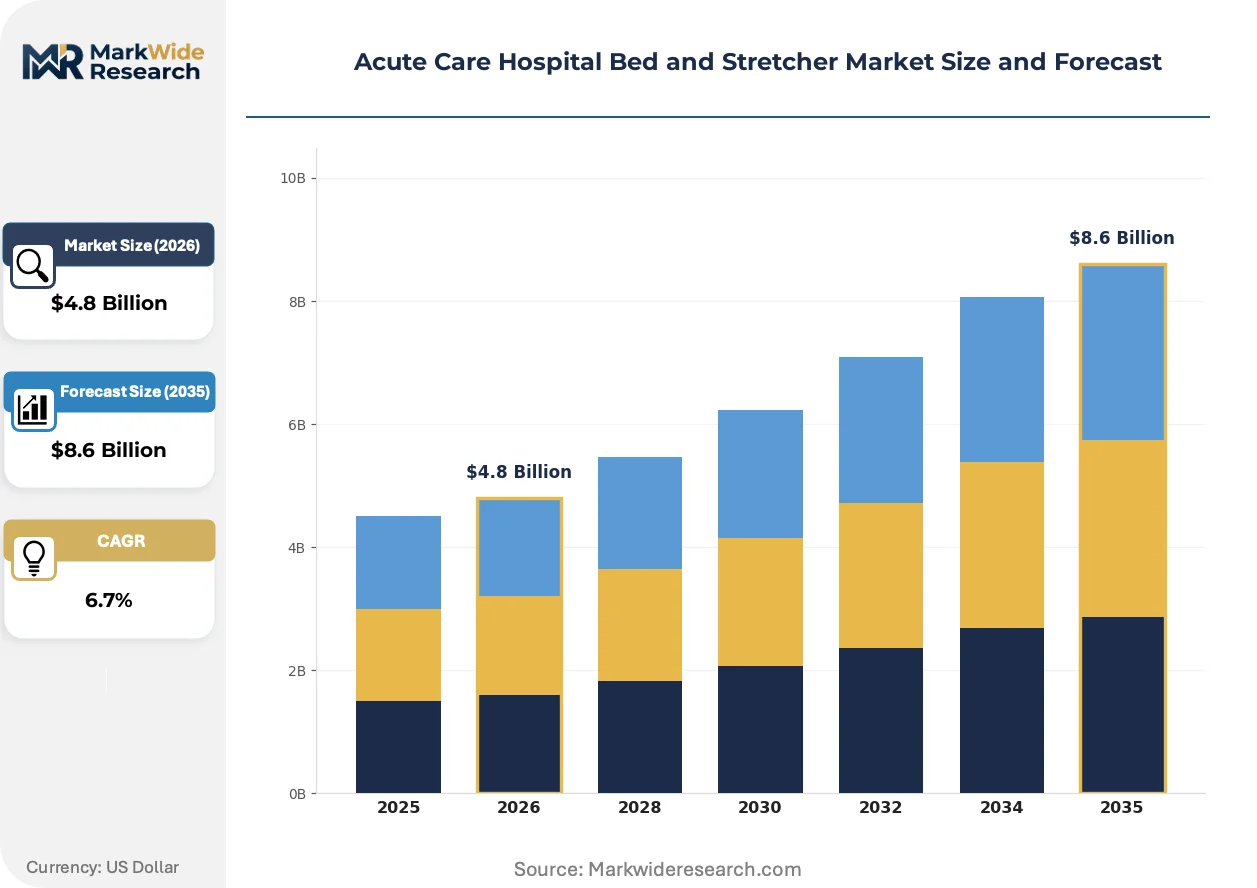
Market Dynamics
Hospital capital expenditure cycles now prioritize smart bed platforms with embedded patient monitoring, compressing replacement timelines for legacy manual units and redirecting procurement budgets toward integrated systems that reduce nursing labor intensity.
Growth Catalysts
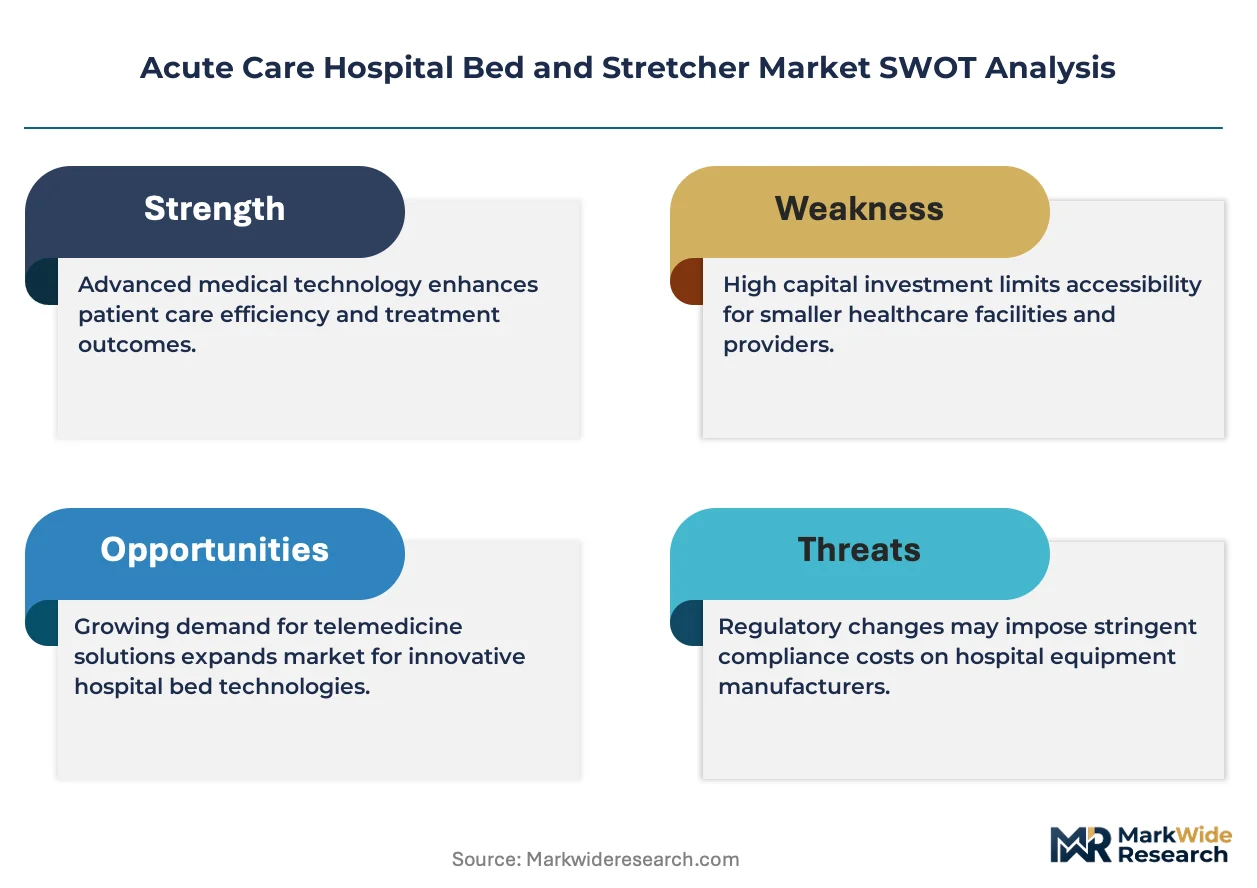
- FDA 21 CFR Entrapment Standards:Mandatory bed rail safety testing accelerates replacement of non-compliant legacy inventory across US acute care facilities, creating forced upgrade demand.
- ICU Infrastructure Modernization:Hospital systems in Germany and Japan are consolidating purchasing power to acquire powered stretchers with hydraulic lift mechanisms for emergency throughput efficiency.
- Antimicrobial Surface Coatings:Copper-ion and silver-embedded bed surfaces reduce hospital-acquired infection liability, driving specification in surgical and immunocompromised patient wards.
Market Restraints
- Steel and Aluminum Input Volatility:Frame material costs fluctuate with commodity indexes, squeezing margin on economy-tier manual bed production.
- Electronics Supply Concentration:Sensor arrays and motor controllers for powered units depend on concentrated Asian semiconductor foundry capacity, exposing lead time risk.
- Cybersecurity Certification Friction:Connected bed platforms face extended FDA premarket review timelines for wireless data transmission protocols, delaying revenue recognition.
Strategic Opportunities
- Long-Term Care Underpenetration:Skilled nursing facilities in rural US markets remain manual-bed dominant, creating retrofit potential as Medicaid reimbursement shifts toward quality metrics.
- EU MDR Regulatory Tailwind:CE marking requirements for powered patient handling equipment filter import competition, advantaging EU-based manufacturers with established notified body relationships.
- Telehealth Convergence:Integration of bed-embedded sensors with remote monitoring platforms enables acute care at home, opening new reimbursement codes for hospital-at-home programs.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospitals lack in-house expertise to maintain sensor calibration and software updates for smart bed fleets, forcing reliance on OEM service contracts.
- Legacy System Integration Complexity:New electric beds must interface with existing nurse call systems and electronic health records through proprietary protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Care Hospital Bed and Stretcher Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Electric Beds, Stretchers, Specialized Stretchers End User: Hospitals, Clinics, Long-Term Care Facilities, Rehabilitation Centers Technology: Smart Beds, Powered Stretchers, Adjustable Beds, Pressure Relief Systems Application: Emergency Care, Surgical Care, Intensive Care, Palliative Care |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings Inc., Invacare Corporation, Getinge AB, LINET, Paramount Bed Holdings Co., Ltd., ArjoHuntleigh, Midmark Corp, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Care Hospital Bed and Stretcher Market Evolving Landscape
Product development trajectories in acute care beds and stretchers center on automation, connectivity, and infection control, with manufacturers racing to embed clinical intelligence directly into patient support hardware.
Capacitive sensor arrays integrated into mattress platforms now enable continuous monitoring of patient position, respiration rate, and bed exit events without wearable attachments. ICU departments in tertiary hospitals are adopting these systems fastest, with some health systems mandating smart bed specifications in all new construction. This capability is displacing standalone patient monitoring devices and compressing capital equipment footprints at the bedside.
The EU Medical Device Regulation's strengthened post-market surveillance requirements for Class IIa powered beds are forcing manufacturers to maintain detailed clinical evidence databases. Compliance costs have risen substantially for imported equipment, prompting some Asian producers to establish EU-based quality management subsidiaries. German and French hospital procurement consortia now prioritize MDR-certified suppliers in tender evaluations, reshaping competitive access.
Group Purchasing Organizations in the United States are consolidating acute care bed contracts into multi-hospital system agreements, reducing vendor count and extending contract durations. Independent community hospitals face exclusion from preferred pricing tiers, pushing them toward refurbished equipment markets or regional distributor alliances. This concentration is most visible in the Southeast and Midwest, where Catholic health networks and for-profit chains dominate bed procurement decisions.
Acute Care Hospital Bed and Stretcher Market Segmentation
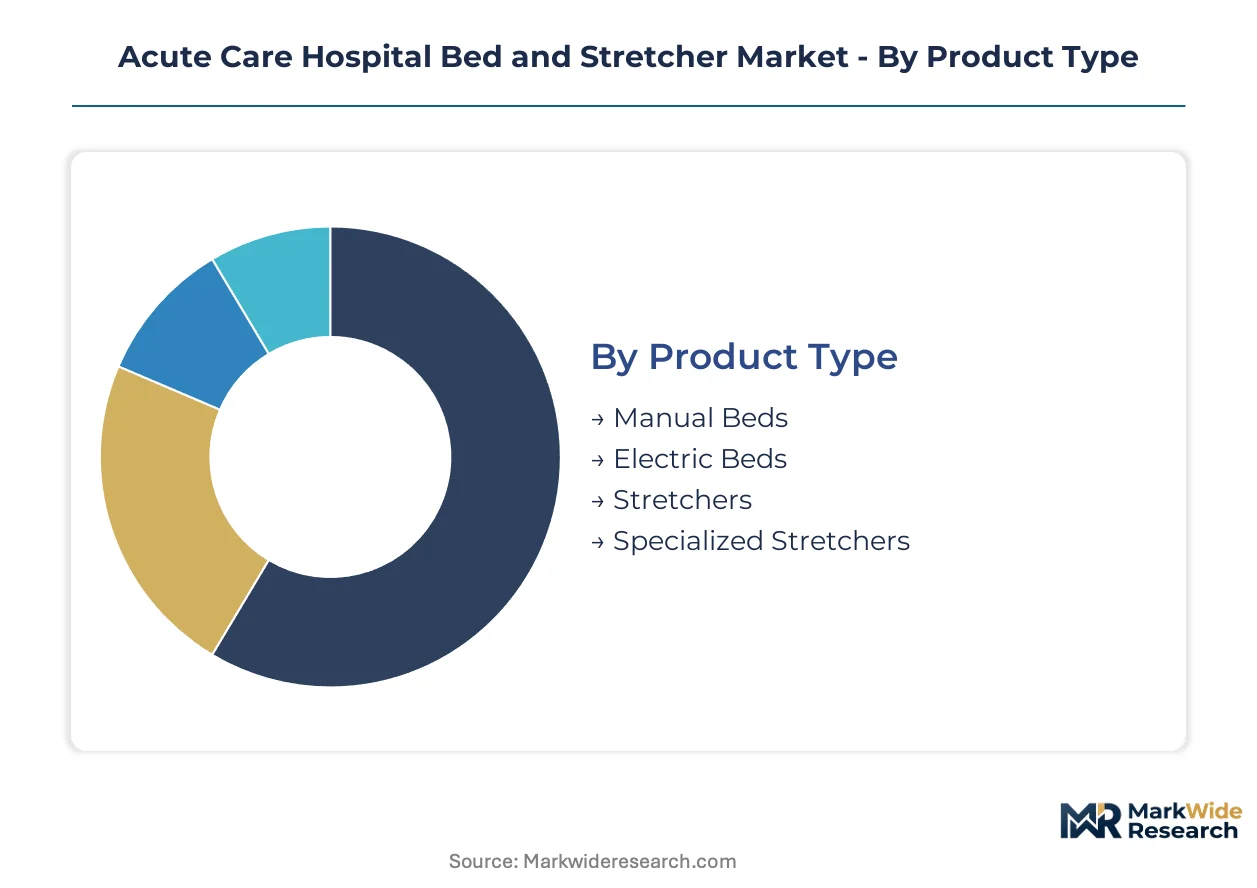
Segmentation in acute care beds and stretchers reveals how regulatory pressure, clinical workflow demands, and capital allocation priorities split procurement decisions across hardware categories. Understanding these divides exposes where manufacturers must align certification, feature sets, and service models to capture hospital system contracts.
Product Type:
FDA 21 CFR entrapment standards and EU MDR Class IIa requirements create divergent compliance burdens across powered versus manual platforms, directly shaping manufacturing cost structures and hospital replacement cycles.
- Electric Beds:Motorized platforms with embedded sensor arrays and programmable positioning enable continuous patient monitoring without wearable attachments. Tertiary hospitals in the United States and Germany are consolidating procurement around ICU-grade electric specifications as nursing labor costs climb and fall prevention liability intensifies.
- Specialized Stretchers:Hydraulic lift mechanisms and radiolucent surfaces designed for surgical and emergency throughput dominate premium margin pools. Hospital systems in Japan prioritize powered stretcher acquisitions through consolidated purchasing consortia to optimize emergency department patient flow metrics.
- Manual Beds:Steel-framed platforms with hand-crank adjustment retain volume dominance in cost-constrained rural clinics and long-term care facilities where capital budgets limit electrification.
- Stretchers:Standard transport platforms with fixed-height or basic hydraulic functionality serve general ward transfers and outpatient procedures where throughput speed matters less than acquisition cost.
Manual beds handle the majority of installed base volume; specialized stretchers are gaining share fastest as emergency department modernization accelerates.
End User:
Capital intensity and reimbursement structure split demand sharply between acute care institutions with centralized procurement power and distributed facilities operating on constrained operating budgets.
- Hospitals:Multi-hospital systems in the United States leverage Group Purchasing Organization contracts to extract volume pricing on smart bed platforms with integrated nurse call and EHR connectivity. FDA cybersecurity premarket review timelines for connected devices extend deployment cycles but do not dampen replacement demand from tertiary centers.
- Long-Term Care Facilities:Skilled nursing operators in rural US markets remain manual-bed dominant, though Medicaid quality metric shifts are creating retrofit demand for pressure relief and bed exit monitoring capabilities.
- Clinics:Outpatient surgical and diagnostic centers prioritize stretcher mobility and rapid turnover over embedded monitoring, driving specification of lightweight aluminum-frame transport platforms.
- Rehabilitation Centers:Patient mobility training requirements favor adjustable height beds with robust side rail configurations and bariatric weight ratings.
Hospitals command the dominant share of premium electric bed revenue; long-term care facilities present the steepest expansion trajectory as regulatory quality pressures mount.
Technology:
Component supply concentration in Asian semiconductor foundries creates lead time risk for powered platforms, while mechanical systems face raw material volatility in steel and aluminum indexes.
- Smart Beds:Capacitive sensor arrays embedded in mattress platforms enable continuous respiration, position, and bed exit detection. ICU departments mandate these specifications in new construction, displacing standalone monitoring devices and compressing bedside equipment footprints.
- Powered Stretchers:Electric motor and battery systems support hydraulic lift and Trendelenburg positioning for surgical and emergency applications. German and French hospital procurement consortia prioritize MDR-certified powered handling equipment, filtering import competition from non-EU suppliers.
- Adjustable Beds:Electric height and articulation controls without full sensor integration serve step-down units and general medical wards where monitoring redundancy exists.
- Pressure Relief Systems:Alternating air mattress overlays and low-air-loss surfaces reduce hospital-acquired pressure injury liability in surgical and immunocompromised patient populations.
Adjustable beds move the highest unit volumes; smart beds are climbing the fastest as health systems mandate embedded monitoring in capital planning cycles.
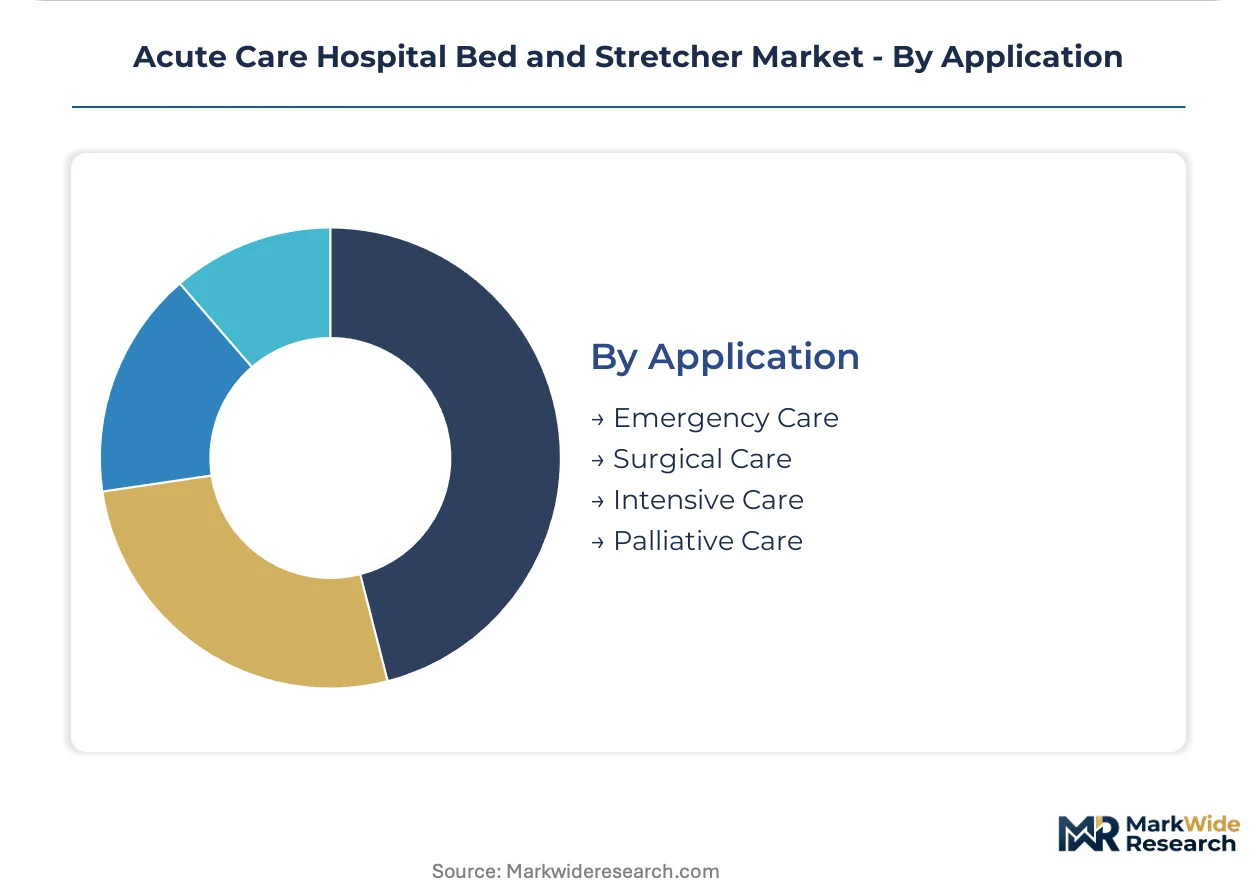
Application:
Clinical acuity determines feature intensity and replacement frequency, with highest-specification platforms concentrated where patient risk and staffing ratios justify premium capital outlay.
- Intensive Care:Multi-parameter sensor integration, automated turning protocols, and seamless EHR data transmission define procurement specifications. Japan's MHLW electromagnetic compatibility testing requirements filter supplier eligibility for ICU-grade connected beds.
- Emergency Care:Powered stretchers with radiolucent surfaces and rapid height adjustment optimize throughput in high-volume trauma receiving centers. Hospital systems consolidate stretcher fleet standardization to reduce biomedical engineering training burden.
- Surgical Care:Operating room beds require C-arm compatibility, extreme positioning range, and load capacity exceeding standard inpatient platforms.
- Palliative Care:Comfort-focused specifications prioritize low-height fall prevention, pressure redistribution surfaces, and quiet motor operation over monitoring intensity.
Intensive care absorbs the highest per-unit investment; emergency care is expanding most quickly as health systems prioritize throughput efficiency metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in acute care beds and stretchers reveal a pronounced trade surplus in precision-manufacturing economies versus import dependence in healthcare infrastructure expansion markets. Germany and Japan maintain net export positions in powered ICU platforms, while the United States and emerging Asian markets absorb premium equipment imports.
United States
Hospital system consolidation through Group Purchasing Organizations concentrates procurement power among multi-facility networks in Texas and Florida. FDA 21 CFR entrapment standards and cybersecurity premarket reviews for connected beds filter supplier eligibility and extend deployment timelines. The Southeast corridor from Atlanta to Miami anchors stretcher fleet standardization programs as Catholic health networks and for-profit chains dominate capital allocation decisions.
Germany
Procurement consortia in Bavaria and North Rhine-Westphalia consolidate purchasing power for MDR-certified powered handling equipment. EU Medical Device Regulation post-market surveillance requirements and CE marking protocols filter import competition from non-EU suppliers. The Stuttgart-Munich industrial corridor hosts manufacturing clusters supplying hydraulic lift mechanisms to domestic and export markets.
Japan
Ministry of Health, Labour and Welfare electromagnetic compatibility testing and PMDA safety protocols create distinct regulatory barriers for imported ICU-grade connected beds. Metropolitan Tokyo and Osaka-Kobe hospital systems prioritize powered stretcher acquisitions through consolidated purchasing to optimize emergency department throughput metrics. Domestic manufacturers leverage localized compliance expertise to defend installed base positions.
China
Hospital infrastructure modernization in the Yangtze River Delta and Pearl River Delta drives demand for electric beds with pressure relief systems. NMPA medical device registration and GB standards compliance shape product design for domestic market access. Shanghai and Shenzhen clusters concentrate assembly capacity for manual and mid-tier adjustable platforms serving cost-sensitive provincial hospitals.
United Kingdom
NHS capital expenditure constraints in England favor refurbished equipment markets and extended replacement cycles for legacy manual beds. MHRA post-Brexit regulatory alignment with EU MDR frameworks creates transitional certification complexity for powered platform suppliers. The Greater Manchester and West Midlands hospital networks experiment with hospital-at-home reimbursement models requiring telehealth-integrated bed specifications.
Acute Care Hospital Bed and Stretcher Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates possessing captive manufacturing depth and established hospital contracting relationships. The vendor base stratifies across three tiers: integrated multinationals with full product portfolios, regional specialists with regulatory proximity advantages, and contract manufacturers serving private-label distributors. Strategic moves center on backward integration into sensor and motor controller supply, plus service contract expansion to capture recurring revenue from smart bed maintenance.
Among North American-based multinationals, Stryker Corporation and Hill-Rom Holdings Inc. exemplify the integrated-tier archetype with vertical control over component supply and direct hospital system relationships. Paramount Bed Holdings Co., Ltd. occupies a position representing regulatory-proximate specialists leveraging Japan's MHLW compliance requirements. Invacare Corporation and Getinge AB sit within the diversified medical technology tier with cross-category hospital equipment portfolios. LINET and ArjoHuntleigh represent European-focused specialists navigating EU MDR certification complexity.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings Inc. |
| Invacare Corporation |
| Getinge AB |
| LINET |
| Paramount Bed Holdings Co., Ltd. |
| ArjoHuntleigh |
| Midmark Corp |
| Medline Industries |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Asian semiconductor foundries directly shapes both component availability floors and electric bed price baselines, with sensor array shortages compressing margins for powered platform manufacturers while steel frame overcapacity sustains manual bed affordability.
Pricing Analysis
Hospital system GPO buyers anchor contract-based long-term procurement structures across the acute care bed market. Three-tier pricing structure across premium ICU-grade smart beds, standard adjustable electric platforms, and economy manual frames reflects FDA cybersecurity certification tiers and embedded sensor sophistication. Cost compression in the economy manual tier is intensifying because steel commodity volatility squeezes foundry margins. Rural long-term care facilities exhibit highest price sensitivity, while tertiary hospital systems prioritize clinical integration over unit cost.
Supply Chain Analysis
Strategic stockpiling of motor controllers and sensor arrays dominates inventory strategy as lead time volatility from Taiwan, South Korea, and China exposes OEMs to production disruption. Frame fabrication draws from domestic steel rolling capacity in Germany and Japan, while hydraulic lift mechanisms rest on precision machining clusters in the Stuttgart-Munich corridor. Single-source vulnerability in Asian semiconductor foundry concentration represents the dominant structural risk. Distribution runs through direct hospital contracting networks for premium tiers and regional medical equipment distributors for cost-constrained segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart bed platforms are transitioning toward ecosystem economics where EHR interoperability and telehealth convergence determine competitive viability, with sensor data liquidity becoming the primary value capture mechanism.
For Market Incumbents: Secure captive supply of motor controllers and capacitive sensor arrays through backward integration into Asian semiconductor partnerships, insulating production from foundry allocation volatility. Fortify FDA cybersecurity premarket submission capabilities to compress revenue recognition timelines as wireless data transmission protocols face extended regulatory scrutiny. Service contract expansion into sensor calibration and software maintenance captures recurring revenue streams as hospital biomedical engineering talent scarcity deepens. For New Entrants and Emerging Players: Differentiate on telehealth-integrated bed specifications targeting hospital-at-home reimbursement codes, where regulatory greenfield status offsets incumbent installed base advantages. Penetrate rural US skilled nursing facilities through Medicaid quality metric alignment, retrofitting manual bed dominant installed bases with pressure relief and bed exit monitoring overlays. Pursue EU MDR certification investment to filter import competition and access German and French procurement consortia tender evaluations. For Investors and Strategic Acquirers: Regional specialists with established notified body relationships and localized regulatory compliance infrastructure offer asymmetric exposure to EU MDR and Japan MHLW certification tailwinds. Long-term viability hinges on software-enabled service revenue transition, with hardware margins compressing as sensor commoditization accelerates. Watch for FDA cybersecurity premarket review timeline normalization as inflection indicator for connected platform revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive semiconductor sourcing from Taiwan and South Korea insulates production from foundry allocation volatility. |
| FDA Cybersecurity Premarket Investment | Accelerated 510(k) timelines for wireless data transmission protocols compress revenue recognition delays. |
| Hospital System Direct Contracting | GPO consolidation in Texas and Florida demands multi-facility volume pricing and EHR integration capabilities. |
| EU MDR Certification Subsidiary | Establishing EU-based quality management entities filters import competition from Asian producers. |
| Telehealth Platform Integration | Bed-embedded sensor convergence with remote monitoring platforms opens hospital-at-home reimbursement codes. |
Research Methodology
Operator-level perspectives from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and ICU clinical staff anchored the qualitative base for this study. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract repositories, and steel commodity trade data. Bottom-up unit demand modeling triangulated against top-down capital expenditure forecasts across acute care infrastructure modernization programs.
Sensitivity analysis across steel price volatility bands, semiconductor lead time scenarios, and regulatory review duration distributions tested forecast robustness throughout the projection horizon. Segmentation modeling captured product type splits across electric, manual, and stretcher platforms; technology tiers spanning smart, powered, and pressure relief systems; and application intensity across intensive care, emergency, surgical, and palliative settings. CAGR derivation incorporated replacement cycle compression from FDA entrapment standard enforcement and ICU infrastructure modernization cadence in Germany and Japan.
Material uncertainties — steel and aluminum commodity index swings, Asian foundry capacity allocation disruptions, FDA cybersecurity premarket review timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding hospital capital expenditure continuity and regulatory certification pathway stability. Revision becomes warranted when semiconductor supply concentration or cybersecurity compliance friction crosses thresholds that materially alter OEM production schedules or revenue recognition timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Biofeedback Equipment Market