
 Canada Bariatric Surgery Market | 2026-2036
Canada Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Bariatric Surgery Market Outlook
Procedure bundling into comprehensive metabolic care packages is restructuring how Canadian hospitals procure bariatric services. Medtronic PLC leverages its integrated surgical stapling and monitoring portfolio to anchor contracts with provincial health networks. Johnson & Johnson competes through its broad device ecosystem spanning sutures to energy platforms. Intuitive Surgical Inc specializes in robotic-assisted installations that command premium positioning in academic medical centers.
Bariatric surgery encompasses restrictive, malabsorptive, and combined procedures that alter gastrointestinal anatomy to achieve sustained weight reduction and metabolic improvement; gastric bypass and sleeve gastrectomy dominate Canadian procedure volumes due to superior long-term remission rates for type 2 diabetes. Laparoscopic technique remains the standard of care, though robotic-assisted platforms are capturing share in high-volume centers where precision and ergonomics reduce surgeon fatigue. Hospitals constitute the primary end-user setting, absorbing the majority of complex revisions and conversions, while ambulatory care facilities are carving out selective primary sleeve gastrectomy cases in provinces with streamlined referral pathways.
Health Canada and the Canadian Agency for Drugs and Technologies in Health (CADTH) jointly govern device approval and evidence-based reimbursement recommendations that determine provincial listing decisions. Provincial formularies and wait-time benchmarks from bodies such as Ontario Health directly shape surgical throughput and capital equipment procurement cycles. Stakeholders must track CADTH health technology reassessments and emerging provincial bundled-payment pilots that could redistribute margin pools between device manufacturers and hospital operators.
Market Dynamics
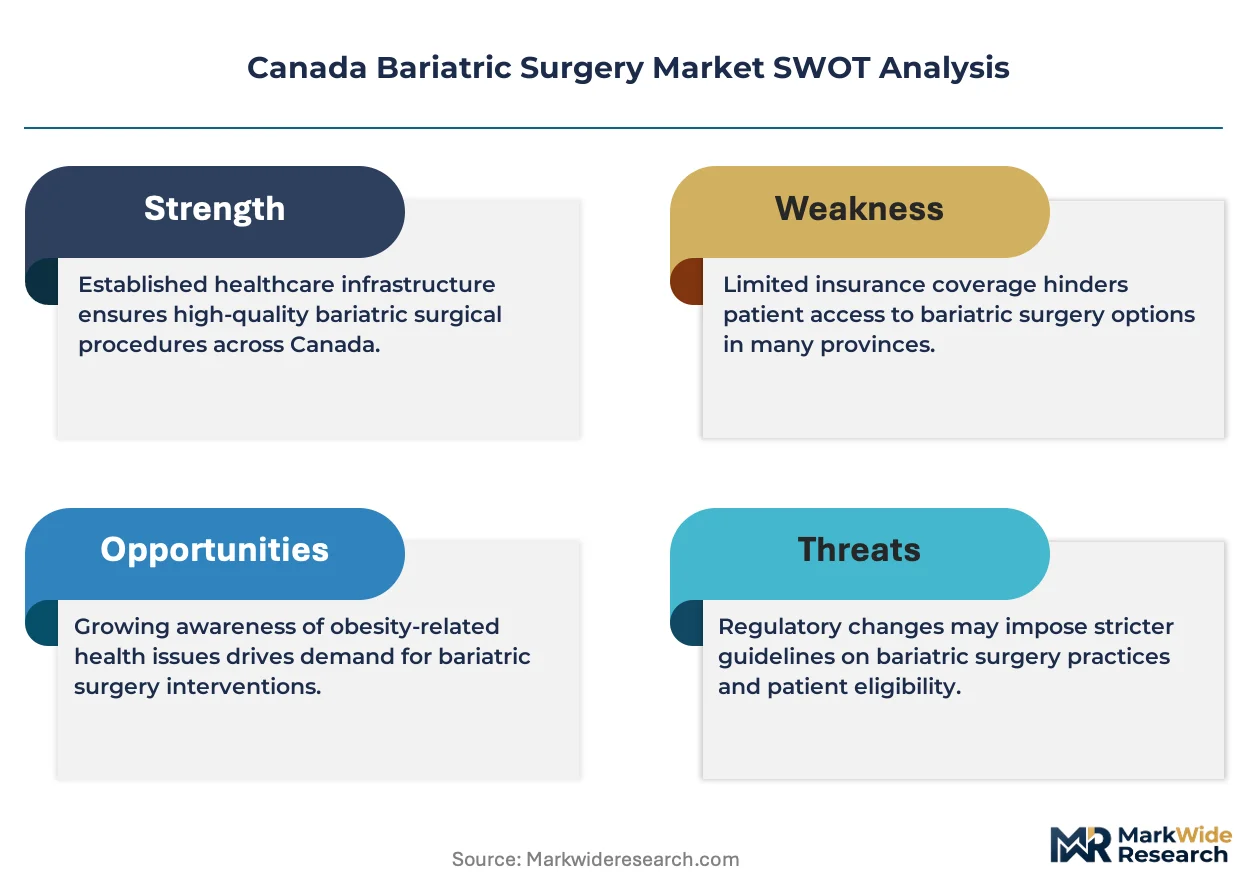
Provincial bundled-payment pilots are compressing margin pools between device manufacturers and hospital operators, forcing suppliers to restructure contract terms around metabolic outcomes rather than discrete procedure volumes.
Growth Catalysts
- Type 2 diabetes remission protocols:Ontario Health and similar provincial bodies now mandate bariatric surgery as first-line therapy for obese diabetics, expanding eligible patient pools beyond traditional BMI thresholds.
- Robotic platform diffusion:Academic medical centers in Quebec and British Columbia prioritize da Vinci installations for sleeve gastrectomy precision, creating upgrade cycles in teaching hospitals.
- CADTH evidence reassessments:Health Canada's joint reviews with provincial health technology agencies accelerate device listing decisions, shortening time-to-reimbursement for novel stapling and energy platforms.
Market Restraints
- Specialized surgeon scarcity:Fellowship-trained bariatric surgeons concentrate in Toronto, Montreal, and Vancouver corridors, creating wait-time bottlenecks exceeding 18 months in Atlantic provinces.
- Capital equipment intensity:Robotic-assisted suites require $2.5M+ installation commitments plus annual service contracts, straining capital budgets of community hospitals outside urban surgical clusters.
- Revision surgery complexity:Failed gastric band procedures from earlier decades generate costly conversions to bypass or sleeve, consuming OR capacity without generating new patient revenue.
Strategic Opportunities
- Ambulatory care expansion:Streamlined referral pathways in Alberta and Saskatchewan enable selective sleeve gastrectomy cases in standalone surgical centers, decoupling volume from inpatient bed availability.
- Metabolic surgery bundling:Provincial pilots in Ontario test comprehensive care packages spanning preoperative endocrinology through five-year follow-up, opening margin capture for integrated service providers.
- Indigenous health partnerships:Northern Ontario and Manitoba health authorities seek mobile bariatric screening and tele-surgical consultation to address geographic access gaps.
Industry Challenges
- Multidisciplinary program staffing:Psychologists, dietitians, and endocrinologists required for accredited centers face recruitment competition from private metabolic clinics.
- Device traceability compliance:Health Canada's strengthened medical device regulations demand enhanced lot tracking for implanted stapling cartridges, forcing inventory system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Bariatric Surgery Market |
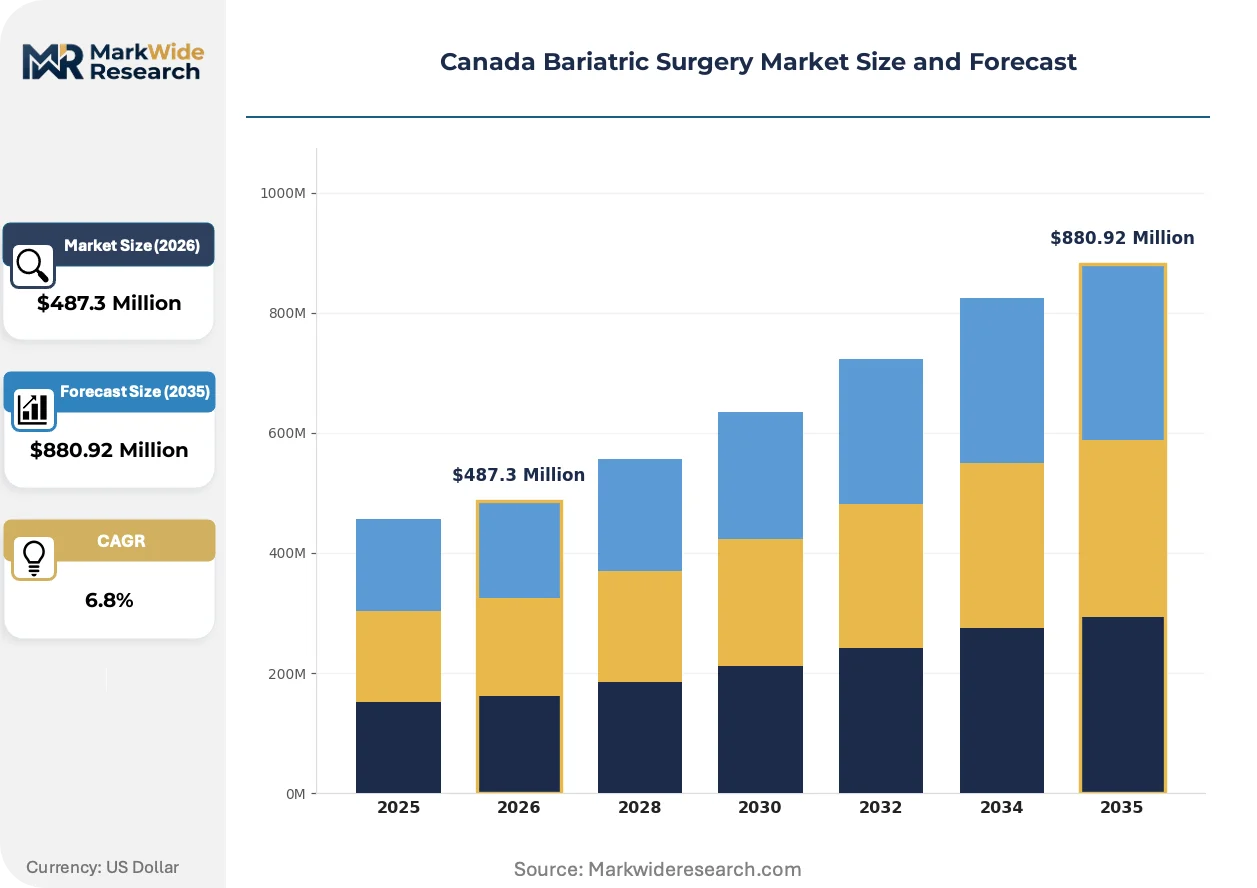
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion Technique: Laparoscopic, Open Surgery, Robotic-Assisted, Endoscopic End User: Hospitals, Surgical Centers, Ambulatory Care, Specialty Clinics Demographics: Adults, Adolescents, Elderly, Obesity Class |
| Companies Covered | Medtronic PLC, Apollo Endosurgery Inc, Olympus Corporation, The Cooper Companies, 3M Company, ReShape Lifesciences Inc, GI Dynamics, Johnson & Johnson, Intuitive Surgical Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Bariatric Surgery Market Strategic Shifts
Digital surgical planning and intraoperative navigation are compressing operative variability while provincial reimbursement models pivot toward episode-based payments that reward long-term metabolic outcomes over procedure throughput.
Single-anastomosis duodeno-ileal bypass with sleeve gastrectomy (SADI-S) is unifying restrictive and malabsorptive mechanisms in one operative session. High-volume Ontario centers adopt this configuration for super-obese patients with refractory diabetes. The procedure is unifying metabolic and bariatric service lines previously siloed under separate departmental budgets.
Health Canada's 2023 strengthened medical device regulations now mandate post-market surveillance for all implanted surgical staplers, accelerating adverse event reporting timelines from 30 to 10 days. Manufacturers must submit annual safety summaries to maintain licenses. Class III device holders are responding by embedding clinical affairs teams within Canadian subsidiaries rather than managing submissions from US headquarters.
Hospital procurement committees now require five-year total cost-of-ownership analyses for robotic platforms, unbundling capital, disposable, and maintenance expenditures. Vancouver Coastal Health and similar authorities weight surgeon ergonomics and conversion-to-open rates alongside sticker price. This behavioral shift favors vendors offering outcome guarantees and training commitments over equipment-only transactions.
Canada Bariatric Surgery Market Segmentation
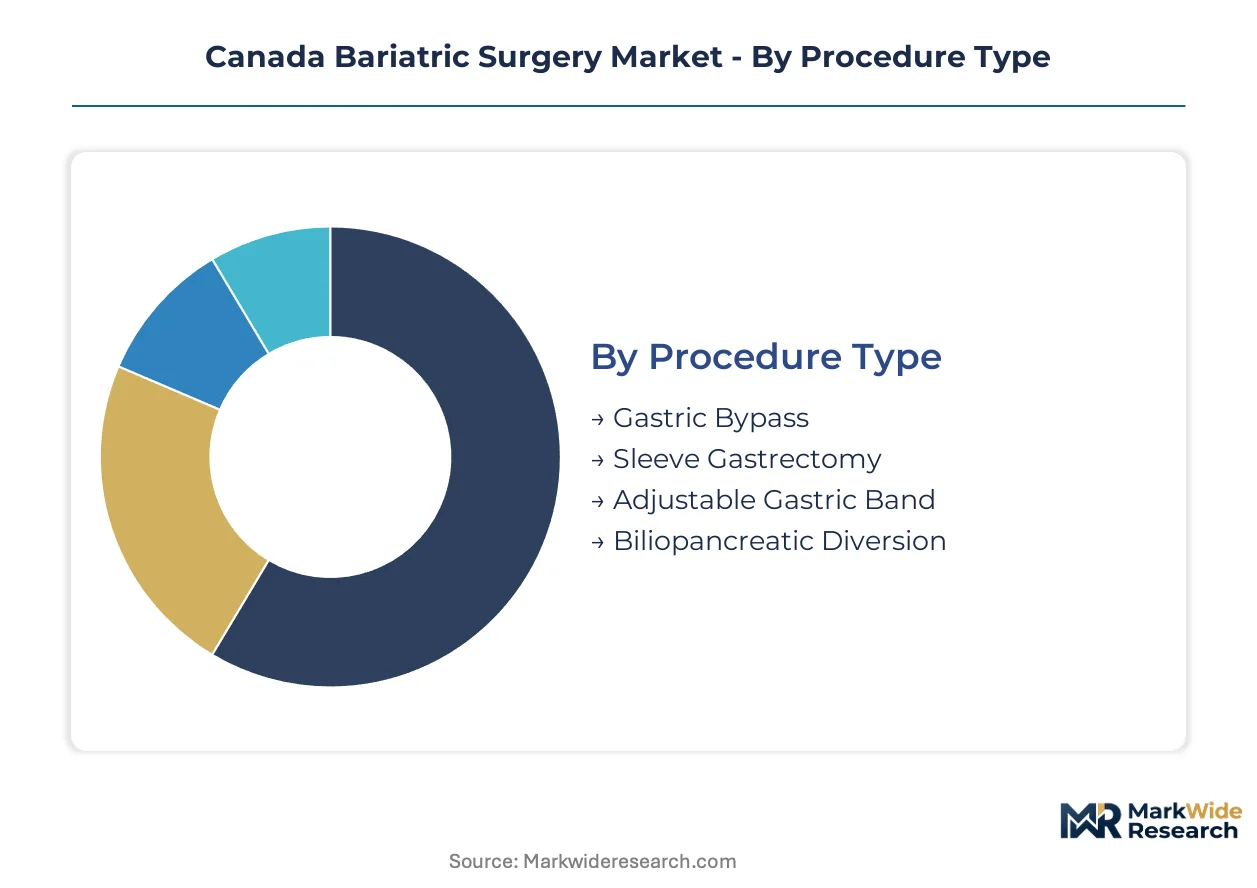
Procedure mix and technique selection determine reimbursement pathways and capital allocation across Canadian provincial health networks. Demographic targeting and site-of-service decisions reshape where margin pools concentrate between device manufacturers and care delivery operators.
Procedure Type:
Technical sophistication and metabolic efficacy differentiate procedural categories in provincial coverage decisions.
- Sleeve Gastrectomy:Vertical gastric resection preserves pyloric function while reducing ghrelin secretion. Ontario Health prioritizes this configuration for BMI 35-50 cohorts, compressing wait times through standardized referral protocols.
- Gastric Bypass:Roux-en-Y reconstruction delivers superior diabetes remission rates through proximal intestinal exclusion. Quebec's university hospitals anchor volume here, leveraging fellowship-trained surgeons for complex metabolic cases.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port access dominates revision surgery queues. Earlier-generation implants from the 2000s now drive conversion demand.
- Biliopancreatic Diversion:Malabsorptive limb configuration reserved for super-obese patients with refractory metabolic syndrome. British Columbia's tertiary centers maintain selective expertise.
Mature deployment sits with Gastric Bypass. Newer deployment is concentrated in Sleeve Gastrectomy.
Technique:
Instrumentation intensity and surgeon ergonomics stratify capital requirements across facility types.
- Laparoscopic:Multiport abdominal access with 5-12mm trocar placement remains the standard-of-care default. Community hospitals across Alberta and Saskatchewan standardize here to minimize equipment overhead.
- Robotic-Assisted:Da Vinci platform deployment enables wristed articulation in tight mediastinal spaces. Toronto's University Health Network and Montreal's McGill University Health Centre anchor installation density.
- Open Surgery:Midline laparotomy reserved for conversion scenarios and revisional adhesiolysis. Atlantic provinces retain higher open rates due to fellowship training gaps.
- Endoscopic:Transoral approaches including sleeve gastroplasty and intragastric balloon deployment. Private pay clinics in Vancouver and Calgary pilot these configurations outside provincial formularies.
Volume concentrates in Laparoscopic. Margin expansion is climbing the fastest in Robotic-Assisted.
End User:
Regulatory accreditation and reimbursement bundling determine site eligibility for complex metabolic procedures.
- Hospitals:Inpatient bed capacity and ICU backup required for leak management and hemorrhage control. Provincial health authorities mandate this setting for bypass and revision cases.
- Surgical Centers:Standalone facilities with overnight observation capability. Alberta Health Services licenses selective sleeve gastrectomy here through streamlined accreditation.
- Ambulatory Care:Same-day discharge protocols for low-BMI sleeve candidates with robust home support. Saskatchewan's rural health regions pilot telemedicine follow-up to enable this shift.
- Specialty Clinics:Private metabolic centers offering endoscopic and medical weight management. Ontario restricts these from provincial billing for surgical intervention.
Complex cases cluster in Hospitals. Same-day volume is expanding most quickly in Ambulatory Care.
Demographics:
Comorbidity burden and surgical risk profile shape candidacy thresholds and informed consent protocols.
- Adults:Working-age population with type 2 diabetes and cardiovascular risk dominates procedural volume. Ontario's employer-sponsored disability programs track return-to-work metrics post-intervention.
- Obesity Class:BMI stratification into Class II and III categories determines medical necessity documentation. CADTH reviews evidence thresholds separately for BMI 35-40 versus 40+ populations.
- Adolescents:Pediatric metabolic surgery requires specialized accreditation and family-based behavioral support. The Hospital for Sick Children in Toronto anchors national expertise.
- Elderly:Patients over 65 with frailty indices require modified anesthesia protocols. British Columbia's patient prioritization frameworks deprioritize this cohort for non-diabetic indications.
Volume leadership rests with Adults. Steepest expansion trajectory is emerging in Adolescents as pediatric accreditation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada produces surgical expertise and device demand simultaneously. Metropolitan teaching hospitals generate procedure volume that attracts capital investment from equipment manufacturers. Provincial health authorities redistribute this consumption across urban surgical corridors.
Ontario
Toronto's University Health Network and Hamilton Health Sciences anchor the nation's highest bariatric procedure volumes. Ontario Health mandates surgery as first-line therapy for obese diabetics, expanding eligibility beyond traditional BMI thresholds. The Greater Toronto Area concentrates fellowship-trained surgeons and robotic platform installations.
Quebec
McGill University Health Centre and CHUM in Montreal specialize in complex metabolic cases requiring Roux-en-Y reconstruction. The province's health technology assessment body accelerates device listings through parallel CADTH reviews. Quebec's university hospitals prioritize da Vinci installations for sleeve gastrectomy precision.
British Columbia
Vancouver Coastal Health and Fraser Health Authority manage super-obese patients with refractory diabetes through tertiary referral networks. Health Canada and PMRA joint oversight shapes provincial procurement timelines for novel stapling platforms. Vancouver's surgical cluster leads ambulatory care pilots for same-day sleeve gastrectomy discharge.
Alberta
Alberta Health Services licenses standalone surgical centers for selective sleeve gastrectomy through streamlined accreditation pathways. The province's bundled-payment experiments test comprehensive metabolic care packages spanning preoperative endocrinology through five-year follow-up. Calgary and Edmonton anchor Prairie province surgical capacity.
Atlantic Canada
New Brunswick and Nova Scotia face wait-time bottlenecks exceeding eighteen months due to fellowship-trained surgeon scarcity. Provincial health authorities explore mobile bariatric screening and tele-surgical consultation to address geographic access gaps. Halifax's QEII Health Sciences Centre maintains limited complex revision capability.
Canada Bariatric Surgery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Canada's bariatric surgery market. Medtronic PLC and Johnson & Johnson leverage integrated surgical portfolios to anchor provincial health network contracts. Intuitive Surgical Inc commands premium positioning through robotic-assisted platform installations. Competitive moves center on outcome guarantees and training commitments rather than equipment-only transactions.
Within the diversified medical technology tier, Medtronic PLC and Johnson & Johnson exemplify portfolio breadth spanning stapling, energy, and monitoring platforms. Intuitive Surgical Inc occupies the specialized robotic-assisted position, with installations concentrated in Toronto, Montreal, and Vancouver teaching hospitals. These three companies represent the dominant competitive archetypes shaping procurement negotiations with provincial health authorities.
| Leading Market Players |
|---|
| Medtronic PLC |
| Apollo Endosurgery Inc |
| Olympus Corporation |
| The Cooper Companies |
| 3M Company |
| ReShape Lifesciences Inc |
| GI Dynamics |
| Johnson & Johnson |
| Intuitive Surgical Inc |
| Others |
Value Chain & Pricing Dynamics
Disposable stapler cartridge costs cascade through three-tier pricing structures across premium, standard, and economy levels, with Health Canada's 2023 post-market surveillance mandates forcing inventory system upgrades that compress margin pools for community hospitals while academic centers absorb premium robotic platform expenditures through provincial bundled-payment pilots.
Pricing Analysis
Margin tightening in standard-tier laparoscopic instrumentation reflects Ontario Health's episode-based payment pilots that unbundle capital, disposable, and maintenance expenditures into five-year total cost-of-ownership frameworks. Price differentiation hinges on Health Canada Class III device certification tiers and surgeon training commitments bundled with platform installations. Cost-down pressure on economy-tier open surgery equipment accelerates as Atlantic provinces delay capital refresh cycles amid fellowship-trained surgeon scarcity. Community hospitals outside Toronto, Montreal, and Vancouver corridors exhibit highest price sensitivity; academic medical centers with da Vinci installations demonstrate lowest sensitivity due to outcome guarantee contracts.
Supply Chain Analysis
Health Canada's strengthened medical device regulations and domestic-content preferences for post-market surveillance teams reshape sourcing toward Canadian-based clinical affairs subsidiaries rather than US headquarters management. Supply concentration rests on Ireland and Costa Rica for surgical stapler manufacturing, with precision robotic instrumentation anchored in California and Connecticut production facilities. Titanium and medical-grade polymer feedstocks draw from Chinese and German chemical processors. Single-source vulnerability concentrates in da Vinci platform service contracts. Distribution runs through provincial health network procurement committees that mandate five-year total cost-of-ownership analyses before capital authorization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over surgeon training pipelines and post-market surveillance infrastructure determines contract durability with provincial health authorities.
For Market Incumbents: Acquire fellowship-trained surgeon networks to lock in academic medical center preference. Secure exclusive training commitments with McGill University Health Centre and University Health Network to block robotic platform competitors. Deepen backward integration into post-market surveillance infrastructure to satisfy Health Canada's 10-day adverse event reporting mandates without US headquarters latency.
For New Entrants and Emerging Players: Tele-surgical consultation platforms offer the lowest barrier entry into Atlantic Canada and Northern Ontario access gaps. Target standalone surgical centers in Alberta and Saskatchewan where streamlined accreditation enables selective sleeve gastrectomy volume outside hospital procurement committees. Partner with Indigenous health authorities on mobile bariatric screening to bypass Toronto-Montreal-Vancouver corridor concentration.
For Investors and Strategic Acquirers: CADTH evidence reassessments accelerating device listing decisions is the leading indicator that reimbursement velocity will favor integrated metabolic care providers over discrete equipment vendors. Five-to-ten year viability favors companies with stapling, energy, and monitoring portfolios that anchor comprehensive care package contracts. Watch for Ontario bundled-payment pilot expansion signals as inflection points for margin pool redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Health Network Partnership | Ontario Health bundled-payment pilots reward long-term metabolic outcome guarantees over procedure throughput volume. |
| Robotic Platform Training Commitment | McGill University Health Centre and University Health Network prioritize da Vinci installations with embedded surgeon education programs. |
| Post-Market Surveillance Infrastructure | Health Canada's 10-day adverse event reporting mandates favor vendors with Canadian-based clinical affairs teams. |
| Ambulatory Care Accreditation | Alberta Health Services licenses standalone surgical centers for selective sleeve gastrectomy outside hospital bed constraints. |
| Indigenous Health Mobile Screening | Northern Ontario and Manitoba authorities seek tele-surgical consultation to address geographic access gaps. |
Study Parameters
Independent corroboration across hospital procurement committee members, biomedical engineering directors, and provincial health technology assessment officers underwrites the qualitative findings in this study. Primary interviews with bariatric surgeons, GPO contracts managers, and CADTH evidence review staff combined with secondary validation from Health Canada device licensing databases, provincial formulary listings, and hospital capital expenditure disclosures. Bottom-up procedure volume modeling and top-down provincial health authority budget triangulation anchored market sizing.
Comparable historical periods spanning pre-pandemic through post-surge recovery established baseline utilization patterns across the projection horizon. Segmentation modeling incorporated procedure type, surgical technique, end-user facility accreditation tier, and patient BMI stratification. CAGRs were derived from provincial wait-time benchmark trajectories and robotic platform installation pipelines. Forecast inputs included CADTH reassessment calendars and Ontario Health bundled-payment pilot expansion signals.
Inputs from hospital procurement databases and provincial health authority capital plans were available through the study window; gaps in real-time robotic platform utilization rates introduce uncertainty bands around academic medical center volume assumptions. Forecasts reflect documented assumptions regarding provincial reimbursement policy continuity and surgeon fellowship training pipeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market