
 Hydrotherapy Equipment Market | 2026-2036
Hydrotherapy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrotherapy Equipment Market Intelligence
Rehabilitation centers is rotating toward hydrotherapy equipment as post-acute care providers seek alternatives to pharmaceutical pain management. Jacuzzi Inc. anchors the residential wellness segment through established brand equity in jetted bath systems. HYDROWORX specializes in variable-depth underwater treadmills for clinical gait retraining. Kohler Co competes across the premium whirlpool bath category with integrated hydro-massage configurations.
Hydrotherapy equipment encompasses electromechanical and plumbing-based systems designed to deliver temperature-controlled, pressurized water for therapeutic intervention, typically operating within precise thermal ranges and flow-rate parameters to achieve tissue mobilization or cardiovascular conditioning. Whirlpool baths retain the largest installed base among product types, though cold plunge tubs are gaining fastest as athletic recovery protocols expand beyond elite sports. In the end-user dimension, hospitals maintain mature procurement cycles while spa facilities capture expanding margin pools through premium wellness positioning. Permanent installations dominate infrastructure-heavy settings, yet modular solutions are penetrating satellite clinics requiring deployment flexibility.
FDA 510(k) clearance governs Class II hydrotherapy devices in the United States, while ISO 13485 quality management standards apply to manufacturers targeting regulated medical markets. The EU Medical Device Regulation imposes conformity assessment requirements on hydrotherapy equipment with therapeutic claims, affecting export access for non-European suppliers. Stakeholders must monitor evolving reimbursement codes for aquatic therapy across public and private payers to anticipate procurement velocity shifts.
Market Dynamics
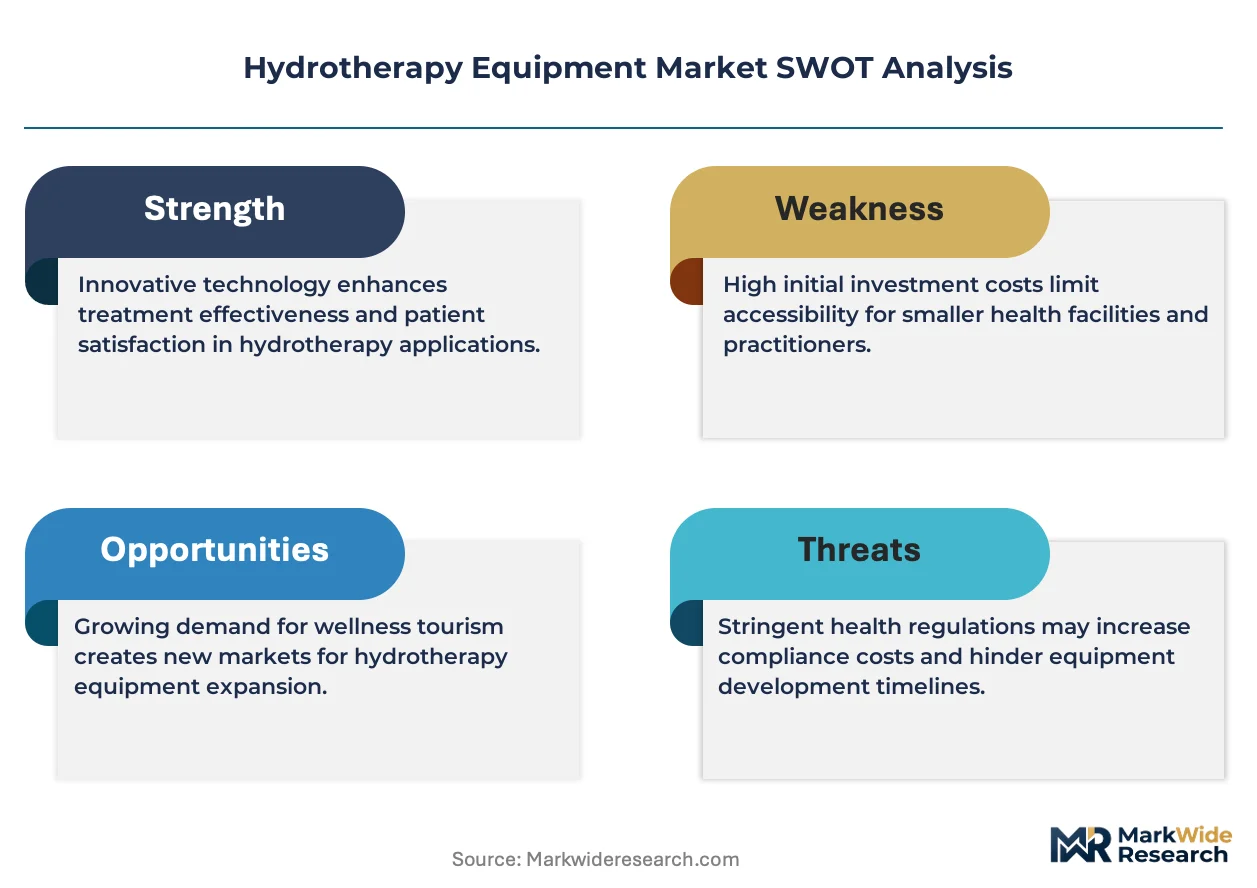
Reimbursement code expansions for aquatic therapy are compressing hospital procurement cycles while accelerating satellite clinic deployments across North America and Western Europe. This structural shift toward decentralized care delivery is redistributing equipment demand from permanent installations toward modular, transportable systems.
Growth Catalysts
- Post-surgical rehabilitation protocols:Orthopedic centers in Germany leverage statutory rehabilitation coverage to integrate underwater treadmill systems into standardized recovery pathways.
- FDA 510(k) pathway efficiency:Streamlined Class II device clearances for hydrotherapy equipment reduce time-to-market for electromechanical systems targeting clinical gait retraining.
- Cold plunge adoption:Athletic recovery facilities beyond elite sports are installing temperature-controlled immersion systems to serve amateur endurance athletes and corporate wellness programs.
Market Restraints
- Stainless steel input volatility:Fluctuating nickel and chromium prices compress margin structures for whirlpool bath manufacturers dependent on corrosion-resistant alloys.
- EU MDR conformity costs:The Medical Device Regulation imposes elevated clinical evidence requirements on hydrotherapy equipment with therapeutic claims, raising barriers for non-European exporters.
- Pharmaceutical pain management substitution:Opioid-based protocols retain institutional inertia in certain post-acute settings despite aquatic therapy efficacy data.
Strategic Opportunities
- Home-based rehabilitation:Residential jetted bath systems with clinical-grade temperature controls address aging-in-place demographics in Japan and the United States.
- ISO 13485 certification arbitrage:Quality management compliance enables premium pricing for manufacturers targeting regulated medical markets versus wellness-only positioning.
- Telehealth integration:Remote monitoring sensors embedded in hydrotherapy equipment enable outcome tracking for payers piloting value-based reimbursement models.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in fluid dynamics and therapeutic temperature control limits R&D velocity for mid-tier manufacturers.
- Legacy plumbing infrastructure:Hospital retrofit requirements for water pressure and drainage specifications extend installation timelines and inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrotherapy Equipment Market |
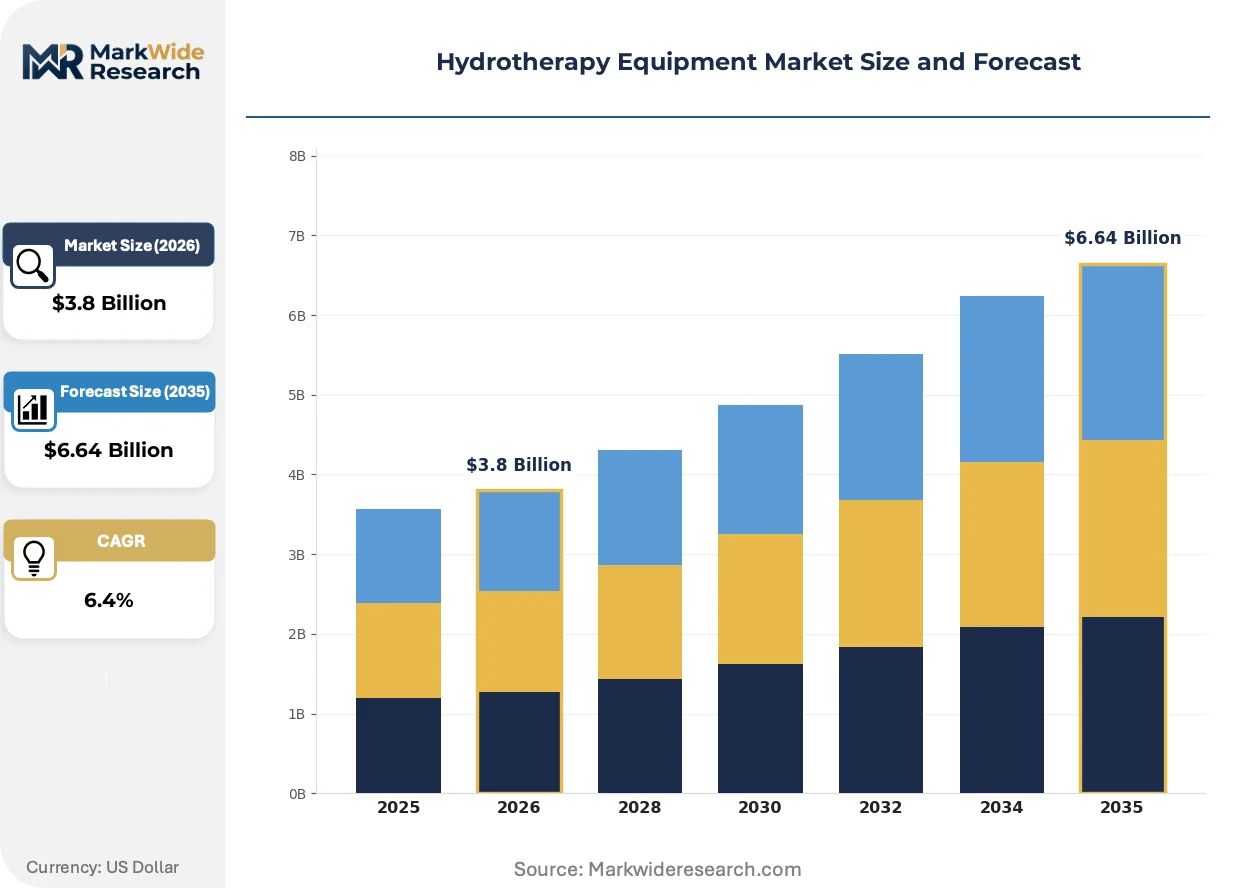
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whirlpool Baths, Aqua Treadmills, Hydro Massage Equipment, Cold Plunge Tubs End User: Rehabilitation Centers, Spa Facilities, Fitness Centers, Hospitals Application: Physical Therapy, Sports Medicine, Wellness Treatments, Pain Management Installation Type: Permanent Installations, Portable Systems, Wall-Mounted Units, Modular Solutions |
| Companies Covered | Prime Pacific Health Innovations Corporation, Jacuzzi Inc., HYDROWORX, Sidmar Manufacturing, Inc., Kohler Co, EWAC, SwimEx Inc, Narang Medical Limited, Hydro Physio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrotherapy Equipment Market Strategic Shifts & Innovations
Electromechanical precision is overtaking passive hydro-massage systems as clinical evidence demands measurable therapeutic outcomes. Equipment manufacturers are embedding sensor arrays and automated feedback loops to satisfy payer documentation requirements.
Variable-depth underwater treadmills with integrated force plates are displacing fixed-depth pool systems in neurological rehabilitation settings. Stroke recovery centers in the United States and Germany are adopting these platforms to quantify gait symmetry during aquatic locomotion. The technology is displacing subjective therapist observation with objective biomechanical data, compressing the standard of care for motor function assessment.
The EU Medical Device Regulation's expanded clinical evidence requirements are reshaping conformity assessment pathways for hydrotherapy equipment with therapeutic claims. Manufacturers targeting European markets must now compile post-market surveillance data and risk management documentation beyond previous Medical Device Directive thresholds. Class II devices with cardiovascular conditioning indications face the steepest compliance burden, prompting some suppliers to narrow their CE-marked product portfolios.
Hospital procurement departments are unbundling equipment purchases from long-term service contracts, forcing manufacturers to compete on upfront capital cost rather than bundled lifecycle pricing. This behavior shift pressures margin structures for suppliers historically dependent on captive aftermarket revenue streams. The pattern is most pronounced in United States health systems responding to capital expenditure constraints from Medicare reimbursement compression.
Hydrotherapy Equipment Market Segmentation
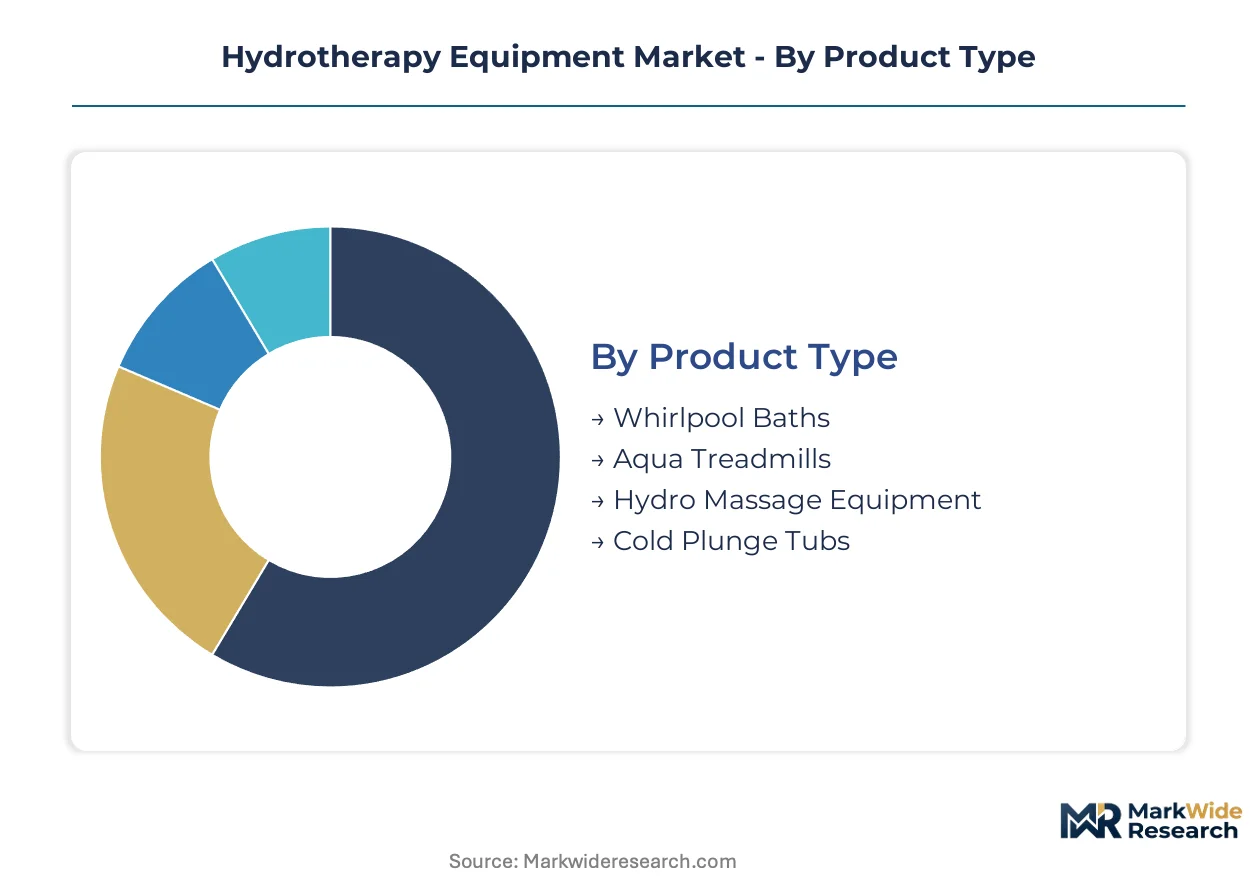
Segmentation in hydrotherapy equipment reveals divergent technology requirements across clinical and wellness environments. Product specifications vary dramatically between FDA-regulated rehabilitation settings and discretionary spa installations. Understanding these boundaries shapes procurement strategy and regulatory compliance pathways.
Product Type:
Domestic demand concentrates on whirlpool baths and hydro massage equipment for residential wellness, while aqua treadmills and cold plunge tubs draw heavier export volumes to clinical and athletic facilities in Germany and Japan.
- Whirlpool Baths:These systems integrate jetted water circulation with precise temperature controls for tissue mobilization. Rehabilitation centers in Germany deploy clinical-grade units under statutory coverage, though residential installations dominate volume in the United States. Whirlpool baths hold the largest share; momentum sits with cold plunge tubs.
- Cold Plunge Tubs:Temperature-controlled immersion systems operating at therapeutic cold ranges support athletic recovery protocols. Corporate wellness programs and amateur endurance facilities in the United States are expanding installations beyond elite sports infrastructure. Cold plunge tubs are gaining share fastest among all product types.
- Aqua Treadmills:Variable-depth underwater platforms with electromechanical drive systems enable gait retraining in neurological rehabilitation.
- Hydro Massage Equipment:Pressurized water jet arrays target specific muscle groups without full immersion requirements.
Electromechanical precision is displacing passive hydro-massage systems as clinical evidence demands measurable therapeutic outcomes.
End User:
Cost tier stratification separates capital-intensive hospital procurement from margin-focused spa facility deployments, with rehabilitation centers occupying the mid-tier reimbursement corridor.
- Rehabilitation Centers:These facilities integrate hydrotherapy into standardized post-surgical recovery pathways. German centers leverage statutory coverage to procure underwater treadmill systems, while Medicare reimbursement codes shape purchasing velocity in the United States. Rehabilitation centers anchor clinical demand; spa facilities capture expanding margin pools.
- Spa Facilities:Premium wellness positioning drives investment in aesthetic hydro-massage and thermal experience configurations. Medical spa infrastructure in Germany creates dense procurement clusters for multi-modality installations.
- Fitness Centers:Athletic recovery zones within commercial gyms are adopting cold plunge protocols to differentiate membership value.
- Hospitals:Mature procurement cycles emphasize unbundled equipment purchases over long-term service contracts under capital expenditure constraints.
Decentralized care delivery is redistributing demand from hospital capital budgets toward satellite clinic and fitness center deployments.
Application:
Volume concentration follows reimbursement code availability, with physical therapy and pain management capturing institutional spend while wellness treatments rely on discretionary consumer payment.
- Physical Therapy:Aquatic locomotion protocols leverage buoyancy to reduce joint loading during motor function rehabilitation. Stroke recovery centers in the United States and Germany are adopting force plate-integrated treadmills to quantify gait symmetry objectively.
- Sports Medicine:Cold immersion and contrast hydrotherapy support return-to-play protocols for musculoskeletal injuries. Athletic training facilities are embedding temperature-controlled systems into standardized recovery workflows.
- Wellness Treatments:Thermal hydrotherapy and hydro-massage target stress reduction and circulation improvement without clinical diagnostic requirements.
- Pain Management:Aquatic therapy offers non-pharmaceutical alternatives to opioid-based protocols in post-acute settings, though institutional inertia persists in certain care environments.
Physical therapy commands the deepest installed base; sports medicine applications are expanding most quickly as athletic recovery protocols proliferate beyond elite competition.
Installation Type:
Customer type stratification separates infrastructure-heavy permanent installations from deployment-flexible modular solutions serving satellite clinic networks.
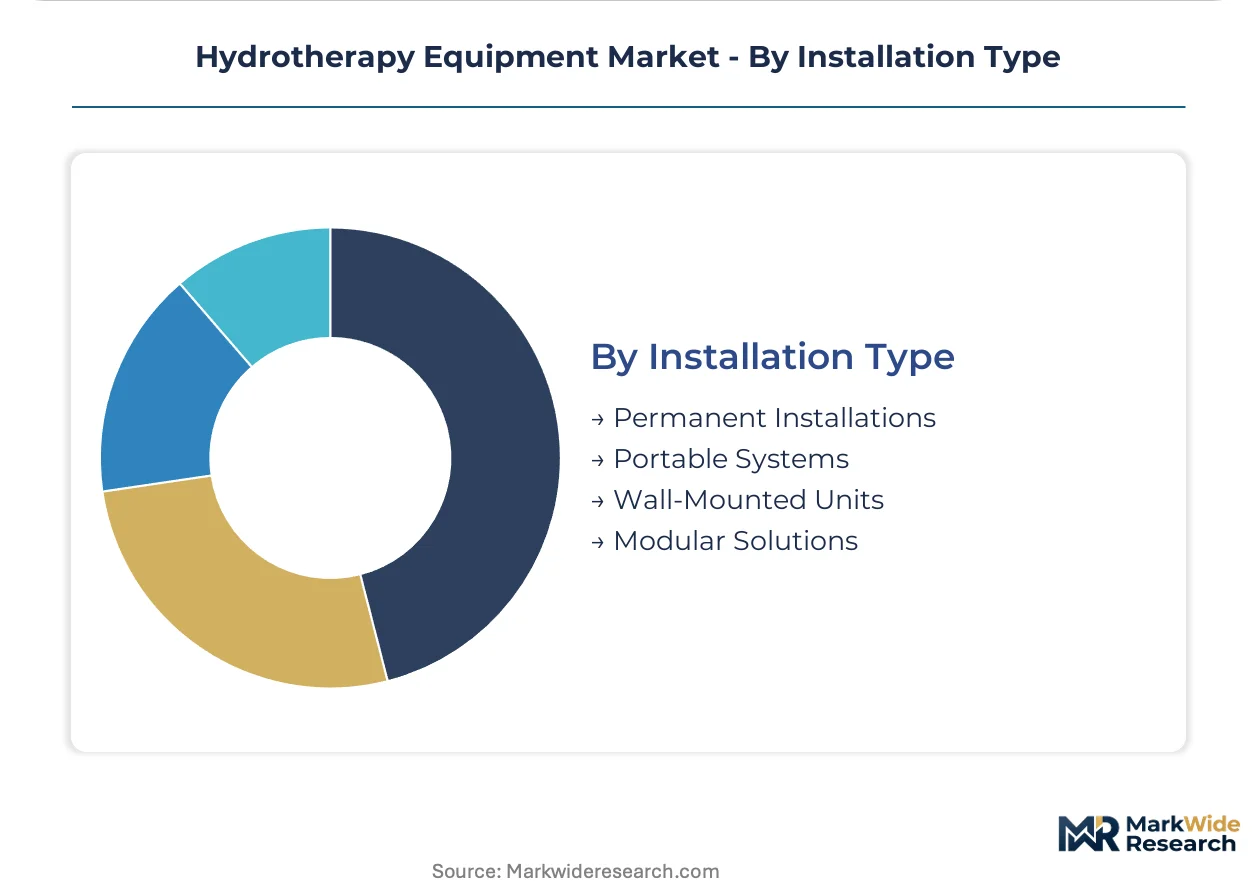
- Permanent Installations:Built-in pool and bath systems require dedicated plumbing infrastructure and construction timelines. Hospital retrofit requirements for water pressure and drainage specifications extend project durations and inflate capital costs.
- Modular Solutions:Self-contained electromechanical units enable rapid deployment across satellite clinic networks. These systems penetrate decentralized care delivery models in North America and Western Europe where reimbursement code expansions accelerate site expansion.
- Portable Systems:Transportable units with temporary plumbing connections serve field rehabilitation and mobile therapy services.
- Wall-Mounted Units:Space-constrained installations in urban clinical environments favor compact hydro-massage configurations.
Permanent installations retain infrastructure dominance; modular solutions are penetrating fastest where procurement flexibility outweighs capital intensity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export clinical-grade hydrotherapy systems to rehabilitation networks across Japan and the United States, establishing the primary trade corridor in this medical device category.
United States
Medicare reimbursement codes for aquatic therapy compress hospital procurement cycles while accelerating satellite clinic deployments. FDA 510(k) clearance pathways govern Class II device market entry for electromechanical systems. Stroke recovery centers in Boston and Chicago adopt force plate-integrated treadmills to quantify gait symmetry during neurological rehabilitation.
Germany
Statutory rehabilitation coverage creates dense procurement clusters for underwater treadmill systems in post-surgical orthopedic care. EU Medical Device Regulation conformity assessments impose elevated clinical evidence requirements on therapeutic equipment exports. Medical spa infrastructure in Bavaria and Baden-Württemberg drives multi-modality installation demand for thermal hydrotherapy configurations.
Japan
Aging-in-place demographics expand residential jetted bath procurement with clinical-grade temperature controls. METI standards and PMDA oversight shape quality management requirements for therapeutic equipment imports. Rehabilitation facilities in Tokyo and Osaka integrate aquatic locomotion protocols into standardized stroke recovery pathways.
United Kingdom
NHS procurement frameworks emphasize unbundled equipment purchases over long-term service contracts under capital expenditure constraints. MHRA regulations align with EU MDR transitional provisions for hydrotherapy device conformity. Private rehabilitation networks in London and Manchester deploy modular systems to enable rapid satellite clinic expansion.
Australia
TGA registration requirements create compliance barriers for non-domestic suppliers targeting therapeutic hydrotherapy claims. Private health insurance reimbursement for aquatic physiotherapy drives clinical installation demand. Sports medicine facilities in Sydney and Melbourne embed cold plunge protocols into amateur athletic recovery workflows.
Hydrotherapy Equipment Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, creating a bifurcated market structure where ISO 13485 compliance separates regulated medical positioning from wellness-only segments. The vendor base clusters around three archetypes: residential wellness brands with established consumer equity, clinical specialists targeting rehabilitation protocols, and diversified plumbing fixture manufacturers extending into therapeutic configurations. Dominant competitive moves include portfolio diversification across residential and clinical segments and geographic expansion through distributor partnerships in statutory coverage markets.
Within the clinical specialist tier, HYDROWORX and SwimEx Inc exemplify electromechanical precision positioning for neurological rehabilitation applications. Jacuzzi Inc anchors residential wellness demand through brand equity in jetted bath systems, while Kohler Co occupies a position across premium fixture categories with integrated hydro-massage configurations. Sidmar Manufacturing, Inc. and EWAC represent European fabricators targeting statutory rehabilitation coverage markets in Germany and adjacent economies.
| Leading Market Players |
|---|
| Prime Pacific Health Innovations Corporation |
| Jacuzzi Inc. |
| HYDROWORX |
| Sidmar Manufacturing, Inc. |
| Kohler Co |
| EWAC |
| SwimEx Inc |
| Narang Medical Limited |
| Hydro Physio |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German stainless steel fabrication facilities shapes margin structures for whirlpool bath manufacturers, concentrating supply power among corrosion-resistant alloy processors while establishing price floors for clinical-grade equipment exports to Japan and the United States.
Pricing Analysis
Next-generation electromechanical precision systems command 40-60% premiums over passive hydro-massage configurations, while prior-generation fixed-depth pool installations face accelerated depreciation. Three-tier pricing structure across premium clinical-grade, standard rehabilitation, and economy wellness tiers separates ISO 13485-certified manufacturers from wellness-only competitors. Pricing pressure stems from hospital procurement departments unbundling long-term service contracts, compressing upfront capital margins. Rehabilitation centers exhibit highest price sensitivity due to reimbursement code dependency, while medical spa facilities absorb premium positioning with lower elasticity.
Supply Chain Analysis
Extended lead times for nickel-chromium alloy deliveries from German and Japanese mills constrain production scheduling for corrosion-resistant whirlpool bath fabricators. Component sourcing draws from Taiwan for electromechanical drive systems, Germany for precision temperature controls, and China for standardized plumbing fixtures. Single-source vulnerability concentrates in marine-grade stainless steel suppliers serving clinical equipment specifications. Distribution runs through specialized medical device distributors in statutory coverage markets and direct-to-facility channels for wellness segment deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrotherapy equipment demand follows post-acute care investment cycles, with Medicare reimbursement compression and statutory rehabilitation coverage expansions creating divergent regional recovery trajectories across the analysis window.
For Market Incumbents: Shield installed base revenue through captive aftermarket service contracts targeting hospital systems reversing unbundled procurement patterns. Deepen vertical integration into stainless steel alloy processing to offset nickel price volatility compressing whirlpool bath margins. Prioritize ISO 13485 certification maintenance against EU MDR clinical evidence escalation threatening non-compliant competitors. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for Class II electromechanical devices enable rapid market entry against legacy pool system incumbents. Target modular solution deployments in North American satellite clinic networks where reimbursement code expansions accelerate site expansion velocity. Pursue telehealth integration partnerships with value-based reimbursement pilot programs as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical-grade electromechanical specialists over passive wellness equipment commoditization. Long-term viability concentrates in underwater treadmill platforms with force plate integration serving neurological rehabilitation protocols. Watch Medicare aquatic therapy code expansion velocity as inflection indicator for hospital procurement cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management compliance unlocks premium pricing in FDA-regulated medical markets versus wellness-only positioning. |
| Telehealth Sensor Integration | Remote monitoring capabilities align hydrotherapy equipment with value-based reimbursement pilots at major US payers. |
| Modular System Development | Self-contained electromechanical units penetrate decentralized care delivery models in Western Europe and North America. |
| EU MDR Conformity Pathway | Post-market surveillance documentation enables continued CE marking access for therapeutic claim equipment exports. |
| Stainless Steel Backward Integration | In-house alloy processing mitigates nickel price volatility threatening whirlpool bath manufacturer margins. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee members, rehabilitation center clinical directors, biomedical engineering specialists, and GPO contracts managers, then refined against secondary validation from FDA 510(k) clearance databases, ISO 13485 certification registries, CMS Medicare reimbursement code filings, and hospital procurement transaction records. Bottom-up equipment shipment analysis triangulated with top-down statutory coverage spending estimates across German, Japanese, and United States markets.
Variance decomposition across product type, end-user facility tier, installation configuration, and regional regulatory cluster shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level demand elasticity modeling and reimbursement velocity assumptions. Forecast inputs incorporated aquatic therapy protocol adoption curves in stroke recovery centers and cold plunge penetration rates in corporate wellness programs.
Underlying assumptions cover Medicare reimbursement stability, EU MDR transitional provision continuity, and nickel alloy price band containment, with deviation risk concentrated in pharmaceutical pain management substitution dynamics and hospital capital expenditure constraint persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Biofeedback Equipment Market