
 Biofeedback Equipment Market | 2026-2036
Biofeedback Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Biofeedback Equipment Market Analysis
Specialized neurofeedback technician training shortages across clinical settings is unwinding installation timelines for advanced biofeedback suites. HeartMath LLC leverages decades of heart rate variability algorithm development to sustain brand authority in stress management applications. Neurocare Group AG anchors its European presence through direct clinic service networks, while Thought Technology Ltd. competes on modular EMG and EEG system configurability for rehabilitation centers.
Biofeedback equipment comprises sensor-based instruments that measure physiological signals including electromyography, skin temperature, electroencephalography, and heart rate variability with sampling frequencies typically ranging from 256 Hz to 2048 Hz for neurofeedback applications, converting analog biological data into real-time visual or auditory feedback for therapeutic intervention or performance training. Neurofeedback systems command premium positioning due to complex signal processing requirements and practitioner certification barriers, whereas wearable devices represent the fastest-expanding access point as consumer-grade photoplethysmography and accelerometer integration drives home care and fitness center adoption. Software solutions increasingly determine switching costs as cloud-based session analytics and remote patient monitoring integrations embed clinicians into subscription ecosystems.
FDA 510(k) premarket notification requirements govern neurofeedback and EMG device commercialization in the United States, while CE marking under the EU MDR and In Vitro Diagnostic Regulation framework dictates market access across European member states with intensified clinical evidence demands for active therapeutic devices. Japan's PMDA enforces QMS Ministerial Ordinance 169 compliance for imported biofeedback systems, adding localization costs that filter smaller manufacturers from East Asian distribution. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications and MDR transition deadlines to calibrate regulatory investment against addressable market expansion.
Market Dynamics
The biofeedback equipment sector faces a structural inflection as software-as-medical-device classifications compress hardware margins and elevate recurring revenue models. Cloud-based session analytics now determine customer switching costs more than sensor specifications, forcing manufacturers to reconfigure R&D allocation toward platform development.
Growth Catalysts
- FDA 510(k) clearance streamlining:The premarket notification pathway for neurofeedback and EMG devices accelerates commercialization timelines for wearable manufacturers targeting clinical validation. Rehabilitation centers in the United States leverage this regulatory efficiency to expand non-pharmacological pain therapy suites.
- Heart rate variability algorithm maturation:Decades of psychophysiological research validation enables consumer-grade photoplethysmography integration into home care and fitness center applications. Stress management protocols now deploy portable devices with clinical credibility.
- Germany:Reimbursement frameworks for non-pharmacological interventions mature fastest here, driving clinic and hospital adoption of neurofeedback systems for rehabilitation protocols. The statutory health insurance landscape increasingly covers biofeedback for chronic pain and anxiety disorders.
Market Restraints
- Specialized technician training scarcity:Neurofeedback certification barriers create installation bottlenecks for advanced biofeedback suites across clinical settings. Practitioner availability constrains deployment velocity regardless of equipment procurement budgets.
- EU MDR clinical evidence intensification:CE marking requirements for active therapeutic devices under the Medical Device Regulation extend product development timelines and elevate documentation costs. Smaller manufacturers face resource strain meeting post-market surveillance obligations.
- Japan PMDA localization costs:QMS Ministerial Ordinance 169 compliance for imported systems adds distribution overhead that filters smaller manufacturers from East Asian market entry. The technical conformity assessment burden disproportionately impacts mid-tier suppliers.
Strategic Opportunities
- Remote patient monitoring integration:Cloud-based session analytics embed clinicians into subscription ecosystems, creating recurring revenue streams beyond hardware sales. Telehealth infrastructure expansion accelerates platform adoption for home-based neurofeedback.
- Consumer wellness channel penetration:Fitness centers and corporate wellness programs represent underpenetrated demand for heart rate variability training devices. Photoplethysmography-enabled wearables bypass clinical certification barriers through general wellness positioning.
- EU Green Deal sustainable manufacturing incentives:Medical device producers accessing circular economy funding can differentiate through reduced environmental footprint in sensor production and packaging. Procurement criteria in German and Dutch healthcare systems increasingly weight sustainability metrics.
Industry Challenges
- Neurofeedback practitioner certification pipeline:The specialized training required for qEEG interpretation and protocol customization creates talent scarcity that extends installation timelines. Clinical education institutions struggle to scale output matching equipment deployment rates.
- Software-hardware integration complexity:Legacy EMG and EEG systems require substantial reconfiguration to interface with cloud analytics platforms. Rehabilitation centers face operational disruption during migration to subscription-based session management tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofeedback Equipment Market |
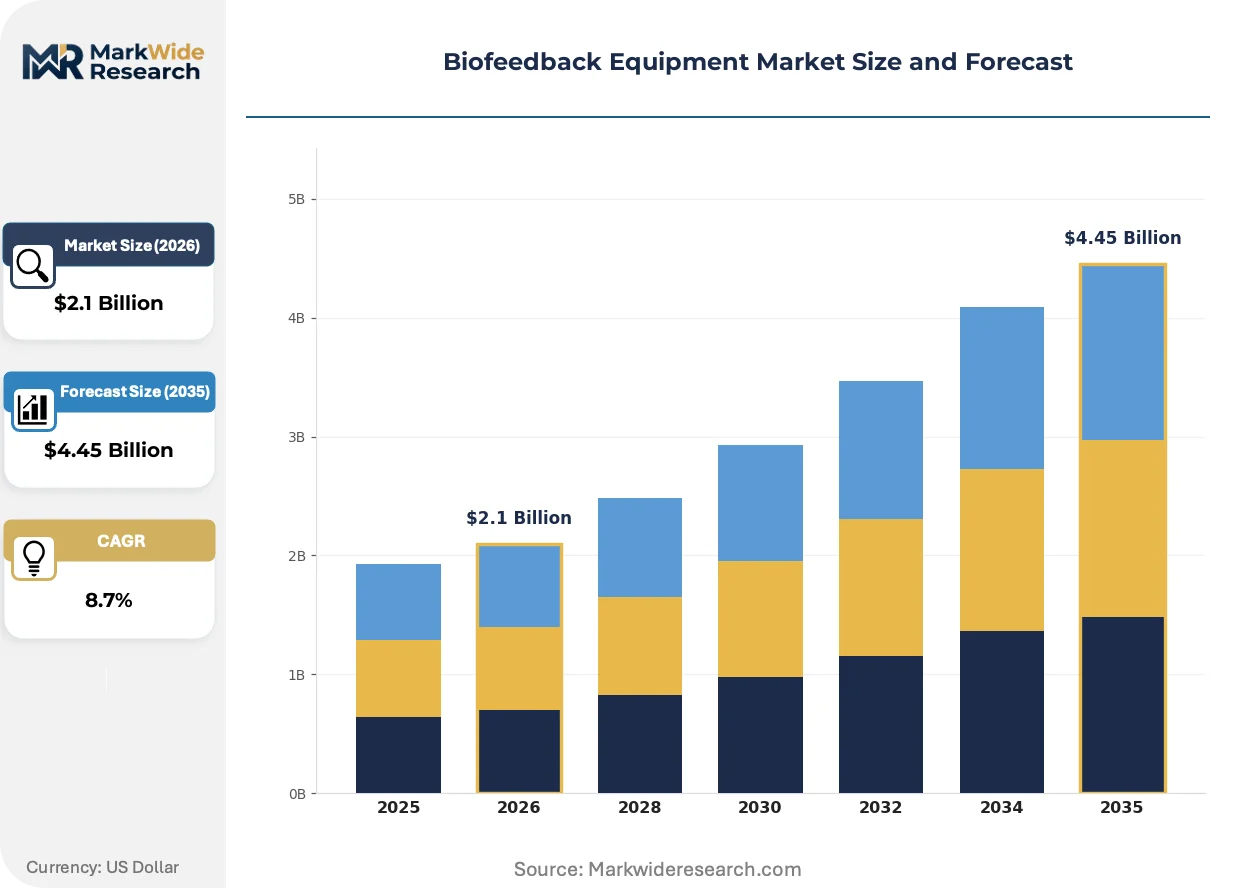
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromyography, Neurofeedback, Thermal Biofeedback, Heart Rate Variability End User: Clinics, Hospitals, Home Care, Fitness Centers Technology: Wireless Systems, Portable Devices, Software Solutions, Wearable Devices Application: Stress Management, Pain Relief, Rehabilitation, Performance Enhancement |
| Companies Covered | HeartMath LLC, Neurocare Group AG, Thought Technology Ltd., ELMIKO Medical Equipment, QX World Ltd., BrainMaster Technologies Inc., NeuroSky Inc., Zynex Medical Inc., Mind Media B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofeedback Equipment Market Emerging Trajectories
Real-time physiological signal processing is migrating from dedicated hardware to smartphone-integrated architectures, compressing device form factors and democratizing access points. This architectural shift redefines competitive advantage toward algorithm IP and platform stickiness rather than sensor manufacturing scale.
Photoplethysmography is decomposing the traditional electrocardiography-dominated heart rate variability market by enabling continuous monitoring through consumer wearables. Fitness centers and corporate wellness programs adopt these lower-cost alternatives for stress management training. The technology is decomposing premium positioning for clinical-grade systems as algorithm accuracy converges across price tiers.
CE marking under the EU MDR intensifies clinical evidence requirements for active therapeutic biofeedback devices, extending development timelines by twelve to eighteen months. Manufacturers must generate post-market surveillance data that predecessor directives did not mandate. Neurofeedback systems face the steepest compliance burden due to their therapeutic claims for attention and mood disorders.
Subscription-based session analytics are displacing perpetual software licenses in clinical procurement decisions. Rehabilitation centers and private practices prioritize platforms offering remote patient monitoring integration over standalone device purchases. This shift concentrates most visibly in United States reimbursement environments where value-based care metrics reward treatment adherence tracking.
Biofeedback Equipment Market Segmentation
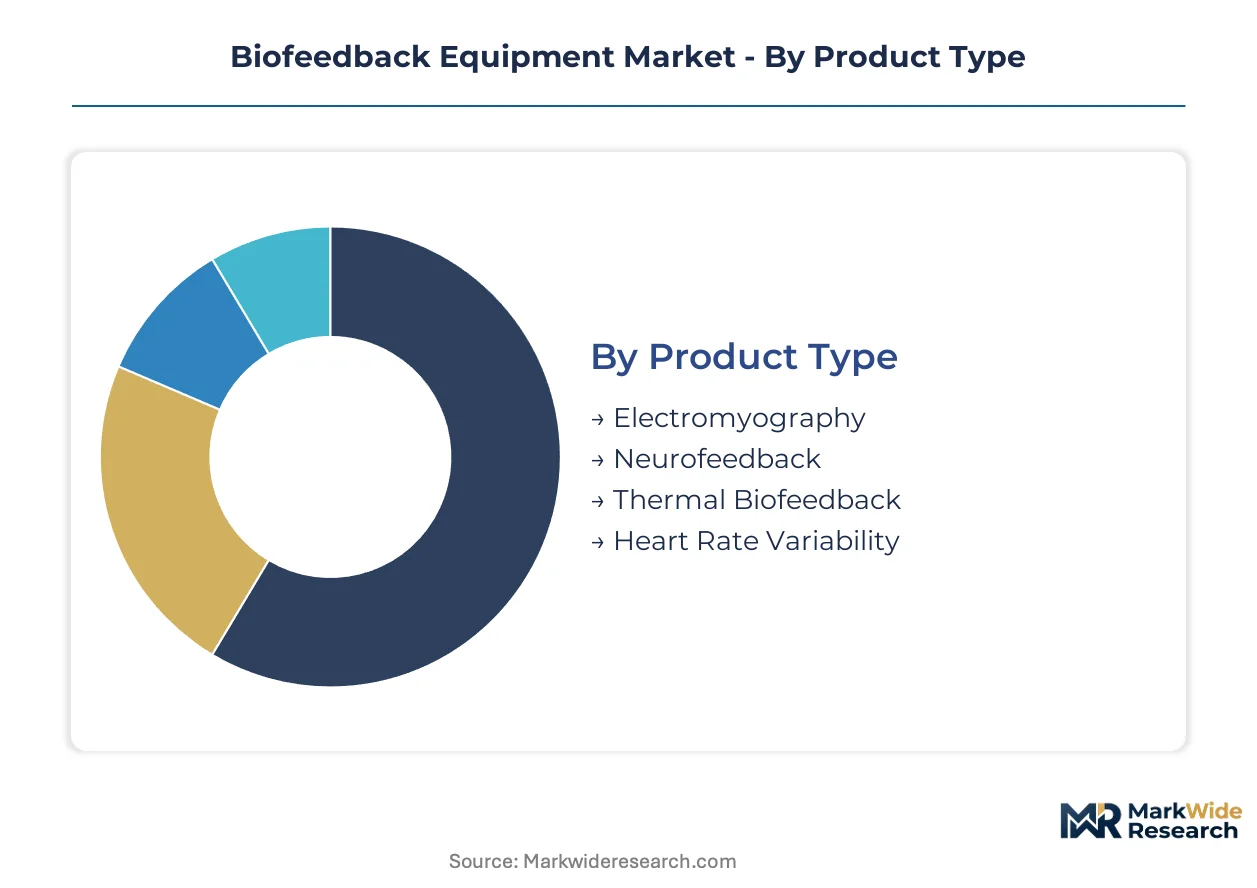
Biofeedback equipment segmentation reveals divergent margin structures across hardware and software configurations. Product architecture and end-user setting determine regulatory pathway complexity and pricing power.
Product Type:
Photoplethysmography-enabled wearables exert substitution pressure on traditional electrode-based systems across all clinical and consumer tiers.
- Electromyography:Surface electrode arrays measure muscle activation with sampling rates of 1000-2000 Hz for rehabilitation protocols. Physical therapy departments in German hospitals deploy EMG suites for post-surgical motor recovery, constrained by technician calibration requirements.
- Neurofeedback:Quantitative electroencephalography systems process cortical signals at 256-2048 Hz with real-time feedback algorithms. United States psychiatric clinics invest in qEEG suites for attention deficit protocols, facing certification bottlenecks that extend installation timelines.
- Thermal Biofeedback:Skin conductance sensors track autonomic arousal through temperature differentials.
- Heart Rate Variability:R-R interval analysis from ECG or PPG sensors enables stress assessment with minimal operator training.
Heart rate variability anchors the volume base while neurofeedback gains share at the steepest rate.
End User:
Reimbursement eligibility separates institutional purchasers from out-of-pocket consumer channels.
- Clinics:Private neurological and psychological practices purchase modular systems with session management software. German statutory health insurance coverage for chronic pain biofeedback drives equipment refresh cycles in independent practices.
- Hospitals:Integrated rehabilitation departments require EMG and neurofeedback suites with enterprise IT compatibility. Japanese university hospitals face PMDA QMS Ordinance 169 compliance costs that filter mid-tier suppliers from procurement shortlists.
- Home Care:Direct-to-consumer wearables bypass clinical certification through general wellness positioning.
- Fitness Centers:Corporate wellness programs adopt HRV training devices for member retention programs.
Hospitals dominate capital expenditure while home care expands most quickly.
Technology:
Cloud connectivity requirements are elevating software development costs above sensor manufacturing scale.
- Wireless Systems:Bluetooth and Wi-Fi enabled devices transmit physiological data to centralized displays for group therapy settings. United States rehabilitation centers prioritize wireless EMG configurations to reduce cable management overhead in movement-based protocols.
- Portable Devices:Battery-powered units with integrated displays serve mobile clinicians and home-based patients. Japanese home care agencies source portable neurofeedback systems for remote psychiatric monitoring, navigating METI technical conformity assessments.
- Software Solutions:Cloud-based session analytics platforms with subscription licensing models.
- Wearable Devices:Consumer-grade photoplethysmography and accelerometer integration for continuous monitoring.
Portable devices anchor the installed base while software solutions capture expanding recurring revenue share.
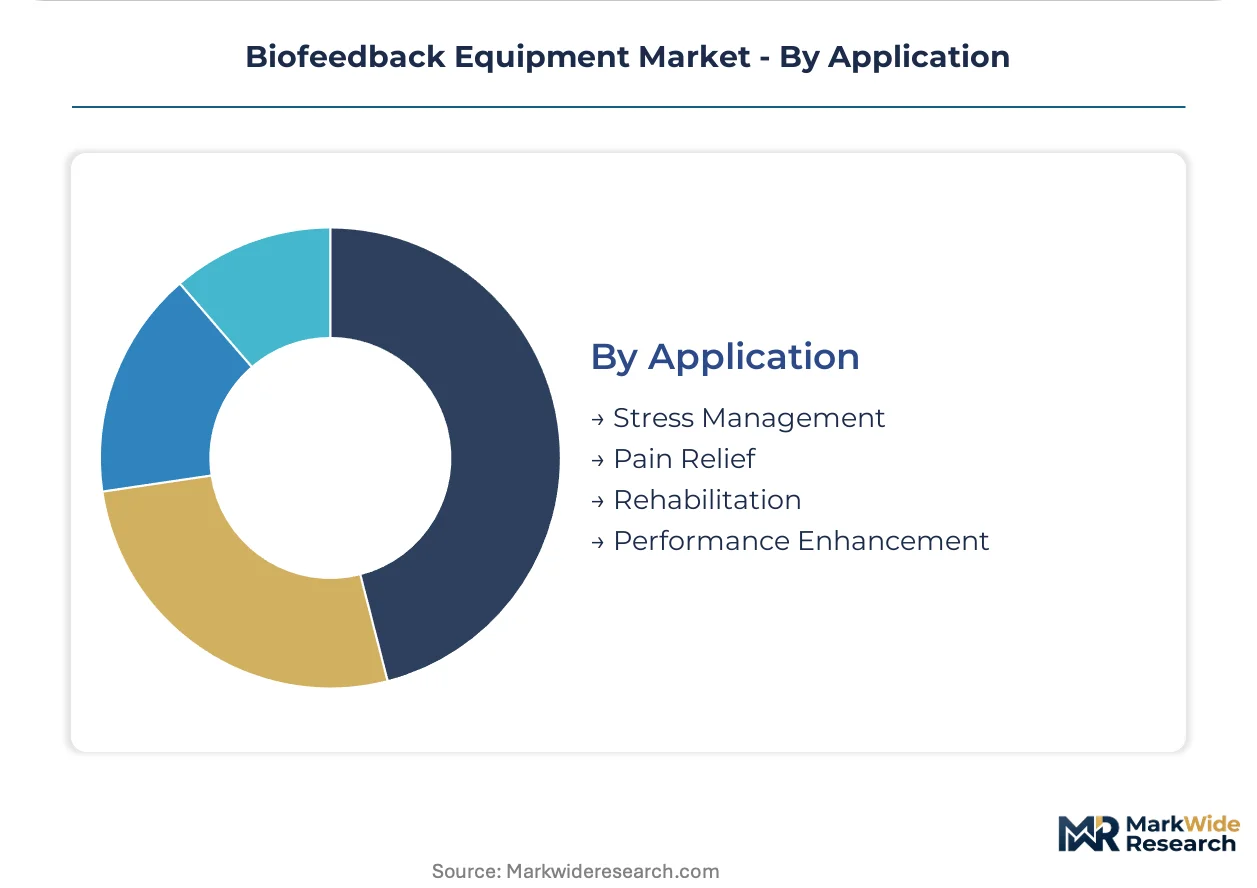
Application:
Clinical evidence requirements vary sharply between therapeutic claims and wellness positioning.
- Stress Management:HRV training protocols target autonomic regulation through paced breathing feedback. Corporate wellness programs in Germany deploy wearable devices for employee resilience programs, leveraging decades of psychophysiological validation.
- Pain Relief:EMG biofeedback for tension reduction and thermal feedback for migraine management. United States pain clinics integrate biofeedback into non-pharmacological therapy suites under evolving CPT reimbursement codes.
- Rehabilitation:Motor learning protocols using real-time EMG or movement feedback.
- Performance Enhancement:Neurofeedback for attention training in athletic and executive coaching contexts.
Stress management anchors the consumer volume base while pain relief applications climb fastest in clinical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor commercialization velocity in the United States, while CE marking under the EU MDR and Japan's PMDA QMS Ordinance 169 shape access timelines across their respective jurisdictions. Equipment procurement concentrates where reimbursement frameworks for non-pharmacological interventions mature fastest.
United States
Rehabilitation centers and pain clinics drive neurofeedback and EMG system deployment under evolving CPT reimbursement codes for non-pharmacological therapies. FDA 510(k) premarket notification streamlines commercialization for wearable manufacturers targeting clinical validation. The Greater Boston and San Francisco Bay Area clusters host concentrated psychiatric and neurological practice networks investing in qEEG suites.
Germany
Statutory health insurance coverage for chronic pain and anxiety biofeedback propels equipment refresh cycles in independent neurological practices. CE marking under the EU MDR intensifies clinical evidence requirements for active therapeutic devices, extending development timelines by twelve to eighteen months. The Munich and Berlin metropolitan areas concentrate rehabilitation hospital networks adopting modular EMG systems for post-surgical motor recovery protocols.
Japan
University hospitals and home care agencies source portable neurofeedback systems for remote psychiatric monitoring applications. PMDA QMS Ministerial Ordinance 169 compliance adds localization costs that filter mid-tier suppliers from procurement shortlists. The Tokyo-Osaka corridor anchors demand for METI technical conformity-assessed devices in integrated rehabilitation departments.
United Kingdom
NHS Integrated Care Systems pilot biofeedback for chronic pain management within community rehabilitation pathways, creating procurement opportunities for cloud-integrated platforms. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence standards elevates documentation burdens for device manufacturers. The London-Southeast and Manchester clusters concentrate private neurological practices investing in subscription-based session analytics.
Australia
TGA approval pathways for software-as-medical-device classifications compress hardware margins while elevating recurring revenue models for cloud-based platforms. Private health insurers increasingly cover biofeedback for stress management and pain relief indications. The Sydney and Melbourne metropolitan areas host concentrated corporate wellness program adopters of heart rate variability training devices.
Biofeedback Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation hinging on algorithm IP and platform stickiness rather than sensor manufacturing scale. The vendor base stratifies between neurofeedback suite providers with certification-dependent installation services and consumer-grade wearable manufacturers bypassing clinical barriers through wellness positioning. Three archetypes dominate: modular system configurators for rehabilitation centers, heart rate variability algorithm specialists, and cloud platform operators embedding clinicians into subscription ecosystems. Competitive moves concentrate on strategic partnerships with telehealth infrastructure providers and portfolio diversification into remote patient monitoring integrations.
Within the algorithm-specialist tier, HeartMath LLC and Neurocare Group AG exemplify divergent geographic anchoring strategies, with the former leveraging decades of psychophysiological validation and the latter deploying direct clinic service networks across European markets. Thought Technology Ltd. occupies a position among modular system configurators, representing the Canadian fabrication base serving rehabilitation center demand for EMG and EEG configurability. These three anchors illustrate how competitive positioning fragments across certification-intensive clinical channels and wellness-positioned consumer access points.
| Leading Market Players |
|---|
| HeartMath LLC |
| Neurocare Group AG |
| Thought Technology Ltd. |
| ELMIKO Medical Equipment |
| QX World Ltd. |
| BrainMaster Technologies Inc. |
| NeuroSky Inc. |
| Zynex Medical Inc. |
| Mind Media B.V. |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified manufacturers while elevating premium positioning for cleared neurofeedback systems. The interplay between regulatory compliance costs and subscription-based software models is restructuring how buyers evaluate total cost of ownership across clinical and consumer tiers.
Pricing Analysis
United States-Germany price spreads for comparable neurofeedback suites reach 15-25% after accounting for CE marking documentation burdens and statutory health insurance reimbursement differentials. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from CE-marked European variants and uncertified wellness-positioned wearables. Pricing pressure stems from photoplethysmography-enabled consumer devices converging on clinical-grade heart rate variability algorithm accuracy. Hospital purchasing committees demonstrate lowest price sensitivity due to enterprise IT integration requirements, while independent neurological practices negotiate aggressively on modular system configurability.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes have elevated inbound logistics costs for electrode arrays and signal processing chipsets sourced from Taiwanese and South Korean fabs. Sensor manufacturing concentrates in China, Taiwan, and Germany, with cloud analytics platform development anchored in the United States and Israel. Raw material dependencies span medical-grade silver-silver chloride for surface electrodes, gallium arsenide for photoplethysmography sensors, and specialized analog-to-digital converters for EEG sampling. Single-source vulnerability in 256-2048 Hz sampling chipset supply creates procurement risk for neurofeedback system assemblers. Distribution runs through direct clinic service networks for certified systems and consumer electronics retail channels for wellness-positioned wearables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in biofeedback equipment rest on practitioner certification network effects—clinicians trained on specific platforms face substantial retraining costs when switching vendors, embedding incumbents into institutional procurement cycles.
For Market Incumbents: Shield installed base relationships by embedding cloud-based session analytics deeper into hospital IT ecosystems, creating data migration friction that slows competitive displacement. Accelerate certification pipeline partnerships with clinical education institutions to address technician training scarcity before emerging modular competitors capture rehabilitation center refresh cycles. Prioritize backward integration into photoplethysmography sensor fabrication to defend margin position against consumer-grade wearable convergence.
For New Entrants and Emerging Players: Remote patient monitoring integration for home-based psychiatric applications represents the most penetrable white-space target, as incumbent platforms remain optimized for in-clinic deployment. Corporate wellness programs in German and Australian metropolitan areas offer lower certification barriers for heart rate variability algorithm licensing plays. Pursue white-label partnerships with telehealth infrastructure providers to bypass direct sales force buildout requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-medical-device sub-segments as cloud platform development displaces sensor manufacturing scale as the primary investment requirement. Target acquisition archetypes include algorithm-specialist firms with decades of psychophysiological validation IP and regional clinic service networks with embedded customer relationships. Watch FDA guidance on software-as-medical-device classifications as the critical inflection signal—material expansion of regulated scope would re-rate compliant platform operators.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements extend development timelines, filtering resource-constrained competitors from European rehabilitation center procurement. |
| Hospital System Partnership | Enterprise IT compatibility commitments embed vendors into multi-year equipment refresh cycles with switching cost protection. |
| Software Companion Development | Cloud-based session analytics platforms capture recurring revenue streams and elevate customer lifetime value beyond hardware margins. |
| Reimbursement Strategy | CPT code expansion for non-pharmacological pain therapies in United States reimbursement environments directly expands addressable clinical demand. |
| Acquisition of Specialist Firm | Algorithm IP consolidation in heart rate variability and qEEG signal processing accelerates platform differentiation and compresses R&D duplication. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with biofeedback equipment clinicians, hospital biomedical engineers, GPO contracts managers, and neurofeedback certification program directors; and secondary validation against FDA 510(k) premarket notification databases, CE marking certificates under EU MDR, German statutory health insurance reimbursement schedules, and Japanese PMDA QMS Ordinance 169 compliance records. Bottom-up triangulation across equipment shipment data and top-down reconciliation against national healthcare expenditure patterns anchored market sizing.
Across the analysis window, the forecasting framework modeled demand trajectories by product architecture, end-user setting, technology connectivity type, and application therapeutic claim intensity. CAGRs were derived from segmented growth rate reconciliation against macro healthcare digitization indicators and reimbursement policy evolution. Industry-specific inputs included neurofeedback practitioner certification pipeline throughput estimates and photoplethysmography algorithm accuracy convergence curves.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR transition timelines, and Japan PMDA QMS Ordinance 169 enforcement; material policy shifts in software-as-medical-device classification scope or statutory health insurance coverage expansion would require re-modeling. Practitioners should keep alternative scenarios live as cloud platform reimbursement eligibility and consumer wellness device clinical validation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market