
 Patient Simulator Market | 2026-2036
Patient Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Simulator Market Analysis
North America is reconfiguring its patient simulator manufacturing footprint as domestic assembly capacity expands across the United States and Canada. CAE Inc. leverages its aerospace simulation heritage to anchor high-fidelity healthcare training systems in Montreal and Tampa. Laerdal Medical sustains its Stavanger-rooted R&D intensity while competing across resuscitation and maternal-neonatal simulation lines. Kyoto Kagaku Co., Ltd. differentiates through anatomical precision in its Asian manufacturing cluster.
A patient simulator is a physical or virtual manikin system engineered to replicate human physiological responses—cardiac rhythms, respiratory patterns, pupillary reflexes—through embedded pneumatics, hydraulics, or software algorithms for clinical skills assessment. High-fidelity simulators command the largest revenue pool due to their programmable pathologies and integrated debriefing software, while augmented reality modules represent the fastest-expanding technology segment as hardware-integrated platforms mature. Medical education applications dominate volume, though surgical simulation captures premium pricing through procedure-specific task trainers.
FDA clearance pathways for software-as-a-medical-device shape product development timelines for U.S.-bound virtual simulators, while CE marking under the EU MDR governs hardware-integrated system access across European healthcare organizations. ISO 9001 and ISO 13485 certifications function as baseline procurement filters for hospital buyers evaluating vendor quality systems. Stakeholders must weigh regulatory divergence against platform standardization when allocating R&D across geographic markets.
Market Dynamics
Medical education institutions face escalating pressure from the Liaison Committee on Medical Education to integrate simulation-based training into core curricula, forcing capital reallocation toward high-fidelity manikin systems and virtual reality platforms.
Growth Catalysts
- LCME Accreditation Mandates:United States medical schools must demonstrate standardized patient encounter hours through simulation, driving replacement cycles for aging task trainers.
- Haptic Feedback Integration:Tactile realism in software-based platforms now satisfies procedural competency requirements previously reserved for physical manikins.
- Maternal-Neonatal Specialization:Obstetrics departments across Canada and the United Kingdom are expanding simulation laboratory footprints to reduce sentinel event rates in delivery units.
Market Restraints
- Silicone Polymer Volatility:Skin-grade elastomer costs fluctuate with petrochemical feedstock prices, compressing margins for full-body manikin manufacturers.
- Single-Source Pneumatics:Precision valve assemblies for programmable vital signs concentrate among German and Japanese component suppliers.
- FDA 510(k) Pathway Friction:Software-as-a-medical-device submissions for AI-driven physiological engines face extended review timelines compared to hardware predicates.
Strategic Opportunities
- India Medical College Expansion:National Medical Commission accreditation reforms are mandating simulation infrastructure for new MBBS programs across 22 states.
- Augmented Reality Convergence:Mixed reality headsets combined with physical manikins enable hybrid training scenarios at one-third the cost of dedicated virtual reality suites.
- US Veterans Health Administration:The VA's simulation network standardization initiative creates centralized procurement channels for trauma and combat casualty care modules.
Industry Challenges
- Bioinformatics Specialist Scarcity:Vendors struggle to hire engineers capable of modeling complex disease progressions for sepsis and multi-organ failure scenarios.
- ISO 13485 Certification Burden:Small manufacturers face 18-month quality system implementation timelines to access hospital procurement lists.
- Legacy EMR Integration:Simulator data output formats require custom middleware to populate electronic health records for debriefing analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Simulator Market |
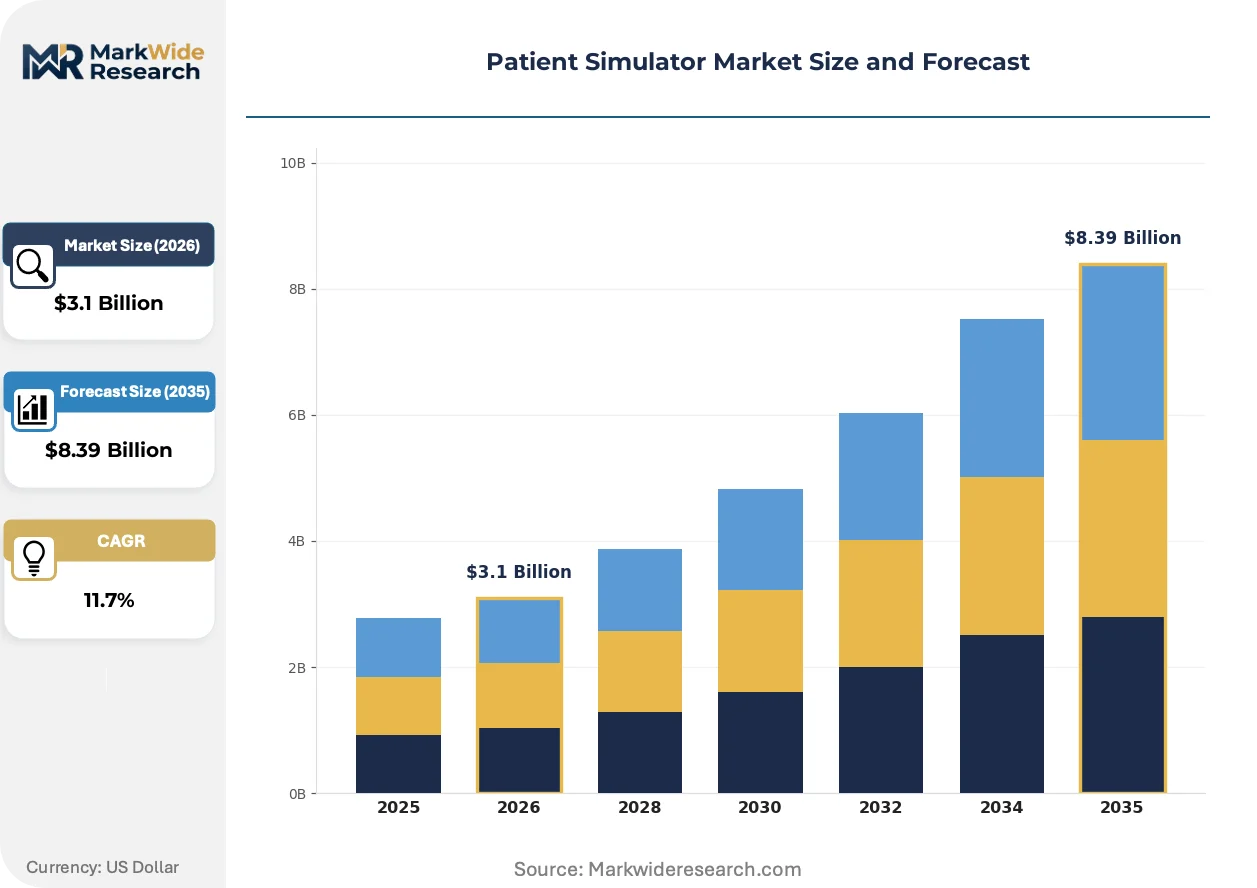
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Fidelity Simulators, Low-Fidelity Simulators, Task Trainers, Virtual Simulators Application: Medical Education, Clinical Training, Surgical Simulation, Emergency Response Training End User: Hospitals, Medical Schools, Training Centers, Healthcare Organizations Technology: Software-Based, Hardware-Integrated, Augmented Reality, Mixed Reality |
| Companies Covered | Surgical Science Sweden AB, Kyoto Kagaku Co., Ltd., Laerdal Medical, Limbs & Things LTD, Mentice AB, Gaumard Scientific, Simulab Corporation, MEDICAL-X, CAE Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Simulator Market Emerging Trajectories
Artificial intelligence is compressing development cycles for physiological modeling while regulatory frameworks struggle to classify adaptive learning algorithms as either educational tools or diagnostic devices.
Cloud-native simulation platforms are rendering obsolete the installed-base advantage of legacy hardware vendors. Hospital networks in the United States and Australia are piloting subscription-based access to scenario libraries that update weekly rather than through three-year capital replacement cycles. This shift collapses the traditional distinction between content and platform ownership.
The EU Medical Device Regulation's classification of software with diagnostic functions is forcing European manufacturers to restructure quality management systems. CE marking timelines for AI-integrated simulators have extended by eight to fourteen months as notified bodies develop competency in algorithm validation. German and French vendors are responding by segregating European and non-European product architectures.
Academic medical centers now unbundle after-sales service contracts from hardware purchases, treating technical support and scenario updates as competitive bid items. This procurement pattern first emerged in the Veterans Health Administration network and has spread to state university hospital systems. The disintermediation compresses vendor margins while accelerating third-party content marketplace development.
Patient Simulator Market Segmentation
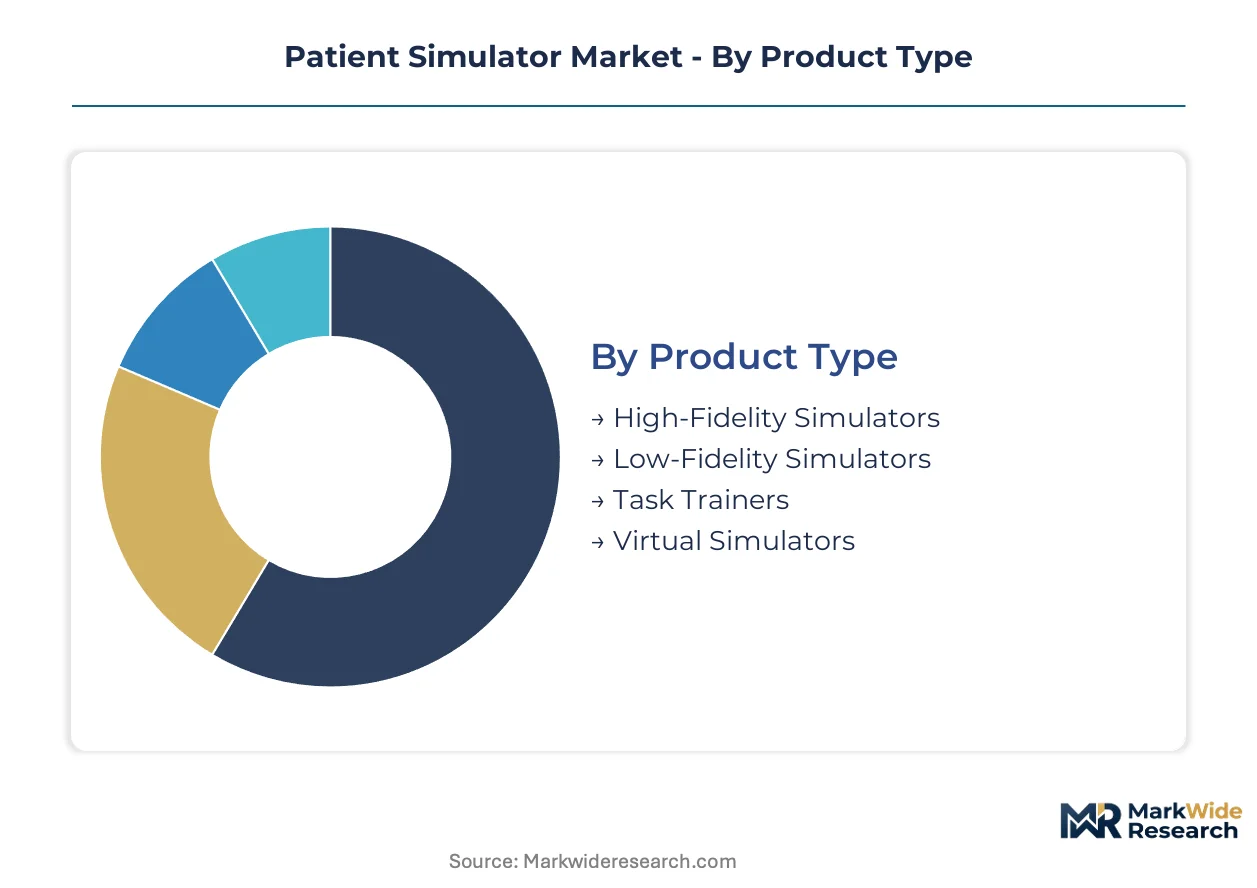
Patient simulator procurement patterns diverge sharply across institutional tiers, with academic medical centers prioritizing high-fidelity systems while community hospitals favor modular task trainers. Understanding these segment boundaries clarifies where vendors must unbundle service contracts from hardware sales.
Product Type:
After-sales service intensity varies dramatically across product tiers, with high-fidelity manikins demanding dedicated field engineering support while virtual platforms rely on cloud-based technical assistance.
- High-Fidelity Simulators:Full-body manikins embed programmable pneumatics and hydraulic systems to replicate cardiac arrest, respiratory failure, and neurological deterioration. United States medical schools allocate capital toward these systems to satisfy LCME accreditation mandates for standardized patient encounter documentation.
- Virtual Simulators:Software-native platforms deploy haptic peripherals and physiological engines accessible via subscription licensing. Australian hospital networks pilot these for remote trauma training where physical manikin logistics prove prohibitive.
- Task Trainers:Procedure-specific anatomical models target discrete skill acquisition—central line insertion, lumbar puncture, airway management—at lower price points.
- Low-Fidelity Simulators:Basic manikins support foundational assessment training without programmable vital signs.
High-Fidelity Simulators hold the largest share; momentum sits with Virtual Simulators.
Application:
Cost tier stratification separates capital-intensive surgical suites from scalable emergency response modules.
- Medical Education:Pre-licensure programs integrate simulation into core curricula, with United States institutions replacing aging task trainers under LCME pressure. Volume concentration here drives standardized procurement specifications.
- Surgical Simulation:Procedure-specific platforms command premium pricing through VR-integrated task trainers for laparoscopy, endoscopy, and open surgery. Canadian academic medical centers expand these investments to reduce operative learning curves.
- Clinical Training:Residency and fellowship programs utilize hybrid physical-virtual scenarios for competency-based progression.
- Emergency Response Training:Pre-hospital and disaster preparedness modules prioritize portability and rapid deployment.
Medical Education commands dominant volume; Surgical Simulation captures the steepest expansion trajectory.
End User:
Customer type determines purchasing authority complexity, with hospital procurement committees imposing ISO 13485 certification filters absent in smaller training centers.
- Medical Schools:United States institutions face the most stringent accreditation-linked capital allocation requirements. LCME standards mandate simulation infrastructure with documented utilization metrics.
- Hospitals:Veterans Health Administration networks centralize procurement through standardized trauma and combat casualty care specifications. This disintermediates traditional vendor service bundling.
- Training Centers:Independent simulation facilities serve multiple institutional clients through scenario library licensing.
- Healthcare Organizations:Integrated delivery networks negotiate enterprise-wide platform standardization.
Medical Schools anchor demand concentration; Healthcare Organizations are gaining share fastest through network consolidation.
Technology:
Supply concentration in precision valve assemblies and haptic actuator manufacturing shapes technology accessibility.
- Augmented Reality:Mixed reality headsets overlay digital pathologies onto physical manikins, enabling hybrid training at reduced hardware cost. United States and United Kingdom obstetrics departments pilot these for maternal-neonatal scenarios.
- Software-Based:Cloud-native platforms eliminate installed-base advantages of legacy vendors through weekly scenario updates rather than capital replacement cycles. FDA 510(k) pathway friction extends development timelines for AI-driven physiological engines.
- Hardware-Integrated:Traditional manikin systems with embedded pneumatics face CE marking delays under EU MDR classification of diagnostic software functions.
- Mixed Reality:Fully immersive environments combine physical props with digital patient avatars for team-based crisis resource management.
Software-Based platforms hold established share; Augmented Reality is expanding most quickly through cost-advantaged deployment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision valve assemblies for programmable vital signs concentrate among German and Japanese component suppliers, creating geographic dependencies in high-fidelity manikin manufacturing. Domestic assembly capacity is expanding across North America as medical schools accelerate capital reallocation toward simulation infrastructure.
United States
The Liaison Committee on Medical Education mandates standardized patient encounter hours through simulation, driving replacement cycles for aging task trainers. FDA 510(k) pathway friction extends review timelines for AI-driven physiological engines compared to hardware predicates. Tampa and Montreal anchor North American manufacturing clusters for aerospace-heritage healthcare training systems.
Germany
CE marking timelines under EU MDR have extended by eight to fourteen months for AI-integrated simulators as notified bodies develop algorithm validation competency. German vendors are restructuring quality management systems to segregate European and non-European product architectures. Precision pneumatics manufacturing concentrates in Baden-Württemberg and Bavaria, supplying valve assemblies for programmable vital signs systems.
Japan
PMDA consultation pathways shape development timelines for software-as-a-medical-device platforms targeting clinical skills assessment. Kyoto Kagaku Co., Ltd. leverages its Asian manufacturing cluster to differentiate through anatomical precision in maternal-neonatal and resuscitation simulation lines. The Kansai region maintains R&D intensity for hardware-integrated physiological modeling systems.
United Kingdom
Obstetrics departments across England and Scotland are expanding simulation laboratory footprints to reduce sentinel event rates in delivery units. MHRA guidance on software medical devices influences procurement specifications for National Health Service trusts. London and Southeast academic medical centers unbundle after-sales service contracts from hardware purchases, treating technical support as competitive bid items.
India
National Medical Commission accreditation reforms mandate simulation infrastructure for new MBBS programs across 22 states, creating demand concentration in Maharashtra, Karnataka, and Tamil Nadu. CDSCO regulatory frameworks for medical device software are evolving alongside institutional procurement capacity. Delhi-NCR and Hyderabad medical colleges are piloting hybrid physical-virtual training scenarios through augmented reality convergence.
Patient Simulator Market Vendor Landscape
Aerospace-heritage simulation specialists and anatomical precision manufacturers split the market between programmable physiological systems and procedure-specific task trainers. The vendor base clusters around three strategic archetypes: integrated platform providers with embedded pneumatics, software-native subscription platforms with haptic peripherals, and specialized anatomical model fabricators. Competitive positioning depends on FDA clearance velocity for AI-driven engines and CE marking efficiency under EU MDR classification rules. M&A activity targets scenario content libraries and cloud-native platform capabilities.
Within the integrated platform tier, CAE Inc. and Laerdal Medical occupy positions shaped by aerospace simulation heritage and Stavanger-rooted R&D intensity respectively. Kyoto Kagaku Co., Ltd. exemplifies the anatomical precision archetype through its Asian manufacturing cluster focus. These three entities represent contrasting geographic and technological positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| Surgical Science Sweden AB |
| Kyoto Kagaku Co., Ltd. |
| Laerdal Medical |
| Limbs & Things LTD |
| Mentice AB |
| Gaumard Scientific |
| Simulab Corporation |
| MEDICAL-X |
| CAE Inc. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Hamburg maritime corridor carries silicone polymer feedstocks and precision pneumatic components that feed North American and European assembly plants, with freight cost volatility amplifying margin compression for full-body manikin manufacturers while creating price differentiation between ISO 13485-certified tier-one suppliers and uncertified competitors.
Pricing Analysis
FDA 510(k) clearance dictates the pricing tier structure across the patient simulator market, separating premium-validated AI-driven physiological engines from standard hardware-predicate systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in the mid-tier is intensifying because academic medical centers now unbundle technical support contracts for competitive bidding. Community hospitals exhibit the highest price sensitivity, while United States medical schools under LCME mandates demonstrate inelastic demand for high-fidelity systems.
Supply Chain Analysis
Silicone polymer feedstocks and specialty elastomers draw from petrochemical complexes in Germany, Japan, and the United States, with skin-grade material specifications resting on medical-grade certification chains. Precision valve assemblies for programmable vital signs sources from Baden-Württemberg and Osaka manufacturing clusters. Single-source vulnerability concentrates in haptic actuator controllers for software-native platforms. Distribution runs through hospital procurement committees and GPO contracts in North America, direct institutional sales in Europe, and emerging distributor networks across Indian medical college systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native platform economics are displacing installed-base advantages as subscription scenario libraries sever the traditional content-platform ownership bond, creating interoperability requirements that favor vendors with open API architectures over proprietary hardware ecosystems.
For Market Incumbents: Pre-empt disintermediation by acquiring cloud-native scenario content libraries before third-party marketplaces mature. Anchor defensive positioning through backward integration into precision pneumatics manufacturing in Germany or Japan, reducing exposure to valve assembly supply concentration. Certification investment in FDA AI-driven physiological engine pathways creates switching costs against software-native entrants. For New Entrants and Emerging Players: Build out augmented reality convergence offerings for United Kingdom and Canadian obstetrics departments, where maternal-neonatal simulation laboratory expansion outpaces high-fidelity manikin procurement capacity. The Indian medical college accreditation mandate across 22 states represents the most penetrable geography. A scenario-library-first go-to-market angle bypasses capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace-heritage simulation divisions seeking healthcare vertical diversification. Long-term viability hinges on platform economics capture rather than hardware replacement cycles. The signal to watch is Veterans Health Administration procurement centralization velocity, which accelerates third-party content marketplace formation and compresses integrated vendor margins.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR algorithm validation competency extends timelines for AI-integrated simulators entering European healthcare organizations. |
| Hospital System Partnership | Veterans Health Administration network standardization creates centralized procurement channels for trauma and combat casualty modules. |
| Software Companion Development | FDA 510(k) submissions for physiological engines require companion debriefing analytics to satisfy software-as-a-medical-device classification. |
| Reimbursement Strategy | LCME accreditation mandates in United States medical schools convert simulation infrastructure into non-discretionary capital allocation. |
| Platform Integration | Open API architectures enable third-party scenario marketplaces that collapse legacy vendor content ownership advantages. |
Methodological Framework
Desk research of FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement contracts, and academic medical center capital expenditure disclosures preceded structured interviews with simulation laboratory directors, biomedical engineering procurement leads, GPO contracts managers, and regulatory affairs specialists at notified bodies. Primary fieldwork with United States medical school administrators and Indian National Medical Commission accreditation officers combined with secondary validation through ISO certification registries and trade customs data. Bottom-up scenario utilization metrics and top-down capital allocation patterns underwent triangulation.
Assumptions held fixed include LCME accreditation mandate enforcement intensity, EU MDR classification stability for software diagnostic functions, and petrochemical feedstock price correlation patterns. The analytical framework modeled product type, application, end user, and technology dimensions across the projection horizon. CAGRs derived from replacement cycle analysis for physical manikins and subscription growth curves for cloud-native platforms. Forecast inputs incorporated maternal-neonatal sentinel event reduction targets in United Kingdom obstetrics departments and National Medical Commission infrastructure mandates across Indian states.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-native entrants or aerospace-heritage diversifiers would shift outcomes beyond modeled ranges. Cross-checking against Veterans Health Administration procurement standardization velocity and Indian medical college accreditation compliance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Patient Positioning Equipment Market