
 Total Lab Automation Market | 2026-2036
Total Lab Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Total Lab Automation Market Analysis
Buyer concentration among pharmaceutical companies and large contract research organizations is restructuring procurement dynamics across the Total Lab Automation landscape. Thermo Fisher Scientific Inc. leverages its integrated reagent-to-software portfolio to capture multi-year service contracts. Tecan Group Ltd. specializes in liquid-handling workstations that anchor its position in genomics and proteomics workflows. Danaher Corporation competes through its life sciences operating companies, extending automation architectures from sample prep through analytical readout.
Total lab automation encompasses integrated hardware and software systems that execute pre-analytical, analytical, and post-analytical laboratory procedures with minimal human intervention, typically achieving throughput rates exceeding 10,000 samples per day in high-volume clinical settings while maintaining coefficient-of-variation targets below 5 percent. Its primary purpose centers on eliminating manual pipetting errors, reducing turnaround times, and enabling continuous operation in diagnostic and research environments. Automation Systems and Workstations within the Product Type dimension lead current revenue pools, though Software segments are capturing expanding margin contributions as laboratories prioritize data integration and AI-driven decision support. Robotics and AI within the Technology dimension represent the fastest-advancing capability layers, displacing legacy barcode-scanning-dependent workflows in facilities pursuing predictive maintenance and autonomous quality control.
FDA 21 CFR Part 11 electronic records requirements and EU MDR device traceability mandates shape product development roadmaps, compelling vendors to embed audit trails and digital signatures as standard features rather than optional modules. ISO 15189 medical laboratory accreditation standards and CLIA regulations in the United States further constrain market access for systems lacking documented analytical performance verification. Stakeholders must monitor evolving AI validation frameworks from regulators and determine whether to build compliant algorithms internally or partner with established diagnostic platform providers.
Market Dynamics
Pharmaceutical contract research organizations are consolidating procurement around multi-year automation partnerships, compressing vendor selection cycles and elevating software integration capabilities above standalone hardware specifications in competitive evaluations.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates force diagnostic laboratories to replace legacy paper-based workflows with validated digital systems, creating immediate replacement demand across GLP-certified facilities in the United States.
- Genomics workflows:Next-generation sequencing throughput requirements exceed manual processing capacity, pushing academic medical centers and biobanks toward integrated liquid-handling robotics.
- China's NMPA:Accelerated medical device registration pathways for AI-enabled diagnostic instruments incentivize domestic manufacturers to automate quality control and batch release testing.
Market Restraints
- Capital intensity:Fully integrated automation lines require seven-figure upfront investment, excluding mid-sized hospital laboratories from vendor consideration sets.
- Consumables lock-in:Proprietary reagent cartridges and disposable tips tie operating economics to single-source supply agreements, amplifying total cost of ownership beyond initial equipment expenditure.
- EU MDR traceability:Device history record requirements extend validation timelines by 12-18 months, delaying revenue recognition for system deployments in European diagnostic networks.
Strategic Opportunities
- India's CDSCO:Relaxed import licensing for pre-owned refurbished automation creates secondary market entry for certified pre-analytical systems in price-sensitive Tier-2 cities.
- AI-ML convergence:Predictive maintenance algorithms layered onto existing robotics infrastructure unlock aftermarket software revenue without displacing installed hardware bases.
- Decentralized testing:Point-of-care molecular diagnostics demand compact, cloud-connected workstations that bridge clinical laboratory and physician office environments.
Industry Challenges
- Mechatronics talent scarcity:Shortage of technicians capable of servicing precision robotics and fluidics subsystems extends mean time to repair and elevates vendor service contract pricing.
- LIMS integration complexity:Proprietary data formats from legacy instrumentation resist standardized API connectivity, forcing custom middleware development for heterogeneous laboratory environments.
- ISO 15189 accreditation timelines:Documented analytical verification studies for automated methods consume 6-9 months, delaying operational deployment after physical installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Lab Automation Market |
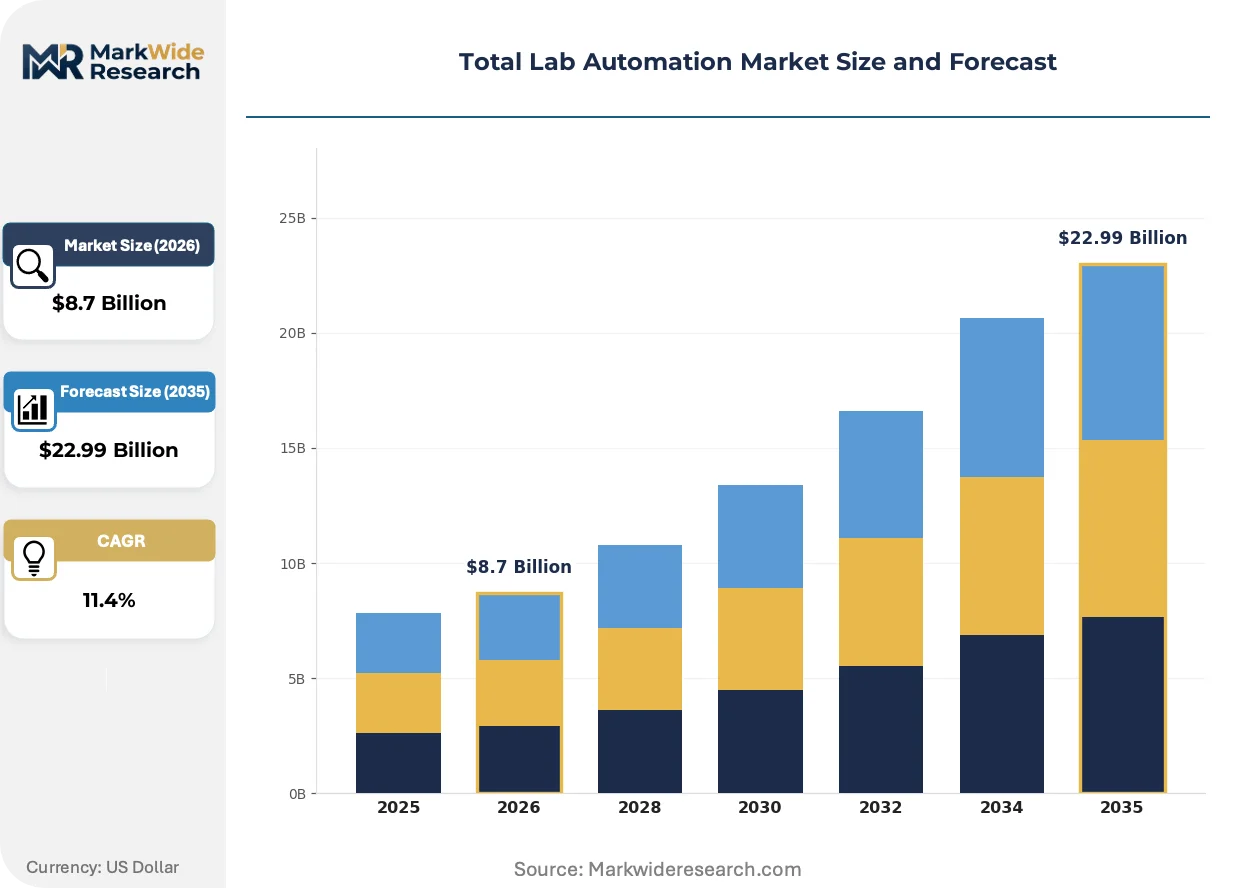
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Systems, Workstations, Software, Reagents End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Contract Research Organizations Technology: Robotics, AI, Machine Learning, Barcode Scanning Application: Sample Processing, Data Management, Quality Control, Inventory Management |
| Companies Covered | Siemens Healthineers AG, Tecan Group Ltd., Thermo Fisher Scientific Inc., PerkinElmer Inc., Agilent Technologies Inc., Danaher Corporation, Abbott Laboratories, Bio-Rad Laboratories Inc., Roche Diagnostics International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Lab Automation Market Emerging Trajectories
Artificial intelligence is penetrating laboratory decision layers previously reserved for human technologists, compressing quality control cycles and enabling autonomous exception handling in high-throughput environments.
Computer vision systems equipped with deep learning models are automating morphological assessment in hematology and microbiology workflows. Reference laboratories in Germany and Japan are deploying these systems for 24-hour unattended operation. The technology is automating slide review queues that previously required staffed evening shifts, reducing labor cost structures by reallocating specialist pathologists to complex case arbitration.
EU MDR Article 10 post-market surveillance obligations now require automated systems to generate structured periodic safety update reports without manual data aggregation. Device manufacturers must embed standardized data export formats compatible with EUDAMED submission portals. In vitro diagnostic kit producers operating automated manufacturing lines face the steepest compliance burden, driving demand for manufacturing execution systems with built-in regulatory reporting modules.
Service contract unbundling is fragmenting traditional full-service agreements into discrete software subscription, spare parts logistics, and remote support tiers. Large pharmaceutical quality control laboratories in the United States are negotiating à-la-carte maintenance arrangements that exclude on-site engineer visits. This restructuring concentrates vendor profitability in high-margin software components while commoditizing hardware break-fix coverage.
Total Lab Automation Market Segmentation
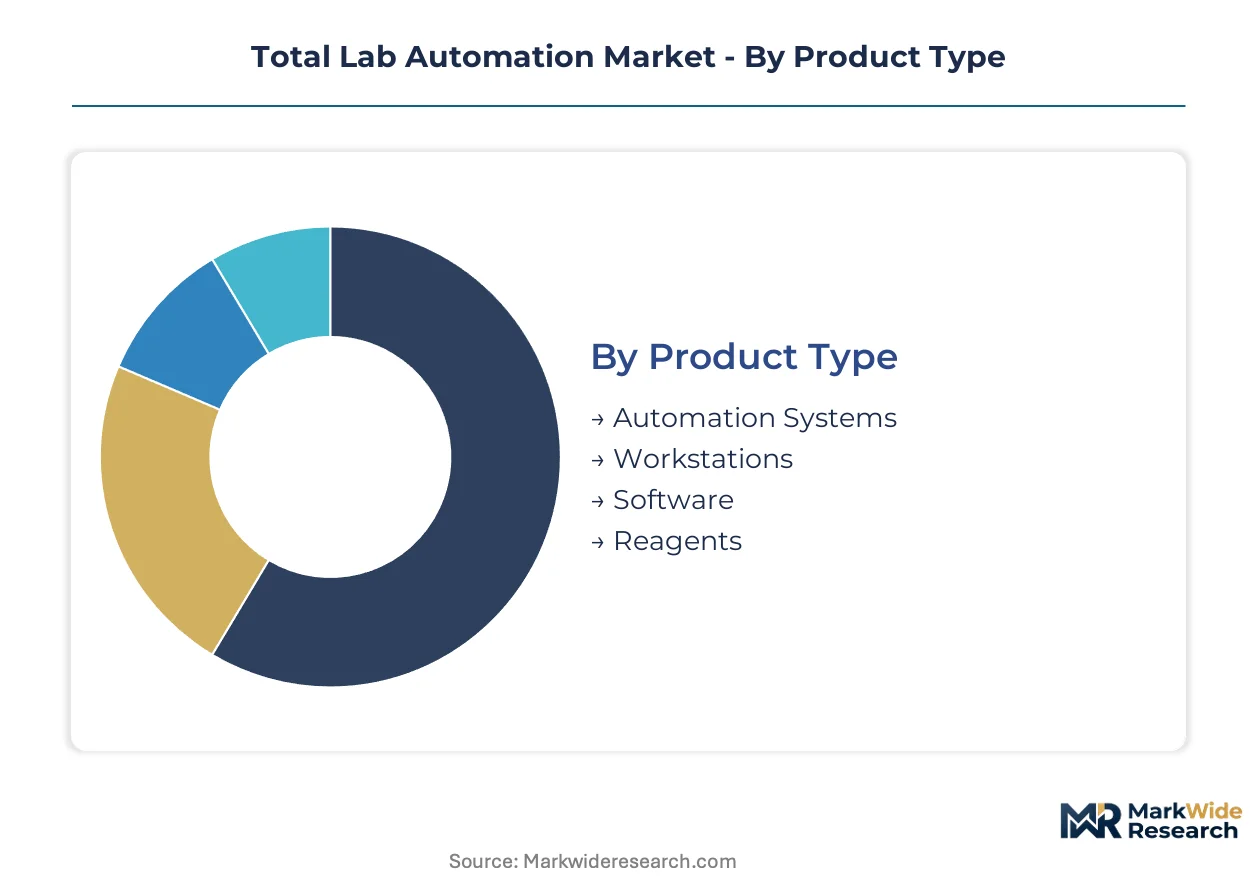
Segmentation in total lab automation reveals divergent upgrade cycles across hardware and software layers. Pharmaceutical companies and diagnostic networks prioritize replacement timing based on regulatory deadlines rather than equipment age alone.
Product Type:
Replacement cycles vary sharply across capital equipment versus recurring revenue categories, with FDA validation timelines forcing synchronized upgrades across integrated portfolios.
- Automation Systems:Integrated lines handling pre-analytical through post-analytical workflows command seven-figure capital commitments. Demand clusters in GLP-certified contract research facilities in the United States and Germany as these sites face FDA 21 CFR Part 11 and EU MDR compliance deadlines simultaneously.
- Workstations:Modular liquid-handling platforms anchor genomics and proteomics pipelines with throughput rates exceeding 10,000 samples daily. Academic medical centers in China are expanding procurement as NMPA accelerates AI-enabled device registrations.
- Software:LIMS integration and AI-driven decision support layers capture expanding margin contributions from existing hardware bases.
- Reagents:Proprietary consumables lock operating economics into single-source supply agreements, amplifying total cost of ownership.
Volume placements concentrate in Automation Systems; the faster expansion belongs to Software.
End User:
Procurement authority is consolidating around multi-year automation partnerships, compressing vendor selection cycles and elevating integration capabilities in competitive evaluations.
- Clinical Laboratories:High-volume diagnostic networks in the United States pursue 24-hour unattended operation to reduce labor cost structures. ISO 15189 accreditation standards and CLIA regulations constrain market access for systems lacking documented analytical performance verification.
- Pharmaceutical Companies:Quality control laboratories are unbundling traditional full-service agreements into discrete software subscription and remote support tiers. FDA electronic records mandates force replacement of legacy paper-based workflows with validated digital systems.
- Research Institutions:Academic medical centers face capital intensity barriers that exclude mid-sized hospital laboratories from integrated automation consideration sets.
- Contract Research Organizations:Large CROs are consolidating procurement around multi-year partnerships, compressing vendor selection cycles.
Contract Research Organizations dominate current procurement volume; Research Institutions face the steepest capital barriers to participation.
Technology:
Capability layers are displacing legacy workflows in facilities pursuing predictive maintenance and autonomous quality control.
- Robotics:Precision fluidics and mechatronics subsystems require scarce technician talent, extending mean time to repair. Reference laboratories in Germany and Japan deploy these systems for unattended overnight operation.
- AI:Deep learning models automate morphological assessment in hematology and microbiology, reallocating specialist pathologists to complex case arbitration. EU MDR Article 10 post-market surveillance obligations now require structured periodic safety update reports without manual data aggregation.
- Machine Learning:Predictive maintenance algorithms unlock aftermarket software revenue without displacing installed hardware bases.
- Barcode Scanning:Legacy identification workflows persist in cost-constrained environments but face displacement by computer vision systems.
Robotics commands the largest installed base; AI is climbing the fastest as regulatory frameworks mature.
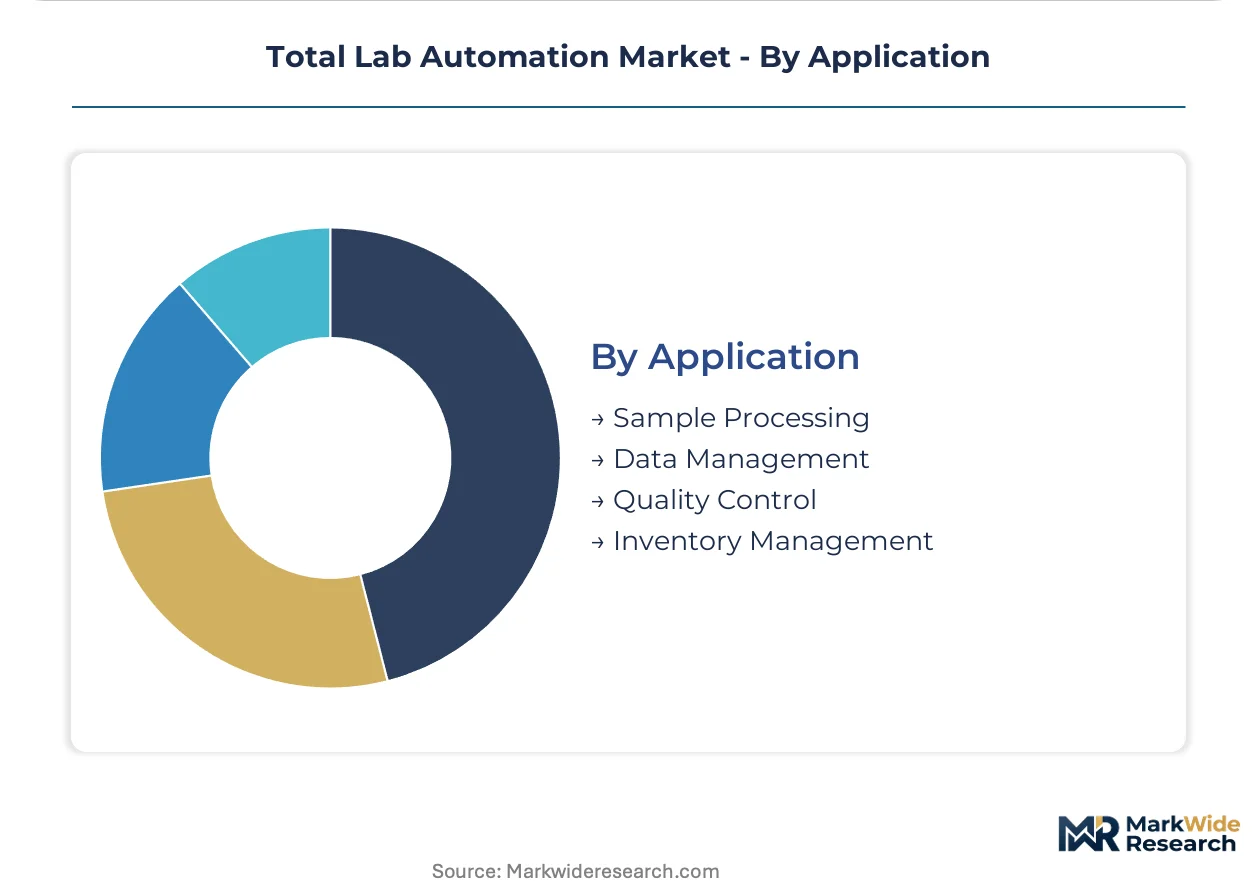
Application:
Functional priorities differ between diagnostic laboratories seeking turnaround compression and research environments optimizing for throughput flexibility.
- Sample Processing:Pre-analytical automation eliminates manual pipetting errors in high-throughput clinical settings. Next-generation sequencing throughput requirements exceed manual processing capacity, pushing academic medical centers toward integrated liquid-handling robotics.
- Data Management:Proprietary data formats from legacy instrumentation resist standardized API connectivity, forcing custom middleware development. Laboratories prioritize data integration across heterogeneous instrument fleets.
- Quality Control:Autonomous exception handling compresses quality control cycles in high-throughput environments. EU MDR device traceability mandates extend validation timelines by 12-18 months for European diagnostic networks.
- Inventory Management:Cloud-connected workstations bridge clinical laboratory and physician office environments for decentralized testing models.
Sample Processing absorbs the largest share of automation investment; Data Management is gaining share fastest as interoperability demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract research organizations cluster their automation procurement in the United States, Germany, and China, where GLP-certified facility density drives replacement demand. Regulatory deadlines for FDA 21 CFR Part 11 and EU MDR compliance are synchronizing upgrade cycles across these three markets. Each geography presents distinct procurement authority structures and compliance acceleration mechanisms.
United States
High-volume diagnostic networks in Massachusetts and North Carolina pursue 24-hour unattended operation to compress labor cost structures. FDA 21 CFR Part 11 electronic records mandates force replacement of legacy paper-based workflows with validated digital systems. The Research Triangle Park cluster hosts dense concentrations of contract research facilities facing synchronized compliance deadlines.
Germany
Reference laboratories in Munich and Heidelberg deploy computer vision systems for overnight unattended morphological assessment. EU MDR Article 10 post-market surveillance obligations require automated generation of structured periodic safety update reports. The Baden-Württemberg industrial corridor concentrates precision mechatronics talent servicing fluidics subsystems.
China
Academic medical centers in Shanghai and Beijing expand procurement of modular liquid-handling platforms as NMPA accelerates AI-enabled device registration pathways. The national regulator's relaxed import licensing for refurbished pre-analytical systems creates secondary market entry in price-sensitive Tier-2 cities. Yangtze River Delta biobanks drive next-generation sequencing throughput requirements exceeding manual capacity.
Japan
Tokyo and Osaka metropolitan laboratories deploy predictive maintenance algorithms layered onto existing robotics infrastructure. METI standards for autonomous quality control shape vendor product development roadmaps. The Kansai region's diagnostic networks prioritize software integration capabilities above standalone hardware specifications in competitive evaluations.
India
CDSCO relaxed import licensing enables certified pre-owned automation penetration into Tier-2 hospital laboratories in Maharashtra and Karnataka. Capital intensity barriers exclude mid-sized facilities from integrated seven-figure automation lines. The Delhi-NCR corridor concentrates pharmaceutical quality control laboratories unbundling traditional full-service agreements into discrete software tiers.
Total Lab Automation Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven software overlays and predictive maintenance services. The vendor base stratifies across three maturity tiers: diversified life sciences conglomerates with integrated reagent-to-software portfolios; specialized liquid-handling workstation fabricators anchoring genomics workflows; and diagnostics platform providers extending automation architectures from sample prep through analytical readout. Consolidation pressure concentrates procurement authority around multi-year automation partnerships. Competitive moves center on strategic partnerships for LIMS integration capabilities and portfolio diversification into cloud-connected decentralized testing workstations.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc., Danaher Corporation, and Siemens Healthineers AG exemplify integrated platform strategies spanning pre-analytical through post-analytical workflows. These entities occupy positions where multi-year service contracts and proprietary consumables lock-in amplify total cost of ownership economics. Tecan Group Ltd. and PerkinElmer Inc. represent the specialized workstation archetype, with geographic origins in Switzerland and the United States respectively. Their market positions derive from modular liquid-handling platforms that anchor high-throughput genomics and proteomics pipelines. Roche Diagnostics International AG and Abbott Laboratories exemplify diagnostics-native automation strategies, with Swiss and American corporate structures positioning them within regulated device traceability frameworks.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Tecan Group Ltd. |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| Bio-Rad Laboratories Inc. |
| Roche Diagnostics International AG |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up liquid-handling specialists in Switzerland and the United States anchor supply-side discipline through captive consumables revenue streams, translating proprietary reagent lock-in into pricing power that resists commoditization pressure across pharmaceutical quality control laboratories.
Pricing Analysis
Volume placements concentrate in seven-figure integrated automation lines while margin expansion flows to software subscriptions and predictive maintenance tiers. Pricing stratifies across FDA-validated premium systems, CE-marked standard workstations, and refurbished economy units entering India through relaxed CDSCO pathways. Cost compression in the economy tier intensifies as Chinese domestic manufacturers exploit NMPA accelerated registration for AI-enabled devices. Contract research organizations exhibit lowest price sensitivity due to multi-year partnership consolidation; mid-sized hospital laboratories face exclusion from integrated line consideration sets.
Supply Chain Analysis
Refurbishment flows from Germany and the United States into India's Tier-2 cities through CDSCO-certified pre-owned channels, creating secondary circulation that extends equipment lifecycles and fragments new-equipment demand. Precision mechatronics subsystems draw from Switzerland, Germany, and Japan, with fluidics components resting on specialized polymer supply chains concentrated in Baden-Württemberg. Single-source vulnerability persists in proprietary disposable tips and reagent cartridges that tether operating economics to original vendor agreements. Distribution runs through direct field service organizations for premium tiers and third-party logistics partners for consumables replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA 21 CFR Part 11 compliance deadlines is compressing vendor selection cycles and forcing capital-constrained mid-caps toward acquisition or exit.
For Market Incumbents: Deepen vertical control over precision fluidics manufacturing to insulate margins from mechatronics talent scarcity. Expand predictive maintenance software attach rates on installed robotics bases in Germany and Japan before emerging AI-native entrants displace legacy barcode-dependent workflows. For New Entrants and Emerging Players: Capture white-space in India's Tier-2 pre-analytical refurbishment market where CDSCO relaxed licensing creates entry without seven-figure capital requirements. Target cloud-connected decentralized testing workstations bridging clinical laboratory and physician office environments through SaaS-enabled service models. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized liquid-handling workstation fabricators with ISO 15189-compliant installed bases in China and fragmented European diagnostic networks. Watch NMPA AI-validation framework maturation as inflection signal for domestic Chinese automation platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-ML Companion Development | Predictive maintenance algorithms layered onto Tecan and Thermo Fisher robotics unlock recurring software revenue without hardware displacement. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 validation investment separates premium-tier vendors from economy competitors in GLP-certified CRO procurement. |
| Backward Integration | In-house precision fluidics manufacturing insulates Danaher and Siemens from mechatronics technician scarcity elevating service costs. |
| Strategic Partnership | LIMS integration alliances with Epic and Cerner determine competitive positioning in United States academic medical center evaluations. |
| Geographic Expansion | NMPA accelerated AI-device registration enables domestic Chinese manufacturers to challenge Swiss and American incumbents in Yangtze River Delta biobanks. |
Methodological Framework
Independent corroboration across laboratory operations directors, biomedical engineers at GLP-certified CROs, GPO contracts managers, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and ISO 15189 accreditation records. Bottom-up segmentation modeling triangulates against top-down pharmaceutical R&D expenditure and diagnostic laboratory capital budget proxies.
Rate-of-change decomposition across the analysis window isolates volume growth in automation systems from value expansion in software and services. Segmentation dimensions span product type, end-user archetype, technology layer, and application function, with regional regulatory cluster as an additional modeling axis. CAGRs derive from installed base replacement cycles synchronized to FDA and EU MDR compliance deadlines, overlaid with NMPA pathway acceleration effects and CDSCO secondary market penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI-validation framework maturation, mechatronics talent pipeline constraints, and consumables lock-in regulatory scrutiny. Forecasts reflect documented assumptions regarding replacement timing, compliance deadline adherence, and technology substitution elasticities. Material deviation in NMPA AI-registration velocity or EU MDR post-market surveillance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Global Phototherapy Equipment Market