
 Clinical Trial Equipment and Ancillary Solutions Market | 2026-2036
Clinical Trial Equipment and Ancillary Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Equipment and Ancillary Solutions Market Intelligence
Cloud-connected telemetry is fragmenting the traditional site-based equipment model into distributed, patient-centric architectures. Thermo Fisher Scientific leverages its end-to-end laboratory platform to sustain service density across Phase I-III trials. Danaher Corporation anchors instrument reliability through diagnostic-grade manufacturing protocols. PAREXEL International Corp. competes on protocol-specific logistics integration rather than hardware ownership.
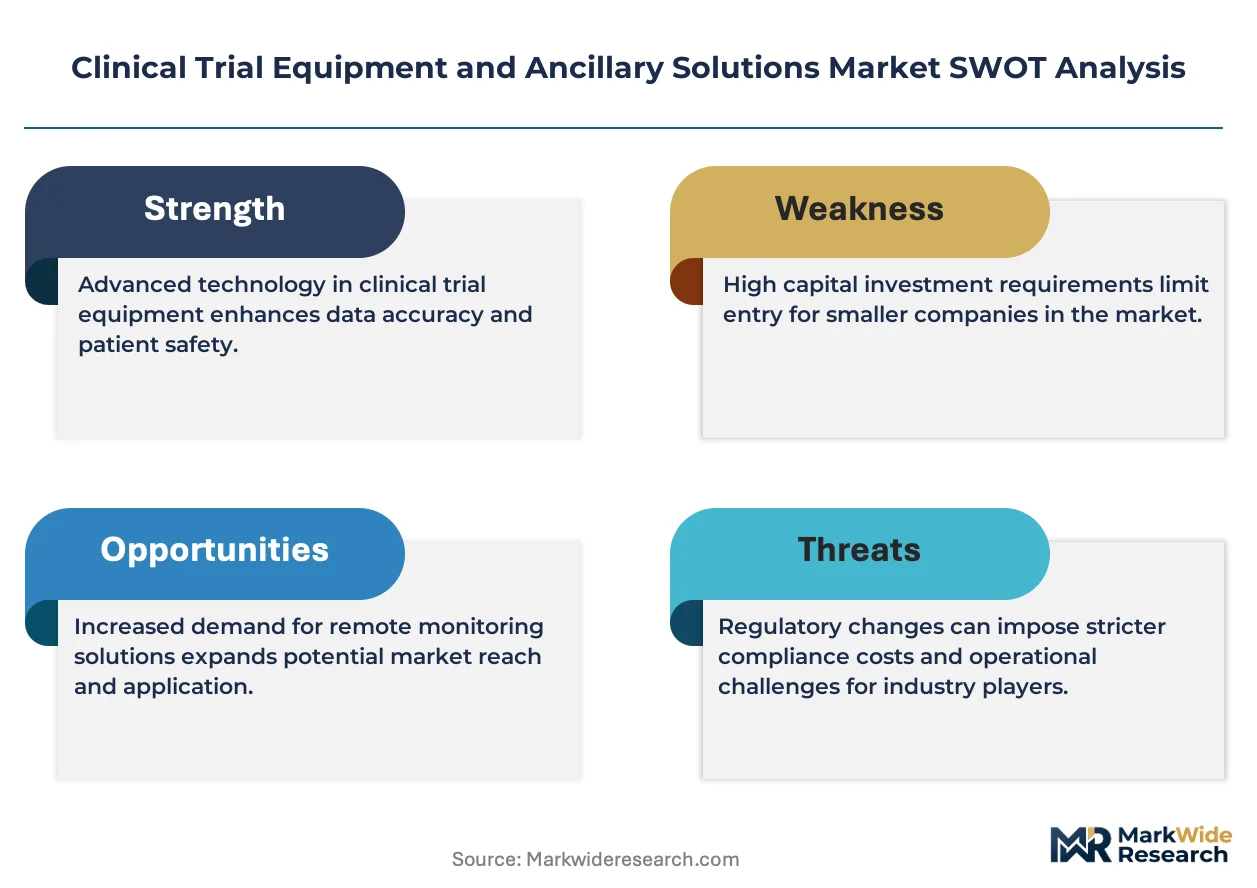
Clinical trial equipment and ancillary solutions comprise purpose-built instruments, consumables, and supporting infrastructure engineered to capture, process, and transmit patient data under Good Clinical Practice conditions; specifications typically include temperature-controlled storage ranges, calibration tolerances traceable to ISO 17025, and interoperability with electronic data capture platforms. The primary commercial purpose is to preserve data integrity across geographically dispersed investigational sites while enabling regulatory audit trails. Imaging devices and lab instruments retain the deepest margin pools due to capital intensity and recurring service contracts. Wearable devices and remote monitoring represent the fastest-expanding technology dimension as sponsors pursue hybrid and decentralized trial designs. Pharmaceutical companies and clinical research organizations dominate end-user procurement, though research institutions occupy growing share in early-phase academic-led studies.
FDA's guidance on decentralized clinical trials and EMA's reflection paper on remote data collection reshape equipment validation requirements, compelling manufacturers to demonstrate cybersecurity and patient-identity verification capabilities. ISO 14155 and ICH-GCP standards govern design controls and risk management, creating compliance barriers for entrants lacking established quality systems. Stakeholders must weigh capital deployment against subscription-based equipment service models as trial complexity shifts toward continuous, real-world data capture.
Market Dynamics
Decentralized trial architectures are fragmenting equipment deployment from centralized sites to distributed patient locations, forcing manufacturers to revalidate calibration protocols and data-capture workflows across variable home environments rather than controlled clinical settings.
Growth Catalysts
- FDA Decentralized Clinical Trial Guidance:The agency's 2023 guidance on remote data collection removes regulatory ambiguity for wearable-enabled protocols, accelerating sponsor investment in telemetry infrastructure.
- Cloud-native telemetry platforms:Real-time data transmission from patient homes compresses monitoring timelines and reduces site visit burdens for cardiology and metabolic studies.
- EMA reflection paper on digital health technologies:The European regulator's framework for remote monitoring legitimizes patient-centric trial designs across EU member states.
Market Restraints
- ISO 17025 calibration costs:Temperature-controlled storage devices require recurrent third-party certification, elevating total cost of ownership for multi-site oncology trials.
- Single-source sensor suppliers:Specialized biometric chip fabrication concentrates in East Asian foundries, exposing equipment manufacturers to geopolitical supply disruption.
- Interoperability gaps:Legacy electronic data capture platforms lack native API connectivity with emerging wearable protocols, forcing expensive middleware development.
Strategic Opportunities
- Underpenetrated Latin American sites:Brazil's ANVISA has streamlined import licensing for clinical trial devices, opening patient recruitment pools for infectious disease studies.
- AI-enabled predictive maintenance:Machine learning algorithms applied to instrument telemetry reduce unplanned downtime and extend service contract attach rates.
- Subscription-based equipment-as-a-service:Biotech sponsors increasingly prefer operational expenditure models over capital deployment for Phase I-II adaptive trials.
Industry Challenges
- Cybersecurity validation complexity:FDA's software-as-a-medical-device guidance requires continuous threat monitoring for cloud-connected instruments, extending qualification timelines.
- Specialized field engineering scarcity:Hybrid trial models demand technicians capable of both laboratory calibration and patient home troubleshooting, a skill intersection with limited training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Equipment and Ancillary Solutions Market |
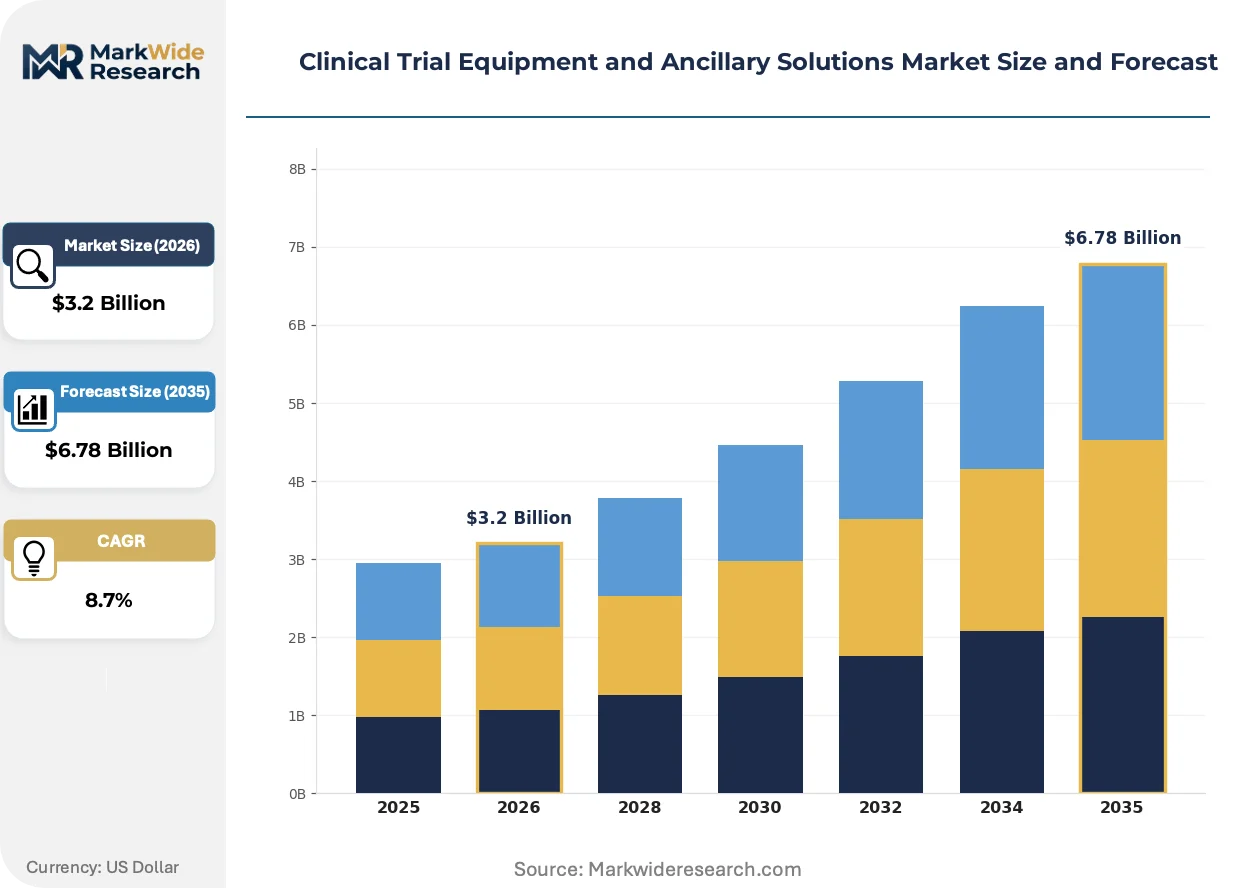
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Equipment, Imaging Devices, Lab Instruments, Monitoring Systems Application: Cardiology, Oncology, Neurology, Pediatric Trials Technology: Wearable Devices, Remote Monitoring, Biometric Sensors, Cloud Solutions End User: Pharmaceutical Companies, Research Institutions, Clinical Research Organizations, Academic Entities |
| Companies Covered | Thermo Fisher Scientific Inc., Ancillare LP, PAREXEL International Corp., Marken, Danaher Corporation, Merck KGaA, Agilent Technologies Inc., Iron Mountain Incorporated, Imperial CRS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Equipment and Ancillary Solutions Market Strategic Shifts & Innovations
Equipment architectures are pivoting from site-centric hardware ownership toward patient-located, connectivity-first service models that prioritize data continuity over physical instrument control.
Point-of-care diagnostics is migrating from centralized laboratory analyzers to handheld, connected devices capable of immediate biomarker quantification at patient homes. Mid-size biotech sponsors are adopting these platforms for real-time pharmacokinetic monitoring in early-phase oncology studies. This shift is compressing the traditional site-lab logistics chain and redistributing margin capture from central laboratories to device-integrated service providers.
EMA's Medical Device Regulation (MDR) is tightening clinical evidence requirements for trial equipment with diagnostic functions, compelling manufacturers to generate performance data beyond ISO 14155 compliance. In-vitro diagnostic components now face notified body scrutiny previously reserved for therapeutic devices. European CROs are responding by consolidating vendor qualification processes and demanding pre-submitted technical documentation packages.
Site-less trial participation is reconfiguring patient recruitment geography away from metropolitan academic medical centers toward suburban and rural catchment areas. Decentralized networks of home health nurses and mobile phlebotomists are displacing traditional site coordinators as the primary patient touchpoint. This pattern is most pronounced in United States metabolic and cardiovascular studies where travel burden historically drove dropout rates.
Clinical Trial Equipment and Ancillary Solutions Market Segmentation
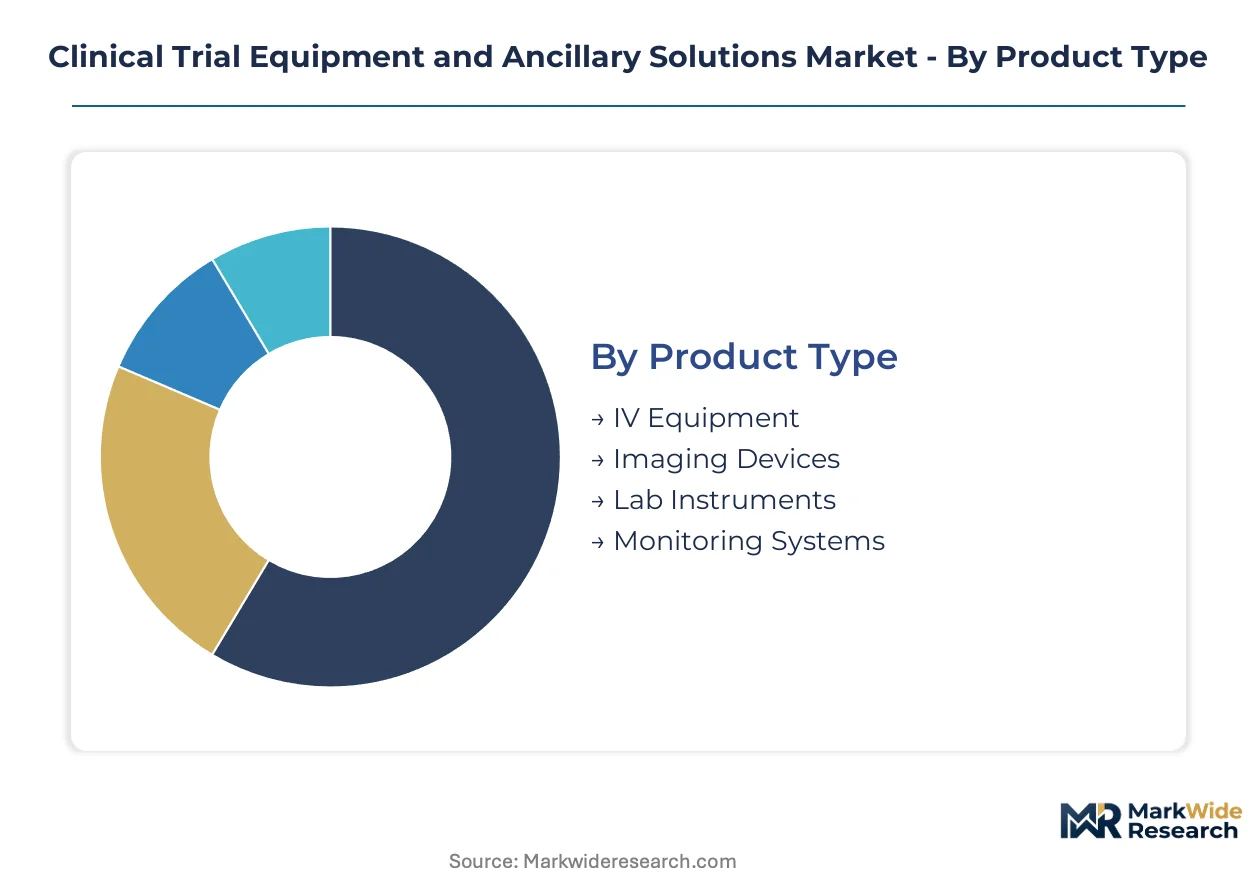
Segmentation in clinical trial equipment reveals how technology specialization, therapeutic focus, and procurement authority fragment purchasing decisions across sponsor organizations. Equipment vendors must align calibration protocols and service models to distinct user workflows rather than deploying uniform platforms.
Product Type:
Equipment selection spans acute intervention tools through longitudinal data capture systems, with capital intensity and service attach rates varying sharply across categories.
- Imaging Devices:MRI-compatible monitors and portable ultrasound systems deliver diagnostic-grade visualization under ISO 13485 quality systems. Demand concentrates in United States oncology studies where FDG-PET validation requires traceable calibration chains. Deep margin pools persist from recurring service contracts and software upgrade cycles.
- Lab Instruments:Centrifuges, analyzers, and cold-chain storage units process biomarker samples under temperature-controlled protocols. Pharmaceutical sponsors in Germany and Switzerland anchor procurement for Phase III immunology trials where EMA stability guidelines mandate continuous monitoring documentation.
- IV Equipment:Infusion pumps and vascular access devices support acute care settings in traditional site-based protocols.
- Monitoring Systems:Multi-parameter bedside units aggregate vital signs for centralized surveillance in intensive care study arms.
Established volume favors imaging devices; emerging adoption favors lab instruments configured for point-of-care decentralization.
Application:
Therapeutic area requirements dictate sensor specifications, patient mobility allowances, and regulatory submission pathways for equipment validation.
- Oncology:Immune cell therapy trials demand cryogenic storage and chain-of-custody tracking for cellular products. United States academic medical centers drive specifications for CAR-T manufacturing support equipment.
- Cardiology:Ambulatory ECG and blood pressure monitors enable outpatient safety surveillance. Remote monitoring adoption climbs fastest in United States metabolic syndrome studies where patient travel burden historically eroded retention.
- Neurology:EEG and sleep study devices require specialized signal processing for central nervous system endpoints.
- Pediatric Trials:Miniaturized sensors and age-appropriate interfaces address developmental variability in juvenile patient populations.
Cardiology applications are expanding most quickly through wearable-enabled decentralized designs; oncology retains the deepest equipment investment per enrolled patient.
Technology:
Connectivity architecture determines data latency, cybersecurity exposure, and integration cost with sponsor electronic data capture platforms.
- Wearable Devices:Continuous glucose monitors and activity trackers transmit biometric streams via Bluetooth Low Energy to cloud gateways. FDA software-as-a-medical-device guidance shapes validation scope for algorithm-driven endpoints.
- Remote Monitoring:Hub-and-spoke telemetry platforms aggregate home-based measurements for centralized medical review. EMA reflection paper on digital health technologies legitimizes patient-centric deployment across EU member states.
- Biometric Sensors:Specialized chips for heart rate variability and galvanic skin response concentrate fabrication in East Asian foundries.
- Cloud Solutions:Data lakes and API middleware bridge device output to sponsor databases, with HIPAA and GDPR compliance as table stakes.
Wearable devices gain share fastest in early-phase adaptive trials; remote monitoring platforms secure longest contract durations through integrated service bundling.
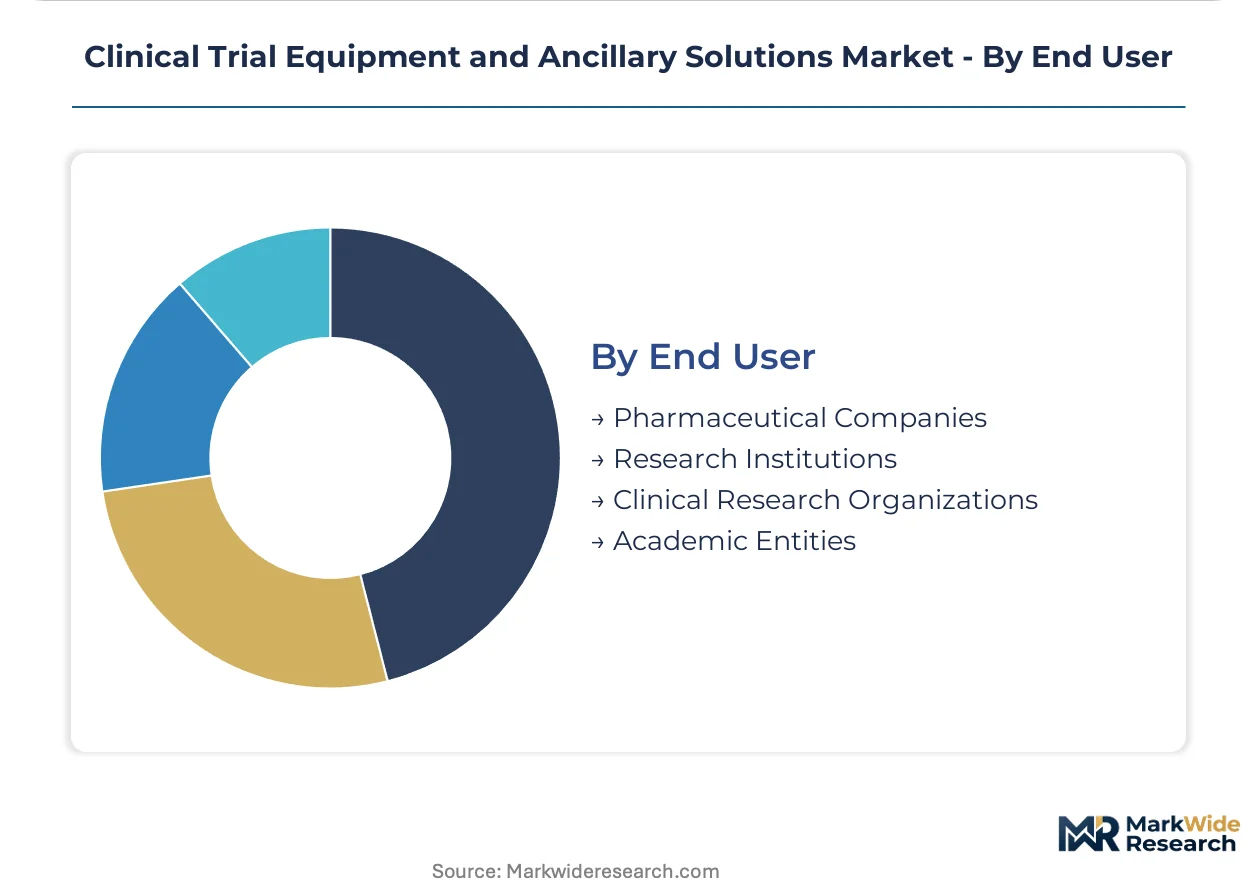
End User:
Procurement authority and budget structure differentiate equipment acquisition patterns across organizational types.
- Clinical Research Organizations:Full-service CROs deploy standardized equipment fleets across multi-site protocols to compress startup timelines. PAREXEL and IQVIA anchor United States demand through integrated logistics capabilities.
- Pharmaceutical Companies:Large sponsors maintain captive equipment pools for strategic therapeutic areas, preferring capital ownership over rental for Phase III programs.
- Research Institutions:Academic medical centers balance NIH funding constraints against equipment sharing agreements across investigator-initiated studies.
- Academic Entities:University-based early-phase units prioritize flexible rental terms and training support over purchase options.
CRO procurement favors standardized platforms; pharmaceutical direct ownership concentrates in late-phase, high-enrollment protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss laboratory equipment manufacturers export precision cold-chain systems to United States pharmaceutical sponsors, while Chinese sensor fabricators supply biometric chipsets to wearable device assemblers across European Union member states.
United States
FDA's 2023 decentralized clinical trial guidance accelerates procurement of cloud-connected telemetry platforms by oncology and cardiology sponsors. The agency's software-as-a-medical-device framework imposes continuous cybersecurity validation on remote monitoring equipment. Boston and San Diego anchor equipment deployment for CAR-T therapy trials, with academic medical centers driving cryogenic storage specifications.
Germany
EMA stability guidelines for Phase III immunology trials sustain demand for temperature-controlled storage units with ISO 17025-traceable calibration. The country's national pharmaceutical regulator enforces MDR compliance for diagnostic-grade trial equipment. Frankfurt and Munich cluster pharmaceutical logistics providers integrating instrument fleets across multi-site EU protocols.
Switzerland
Swissmedic's alignment with EMA reflection papers on digital health technologies legitimizes wearable-enabled trial designs for Basel-headquartered pharmaceutical sponsors. Roche and Novartis procurement patterns favor capital ownership of imaging devices over rental models. The Lake Geneva region concentrates diagnostic-grade manufacturing protocols for precision lab instruments.
China
NMPA's evolving framework for imported medical devices shapes validation timelines for multinational sponsors conducting trials in Shanghai and Beijing. Domestic foundries concentrate biometric sensor fabrication for continuous glucose monitors and activity trackers. The Yangtze River Delta hosts contract manufacturers assembling telemetry hardware for export to European CROs.
Brazil
ANVISA's streamlined import licensing for clinical trial devices opens patient recruitment pools for infectious disease studies in São Paulo and Rio de Janeiro. Local logistics providers adapt cold-chain infrastructure for tropical climate conditions. The Southeast region attracts decentralized trial equipment deployment as sponsors seek underpenetrated recruitment geography.
Clinical Trial Equipment and Ancillary Solutions Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Full-service CROs and pharmaceutical sponsors split equipment acquisition between standardized fleet deployment and captive therapeutic-area pools. Three archetypes dominate: integrated logistics platforms, precision instrument manufacturers, and specialty rental service providers. Competitive moves concentrate on M&A for calibration service networks and strategic partnerships for cloud-native telemetry integration.
Among precision instrument manufacturers, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the capital-intensive archetype with end-to-end laboratory platforms. PAREXEL International Corp. occupies a distinct position as a logistics-integrating CRO competing on protocol-specific service bundling rather than hardware ownership. These three entities represent the dominant competitive vectors shaping procurement patterns across Phase I-III trial architectures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Ancillare LP |
| PAREXEL International Corp. |
| Marken |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies Inc. |
| Iron Mountain Incorporated |
| Imperial CRS Inc. |
| Others |
Cost & Logistics Intelligence
Single-source biometric sensor dependency in East Asian foundries compresses margin structures across equipment tiers while simultaneously forcing sponsors toward subscription-based procurement models that externalize capital risk. This concentration dynamic widens pricing spreads between ISO 17025-certified diagnostic-grade instruments and uncertified economy alternatives as validation timelines extend.
Pricing Analysis
Next-generation wearable telemetry platforms command substantial premiums over legacy site-based monitoring systems, while prior-generation bedside units face accelerating price erosion. Pricing stratifies across premium, standard, and economy tiers based on FDA software-as-a-medical-device certification status and after-sales calibration bundling. Cost compression in the economy tier intensifies because sponsors increasingly prefer operational expenditure models for Phase I-II adaptive trials. Biotech sponsors exhibit highest price sensitivity; large pharmaceutical companies demonstrate lowest sensitivity due to captive equipment pool strategies.
Supply Chain Analysis
Specialized semiconductor feedstock for biometric sensors concentrates fabrication in China, Taiwan, and South Korea, with domestic foundries supplying continuous glucose monitor chipsets for export assembly. Equipment manufacturing draws from precision cold-chain components sourced from Germany and Switzerland, rare-earth magnets for imaging systems, and medical-grade polymers for disposable consumables. Single-source vulnerability in East Asian sensor supply exposes manufacturers to geopolitical disruption. Distribution runs through pharmaceutical logistics providers integrating instrument fleets across multi-site protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decentralized trial architecture fragmentation creates equipment specialization niches as sponsor procurement authority splinters between CROs, pharmaceutical companies, and academic institutions with divergent validation requirements.
For Market Incumbents: Pre-empt emerging entrant pressure in wearable telemetry by acquiring calibration service networks in Brazil and India where ANVISA and CDSCO regulations are tightening. Consolidate backward integration into biometric sensor supply through strategic partnerships with Taiwanese foundries. Prioritize ISO 14155 certification investments that emerging players cannot replicate within qualification timelines. For New Entrants and Emerging Players: Establish a beachhead in Latin American infectious disease trial equipment where ANVISA import licensing reforms have reduced barrier heights. Target Brazilian CROs seeking tropical climate-adapted cold-chain solutions as the most penetrable buyer segment. Deploy equipment-as-a-service pricing to bypass capital ownership preferences among mid-size biotech sponsors. For Investors and Strategic Acquirers: FDA's evolving software-as-a-medical-device guidance reshapes the acquisition landscape toward cloud-native telemetry platforms with embedded cybersecurity validation. Five-to-ten year viability favors precision instrument manufacturers with diagnostic-grade manufacturing protocols over hardware-agnostic logistics integrators. Monitor EMA Medical Device Regulation enforcement intensity as the signal indicating consolidation timing for European equipment vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Acquisition | Compresses startup timelines for multi-site oncology protocols requiring ISO 17025 traceability. |
| Wearable Telemetry Platform Integration | Enables FDA-compliant remote monitoring for decentralized cardiology studies. |
| Equipment-as-a-Service Model Launch | Aligns procurement with biotech sponsor preference for operational expenditure structures. |
| Latin American Logistics Partnership | Captures ANVISA-streamlined import pathways for infectious disease trial expansion. |
| Cybersecurity Validation Investment | Satisfies FDA software-as-a-medical-device continuous threat monitoring requirements. |
Research Approach
Initial hypotheses were tested against primary input from clinical trial operations directors, regulatory affairs specialists, biomedical equipment procurement managers, and CRO logistics coordinators and refined through secondary validation against FDA 483 inspection observations, EMA reflection papers, ClinicalTrials.gov protocol registrations, and ISO 14155 audit reports. Bottom-up equipment deployment estimates triangulated against top-down pharmaceutical R&D expenditure allocations.
Demand-supply balance across the analysis window incorporated therapeutic area enrollment velocity, site activation timelines, and equipment replacement cycles. Segmentation modeling spanned product type, application, technology architecture, and end-user procurement authority with regional regulatory cluster overlays. CAGRs derived from slope-intercept analysis of sponsor capital expenditure patterns and service contract renewal rates, with cross-reference to EDC platform integration complexity indices.
Sensitivities concentrate around FDA guidance revision timelines, EMA MDR enforcement intensity, and East Asian foundry capacity allocation shifts. Cross-checking against IQVIA clinical trial site activation data and Thermo Fisher Scientific segment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market