
 Portable Clinical Analyzer Market | 2026-2036
Portable Clinical Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Clinical Analyzer Market Analytics
EU MDR is recalibrating the cost-of-entry calculus for portable clinical analyzer manufacturers seeking European market access. Siemens Healthineers leverages its extensive regulatory affairs infrastructure to navigate expanded clinical evidence requirements. Abbott Laboratories anchors its competitive position through integrated cartridge ecosystems that simplify compliance documentation. Roche Diagnostics sustains technology leadership by concentrating R&D investment on multiplexed assay platforms that satisfy heightened performance benchmarking.
A portable clinical analyzer is a compact, transportable instrument designed to perform quantitative or qualitative biochemical, hematological, or immunological assays outside traditional centralized laboratory infrastructure, typically operating with sample volumes below 500 microliters and delivering results within 15 minutes for acute clinical decision-making. These devices integrate microfluidic channels, optical detection modules, and electrochemical sensors to automate sample processing and analysis at the point of patient contact. Blood gas analyzers currently dominate installed base volumes across intensive care settings, while immunoassay analyzers represent the fastest-expanding product category driven by cardiac biomarker and infectious disease testing demand. Microfluidics technology commands premium positioning due to consumable lock-in and assay miniaturization advantages, whereas lab-on-a-chip architectures are gaining traction in resource-limited environments where reagent stability and cold-chain independence prove decisive.
FDA 510(k) pathways, EU MDR technical documentation requirements, and CLIA waiver standards collectively shape product development timelines, commercial launch sequencing, and geographic prioritization for portable clinical analyzer portfolios. The FDA's progressive tightening of predicate device equivalency standards is extending clearance durations and elevating clinical validation expenditures for novel platform introductions. Stakeholders must monitor evolving payer coverage determinations for point-of-care testing codes, as reimbursement parity with central laboratory fees will determine adoption velocity across ambulatory and home-based settings.
Market Dynamics
EU MDR's expanded clinical evidence requirements are compressing commercial timelines and forcing manufacturers to front-load validation expenditures before European market entry, fundamentally altering capital allocation across R&D portfolios.
Growth Catalysts
- CLIA Waiver Expansion:The FDA's streamlined waiver pathway for moderate-complexity devices is accelerating ambulatory deployment of waived immunoassay platforms in urgent care settings.
- Cardiac Biomarker Protocols:Emergency departments are integrating troponin and BNP testing into chest pain triage workflows, creating pull-through demand for rapid-turnaround analyzers.
- Microfluidic Cartridge Economics:Closed-system consumables generate recurring revenue streams that justify upfront instrument subsidies and lock in multi-year fleet commitments.
Market Restraints
- Precursor Chemical Volatility:Reagent stability requirements for cold-chain-independent assays depend on lyophilization chemistries subject to pharmaceutical-grade raw material price swings.
- FDA Predicate Tightening:The agency's narrowed equivalency standards for 510(k) submissions are extending clearance timelines and elevating clinical trial costs for novel detection modalities.
- Central Laboratory Substitution:High-throughput core lab automation achieves cost-per-test economics that portable devices cannot match for routine screening volumes.
Strategic Opportunities
- Rural Health Network Gaps:Federally qualified health centers in the United States face CLIA personnel shortages that waived portable systems can address without laboratory technician staffing.
- Multiplexed Infectious Panels:Convergent electrochemical and optical detection architectures enable single-cartridge respiratory and sepsis pathogen identification at triage points.
- Home-Based Renal Monitoring:Medicare Advantage plans are piloting capitated reimbursement for patient-operated creatinine and electrolyte testing in chronic kidney disease populations.
Industry Challenges
- Regulatory Affairs Talent Scarcity:EU MDR technical documentation and FDA Q-Sub navigation require specialized expertise that mid-tier manufacturers struggle to recruit and retain.
- Legacy HIS Integration:Bedside analyzers must interface with proprietary electronic health record systems through fragmented HL7 and FHIR connectivity standards.
- Electrochemical Sensor Drift:Calibration stability over temperature and humidity ranges remains a field-service burden for point-of-care blood gas deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Clinical Analyzer Market |
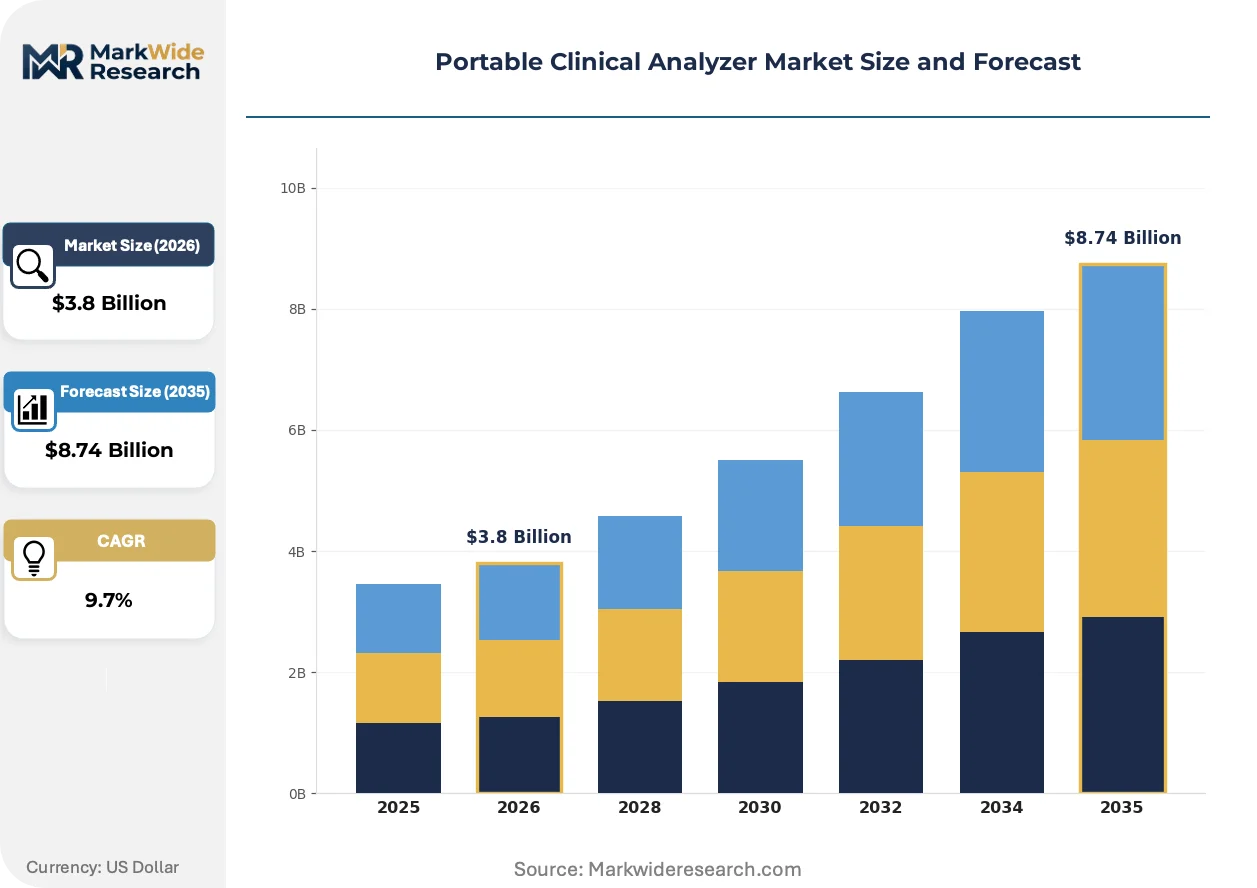
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Analyzers, Blood Gas Analyzers, Biochemistry Analyzers, Hematology Analyzers Technology: Microfluidics, Lab-on-a-Chip, Optical Sensors, Electrophoresis End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Application: Point-of-Care Testing, Disease Screening, Chronic Disease Management, Emergency Diagnostics |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Abbott Laboratories, Werfen, Instrumentation Laboratory, Haemonetics Corporation, Beckman Coulter, Thermo Fisher Scientific, Mindray Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Clinical Analyzer Market Evolving Landscape
Portable clinical analyzers are undergoing architectural transformation as manufacturers converge microfluidics, solid-state sensors, and cloud connectivity into unified platforms that compress the distance between sample acquisition and clinical decision.
Lab-on-a-chip architectures are electrifying point-of-care testing by integrating sample preparation, reaction chambers, and detection modules onto single polymer substrates. Intensive care units in Germany and Japan are deploying these platforms for intraoperative lactate and blood gas monitoring. The technology is electrifying competitive positioning by eliminating external fluidics and reducing maintenance intervals that previously required dedicated biomedical engineering support.
The EU MDR's post-market surveillance requirements are mandating systematic clinical follow-up data collection for all Class IIa and above diagnostic devices. Manufacturers must now maintain risk management files with real-world performance evidence rather than pre-market validation alone. Cardiac biomarker analyzer portfolios face the steepest compliance burden, as troponin assays require ongoing myocardial infarction outcome correlation studies across diverse European hospital networks.
Integrated delivery networks in the United States are consolidating analyzer procurement under centralized value analysis committees that evaluate total cost of ownership across reagent contracts, service agreements, and interoperability certification. This committee-based purchasing is displacing individual hospital department autonomy and compressing vendor negotiation cycles. The shift is most visible in multi-hospital systems spanning Texas, Florida, and Ohio, where standardization across fifty-plus facility footprints generates sufficient volume to demand custom assay menu configurations.
Portable Clinical Analyzer Market Segmentation
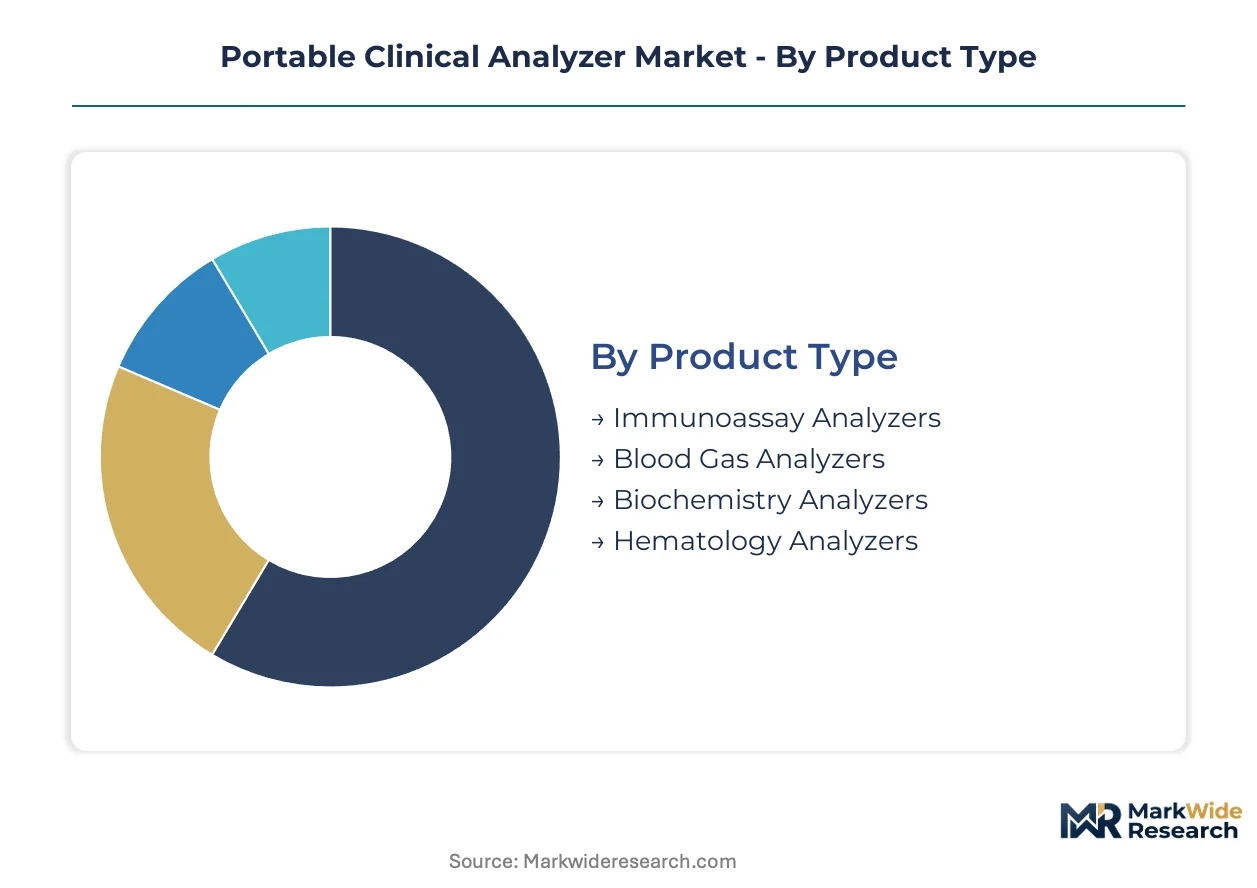
Segmentation in portable clinical analyzers reveals how technology choices, clinical settings, and application urgency dictate procurement priorities. Manufacturers configure platforms around specific workflow constraints rather than pursuing universal device architectures.
Product Type:
Standardization dominates high-volume categories while customization concentrates in specialized assay platforms.
- Immunoassay Analyzers:These platforms deploy antibody-antigen binding reactions with fluorescence or chemiluminescence detection for cardiac biomarkers and infectious disease markers. Emergency departments in the United States are standardizing troponin-capable units across chest pain triage protocols, driven by ACC/AHA guideline mandates for results within 60 minutes.
- Blood Gas Analyzers:Electrochemical sensors measure pH, pCO2, pO2, and derived parameters from arterialized capillary or whole blood samples. Intensive care units across Germany and Japan maintain the largest installed bases, where intraoperative monitoring and ventilator management protocols require continuous bedside availability.
- Biochemistry Analyzers:Photometric or potentiometric detection of electrolytes, metabolites, and enzymes supports renal and hepatic function assessment. Federally qualified health centers deploy waived systems for creatinine and glucose monitoring without laboratory technician staffing.
- Hematology Analyzers:Impedance or optical flow cytometry enumerates cellular components for anemia and infection screening. Rural clinics in Texas and Florida prioritize these for obstetric and pediatric populations lacking proximity to central laboratories.
Leading the category by volume: Blood Gas Analyzers. Expanding most quickly: Immunoassay Analyzers.
Technology:
Cost tiering separates premium microfluidic platforms from commodity electrochemical alternatives.
- Microfluidics:Laminated polymer or glass substrates manipulate sub-microliter volumes through pressure-driven or capillary flow. Abbott Laboratories and Siemens Healthineers dominate this tier with closed-cartridge systems that lock in recurring consumable revenue across integrated delivery networks.
- Lab-on-a-Chip:Monolithic integration of sample preparation, reaction, and detection functions eliminates external fluid handling. Resource-limited settings in India and sub-Saharan Africa favor these for cold-chain-independent operation and minimal maintenance requirements.
- Optical Sensors:Absorbance, reflectance, or fluorescence detection modules provide label-free or fluorophore-dependent quantification. These underpin waived immunoassay platforms in urgent care settings where instrument footprint constraints dominate procurement.
- Electrophoresis:Separation of charged molecules by molecular weight or isoelectric point supports hemoglobin variant identification and protein profiling. Specialty reference laboratories retain these for confirmatory testing outside rapid-turnaround workflows.
Commanding premium pricing: Microfluidics. Gaining share fastest: Lab-on-a-Chip.
End User:
Customer type determines regulatory pathway complexity and reimbursement mechanics.
- Hospitals:Acute care facilities deploy multi-parameter platforms across emergency departments, intensive care units, and operating suites. Value analysis committees in multi-hospital systems spanning Ohio and Florida negotiate enterprise-wide reagent contracts and service agreements.
- Clinics:Ambulatory settings prioritize CLIA-waived systems operable by non-laboratory personnel. Urgent care chains in the United States standardize on single-cartridge immunoassay platforms for respiratory and streptococcal pathogen detection.
- Home Care:Patient-operated devices for anticoagulation monitoring or chronic kidney disease management require simplified interfaces and connectivity to remote monitoring platforms. Medicare Advantage pilots in capitated reimbursement models are testing creatinine and electrolyte self-testing.
- Diagnostic Laboratories:Centralized reference sites deploy portable units for outreach specimen collection and STAT testing overflow. These operations balance throughput economics against point-of-care convenience for satellite locations.
Generating highest revenue concentration: Hospitals. Steepest expansion trajectory: Home Care.
Application:
Maturity differentiates established screening workflows from emerging chronic disease monitoring models.
- Point-of-Care Testing:Immediate-result diagnostics at the site of patient contact compress decision-to-treatment intervals. Cardiac biomarker protocols in United States emergency departments represent the most standardized implementation.
- Disease Screening:Asymptomatic population testing for infectious agents or metabolic conditions deploys portable units in mobile health units and community settings. HIV and hepatitis C rapid testing programs in federally qualified health centers exemplify this application.
- Chronic Disease Management:Longitudinal monitoring of diabetes, heart failure, and renal function requires connectivity to electronic health records and population health dashboards. Accountable care organizations in Texas pilot these for reducing emergency department utilization.
- Emergency Diagnostics:Trauma, stroke, and sepsis protocols demand multiplexed panels with results under 15 minutes. Prehospital deployment in ambulance services is expanding in European markets with established emergency medical services infrastructure.
Highest procedure volume: Point-of-Care Testing. Climbing the fastest: Chronic Disease Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device free trade zones in Shenzhen and the Research Triangle Park in North Carolina concentrate manufacturing and regulatory affairs infrastructure for portable diagnostic platforms.
United States
Emergency department standardization drives analyzer procurement across multi-hospital systems in Texas and Florida. FDA 510(k) pathway refinements for moderate-complexity devices compress clearance timelines for waived immunoassay platforms. The Research Triangle Park anchors regulatory affairs talent pools serving manufacturers navigating predicate device equivalency standards.
Germany
Intensive care unit installed bases for blood gas monitoring sustain replacement demand across university hospital networks. EU MDR technical documentation requirements force manufacturers to front-load clinical validation expenditures before European market entry. The Munich-Stuttgart corridor concentrates engineering talent for microfluidic cartridge development serving point-of-care workflows.
Japan
Aging demographics and home-based chronic disease monitoring pilots expand demand for patient-operated renal function testing. PMDA consultation pathways for in vitro diagnostics provide structured pre-market dialogue reducing regulatory uncertainty. The Kansai region around Osaka hosts precision polymer processing clusters supplying lab-on-a-chip substrate manufacturers.
China
Domestic production incentives under the 14th Five-Year Plan accelerate localization of electrochemical sensor manufacturing. NMPA innovation review pathways for breakthrough diagnostic devices offer expedited approval for multiplexed infectious disease panels. The Yangtze River Delta around Shanghai concentrates contract research organizations conducting clinical trials for portable analyzer market authorization.
India
Federally qualified health center expansion creates procurement volume for CLIA-waived biochemistry analyzers operable by non-laboratory personnel. CDSCO streamlined medical device registration for Class B and C diagnostics reduces import clearance friction for multinational manufacturers. The Bangalore-Hyderabad corridor hosts software development centers building connectivity modules for cloud-integrated point-of-care platforms.
Portable Clinical Analyzer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the portable clinical analyzer market. Siemens Healthineers and Roche Diagnostics anchor the consolidated upper tier through integrated diagnostics portfolios spanning imaging, laboratory, and point-of-care segments. Mid-tier specialists concentrate on single-parameter platforms or regional market penetration. Strategic moves center on regulatory affairs infrastructure scaling and consumable ecosystem lock-in through closed-cartridge architectures.
Within the diversified diagnostics tier, Roche Diagnostics and Siemens Healthineers exemplify conglomerate positioning through breadth across assay modalities and geographic regulatory coverage. Abbott Laboratories occupies a distinct position bridging diversified scale with focused point-of-care specialization through integrated cartridge ecosystems. These three entities anchor competitive dynamics by setting technical documentation standards and value analysis committee engagement protocols that shape procurement patterns across integrated delivery networks.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Abbott Laboratories |
| Werfen |
| Instrumentation Laboratory |
| Haemonetics Corporation |
| Beckman Coulter |
| Thermo Fisher Scientific |
| Mindray Medical |
| Others |
Value Network & Pricing Analysis
Captive cartridge manufacturing anchors both supply security and pricing power for portable clinical analyzer manufacturers, as closed-system consumable production insulates vendors from raw material volatility while locking hospital systems into multi-year reagent commitments. Abbott Laboratories and Siemens Healthineers sustain margin structures through in-house polymer substrate fabrication and lyophilization chemistry control, whereas outsourced consumable producers face compressed pricing from integrated delivery network procurement committees.
Pricing Analysis
Expedited lead-time premiums command pricing separation between spot cartridge orders and contracted fleet commitments across United States hospital systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by assay complexity and regulatory certification tier, with FDA 510(k)-cleared cardiac biomarker platforms sustaining the highest price points. Cost compression in economy-tier electrolyte testing intensifies because central laboratory automation achieves superior cost-per-test economics for routine screening volumes. Federally qualified health centers exhibit the greatest price sensitivity due to capitated reimbursement constraints, while academic medical centers prioritize assay breadth over unit cost.
Supply Chain Analysis
Refurbishment and remanufacturing flows for electrochemical sensor modules concentrate service revenue with original equipment manufacturers in Germany, Japan, and the United States. Precision polymer substrates for microfluidic cartridges draw from the Kansai region around Osaka and the Research Triangle Park in North Carolina, with lyophilized reagent chemistries resting on pharmaceutical-grade precursor supply from Swiss and German specialty chemical producers. Single-source vulnerability persists for cold-chain-independent stabilizer compounds subject to pharmaceutical-grade raw material price swings. Distribution runs through integrated delivery network value analysis committees that consolidate procurement across multi-hospital footprints in Texas, Florida, and Ohio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable clinical analyzers occupy a technology-transition phase as solid-state electrochemical sensors and cloud-integrated microfluidics displace legacy optical detection platforms requiring dedicated biomedical engineering support. This displacement accelerates procurement standardization across hospital systems seeking reduced maintenance intervals and interoperability certification.
For Market Incumbents: Anticipate margin compression from emerging lab-on-a-chip specialists by deepening backward integration into precision polymer substrate manufacturing and expanding regulatory affairs infrastructure to navigate EU MDR post-market surveillance requirements. Prioritize R&D concentration on multiplexed infectious disease panels that satisfy emergency department triage protocols and justify premium positioning against central laboratory substitution threats.
For New Entrants and Emerging Players: Launch via direct contracting with federally qualified health centers facing CLIA personnel shortages, where waived biochemistry analyzers operable by non-laboratory personnel address acute staffing gaps. Target rural health network gaps in Texas and Florida where geographic distance from central laboratories creates pull-through demand for patient-operated renal monitoring devices under Medicare Advantage capitated reimbursement pilots.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified diagnostics conglomerates seeking point-of-care technology tuck-ins to complete integrated diagnostics portfolios spanning imaging, laboratory, and bedside segments. Long-term viability hinges on consumable ecosystem lock-in through closed-cartridge architectures generating recurring revenue streams that justify upfront instrument subsidies. Monitor FDA Q-Sub consultation volume for novel detection modalities as an inflection indicator for regulatory clearance timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Front-loaded clinical validation expenditures secure European market access before predicate device tightening extends clearance timelines. |
| Closed-Cartridge Ecosystem Development | Consumable lock-in generates recurring revenue streams that justify upfront instrument subsidies across integrated delivery networks. |
| Multiplexed Assay Platform R&D | Convergent electrochemical and optical detection architectures enable single-cartridge respiratory and sepsis pathogen identification. |
| Hospital System Partnership Structuring | Value analysis committee engagement protocols shape procurement patterns across multi-hospital footprints in Texas and Florida. |
| Cloud Connectivity Module Integration | HL7 and FHIR interoperability certification satisfies electronic health record integration requirements for bedside analyzer deployments. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings in this study. Primary interviews with clinicians, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records. Bottom-up triangulation across installed base estimates and top-down validation through reagent contract value analysis anchored the market sizing framework.
Comparable-period anchoring to historical reference periods across the projection horizon calibrated the forecast framework. Segmentation dimensions modeled include product type, technology tier, end-user setting, and application urgency, with additional stratification by regulatory pathway complexity and reimbursement mechanism. CAGRs were derived through trend extrapolation adjusted for technology substitution effects and policy intervention timing. Forecast inputs incorporated CLIA waiver expansion velocity and integrated delivery network standardization patterns.
The model assumes a particular technology adoption path; alternative pathways for lab-on-a-chip architectures would alter the outlook if cold-chain-independent operation achieves cost parity with microfluidic platforms. Forecasts reflect assumptions regarding regulatory clearance timeline stability and reimbursement parity maintenance between point-of-care and central laboratory testing codes. Practitioners should monitor FDA predicate device equivalency standard evolution and EU MDR post-market surveillance enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market