
 Critical Care Equipment Market | 2026-2036
Critical Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Equipment Market Analytics
The EU Medical Device Regulation is rebalancing procurement criteria across European hospital systems, compelling manufacturers to elevate clinical evidence standards. Koninklijke Philips N.V. leverages its integrated digital health platform to sustain long-term service contracts with large hospital networks. General Electric Company anchors its position through advanced hemodynamic monitoring systems that dominate North American academic medical centers. Medtronic plc differentiates via its deep portfolio of automated infusion technologies that reduce medication errors in high-acuity settings.
Critical care equipment encompasses life-support apparatus designed for continuous physiological monitoring and therapeutic intervention in patients with acute, reversible organ dysfunction; these systems typically integrate multi-parameter sensing, alarm algorithms, and closed-loop control functions to maintain homeostasis during organ failure. Ventilators and patient monitors command the largest installed base, though automated infusion pumps capture disproportionate margin pools due to software-locked consumables and recurring safety-upgrade subscriptions. Intensive Care Units represent the dominant end-user channel, while digital technology architectures are displacing mechanical and analog platforms as hospitals prioritize remote telemetry and AI-augmented alarm management.
FDA premarket notification requirements, EU MDR conformity assessment procedures, and China's NMPA registration pathways collectively shape product development timelines and market access costs for device manufacturers. The FDA's evolving guidance on interoperable medical devices is pushing vendors toward standardized data protocols that reduce vendor lock-in. Stakeholders must monitor how regulatory divergence between the FDA's quality system regulation and the EU's post-market surveillance obligations reshapes regional competitive advantages.
Market Dynamics
Digital telemetry architectures are compressing replacement cycles for mechanical critical care platforms as hospitals prioritize remote monitoring capabilities and AI-augmented alarm management over incremental hardware upgrades.
Growth Catalysts
- EU MDR Conformity Pressure:The Medical Device Regulation's tightened clinical evidence requirements are forcing hospital procurement teams to favor established vendors with robust quality systems, consolidating purchase authority toward integrated platform suppliers.
- ICU Infrastructure Modernization:Tertiary hospitals in the United States, Germany, and China are simultaneously expanding bed capacity and upgrading monitoring density per bed, creating synchronized demand waves for multi-parameter systems.
- Closed-loop Therapeutic Control:Automated infusion technologies with software-locked safety algorithms are reducing medication error liability, pulling capital allocation toward intelligent pump platforms over conventional delivery devices.
Market Restraints
- Semiconductor Component Volatility:Specialized sensor chipsets and analog front-end integrated circuits face extended lead times from concentrated East Asian foundry capacity, constraining ventilator and monitor production schedules.
- Regulatory Divergence Friction:The FDA's quality system regulation and the EU's post-market surveillance obligations impose non-overlapping documentation burdens, inflating compliance costs for dual-territory product launches.
- Capital Equipment Substitution:Refurbished and certified pre-owned patient monitors from secondary markets are capturing budget-constrained hospital segments, compressing new equipment pricing power in mid-tier product lines.
Strategic Opportunities
- India's Underserved Tertiary Network:The country's expanding private hospital chains and government medical college hospitals present unmet demand for ventilator and hemodynamic monitoring capacity outside metropolitan corridors.
- Remote Telemetry Integration:Cloud-connected device architectures enabling centralized ICU oversight across distributed hospital networks are creating new recurring revenue streams through subscription-based alarm management services.
- FDA Interoperability Guidance:The agency's evolving standards for standardized data protocols are opening vendor-agnostic integration pathways, allowing modular specialists to penetrate previously locked hospital networks.
Industry Challenges
- Embedded Software Validation:AI-augmented alarm algorithms require extensive clinical validation against false-positive thresholds, extending development timelines and regulatory submission preparation.
- Biomedical Engineering Talent Scarcity:Hospitals face acute shortages of technicians capable of maintaining hybrid digital-mechanical platforms, forcing manufacturers to expand field service footprints and training commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Equipment Market |
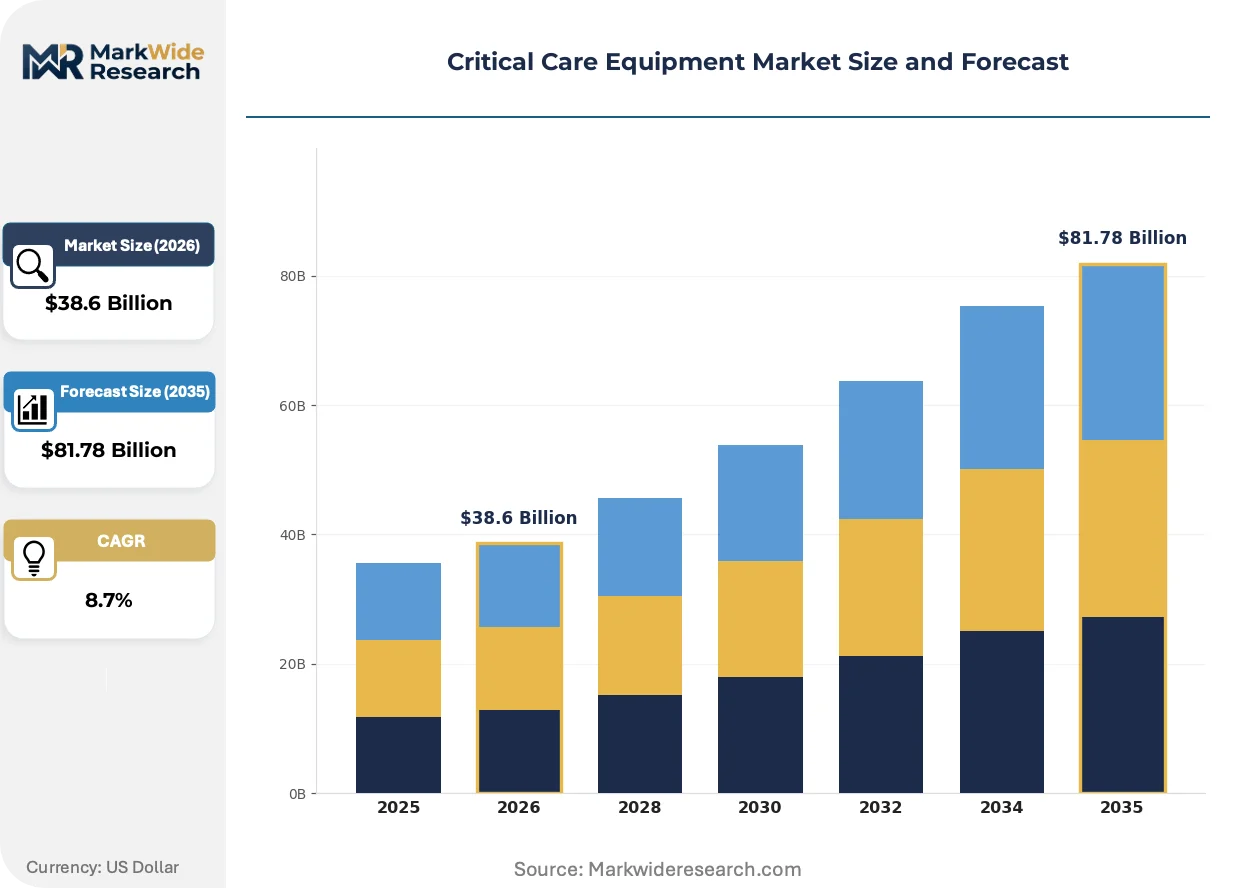
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Monitors, Infusion Pumps, Defibrillators End User: Hospitals, Emergency Clinics, Surgical Centers, Intensive Care Units Technology: Digital, Mechanical, Analog, Automated Application: Respiratory Support, Cardiac Care, Neurological Monitoring, Critical Trauma |
| Companies Covered | Koninklijke Philips N.V., General Electric Company, Medtronic plc, Drägerwerk AG & Co. KGaA, Getinge AB, B. Braun Melsungen AG, Nihon Kohden Corporation, Shenzhen Mindray Biomedical Electronics Co., Ltd., BPL Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Equipment Market Evolving Landscape
Sensor fusion architectures and edge computing capabilities are redefining how physiological data is processed at the point of care, shifting competitive advantage toward software-defined device platforms.
Multi-parameter sensing modules with integrated edge processing are consolidating discrete monitoring functions into single bedside units. Academic medical centers in Germany and the United States are deploying these platforms at accelerated refresh cycles. The technology is absorbing capital previously allocated to standalone hemodynamic, respiratory, and neurological monitoring devices.
The EU Medical Device Regulation's post-market surveillance obligations now mandate systematic clinical follow-up for high-risk devices. Manufacturers must maintain active registries and periodic safety reporting across deployed installed bases. Automated infusion systems and ventilator platforms face the steepest compliance burden, driving consolidation toward vendors with established European regulatory infrastructure.
Hospital procurement committees are unbundling after-sales service contracts from initial capital purchases, separately negotiating multi-year maintenance agreements with third-party clinical engineering firms. This disintermediation is compressing manufacturer service margins and forcing equipment vendors to compete on transparent lifecycle cost models. The pattern is most pronounced in United States health systems with centralized supply chain governance.
Critical Care Equipment Market Segmentation
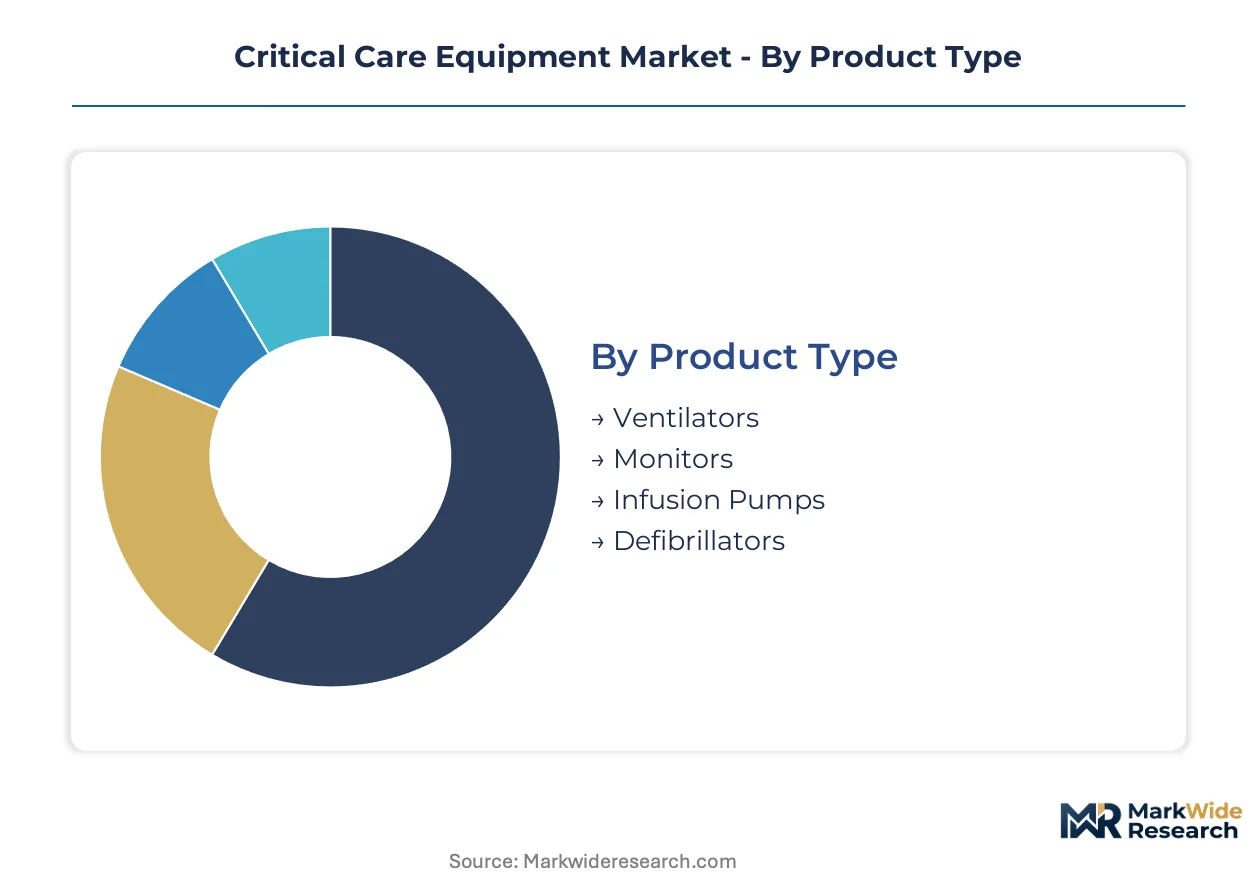
Critical care equipment segmentation reveals how procurement priorities split between high-volume mechanical platforms and premium digital systems. Understanding these divides exposes where capital budgets concentrate and which technology transitions will reshape vendor market share.
Product Type:
Ventilators and patient monitors anchor installed base volume, while infusion pumps command disproportionate margin through software-locked consumables.
- Ventilators:Life-support apparatus delivering controlled respiratory assistance through invasive and non-invasive interfaces. Tertiary hospitals in Germany and the United States are expanding procurement of these systems as ICU bed capacity rises, though semiconductor shortages from East Asian foundries constrain production schedules.
- Monitors:Multi-parameter sensing platforms integrating hemodynamic, respiratory, and neurological data streams at the bedside. Academic medical centers prioritize these for AI-augmented alarm management capabilities, compressing replacement cycles for standalone analog devices.
- Infusion Pumps:Automated delivery systems with closed-loop safety algorithms reducing medication error liability.
- Defibrillators:Emergency cardiac resuscitation devices deployed across hospital crash carts and emergency response fleets.
Today's leader: Monitors. Tomorrow's challenger: Infusion Pumps.
End User:
Procurement authority concentrates in integrated hospital networks, while specialized surgical centers seek modular, space-constrained platforms.
- Hospitals:Comprehensive medical centers with centralized capital equipment committees governing multi-year refresh cycles. These institutions in China are upgrading monitoring density per bed, creating synchronized demand waves for multi-parameter systems.
- Intensive Care Units:High-acuity wards requiring continuous physiological monitoring and therapeutic intervention capabilities. ICUs favor ventilators and patient monitors with remote telemetry integration, driving cloud-connected architecture adoption.
- Emergency Clinics:Rapid-response facilities prioritizing portable defibrillators and compact monitoring for triage throughput.
- Surgical Centers:Ambulatory facilities selecting cost-optimized mechanical platforms over premium digital alternatives.
Procurement gravity centers on Hospitals. Surgical Centers are gaining share fastest.
Technology:
Digital architectures are displacing mechanical and analog platforms as hospitals prioritize remote telemetry and AI-augmented alarm management.
- Digital:Software-defined platforms with edge computing, sensor fusion, and cloud connectivity enabling centralized ICU oversight. These systems absorb capital previously allocated to standalone devices across German and United States academic centers.
- Automated:Closed-loop therapeutic control systems with embedded safety algorithms and recurring software upgrade subscriptions.
- Mechanical:Pneumatic and electromechanical platforms without embedded software validation requirements.
- Analog:Legacy sensing and display technologies facing accelerated replacement cycles.
Digital platforms command premium positioning. Automated systems show steepest expansion trajectory.
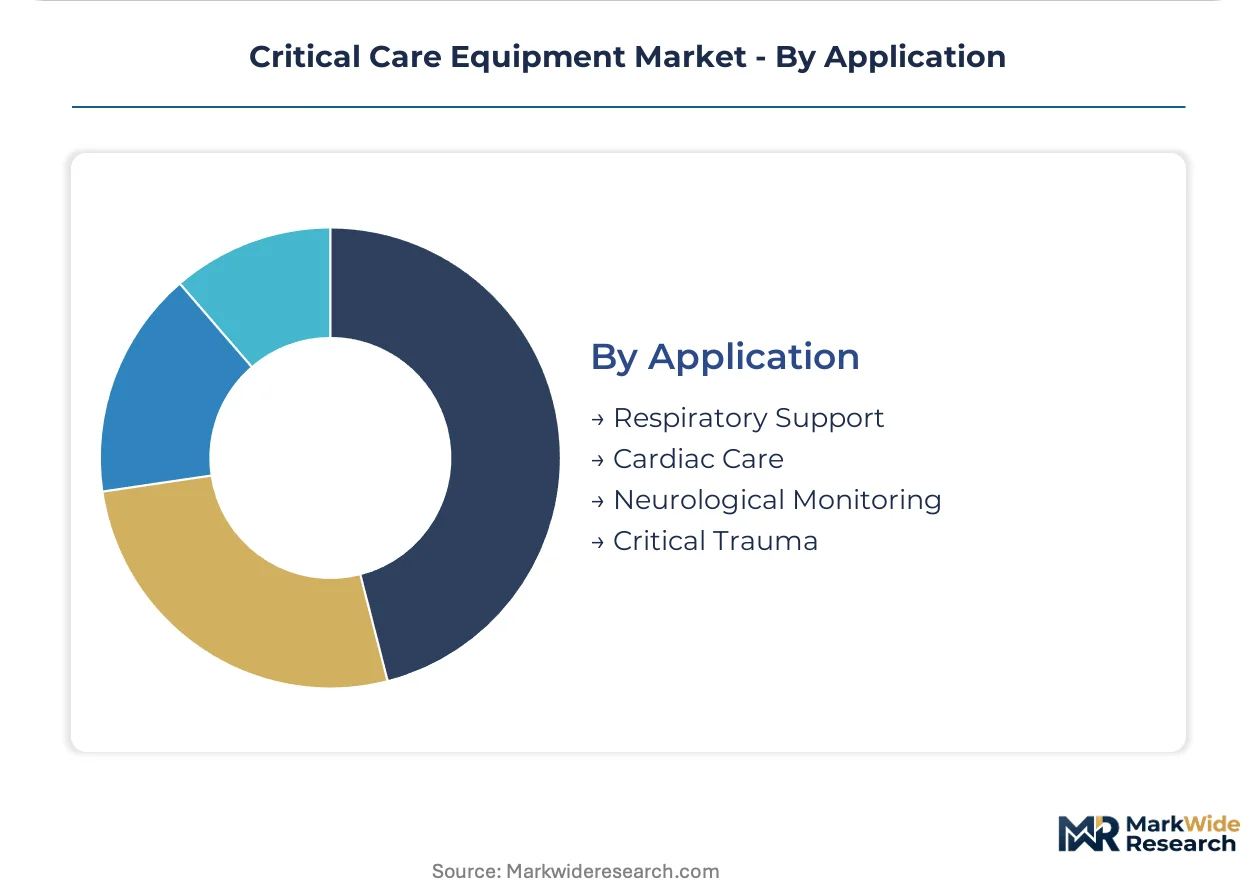
Application:
Respiratory and cardiac applications dominate capital allocation, while neurological monitoring concentrates in specialized academic centers.
- Respiratory Support:Ventilation and oxygenation management for acute reversible lung dysfunction. Demand concentrates in tertiary hospitals expanding ICU infrastructure, with EU MDR conformity pressure favoring established vendors with robust quality systems.
- Cardiac Care:Hemodynamic monitoring and emergency defibrillation for acute cardiovascular events. North American academic medical centers anchor demand for advanced monitoring systems in this category.
- Neurological Monitoring:Intracranial pressure and cerebral activity sensing for trauma and stroke patients.
- Critical Trauma:Multi-system physiological support for polytrauma patients requiring simultaneous respiratory, cardiac, and neurological intervention.
Respiratory Support leads volume. Neurological Monitoring offers highest untapped pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The critical care equipment industry traces its modern foundations to post-war European hospital systematization and North American academic medical center expansion, with Germany and the United States establishing the first standardized ICU instrumentation protocols during the 1960s.
United States
Academic medical centers in Boston and the Research Triangle are expanding multi-parameter monitoring density per ICU bed. FDA premarket notification pathways for interoperable devices are accelerating cloud-connected platform approvals. Philadelphia's hospital network cluster is consolidating procurement authority toward integrated digital health suppliers.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are synchronizing ventilator procurement with ICU capacity expansion programs. EU MDR conformity assessment procedures are compelling manufacturers to maintain active safety registries across deployed device bases. Berlin-Brandenburg's university hospital network is piloting AI-augmented alarm management systems.
China
Government medical college hospitals in the Yangtze River Delta and Pearl River Delta are upgrading monitoring infrastructure at accelerated refresh cycles. NMPA registration pathways for Class III medical devices are tightening clinical evidence requirements for high-risk therapeutic systems. Shenzhen's biomedical electronics cluster is scaling production of edge-computing patient monitors for domestic hospital networks.
India
Private hospital chains in Maharashtra and Karnataka are expanding ventilator and hemodynamic monitoring capacity outside metropolitan corridors. CDSCO medical device rules are harmonizing with international quality system standards for imported critical care platforms. Delhi-NCR's tertiary referral centers are concentrating procurement of automated infusion systems with closed-loop safety algorithms.
Japan
Metropolitan hospital systems in Tokyo and Osaka are prioritizing remote telemetry integration for centralized ICU oversight. PMDA pharmaceutical and medical device agency reviews are emphasizing post-market surveillance for software-embedded therapeutic devices. Nagoya's medical device manufacturing belt is specializing in sensor fusion architectures for multi-parameter bedside units.
Critical Care Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing models. The market structure consolidates around integrated platform suppliers with established regulatory infrastructure, while modular specialists penetrate through standardized interoperability protocols. Three archetypes dominate: diversified health technology conglomerates with service-locked revenue streams; mid-scale regional fabricators with cost-optimized mechanical platforms; and software-defined device specialists leveraging edge-computing architectures. Competitive moves center on multi-year service contract unbundling and third-party clinical engineering partnerships.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and General Electric Company exemplify the integrated platform archetype, anchoring positions through long-term hospital network relationships. Medtronic plc occupies a position within the automated therapeutic control tier, representing the specialist pathway for closed-loop safety systems. Shenzhen Mindray Biomedical Electronics Co., Ltd. sits within the scale-driven regional fabricator category, reflecting China's domestic production capabilities for digital monitoring platforms.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| General Electric Company |
| Medtronic plc |
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| B. Braun Melsungen AG |
| Nihon Kohden Corporation |
| Shenzhen Mindray Biomedical Electronics Co., Ltd. |
| BPL Medical Technologies |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-cleared and CE-marked systems creates parallel pricing tracks that source from distinct supplier ecosystems. Premium digital platforms with embedded AI algorithms command lifecycle service contracts, while mechanical alternatives face cost compression from refurbished secondary markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by clinical acuity requirements and regulatory jurisdiction. Price differentiation rests on FDA premarket notification depth, EU MDR conformity assessment rigor, and software-locked consumable attachment rates. Cost compression in mid-tier mechanical monitors intensifies because certified pre-owned equipment captures budget-constrained hospital segments. Surgical centers and emergency clinics exhibit highest price sensitivity; academic medical centers in Germany and the United States show lowest sensitivity due to bundled service contract preferences.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundry capacity for specialized sensor chipsets and analog front-end integrated circuits. Component sourcing draws from Taiwan, South Korea, and Japan for semiconductor inputs, with final assembly concentrating in China and Germany. Tariff exposure on medical-grade electronics creates margin volatility for dual-territory product launches. Distribution runs through hospital procurement committees, GPO contracts managers, and third-party clinical engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between India's cost-optimized manufacturing infrastructure and the EU's premium regulatory certification environment, where MDR compliance costs create entry barriers that protect margin pools.
For Market Incumbents: To counter modular specialists penetrating through FDA interoperability guidance, anchor hospital network relationships with transparent lifecycle cost models and expand field service footprints in tier-two Indian cities. Backward integration into sensor fusion architectures reduces semiconductor supply vulnerability. For New Entrants and Emerging Players: Enter via India's underserved tertiary corridors outside Maharashtra and Karnataka, where private hospital chains seek ventilator and hemodynamic monitoring capacity without metropolitan procurement premiums. Target automated infusion systems with closed-loop safety algorithms as the most penetrable segment, leveraging software-defined platform architectures to bypass hardware incumbent lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR post-market surveillance obligations impose registry maintenance burdens that favor vendors with established European regulatory infrastructure. Long-term viability centers on recurring revenue from software-locked consumables and subscription-based alarm management services. Watch for FDA guidance finalization on interoperable data protocols as the inflection signal for modular specialist acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Active safety registries satisfy Berlin-Brandenburg university hospital procurement criteria. |
| Hospital System Partnership | Long-term service contracts with Philadelphia's network cluster lock out modular competitors. |
| Software Companion Development | AI-augmented alarm algorithms differentiate monitors in Boston academic medical centers. |
| FDA Submission for Interoperability | Standardized data protocols open vendor-agnostic integration pathways in US health systems. |
| Reimbursement Strategy | Coverage alignment with CMS Medicare data shapes capital equipment refresh cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ICU clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers against secondary validation through FDA 510(k) filings, EU MDR notified body decisions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up installed base modeling and top-down macroeconomic factor weighting were cross-referenced for triangulation.
Segment-weighting across product type, end user, technology architecture, and application dimensions shaped volume and value outputs over the projection horizon. CAGRs were derived from historical replacement cycle analysis and forward-looking ICU infrastructure investment trajectories. Forecast inputs incorporated semiconductor lead time volatility and regulatory divergence friction between FDA quality system regulation and EU post-market surveillance obligations.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time semiconductor foundry capacity data introduce uncertainty bands around ventilator and monitor production schedule assumptions. Forecasts reflect documented assumptions regarding ICU bed expansion rates and AI algorithm validation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Middle East and Africa Critical Care Equipment (CCE) Market