
 Patient Blood Management Market | 2026-2036
Patient Blood Management Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Blood Management Market Intelligence
The European Union's Medical Device Regulation (MDR) is realigning the cost-of-entry calculus for manufacturers of blood conservation and monitoring devices. Haemonetics Corporation leverages its strong portfolio in cell salvage systems to navigate these stricter compliance requirements. Fresenius SE & Co. KGaA competes on the strength of its extensive distribution network and established presence in hospital systems across Europe and North America. Terumo Corporation differentiates through its focus on specialized hemostatic agents for surgical applications.
Patient blood management encompasses a multidisciplinary, evidence-based strategy to optimize patient outcomes by managing and preserving a patient's own blood. The approach involves specific clinical interventions like preoperative anemia correction and intraoperative coagulopathy management to reduce allogeneic blood transfusions. Blood conservation devices and cell salvage systems form the core product segments, particularly for perioperative care applications. Hemostatic agents represent a high-margin category, essential for trauma management and complex surgical procedures.
Regulatory oversight from bodies like the US Food and Drug Administration (FDA) and China's National Medical Products Administration (NMPA) governs device approval and clinical use protocols. These frameworks directly influence product development timelines and market access for new PBM technologies. The key decision for providers now centers on integrating these disparate technologies into a cohesive, system-wide clinical pathway to improve patient safety.
Market Dynamics
The central force shaping the market is the clinical and administrative mandate to integrate disparate patient blood management technologies into cohesive, system-wide programs. This shift from product-focused purchasing to evidence-based clinical pathway implementation is driven by regulatory bodies and healthcare systems seeking improved patient outcomes and cost efficiencies.
Growth Catalysts
- WHO Framework:The World Health Organization's advocacy for integrated patient blood management programs provides a strong clinical and policy-based impetus for adoption within hospital systems globally.
- Surgical Demand:The high volume of complex procedures, particularly in cardiac surgery, creates consistent demand for blood conservation devices and hemostatic agents to manage perioperative bleeding.
- United States Market Concentration:Advanced surgical infrastructure and the prevalence of integrated delivery networks in the United States create a concentrated, high-value market for PBM technologies.
Market Restraints
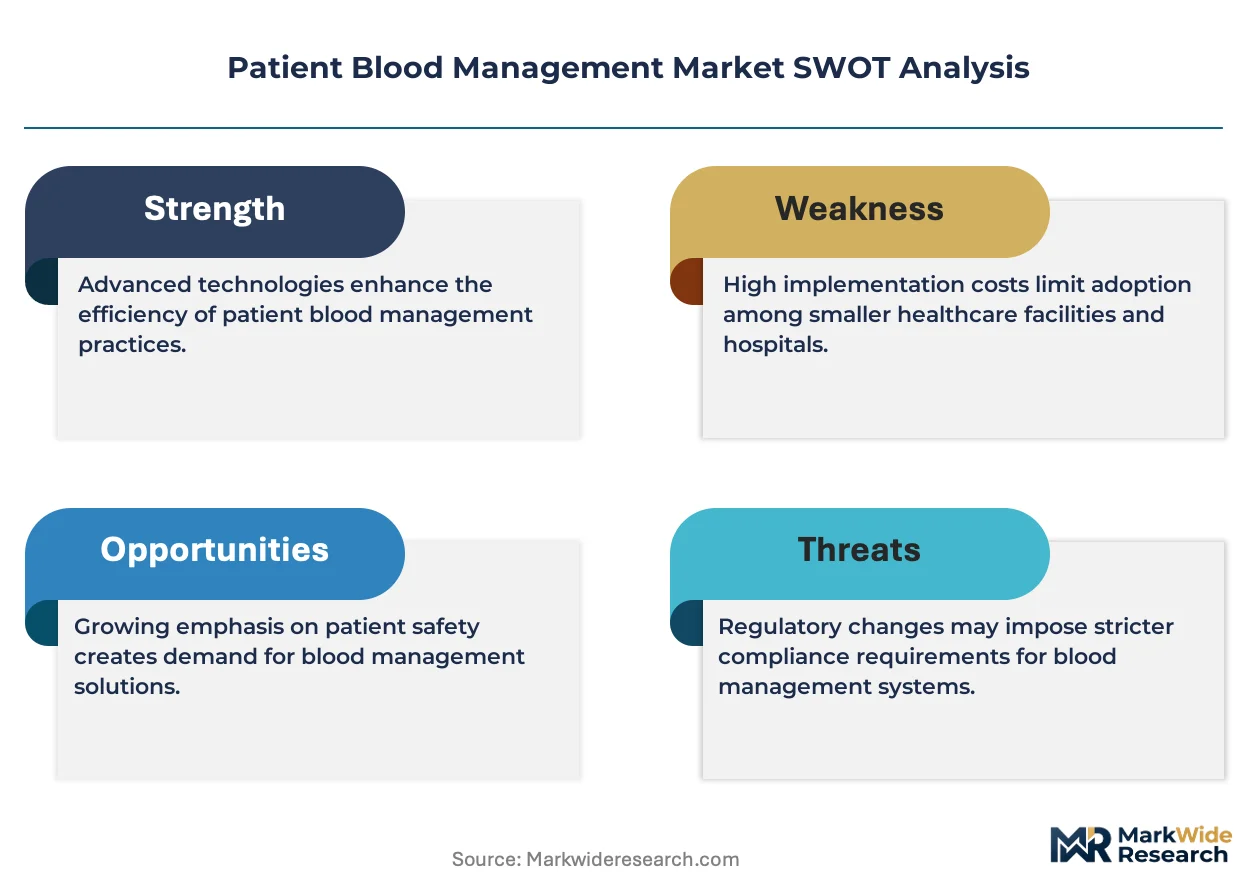
- High Capital Costs:The significant upfront investment required for advanced cell salvage systems and automated blood component separators can be a barrier for hospitals with constrained capital budgets.
- Regulatory Friction:Stricter regulations, such as the European Union's MDR, increase the cost, complexity, and timeline for device approval, delaying market access for new technologies.
- Integration Complexity:The technical difficulty of integrating various PBM technologies from different vendors into a unified clinical workflow and IT infrastructure slows down system-wide implementation.
Strategic Opportunities
- Emerging Market Penetration:There is a significant opportunity to introduce PBM programs and technologies in large healthcare systems in countries like Brazil, where surgical volumes are rising but adoption remains nascent.
- EHR Integration:Developing software that integrates PBM data directly into electronic health records (EHRs) can create clinical decision support tools, representing a high-value service opportunity.
- Oncology and Critical Care Expansion:Applying PBM principles and technologies to non-surgical fields like oncology and critical care medicine opens new clinical applications and expands the addressable patient population.
Industry Challenges
- Clinical Training Gaps:A lack of standardized training and education on comprehensive PBM protocols for surgeons, anesthesiologists, and nurses creates variability in practice and suboptimal outcomes.
- Interoperability with Legacy Systems:Ensuring new PBM devices and software can communicate effectively with existing hospital IT infrastructure and legacy medical equipment remains a persistent operational hurdle.
- Guideline Standardization:The absence of universally accepted clinical guidelines for specific PBM interventions, such as anemia management thresholds, leads to inconsistent application across different healthcare institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Blood Management Market |
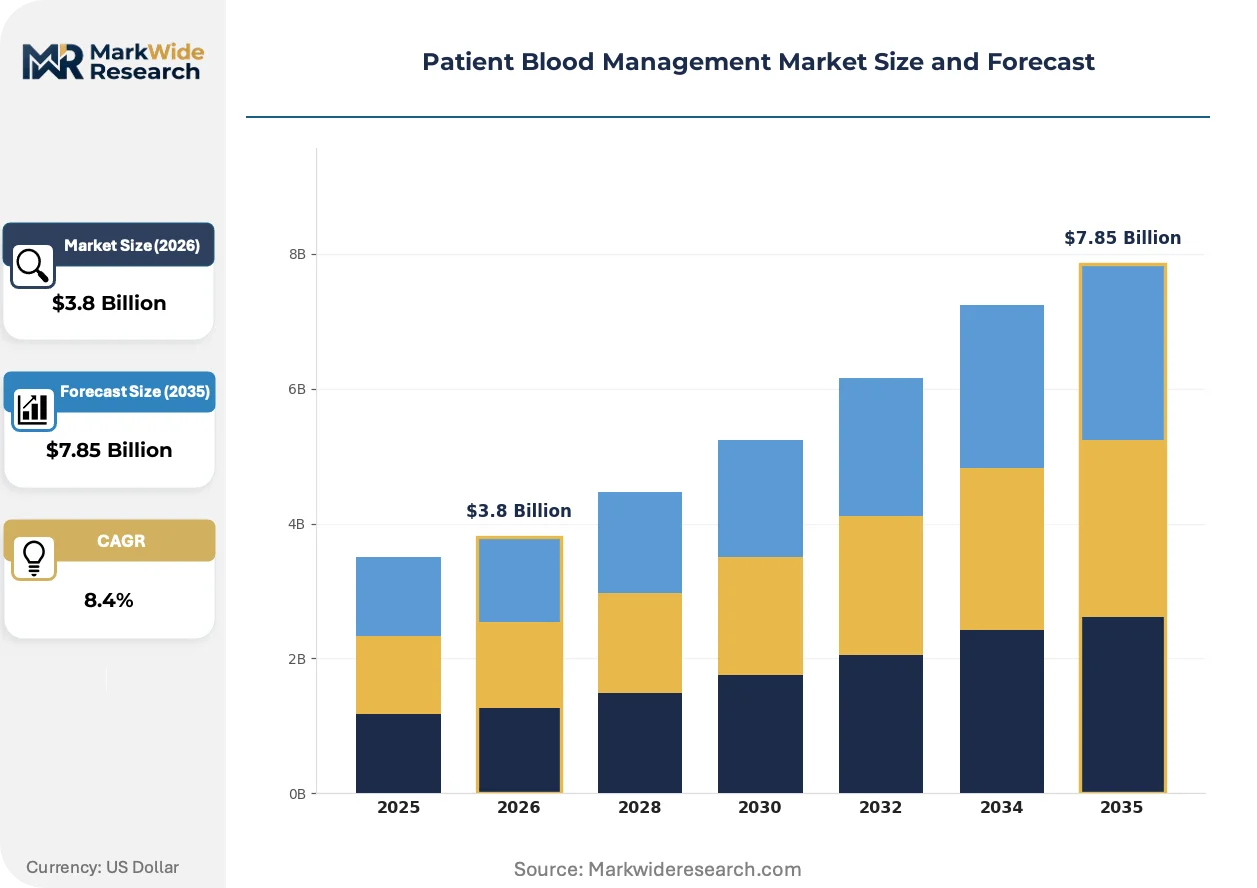
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Conservation Devices, Hemostatic Agents, Cell Salvage Systems, Blood Volume Monitors Application: Perioperative Care, Trauma Management, Critical Care, Chronic Anemia Treatment End User: Hospitals, Blood Banks, Ambulatory Surgery Centers, Research Institutes Therapy Area: Cardiac Surgery, Orthopedic Surgery, Oncology, Obstetrics & Gynecology |
| Companies Covered | Haemonetics Corporation, Fresenius SE & Co. KGaA, Terumo Corporation, Immucor, Inc., B. Braun Melsungen AG, Grifols, S.A., bioMérieux SA, Asahi Kasei Corporation, LivaNova PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Blood Management Market Strategic Shifts & Innovations
The evolution from selling individual products to providing integrated, data-driven solutions is fundamentally altering the competitive landscape. This transition prioritizes technologies that fit seamlessly into established clinical workflows and demonstrate clear value in terms of patient safety and economic benefit for hospital systems.
Point-of-care hemostasis and coagulation monitoring devices provide clinicians with real-time data to guide transfusion decisions during surgery. Anesthesiology and critical care departments are the primary adopters, using the technology to manage acute bleeding and coagulopathy. This diagnostic capability is integrating directly into the surgical workflow, reducing turnaround times associated with central lab testing and enabling faster, more precise interventions.
The European Union's Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence, risk management, and post-market surveillance. This regulation significantly increases the compliance burden and cost for manufacturers of blood conservation and monitoring systems. The device segments are most affected, forcing a re-evaluation of product portfolios and market strategies for Europe.
Hospital systems are moving away from siloed, departmental purchasing of PBM products toward consolidated, system-wide procurement. This shift in buying behavior favors vendors capable of offering a broad portfolio of technologies and support services, displacing niche, single-product suppliers. This trend is most prominent within large integrated delivery networks in the United States seeking to standardize clinical protocols and optimize supply chain costs.
Patient Blood Management Market Segmentation
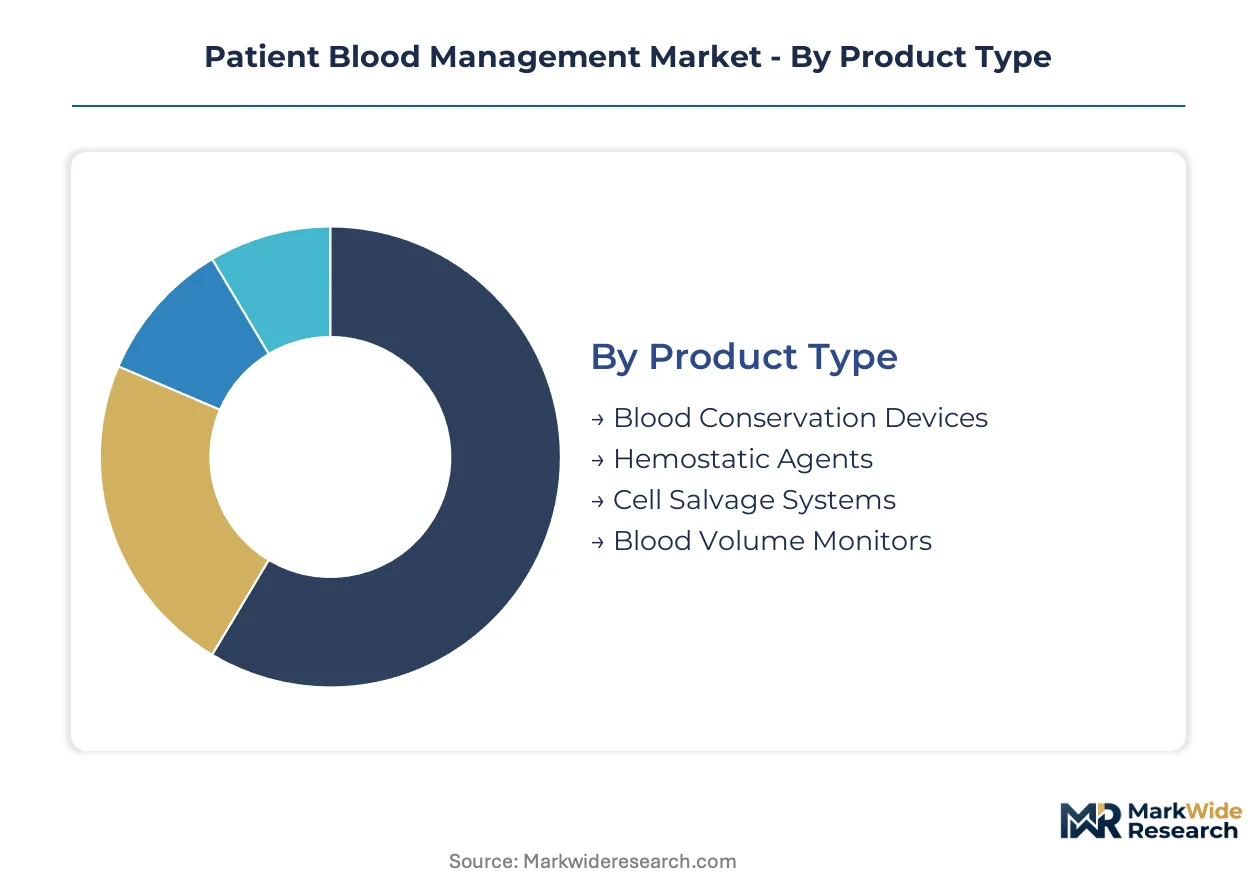
Patient blood management market segmentation provides a granular understanding of how diverse technologies and clinical strategies are integrated into healthcare systems. This breakdown illuminates the specific product types, applications, end-users, and therapy areas driving demand for blood conservation solutions.
Product Type:
The supply of patient blood management technologies concentrates around specialized devices and agents designed for specific clinical interventions.
- Cell Salvage Systems:These devices recover and reinfuse a patient's own blood during surgical procedures. Demand concentrates in high-volume surgical centers in the United States, driven by the imperative to reduce allogeneic transfusions.
- Hemostatic Agents:These specialized pharmaceuticals control bleeding by promoting coagulation at surgical sites. Demand is concentrated in complex cardiac and trauma surgeries, where rapid blood loss management is critical.
- Blood Conservation Devices:These include a range of instruments designed to minimize blood loss during medical procedures.
- Blood Volume Monitors:These systems provide real-time data on a patient's circulating blood volume, guiding fluid management decisions.
Today's leader: Cell Salvage Systems. Tomorrow's challenger: Blood Volume Monitors.
Application:
Application segments are delineated by the clinical context and patient volume where patient blood management principles are applied.
- Perioperative Care:This segment encompasses PBM interventions before, during, and after surgical procedures. Demand is high across all major surgical disciplines, driven by efforts to reduce transfusion-related complications.
- Trauma Management:PBM in trauma focuses on rapid hemorrhage control and resuscitation of critically injured patients. Demand is concentrated in emergency departments and trauma centers, where timely intervention directly impacts survival.
- Critical Care:This application involves managing blood and coagulation in intensive care unit patients with complex medical conditions.
- Chronic Anemia Treatment:PBM strategies address underlying anemia in non-surgical patients to optimize their health status before procedures or for ongoing conditions.
Perioperative Care consistently accounts for the largest share, while Trauma Management exhibits the steepest expansion trajectory.
End User:
The end-user segmentation reflects the diverse institutional settings that adopt patient blood management technologies.
- Hospitals:These institutions represent the primary end-users for comprehensive PBM programs due to their capacity for complex surgeries and critical care. Demand is system-wide, driven by mandates for improved patient safety and cost efficiency.
- Ambulatory Surgery Centers:These facilities focus on outpatient surgical procedures and increasingly adopt PBM to minimize transfusions and enhance recovery. Demand is concentrated in specialized surgical fields like orthopedics.
- Blood Banks:These facilities play a role in supporting PBM by providing blood components and specialized testing for patient management.
- Research Institutes:These organizations conduct studies on PBM efficacy and new technology development, influencing future clinical guidelines.
Hospitals remain the dominant segment, with Ambulatory Surgery Centers gaining share fastest due to procedural shifts.
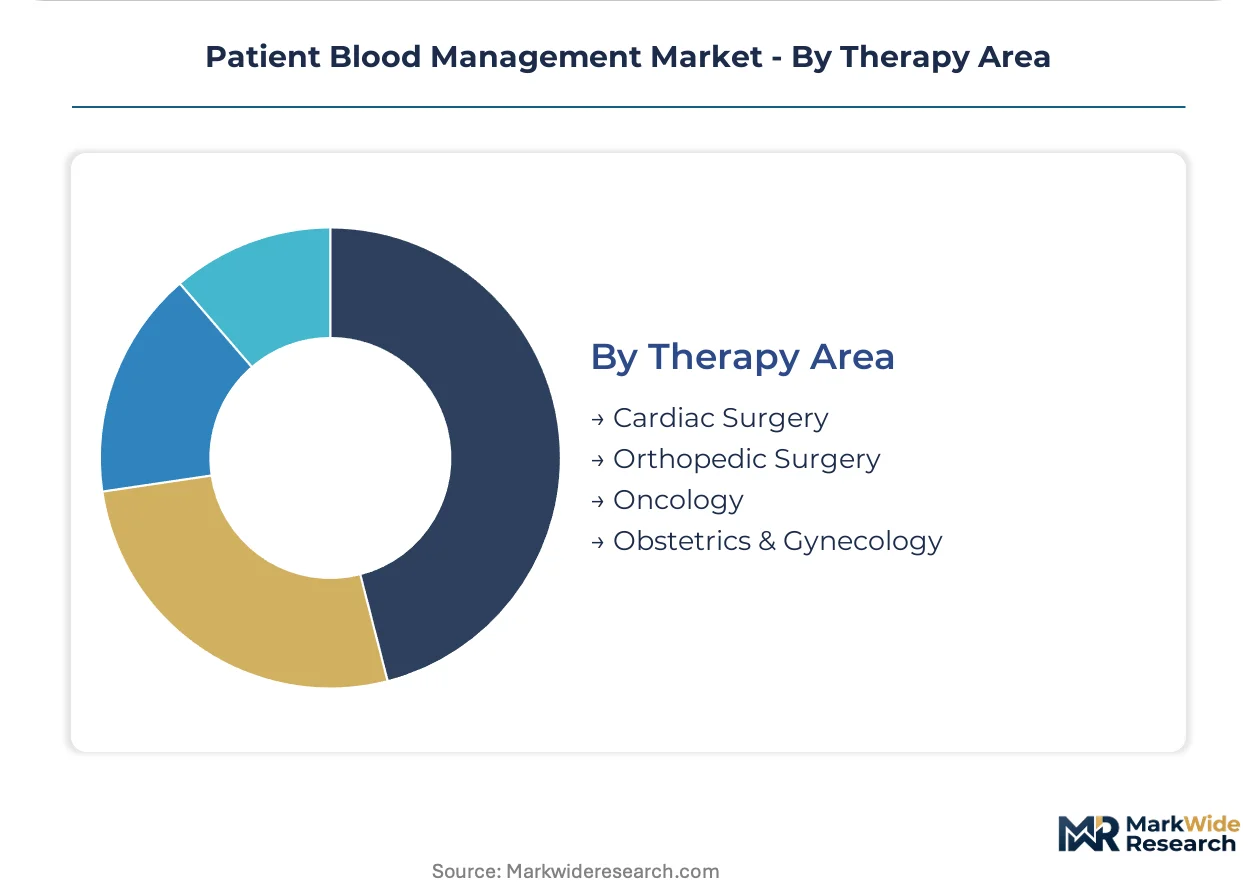
Therapy Area:
Therapy areas highlight the specific medical specialties where patient blood management interventions are most frequently applied.
- Cardiac Surgery:This area is a major consumer of PBM solutions due to the high risk of bleeding and complex blood management requirements. Demand is high for cell salvage and hemostatic agents to reduce transfusion needs.
- Oncology:PBM principles are crucial in oncology for managing anemia and coagulopathy in cancer patients undergoing chemotherapy or surgery. Demand focuses on preoperative anemia correction and minimizing transfusion exposure.
- Orthopedic Surgery:PBM techniques are applied in orthopedic procedures to manage blood loss, particularly in joint replacement surgeries.
- Obstetrics & Gynecology:This area uses PBM for managing peripartum hemorrhage and optimizing blood health in pregnant patients.
Cardiac Surgery represents a foundational segment, while Oncology is expanding most quickly as PBM principles extend beyond traditional surgical fields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Patient Blood Management market's global expansion initially scaled significantly in the United States, driven by its advanced healthcare infrastructure. Early adoption of blood conservation techniques in complex surgical settings established foundational practices. This emphasis on optimizing patient outcomes subsequently influenced clinical guidelines and technology adoption worldwide.
United States
United States demand for patient blood management solutions stems from its high volume of complex surgical procedures, particularly in cardiac surgery. The US Food and Drug Administration (FDA) rigorously governs device approval, influencing product development timelines. Integrated delivery networks in major metropolitan areas like New York City drive system-wide PBM adoption through consolidated procurement.
Germany
German hospitals prioritize patient safety and efficiency, fostering strong demand for advanced blood conservation devices and hemostatic agents. The European Union's Medical Device Regulation (MDR) impacts device market access and compliance costs for manufacturers operating in Germany. Medical technology hubs in Bavaria and Baden-Württemberg innovate in new PBM technologies and clinical protocols.
China
China's expanding healthcare infrastructure and rising surgical volumes create a substantial market for patient blood management technologies. The National Medical Products Administration (NMPA) influences product development and market entry for PBM solutions. Major urban centers like Shanghai are developing comprehensive PBM clinical pathways to standardize care.
Brazil
Brazilian healthcare systems present a significant opportunity for PBM program introduction, driven by increasing surgical volumes and a focus on cost-efficient patient care. ANVISA, Brazil's national health surveillance agency, regulates medical devices and clinical protocols for blood management. São Paulo's private hospital networks are early adopters of advanced PBM technologies to improve patient outcomes.
Japan
Japanese medical facilities focus on reducing transfusion risks due to an aging population and sophisticated healthcare technology. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals and clinical use protocols. Tokyo and Osaka-based medical centers are integrating real-time coagulation monitoring into their surgical workflows for precise interventions.
Patient Blood Management Market Key Industry Players
The competitive structure tilts toward integrated solution providers within the patient blood management market. This market comprises large diversified medical technology firms, specialized PBM device manufacturers, and pharmaceutical companies with targeted hemostatic agents. Companies pursue portfolio diversification and strategic partnerships to offer comprehensive solutions across clinical pathways.
Within the diversified medical technology archetype, Haemonetics Corporation leverages its strong portfolio in cell salvage systems to navigate stricter compliance requirements. Fresenius SE & Co. KGaA occupies a position of strength through its extensive distribution network and established presence in hospital systems. Terumo Corporation exemplifies differentiation through its focus on specialized hemostatic agents for surgical applications.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Fresenius SE & Co. KGaA |
| Terumo Corporation |
| Immucor, Inc. |
| B. Braun Melsungen AG |
| Grifols, S.A. |
| bioMérieux SA |
| Asahi Kasei Corporation |
| LivaNova PLC |
| Others |
Cost & Logistics Intelligence
A clear divergence between advanced, integrated patient blood management solutions and more transactional, single-product offerings influences both pricing models and the complexity of supply chain integration for hospital systems.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing in patient blood management. Value-based contracts and integrated solution packages are becoming the dominant pricing models for comprehensive PBM programs. Clinical evidence and seamless integration capabilities drive price differentiation, commanding a premium for advanced systems. Pricing pressure stems from group purchasing organizations (GPOs) seeking cost efficiencies, making ambulatory surgery centers highly price-sensitive buyers compared to large hospital systems prioritizing outcomes.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for advanced PBM devices. Geographic supply concentration for these technologies primarily centers in Germany, the United States, and Japan. The industry relies on specialized medical-grade plastics and high-precision sensors. Logistics chokepoints and regulatory hurdles represent a structural supply chain risk. Distribution runs through direct sales forces and specialized medical distributors, often facilitated by group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient blood management is a late-cycle quality story, driven by a demand-shift toward integrated, evidence-based solutions that demonstrably improve patient outcomes and system efficiency. This necessitates strategic adjustments across the value chain.
For Market Incumbents: Lock in existing hospital system relationships by expanding comprehensive service contracts and deeper EHR integration. Consolidate product portfolios to meet stricter EU MDR compliance requirements, mitigating the threat of market access delays. Invest in R&D for next-generation point-of-care diagnostics to counter emerging niche competitors. Leveraging strong brand equity and extensive distribution networks will reinforce market leadership.
For New Entrants and Emerging Players: Begin with niche applications in non-surgical fields like oncology and critical care, where PBM principles are less established. Target underpenetrated emerging markets such as Brazil, focusing on cost-effective, foundational PBM technologies. A go-to-market angle emphasizing rapid clinical data generation and local training programs can build early adoption. Focus on interoperability with legacy hospital IT systems to ease integration.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized PBM technology providers lack the scale for global regulatory compliance. The long-term viability of patient blood management is strong over the next decade, driven by persistent clinical mandates and cost-efficiency goals. Acquisition targets should be mid-sized firms with strong intellectual property in real-time monitoring or advanced hemostatic agents. The signal to watch is the widespread adoption of PBM-specific clinical decision support tools in major hospital networks.
| Strategic Initiative | Industry Significance |
|---|---|
| EHR Integration Development | Seamless data flow into electronic health records enhances clinical decision-making for providers. |
| EU MDR Compliance Focus | Securing CE marking ensures continued market access for devices within the European Union. |
| Emerging Market Entry | Introducing PBM programs in Brazil addresses rising surgical volumes and patient safety needs. |
| Point-of-Care Coagulation R&D | Real-time hemostasis monitoring improves patient outcomes in critical surgical settings. |
| Comprehensive PBM Program Bundling | Offering integrated solutions meets hospital demands for system-wide clinical pathways. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative data analysis — were reconciled to build a robust market perspective. Primary data collection involved extensive discussions with clinicians, hospital procurement managers, biomedical engineers, and regulatory affairs leads. Secondary validation drew from WHO guidelines, FDA filings, NMPA reports, and medical journal databases. This approach utilized both bottom-up and top-down triangulation for comprehensive market sizing and forecasting.
Historical market data was cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, therapy area, and regional adoption patterns. Compound annual growth rates were derived through a regression-based approach, incorporating expected shifts in surgical volumes and regulatory mandates. Global healthcare expenditure trends informed volume and value projections.
Several conditions sit outside the modeled scope, including unforeseen technological breakthroughs and major health crises. Forecasts reflect assumptions regarding current regulatory environments and clinical practice evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Febrile Neutropenia Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Multiple Myeloma Market
Hematology
Global Bleeding Disorders Market
Hematology
Blood Plasma Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Neutropenia Treatment Market
Hematology
At-Home Hematology Testing Market
Hematology
Sickle Cell Treatment Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Global Hematology Market