
 Global GMP Testing Service Market | 2026-2036
Global GMP Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global GMP Testing Service Market Foresight
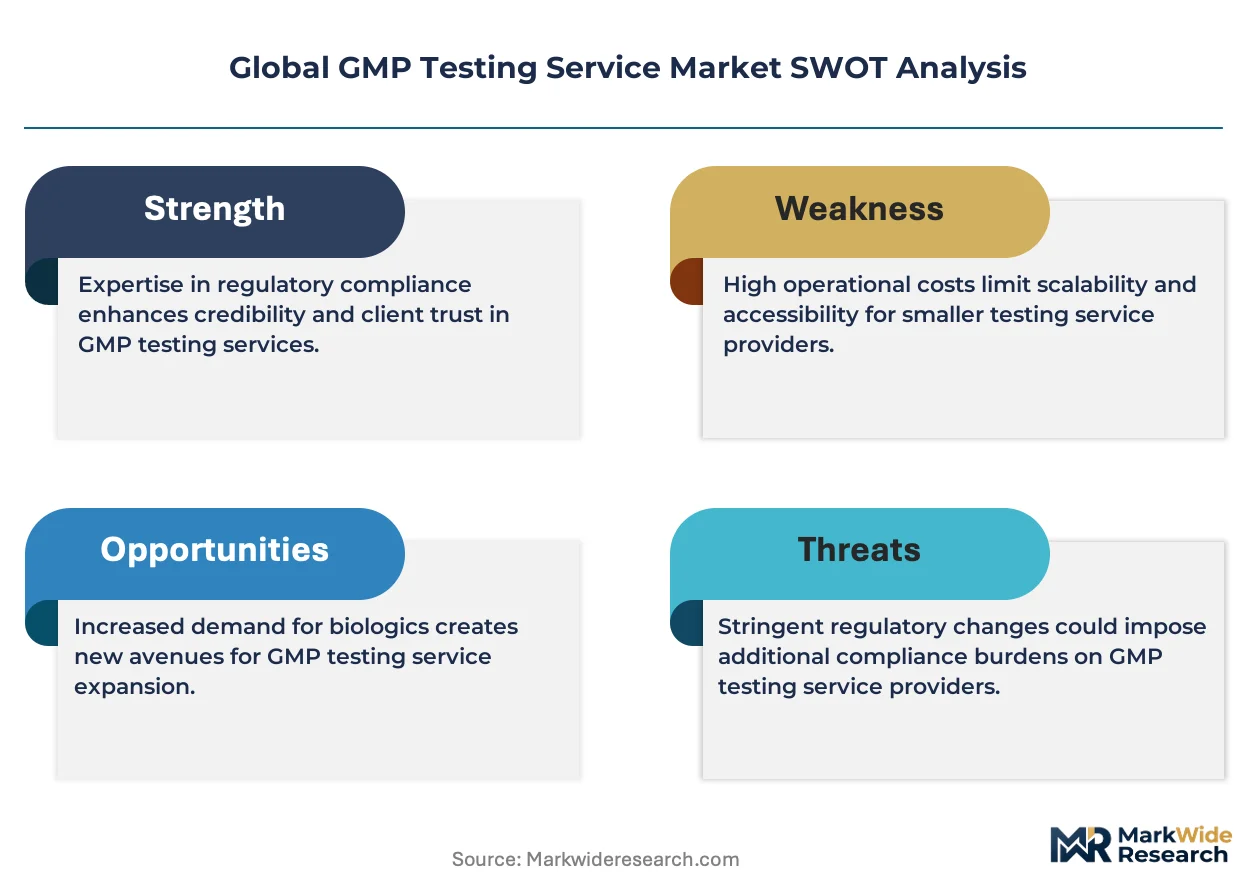
The EU Green Deal's pharmaceutical sustainability package is shifting how manufacturers validate environmental monitoring and packaging integrity across European supply chains. Eurofins Scientific leverages its distributed laboratory network to anchor microbiological testing capacity near major biologics production clusters in France and Germany. Charles River Laboratories dominates complex cell-line characterization for gene therapy clients, while WuXi AppTec competes on integrated chemistry-manufacturing-controls platforms spanning China and the United States.
GMP testing service encompasses the independent verification of pharmaceutical manufacturing processes against current Good Manufacturing Practice standards, encompassing sterility assurance, impurity profiling, and container-closure integrity evaluation using validated analytical methods such as high-performance liquid chromatography and endotoxin limulus amebocyte lysate assays. Its primary purpose is to certify that drug substances, finished products, and production environments meet regulatory specifications before batch release. Microbiological testing and stability testing command the largest revenue shares due to mandatory shelf-life protocols and sterility requirements for parenteral formulations, while chemical analysis extends the fastest growth trajectory driven by escalating impurity identification demands for oligonucleotide and peptide therapeutics. Delivery through outsourced facilities concentrates margin pools among large contract providers, whereas in-house labs retain high-volume pharmaceutical clients seeking captive turnaround control.
FDA enforcement of the Quality Management System regulation under 21 CFR Part 211 shapes United States market access by mandating documented analytical method transfers for outsourced testing. EMA's Annex 1 revision and China's NMPA alignment with ICH Q5A viral safety guidelines compel multinational sponsors to harmonize validation protocols across manufacturing sites in the European Union and Asia-Pacific. Stakeholders must monitor how emerging gene therapy modalities pressure existing GMP frameworks to accommodate novel vector characterization requirements without compromising batch release timelines.
Market Dynamics
The FDA's updated guidance on continuous manufacturing verification and the EU's Annex 1 revision for sterile drug production are tightening compliance requirements across manufacturing networks. Biologics and vaccine developers are expanding their outsourcing of stability and microbiological validation to specialized third-party laboratories, concentrating demand near clustered pharmaceutical manufacturing hubs.
Growth Catalysts
- Annex 1 Revision:The EU's updated sterile manufacturing standards mandate enhanced environmental monitoring and container-closure integrity protocols, forcing sponsors to expand third-party validation capacity.
- Biologics Outsourcing:Gene therapy developers are transferring complex cell-line characterization and viral safety testing to contract laboratories to accelerate batch release timelines.
- China NMPA Alignment:Harmonization with ICH Q5A viral safety guidelines compels multinational sponsors to standardize validation protocols across Asia-Pacific manufacturing sites.
Market Restraints
- Analytical Equipment Concentration:High-performance liquid chromatography and mass spectrometry systems rely on specialized German and Japanese component suppliers, creating input bottlenecks.
- Qualified Personnel Scarcity:The intersection of GMP compliance expertise and advanced analytical chemistry skills limits laboratory expansion in secondary markets.
- Regulatory Divergence:Differences between FDA 21 CFR Part 211 and EMA Annex 1 documentation requirements force redundant method transfers for multi-site sponsors.
Strategic Opportunities
- Continuous Manufacturing Integration:Real-time release testing platforms combining process analytical technology with validated spectroscopic methods enable faster batch certification.
- India CDSCO Expansion:The country's emerging biologics manufacturing clusters lack localized GMP testing capacity, creating white space for contract laboratory investment.
- Oligonucleotide Impurity Profiling:Synthetic RNA and peptide therapeutics require novel chromatographic methods not yet standardized in routine service portfolios.
Industry Challenges
- Gene Therapy Vector Characterization:Existing GMP frameworks lack standardized potency assays for adeno-associated viral vectors, complicating batch release.
- Laboratory Information Management System Migration:Legacy paper-based documentation systems resist integration with electronic batch records, delaying compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GMP Testing Service Market |
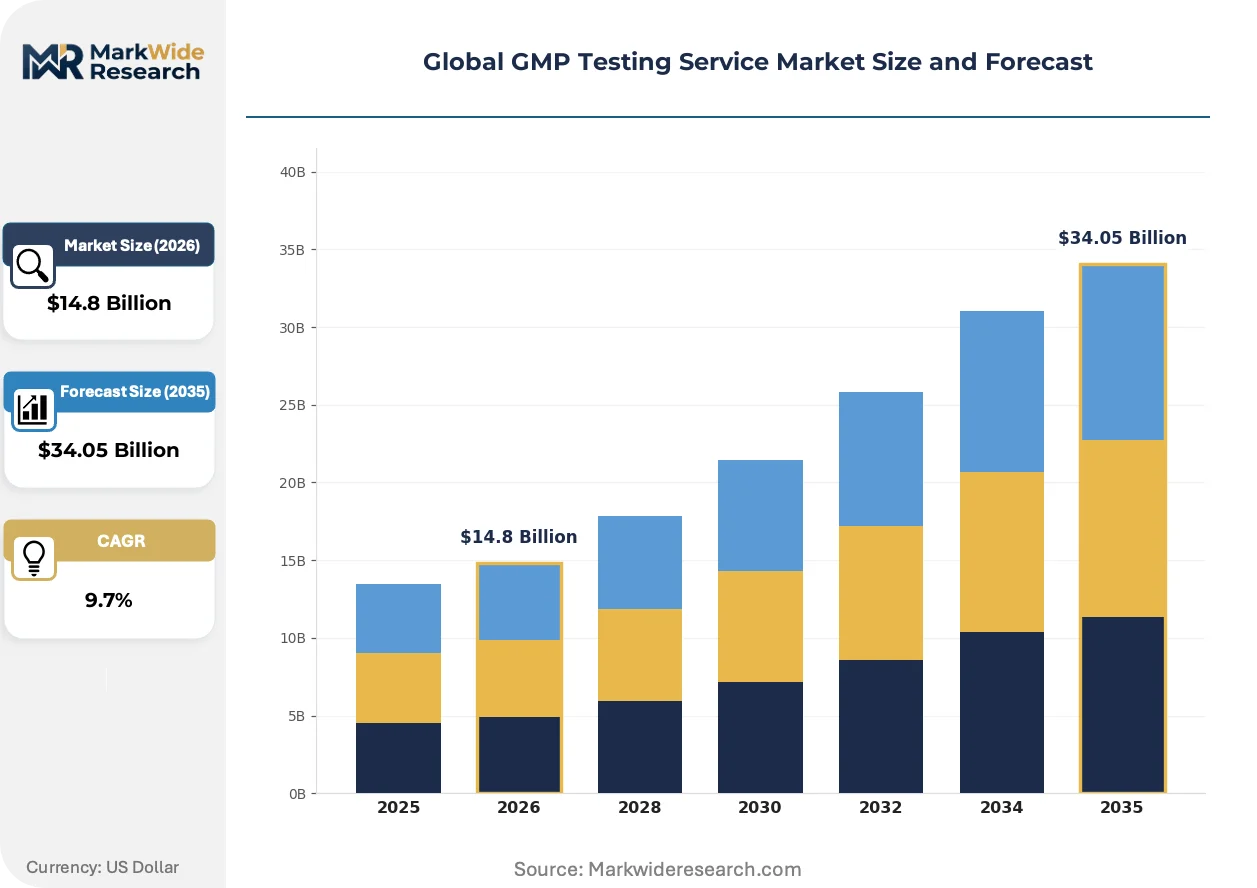
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Chemical Analysis, Stability Testing, Packaging Integrity, Raw Material Testing, Environmental Monitoring Testing Application: Pharmaceutical Formulations, Biologics & Vaccines, Medical Devices, Nutraceuticals, Cosmetic Products, Veterinary Products Client Type: Contract Research Organizations, Generic Manufacturers, Biotechnology Firms, Device Developers, Nutraceutical Companies, Cosmetic Manufacturers Delivery Mode: In-House Labs, Outsourced Facilities, Mobile Testing Units, Remote Data Access |
| Companies Covered | Eurofins Scientific, Charles River Laboratories, SGS, Intertek Group, WuXi AppTec, Sartorius AG, Pace Analytical Services, PPD Inc., Almac Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GMP Testing Service Market Shifts & Advancements
Process analytical technology and real-time release testing are compressing traditional stability study timelines. Laboratories are deploying distributed sensor networks and automated endotoxin detection to replace centralized batch sampling, while sponsors demand integrated chemistry-manufacturing-controls platforms spanning multiple regulatory jurisdictions.
Process analytical technology is decentralizing quality verification from centralized laboratories to manufacturing suites. Biologics producers are embedding at-line spectroscopic sensors for immediate impurity detection, eliminating weeks from traditional batch hold periods. This shift compresses release timelines and reduces reliance on external stability chambers for routine monitoring.
REACH and the EU Green Deal pharmaceutical sustainability package are mandating reduced solvent consumption in analytical workflows. Manufacturers must validate alternative extraction methods and demonstrate lower environmental impact across stability and microbiological testing protocols. German and French contract laboratories are retrofitting facilities to meet these requirements ahead of enforcement deadlines.
Service unbundling is fragmenting long-term testing contracts into modular, milestone-based engagements. Mid-sized biotech sponsors are purchasing sterility assurance and container-closure integrity as discrete services rather than comprehensive packages, pressuring providers to price components separately. This pattern concentrates in the United States where venture-backed developers prioritize cash-flow flexibility over volume discounts.
Global GMP Testing Service Market Segmentation
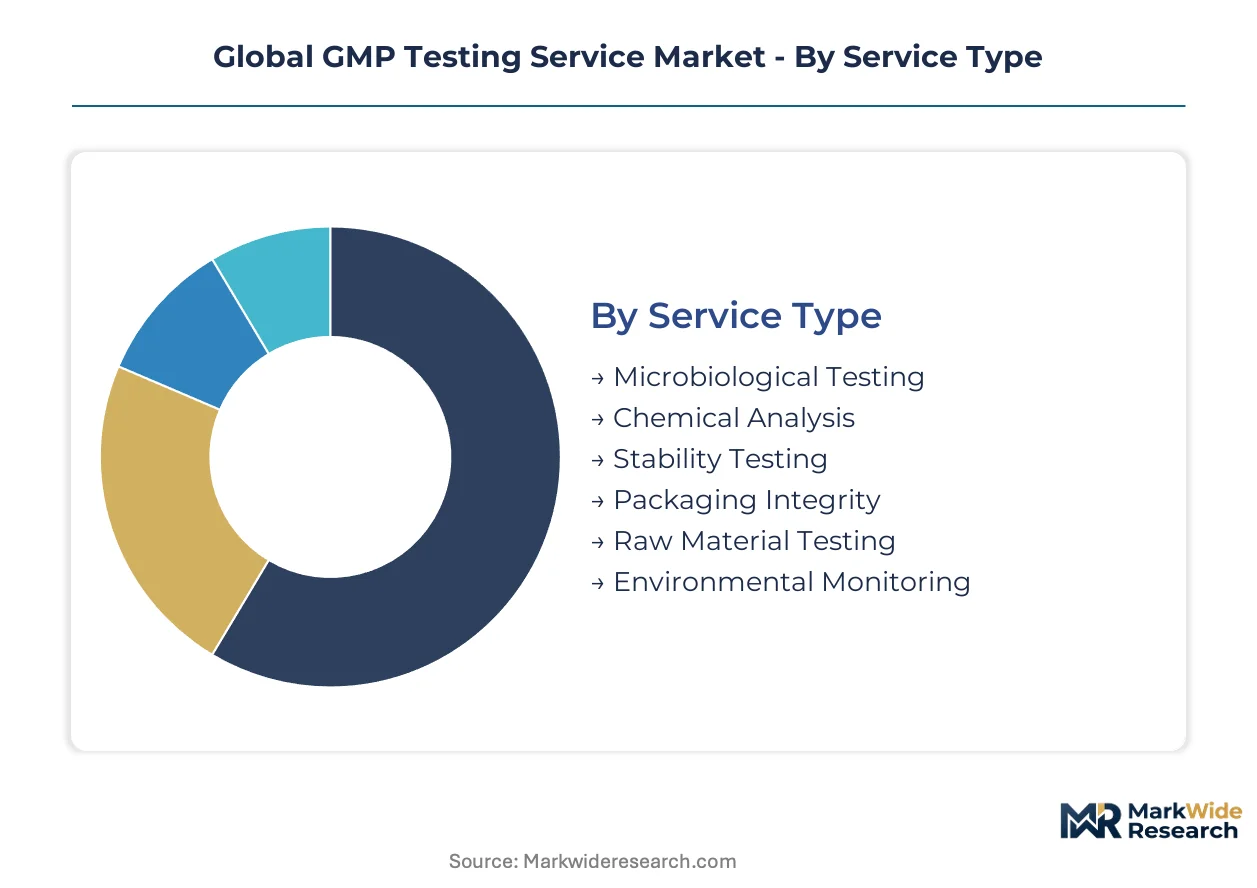
GMP testing services fragment across four intersecting dimensions that determine pricing power, regulatory exposure, and capacity planning. Service type and testing application together dictate equipment requirements and method validation complexity, while client type and delivery mode shape margin structures and contract duration.
Service Type:
Standardization dominates routine microbiological protocols, whereas chemical analysis demands bespoke method development for novel molecular entities.
- Microbiological Testing:Sterility assurance, endotoxin detection, and environmental monitoring constitute mandatory release requirements for parenteral formulations. Demand clusters near biologics manufacturing hubs in Germany, Massachusetts, and Shanghai where FDA and EMA Annex 1 enforcement is strictest.
- Chemical Analysis:Impurity profiling via high-performance liquid chromatography and mass spectrometry addresses synthetic small molecules and emerging oligonucleotide therapeutics. Sponsors in the United States and Switzerland are outsourcing complex peptide characterization to access specialized equipment and PhD-level analytical chemists.
- Stability Testing:ICH Q1A shelf-life protocols require validated storage chambers across multiple temperature and humidity conditions.
- Packaging Integrity:Container-closure validation prevents moisture and oxygen ingress for moisture-sensitive drug products.
- Raw Material Testing:Incoming qualification of APIs and excipients supports batch release documentation.
- Environmental Monitoring:Cleanroom classification and viable particle counts assure sterile manufacturing conditions.
Leading the category by volume: Microbiological Testing. Growing fastest: Chemical Analysis.
Testing Application:
Application-specific regulatory pathways create divergent validation timelines and documentation burdens across end-use sectors.
- Biologics & Vaccines:Cell-line characterization, viral safety testing per ICH Q5A, and potency assay development dominate service portfolios. China's NMPA alignment with international viral safety standards is accelerating method transfer activity between United States and Asia-Pacific manufacturing sites.
- Pharmaceutical Formulations:Small-molecule drug products require dissolution testing, uniformity of dosage units, and forced degradation studies. Generic manufacturers in India and Eastern Europe are consolidating testing contracts to secure volume pricing from contract laboratories.
- Medical Devices:Sterility and biocompatibility validation follow ISO 10993 and FDA 21 CFR Part 820 quality system regulations.
- Nutraceuticals:Dietary supplement cGMP compliance under 21 CFR Part 111 drives identity and purity verification.
- Cosmetic Products:Microbial limit testing and preservative efficacy studies support safety substantiation.
- Veterinary Products:Species-specific pharmacokinetic studies and residue testing follow CVM guidance.
Biologics & Vaccines command premium pricing. Pharmaceutical Formulations deliver highest absolute volume.
Client Type:
Client sophistication and internal capabilities determine whether testing is captive or outsourced, and how contracts are structured.
- Biotechnology Firms:Venture-backed developers lack internal analytical infrastructure and purchase modular testing services on milestone-based terms. These sponsors in Cambridge and San Francisco unbundle sterility, stability, and release testing to preserve cash runway.
- Contract Research Organizations:CROs themselves subcontract specialized GMP validation to testing-only providers with specific regulatory accreditations. European CROs near Basel and Frankfurt are building preferred supplier networks for viral safety and cell banking services.
- Generic Manufacturers:High-volume producers maintain in-house labs for routine release but outsource complex impurity identification.
- Device Developers:Combination product sponsors navigate dual pharmaceutical and device quality system requirements.
- Nutraceutical Companies:Smaller brands rely entirely on third-party laboratories for cGMP documentation.
- Cosmetic Manufacturers:Safety testing demand concentrates among mid-sized brands lacking internal microbiology capacity.
Biotechnology Firms generate fastest contract growth. Generic Manufacturers provide steadiest recurring revenue.
Delivery Mode:
Physical proximity to manufacturing sites versus remote data integration creates distinct operational models and capital intensity profiles.
- Outsourced Facilities:Dedicated contract testing laboratories near pharmaceutical clusters in New Jersey, Bavaria, and Jiangsu offer validated capacity without sponsor capital expenditure. EMA Annex 1 revisions are driving European sponsors toward localized environmental monitoring providers.
- In-House Labs:Large pharmaceutical manufacturers retain captive testing for high-frequency release decisions and intellectual property protection. Roche and Novartis maintain centralized analytical centers in Switzerland with satellite labs in the United States and Singapore.
- Mobile Testing Units:Containerized laboratories deploy to remote manufacturing sites for campaign-based production.
- Remote Data Access:Cloud-based laboratory information management systems enable real-time batch review across distributed networks.
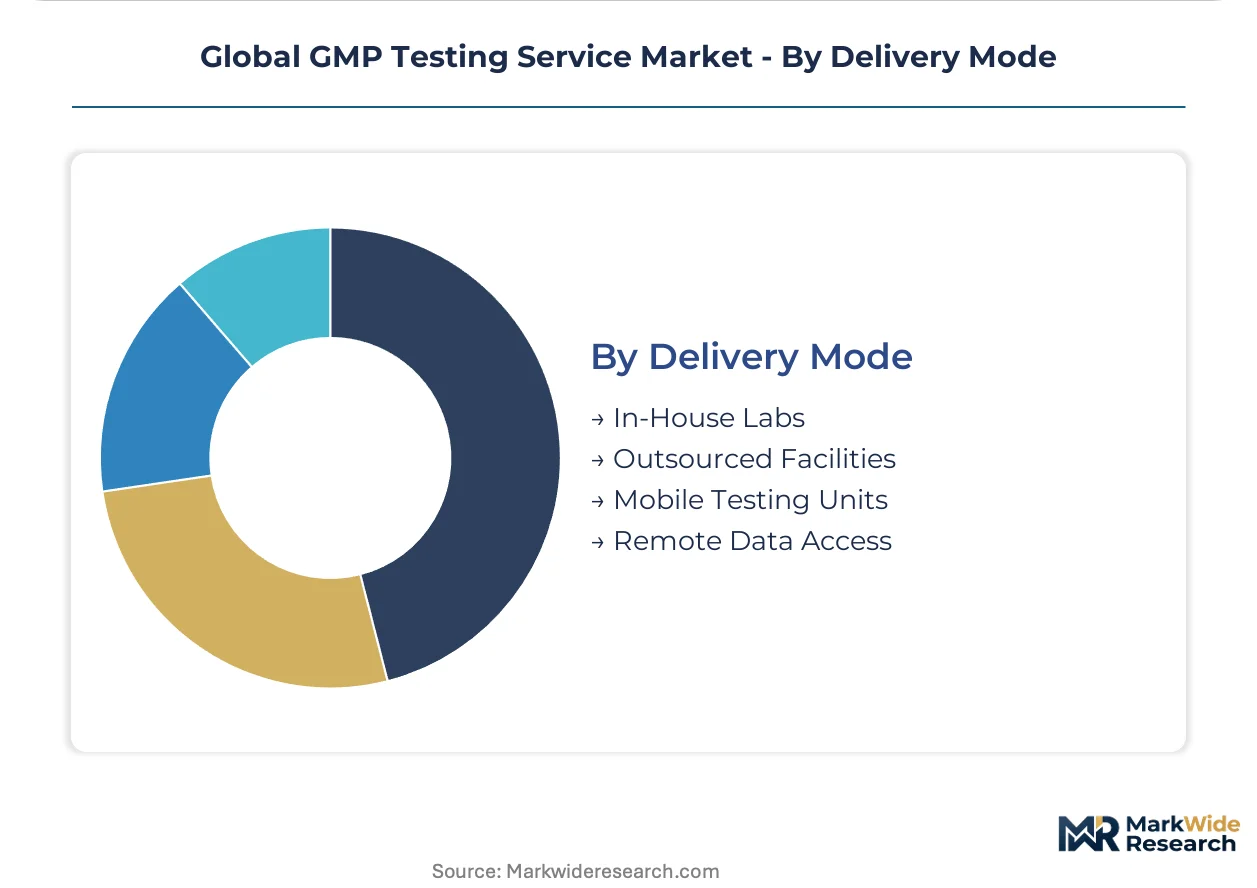
Outsourced Facilities capture majority revenue share. Remote Data Access is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in clustered pharmaceutical manufacturing hubs while consumption disperses across sponsor headquarters and regulatory filing locations. The United States, Germany, and China anchor supply capacity, with demand radiating to biotech centers in Switzerland, the United Kingdom, and Singapore.
United States
FDA enforcement of 21 CFR Part 211 compels documented analytical method transfers for outsourced testing. The Quality Management System regulation mandates electronic batch records integration, driving laboratory information management system upgrades. Massachusetts and New Jersey host dense contract laboratory networks serving Cambridge and Princeton biotech clusters.
Germany
EMA Annex 1 revisions for sterile manufacturing force enhanced environmental monitoring protocols across Bavarian production sites. The EU Green Deal pharmaceutical sustainability package mandates reduced solvent consumption in analytical workflows. Frankfurt and Munich anchor Eurofins Scientific's distributed microbiological testing capacity near major biologics facilities.
China
NMPA alignment with ICH Q5A viral safety guidelines accelerates method transfer activity between Asia-Pacific and United States manufacturing sites. Domestic biologics manufacturing expansion outpaces localized GMP testing capacity. Shanghai and Suzhou in Jiangsu Province concentrate contract laboratory investment near multinational production campuses.
Switzerland
Swissmedic maintains stringent batch release documentation requirements that favor in-house captive testing for large pharmaceutical manufacturers. Roche and Novartis operate centralized analytical centers with satellite capabilities in Singapore and the United States. Basel anchors preferred supplier networks for viral safety and cell banking services.
India
CDSCO expansion of biologics manufacturing oversight creates white space for contract laboratory investment as domestic clusters lack validated GMP testing infrastructure. Generic manufacturers consolidate testing contracts to secure volume pricing from providers. Hyderabad and Bangalore biotech corridors drive demand for modular, milestone-based testing engagements.
Global GMP Testing Service Market Competitive Landscape
The competitive structure tilts toward diversified laboratory networks with regulatory accreditation breadth. Consolidation among large contract providers concentrates margin pools, while mid-sized specialists compete on turnaround speed and therapeutic modality expertise. Three archetypes dominate: integrated chemistry-manufacturing-controls platforms, distributed microbiological testing networks, and gene therapy characterization specialists. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with capacity additions targeting manufacturing hub proximity.
Among diversified laboratory network operators, Eurofins Scientific, Charles River Laboratories, and WuXi AppTec exemplify contrasting geographic and service strategies. Eurofins anchors European capacity through France and Germany laboratory clusters. Charles River occupies a position in complex cell-line characterization for advanced therapy developers. WuXi AppTec represents integrated platform competition spanning China and United States regulatory jurisdictions.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Charles River Laboratories |
| SGS |
| Intertek Group |
| WuXi AppTec |
| Sartorius AG |
| Pace Analytical Services |
| PPD Inc. |
| Almac Group |
| Others |
Supply & Pricing Matrix
Continuous manufacturing verification is compressing batch release timelines while simultaneously concentrating equipment procurement among German and Japanese analytical instrument suppliers. This dual shift elevates capital barriers for new laboratory entrants and transfers pricing power upstream to validated component providers serving FDA and EMA-accredited facilities.
Pricing Analysis
Margin tightening in routine microbiological testing reflects service unbundling by venture-backed biotech sponsors seeking milestone-based payment flexibility. Three-tier pricing structure across premium, standard, and economy levels separates gene therapy vector characterization from routine sterility assurance from commodity environmental monitoring. Price differentiation hinges on certification tier—FDA 21 CFR Part 211 and EMA Annex 1 accreditations command 15-25% premiums—and geographic proximity to manufacturing clusters. Biotechnology firms exhibit highest price sensitivity, while large pharmaceutical manufacturers prioritize turnaround speed over per-test economics.
Supply Chain Analysis
Freight costs for temperature-controlled stability samples and hazardous reagent shipments are escalating as laboratories source specialized chromatography columns and endotoxin detection kits from concentrated suppliers. Equipment manufacturing anchors in Germany, Japan, and the United States, with high-performance liquid chromatography and mass spectrometry systems drawing from single-source component vendors. Single-source vulnerability in analytical instrument electronics creates exposure to semiconductor supply disruptions. Distribution runs through dedicated cold-chain logistics networks serving clustered pharmaceutical hubs in Massachusetts, Bavaria, and Jiangsu Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive equipment servicing and reagent manufacturing is becoming the decisive competitive lever as supply bottlenecks constrain laboratory expansion timelines.
For Market Incumbents: To counter unbundling pressure from modular testing contracts, consolidate environmental monitoring and sterility assurance into integrated platform offerings with guaranteed turnaround commitments. Deepen backward integration into chromatography consumables manufacturing to secure supply continuity during component shortages. For New Entrants and Emerging Players: Capture white space in India's CDSCO-regulated biologics corridor where domestic manufacturing expansion outpaces validated testing capacity. Target gene therapy sponsors requiring adeno-associated viral vector potency assays lacking standardized GMP frameworks. Lead with rapid method transfer capabilities and NMPA-FDA dual accreditation as entry wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified laboratory networks seeking Annex 1 compliance capabilities. Long-term viability favors mid-cap specialists with therapeutic modality depth over commodity testing volume. Watch NMPA enforcement consistency across Jiangsu and Shanghai manufacturing zones as inflection signal for Asia-Pacific method transfer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Accreditation Expansion | Dual FDA-EMA certifications unlock multinational sponsor contracts requiring harmonized validation protocols. |
| Continuous Manufacturing Integration | Real-time release testing platforms embedding process analytical technology compress traditional stability timelines. |
| Gene Therapy Characterization Capability | Adeno-associated viral vector potency assays address standardization gaps delaying batch release decisions. |
| Geographic Proximity Investment | Laboratory placement near Bavarian and Jiangsu biologics clusters reduces sample transit risk. |
| Reagent Manufacturing Backward Integration | In-house endotoxin detection kit production insulates margins from specialized supplier concentration. |
Research Methodology
FDA guidance documents, EMA Annex 1 revision drafts, and NMPA ICH Q5A alignment notices formed the secondary backbone for regulatory trajectory assessment. Primary interviews with drug development executives, regulatory affairs leads, GMP laboratory directors, and contract manufacturing organization procurement managers validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation cross-checked laboratory capacity announcements against sponsor outsourcing survey data.
Bottom-up modeling aggregated individual service line volumes across microbiological testing, chemical analysis, stability protocols, and packaging integrity applications. Segmentation dimensions included service type, testing application, client archetype, and delivery mode. CAGRs were derived from regression analysis of historical outsourcing penetration rates and projected biologics manufacturing expansion. Forecast inputs incorporated ICH guideline implementation timelines and CDSCO oversight expansion milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy regulatory standardization delays and analytical equipment supply disruptions. Forecasts reflect assumptions about NMPA enforcement consistency and EMA Annex 1 interpretation uniformity across notified bodies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pyrogen Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Thyroid Test Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Special Coagulation Tests Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Biomarker Testing Services Market
Testing Services
Drug Tester Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Testing and Analysis Services Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Global Cholesterol Testing Products and Services Market