
 Bioprocess Integrity Testing Systems Market | 2026-2036
Bioprocess Integrity Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Bioprocess Integrity Testing Systems Market Outlook
The EU Green Deal's pharmaceutical sustainability requirements is rebalancing capital allocation toward closed-system integrity testing infrastructure. Merck Millipore leverages its filtration heritage to dominate membrane integrity tester supply chains. Sartorius Group anchors European demand through localized manufacturing and service networks. Thermo Fisher Scientific competes on analytical instrumentation integration with bioprocess workflows.
Bioprocess integrity testing systems comprise instruments and consumables that verify sterile barrier performance in biopharmaceutical manufacturing, typically employing pressure decay or bubble point methods to detect membrane breaches below micron-scale thresholds. These systems ensure compliance with sterility assurance levels mandated for parenteral drug production. Membrane integrity testers command the largest installed base among product categories, while microbial detectors represent the fastest-expanding segment as real-time contamination monitoring displaces traditional culture methods. Pharmaceutical manufacturing applications generate the highest absolute demand, though contract manufacturing organizations are emerging as a concentrated growth channel for outsourced validation services.
The FDA enforces sterility testing requirements under 21 CFR 211, while the EMA's Annex 1 revision mandates continuous process verification for aseptic operations. ISO 13408 standards for aseptic processing of health care products further constrain equipment qualification protocols across jurisdictions. Stakeholders must weigh automated optical density platforms against established pressure-based methods as regulatory expectations for data integrity and electronic records intensify.
Market Dynamics
Automated membrane integrity testing is compressing validation timelines as biologics manufacturers confront sterility assurance mandates from the FDA and EMA simultaneously. This technological shift is redistributing capital toward closed-system platforms capable of continuous process verification.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guidelines mandate automated testing protocols for aseptic operations, compelling facility upgrades across European pharmaceutical manufacturing sites.
- Biologics Pipeline Expansion:Cell and gene therapy manufacturers require enhanced sterility assurance levels, driving demand for membrane integrity testers capable of detecting sub-micron breaches.
- Real-time Microbial Detection:Optical density platforms are displacing traditional culture methods, enabling contamination monitoring that reduces batch release timelines from weeks to hours.
Market Restraints
- Capital Intensity:Automated integrity testing platforms require substantial upfront investment, constraining adoption among mid-sized contract manufacturing organizations with limited capital expenditure budgets.
- Consumables Dependency:Proprietary membrane cartridges and calibration standards tie users to single-source supply chains, creating cost volatility when suppliers consolidate production in specific regions.
- Technical Limitation:Pressure decay methods struggle with detection sensitivity for novel biologic formulations with high viscosity, forcing reliance on slower bubble point alternatives.
Strategic Opportunities
- Contract Manufacturing Channel:Outsourced validation services represent concentrated growth potential as pharmaceutical companies divest in-house testing capabilities to specialized service providers.
- EU Green Deal Alignment:Sustainability mandates for pharmaceutical manufacturing create demand for closed-system integrity testers that eliminate open-container sampling and reduce waste generation.
- Single-Use Technology Convergence:Integration of disposable bioreactors with inline integrity testing enables continuous verification without cleaning validation requirements.
Industry Challenges
- Skill Specialization Gap:Automated platforms require operators trained in both bioprocess engineering and analytical instrumentation, a combination scarce in existing workforce pipelines.
- Legacy System Integration:Newer optical density platforms face compatibility friction with established manufacturing execution systems and electronic batch records infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioprocess Integrity Testing Systems Market |
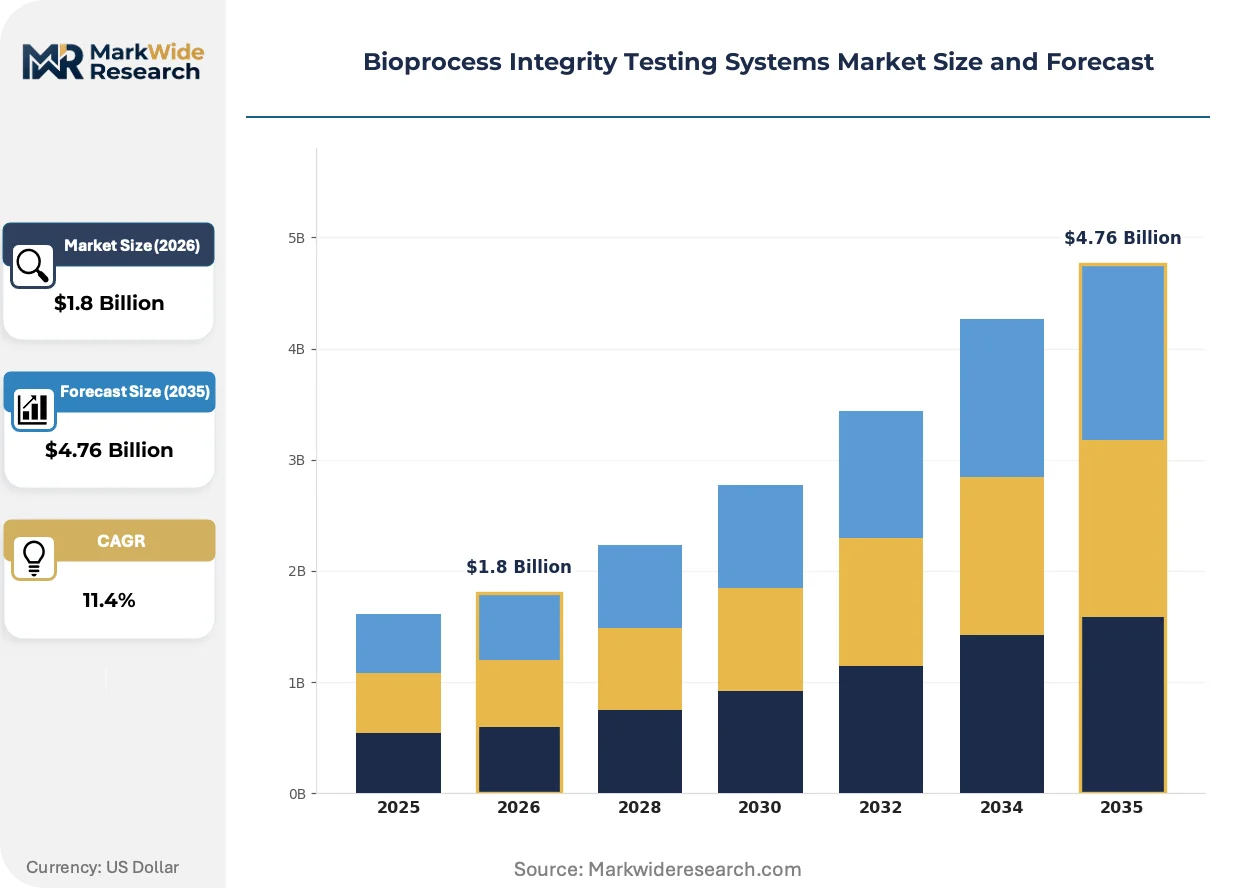
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Integrity Testers, Microbial Detectors, Consumables, Filtration Systems Application: Pharmaceutical Manufacturing, Biologics Production, Quality Control, Research & Development Technology: Pressure Decay, Ultrafiltration, Bubble Point, Optical Density End User: Biotechnology Companies, Contract Manufacturing Organizations, Academic Institutions, Pharmaceutical Firms |
| Companies Covered | Merck Millipore, Pall Corporation, Eurofins Scientific, Sartorius Group, Thermo Fisher Scientific, Cytiva, Parker Hannifin Corporation, Meissner Filtration Products, Charles River Laboratories International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioprocess Integrity Testing Systems Market Strategic Shifts
Digitalization of sterility assurance is compressing the gap between manufacturing and quality control functions. Three interconnected developments are reshaping how membrane integrity gets verified and documented across biopharmaceutical operations.
Laser-based particle counters paired with machine learning algorithms are automating defect classification in membrane filtration systems. Contract manufacturing organizations in the United States are adopting these platforms fastest, driven by FDA quality-by-design enforcement. This automation is compressing the validation workforce requirements while elevating data integrity standards for electronic records submission.
REACH chemical safety regulations in Europe are restricting certain membrane polymer chemistries used in legacy integrity testing consumables. Manufacturers must reformulate cartridge materials to maintain compliance without compromising bubble point specifications. Pharmaceutical producers in Germany and Switzerland are responding by qualifying alternative fluoropolymer membranes ahead of sunset dates for restricted substances.
Service-based pricing models are displacing capital purchase arrangements for high-throughput integrity testing systems. Biologics manufacturers now lease automated platforms with bundled validation support, transferring obsolescence risk to equipment vendors. This shift is most pronounced among emerging biotechnology companies in Massachusetts and California that prioritize operational flexibility over asset ownership.
Bioprocess Integrity Testing Systems Market Segmentation
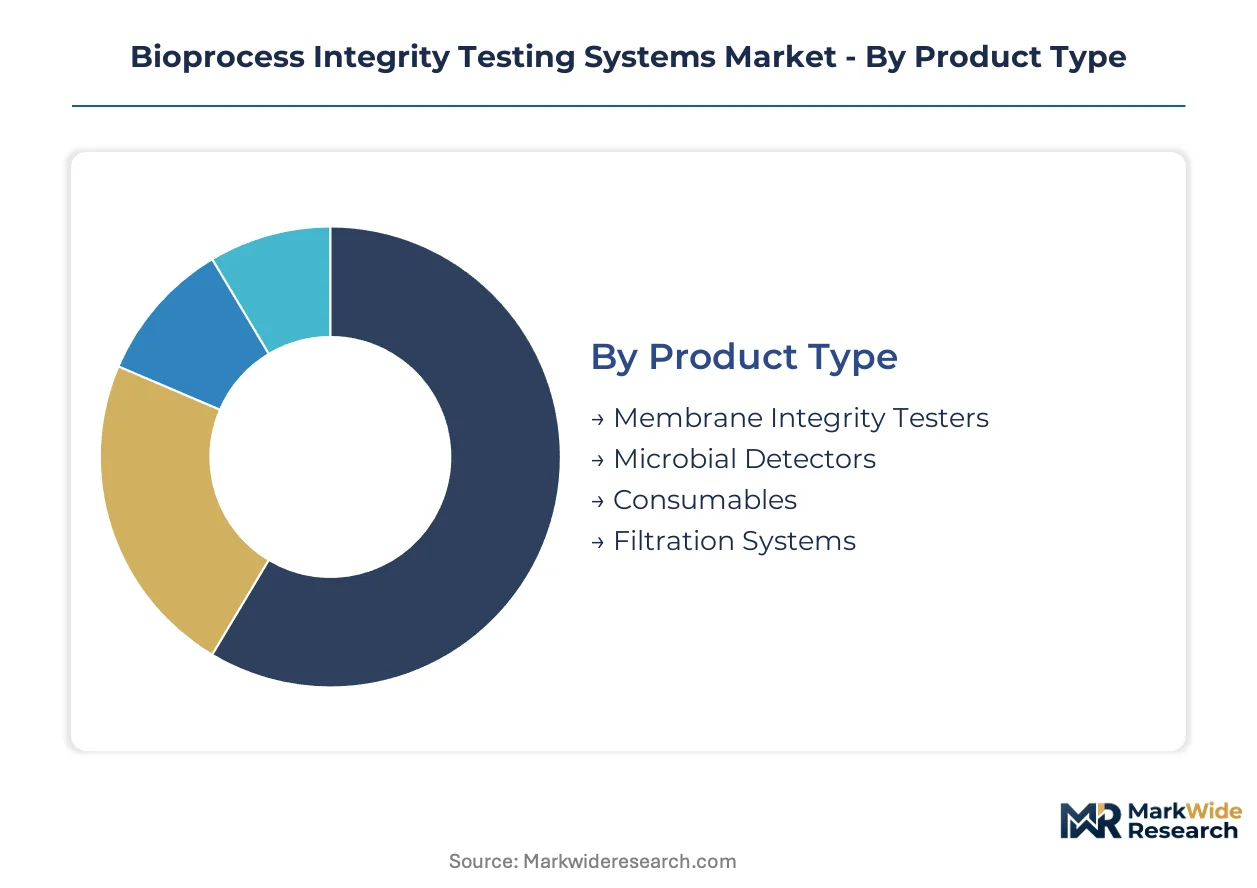
Segmentation in bioprocess integrity testing systems reveals how capital allocation splits across equipment platforms versus recurring consumables, and how regulatory pressure concentrates demand in specific end-use channels. Understanding these partitions clarifies where upgrade cycles and margin pressure intersect.
Product Type:
Equipment replacement cycles in this market accelerate when regulatory mandates force validation protocol upgrades, creating distinct timing patterns across capital goods versus disposable categories.
- Membrane Integrity Testers:These automated platforms employ pressure decay or bubble point methods to verify sterile barrier performance in filtration assemblies. Pharmaceutical manufacturers in Germany and Switzerland are prioritizing these systems to meet EMA Annex 1 requirements for continuous process verification.
- Microbial Detectors:Real-time optical density platforms detect contamination without culture-based delays. Cell and gene therapy producers in Massachusetts and California are adopting these fastest to compress batch release timelines from weeks to hours.
- Consumables:Proprietary membrane cartridges and calibration standards generate recurring revenue tied to installed equipment bases.
- Filtration Systems:Integrated hardware combining integrity testing with bioprocess filtration operations.
Membrane integrity testers sit at the top of the volume ranking, with microbial detectors climbing the fastest.
Application:
Cost tier differentiation separates high-volume commercial manufacturing from lower-throughput development environments, with validation requirements scaling proportionally.
- Pharmaceutical Manufacturing:Commercial-scale parenteral drug production demands continuous integrity verification under FDA 21 CFR 211 and EMA sterile manufacturing guidelines. Facilities in Ireland and Singapore are consolidating testing operations to capture economies of scale.
- Biologics Production:Cell and gene therapy manufacturing requires enhanced sterility assurance for sensitive living products. CDMOs in North Carolina and the Netherlands are building dedicated suites with inline testing capability.
- Quality Control:Release testing and environmental monitoring applications support batch certification.
- Research & Development:Early-stage process development employs lower-throughput integrity verification methods.
Pharmaceutical manufacturing commands the largest absolute spend, while biologics production is expanding most quickly.
Technology:
Technology maturity curves separate established pressure-based methods from emerging optical platforms, with detection sensitivity and speed driving substitution patterns.
- Pressure Decay:Standard automated method measuring pressure loss across membranes over defined intervals. Legacy installations across Midwestern US pharmaceutical corridors rely on this approach for validated stability.
- Bubble Point:Manual or semi-automated technique determining the pressure at which gas displaces liquid from membrane pores. High-viscosity biologic formulations in Swiss and German facilities still require this slower alternative.
- Ultrafiltration:Tangential flow filtration with integrated integrity monitoring for concentration and diafiltration operations.
- Optical Density:Machine learning-enhanced platforms automating microbial detection without destructive sampling. Adoption concentrates among emerging biotechnology companies seeking FDA quality-by-design alignment.
Pressure decay holds the broadest installed base, with optical density gaining share fastest.
End User:
Customer type determines procurement sophistication, with large pharmaceutical firms leveraging volume leverage against emerging biotechnology companies prioritizing operational flexibility.
- Biotechnology Companies:Emerging and mid-cap firms developing novel therapeutics, often lacking in-house validation infrastructure. Massachusetts and California clusters increasingly favor service-based pricing models transferring obsolescence risk to vendors.
- Contract Manufacturing Organizations:Specialized providers offering outsourced integrity testing and validation services. CDMOs in Pennsylvania and Bavaria are capturing divested capabilities from pharmaceutical firms seeking capital efficiency.
- Pharmaceutical Firms:Established manufacturers with integrated quality control operations and regulatory compliance expertise.
- Academic Institutions:Research-focused users with limited throughput requirements and budget constraints.
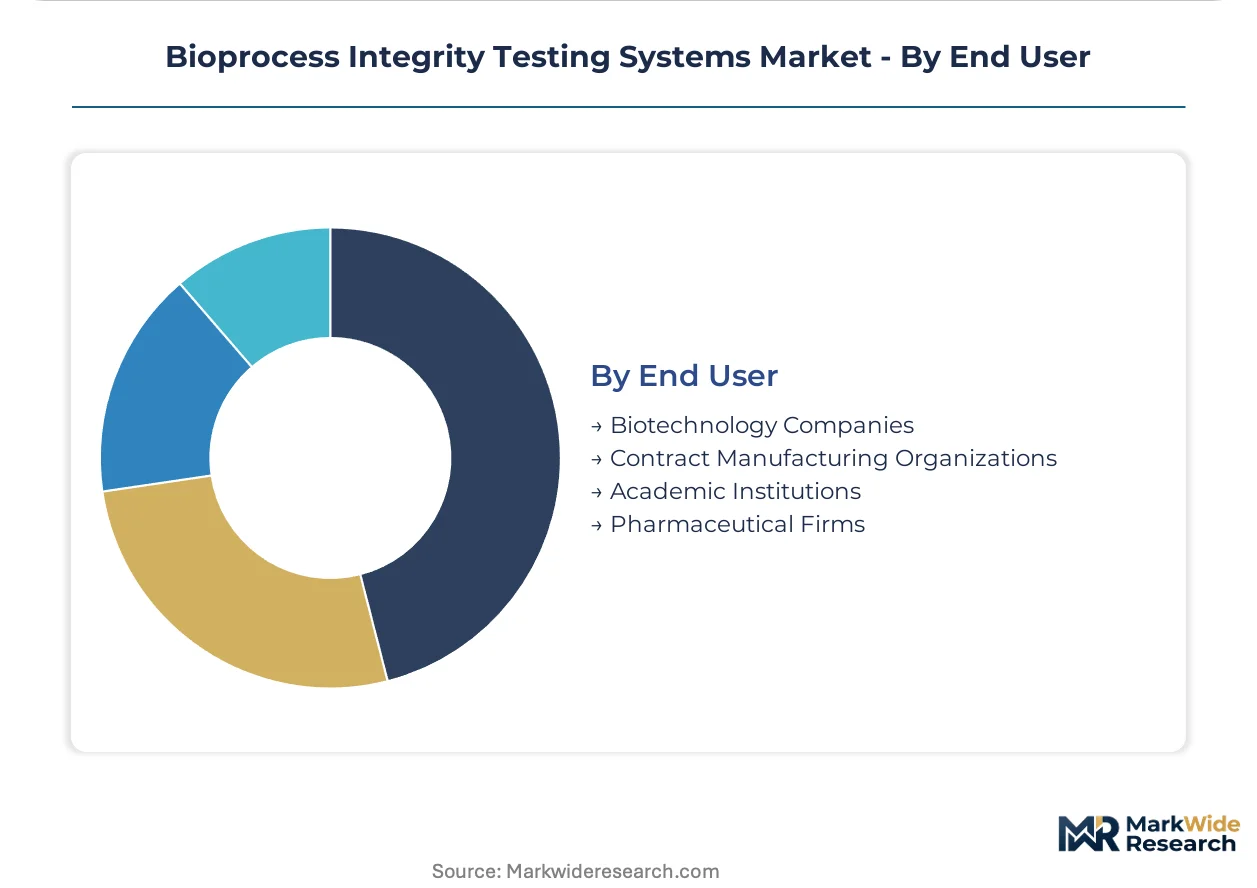
Pharmaceutical firms represent the largest customer segment, with contract manufacturing organizations expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocess integrity testing systems originated from German filtration engineering traditions in the 1980s, later scaling through Swiss pharmaceutical manufacturing clusters and Massachusetts biotechnology corridors. The technology diffused through FDA-regulated facilities in the United States and EMA-governed sites across Europe before establishing production footholds in Asia-Pacific contract manufacturing hubs.
United States
Massachusetts and California biotechnology clusters drive demand for automated membrane integrity platforms that compress batch release timelines. FDA enforcement of 21 CFR 211 sterility requirements under quality-by-design frameworks compels facility upgrades across the Northeast corridor. North Carolina's contract manufacturing corridor is consolidating testing operations to capture economies of scale from pharmaceutical outsourcing trends.
Germany
Rhineland and Bavarian pharmaceutical manufacturing sites prioritize continuous process verification systems under EMA Annex 1 sterile manufacturing mandates. REACH chemical safety regulations restrict legacy membrane polymer chemistries, forcing reformulation of cartridge materials ahead of sunset dates. Hamburg-based filtration specialists are qualifying alternative fluoropolymer membranes to maintain bubble point specifications.
Switzerland
Basel and Zurich biologics producers require enhanced sterility assurance for high-viscosity therapeutic formulations that challenge pressure decay detection sensitivity. Swissmedic regulations align with EMA Annex 1 while maintaining distinct qualification protocols for aseptic processing. The country's precision engineering heritage supports localized manufacturing of optical density platforms with machine learning integration.
Ireland
Dublin and Cork pharmaceutical manufacturing hubs concentrate large-scale parenteral drug production serving European and North American markets. EMA sterile manufacturing guidelines drive automated testing protocol adoption across facilities owned by multinational pharmaceutical firms. The country's contract manufacturing sector is expanding dedicated suites with inline integrity testing capability.
Singapore
Biologics manufacturing investments from global pharmaceutical firms create demand for closed-system integrity testers that eliminate open-container sampling. The country's national pharmaceutical regulator enforces alignment with FDA and EMA sterility assurance standards for export-oriented production. Tuas biomedical manufacturing precinct is attracting contract manufacturing organizations seeking Asian hub status with integrated validation services.
Bioprocess Integrity Testing Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth, with automated optical density platforms commanding pricing separation from pressure decay equipment. The vendor base stratifies between diversified analytical instrumentation conglomerates and specialized filtration technology houses. Three archetypes dominate: diversified life science conglomerates with bioprocess workflow integration, filtration heritage specialists with membrane cartridge supply chains, and analytical instrumentation providers with quality control automation. Consolidation pressure is intensifying through strategic partnerships between equipment vendors and contract manufacturing organizations, while technology licensing agreements accelerate platform interoperability with manufacturing execution systems.
Within the filtration heritage tier, Merck Millipore and Pall Corporation exemplify archetypes built on membrane cartridge supply chains that generate recurring consumables revenue. Sartorius Group occupies a position representing European-centered manufacturing and service network density. These three entities anchor competitive positioning through geographic proximity to German and Swiss pharmaceutical manufacturing clusters, with their GmbH and AG structures reflecting long-standing continental European industrial organization traditions.
| Leading Market Players |
|---|
| Merck Millipore |
| Pall Corporation |
| Eurofins Scientific |
| Sartorius Group |
| Thermo Fisher Scientific |
| Cytiva |
| Parker Hannifin Corporation |
| Meissner Filtration Products |
| Charles River Laboratories International |
| Others |
Value Chain & Pricing Dynamics
Automated optical density platforms and legacy pressure decay systems occupy divergent value tiers that reshape procurement patterns across biopharmaceutical manufacturing. Equipment vendors in Germany and Switzerland command premium positioning through EMA Annex 1 compliance certification, while mid-tier suppliers in the United States compete on bundled validation service contracts that transfer obsolescence risk from biotechnology companies.
Pricing Analysis
Service-based leasing arrangements with embedded validation support dominate capital allocation decisions among emerging biotechnology companies in Massachusetts and California. Price differentiation separates FDA-validated optical density platforms from semi-automated bubble point alternatives, with certification tier and after-sales service bundling as primary drivers. Cost compression in mid-tier membrane integrity testers intensifies as contract manufacturing organizations consolidate purchasing volumes. Small-scale academic institutions exhibit highest price sensitivity, while commercial pharmaceutical manufacturers prioritize compliance assurance over unit economics.
Supply Chain Analysis
Refurbishment flows for membrane integrity testing equipment concentrate in German and Swiss service hubs that extend asset lifecycles for European pharmaceutical manufacturers. Proprietary membrane cartridges draw from fluoropolymer resin supply chains anchored in Germany, Japan, and the United States. Single-source dependency on specialized calibration standards creates vulnerability when suppliers consolidate regional production. Distribution runs through authorized service networks rather than direct equipment sales, with contract manufacturing organizations in Ireland and Singapore emerging as consolidated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as sterility assurance mandates from FDA and EMA simultaneously elevate specifications for automated testing platforms. Demand is concentrating in premium-tier equipment capable of continuous process verification.
For Market Incumbents: Anchor defensive positioning through backward integration into fluoropolymer membrane manufacturing and captive calibration standard production. Threats from machine learning-enhanced optical density platforms require counterinvestment in software-defined detection algorithms. Certification maintenance under evolving EMA Annex 1 interpretations demands dedicated regulatory affairs capacity in Basel and Frankfurt corridors. For New Entrants and Emerging Players: The mid-tier pricing gap between premium optical density systems and economy pressure decay units creates white-space opportunity in service-based validation outsourcing. Contract manufacturing organizations in North Carolina and the Netherlands represent the most penetrable channel. A go-to-market angle emphasizing EU Green Deal alignment through closed-system waste reduction protocols differentiates against established filtration heritage vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary consumables supply chains generate recurring revenue streams tethered to installed equipment bases. Long-term viability favors vendors with integrated membrane cartridge manufacturing and software analytics capabilities. Acquisition target archetypes include specialized microbial detection platform developers with FDA quality-by-design alignment. Practitioners should monitor EMA Annex 1 enforcement intensity across German and Irish manufacturing sites as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | EMA Annex 1 alignment secures access to European pharmaceutical manufacturing procurement. |
| Consumables Supply Chain Integration | Backward control over fluoropolymer membrane production captures recurring revenue from installed bases. |
| Service-Based Pricing Transition | Leasing models with bundled validation transfer obsolescence risk from Massachusetts biotechnology clusters. |
| Machine Learning Platform Development | Optical density automation reduces batch release timelines for cell and gene therapy manufacturers. |
| Contract Manufacturing Partnership | CDMO alliances in Ireland and Singapore consolidate outsourced validation demand channels. |
Study Parameters
Bottom-up biologics production modeling reconciled against top-down filtration equipment supply tracking forms the analytical core of this study. Primary interviews with bioprocess engineering directors, regulatory affairs specialists at EMA-notified bodies, contract manufacturing procurement leads, and quality control automation managers combined with secondary validation from FDA 21 CFR 211 guidance documents, EMA Annex 1 revision texts, ISO 13408 aseptic processing standards, and pharmaceutical capital expenditure disclosures. Triangulation between demand-side facility upgrade pipelines and supply-side equipment shipment data ensures cross-verification.
Historical trendline analysis of membrane integrity tester installations and microbial detector adoptions established baseline penetration rates across the projection horizon. Segmentation modeling incorporated product type, application tier, technology maturity curve, and end-user procurement sophistication dimensions. CAGRs were derived from regression analysis of capital expenditure patterns correlated with regulatory enforcement intensity. Industry-specific forecast inputs included biologics pipeline advancement rates and EMA inspection frequency data.
Caveats apply where REACH chemical safety regulation amendments or sudden fluoropolymer supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding sustained FDA quality-by-design enforcement and stable EMA Annex 1 interpretation. Practitioners should monitor real-time microbial detection technology substitution rates and contract manufacturing organization consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Vitamin D Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Zika Virus Testing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Apoptosis Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Global Newborn Screening Market