
 Global Laboratory Proficiency Testing Market | 2026-2036
Global Laboratory Proficiency Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Proficiency Testing Market Foresight
The direct-to-laboratory digital channel is narrowing as proficiency testing providers consolidate portal access and subscription models. Bio-Rad Laboratories leverages its diagnostic reagent installed base to bundle quality assurance services. LGC Limited anchors its position through UKAS-accredited reference materials that lock in recurring external quality assurance contracts. Randox Laboratories competes on customized panel density across clinical chemistry and immunoassay segments.
Laboratory proficiency testing comprises the organized evaluation of analytical performance through inter-laboratory comparison using blinded samples with assigned reference values, typically requiring coefficient of variation thresholds below 5% for quantitative methods. The practice verifies measurement accuracy for patient safety, regulatory compliance, and international trade acceptance. Clinical diagnostics applications generate the deepest margin pools due to mandatory participation structures tied to reimbursement eligibility. Microbiological testing exhibits the fastest expansion trajectory as food safety evaluation protocols tighten under Codex Alimentarius-aligned national standards. Chemical analysis retains volume leadership in environmental monitoring applications where EPA and MEE discharge regulations mandate periodic verification.
FDA oversight of laboratory-developed tests and EMA In Vitro Diagnostic Regulation implementation compel diagnostic laboratories to document ongoing analytical performance through accredited proficiency schemes. ISO/IEC 17043, ILAC G13, and CLSI GP27-A frameworks define operational benchmarks that determine market access for commercial providers. Stakeholders must monitor evolving mutual recognition arrangements between accreditation bodies as these agreements determine which proficiency certificates satisfy cross-border regulatory submissions.
Market Dynamics
ISO/IEC 17043 accreditation requirements are compressing service delivery timelines while digital platform integration reshapes how laboratories consume external quality assurance. This dual pressure is forcing proficiency testing providers to consolidate portal infrastructure and automate result reporting workflows.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Diagnostic laboratories across Europe must document ongoing analytical performance through accredited proficiency schemes, creating mandatory participation structures.
- Food safety protocols:Codex Alimentarius-aligned national standards are tightening microbiological testing requirements, expanding panel demand for pathogen detection verification.
- Centralized healthcare procurement:The United States, Germany, and China mandate proficiency participation as a condition of reimbursement eligibility, locking in recurring revenue streams.
Market Restraints
- Reference material supply concentration:Certified reference material production concentrates among UKAS-accredited suppliers, creating single-source dependencies for quantitative method validation.
- Accreditation body mutual recognition gaps:Cross-border certificate acceptance remains uneven between ILAC signatories, forcing duplicate scheme participation for multinational laboratory networks.
- Legacy LIS integration costs:Connecting digital proficiency platforms to existing laboratory information systems requires substantial middleware investment and validation timelines.
Strategic Opportunities
- Environmental monitoring expansion:EPA and MEE discharge regulations mandate periodic chemical analysis verification, opening volume leadership positions in water and soil testing panels.
- Point-of-care device validation:FDA oversight of laboratory-developed tests creates demand for decentralized testing quality assurance beyond traditional central laboratory structures.
- Multi-analyte panel customization:Clinical chemistry and immunoassay segments seek denser customized panels that reduce per-test costs while maintaining analytical rigor.
Industry Challenges
- Statistical competency gaps:Coefficient of variation threshold interpretation and z-score calculation expertise remains scarce among mid-sized laboratory technical staff.
- Blinded sample logistics complexity:Maintaining sample integrity across temperature-controlled distribution networks while preserving analyte stability strains operational infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Proficiency Testing Market |
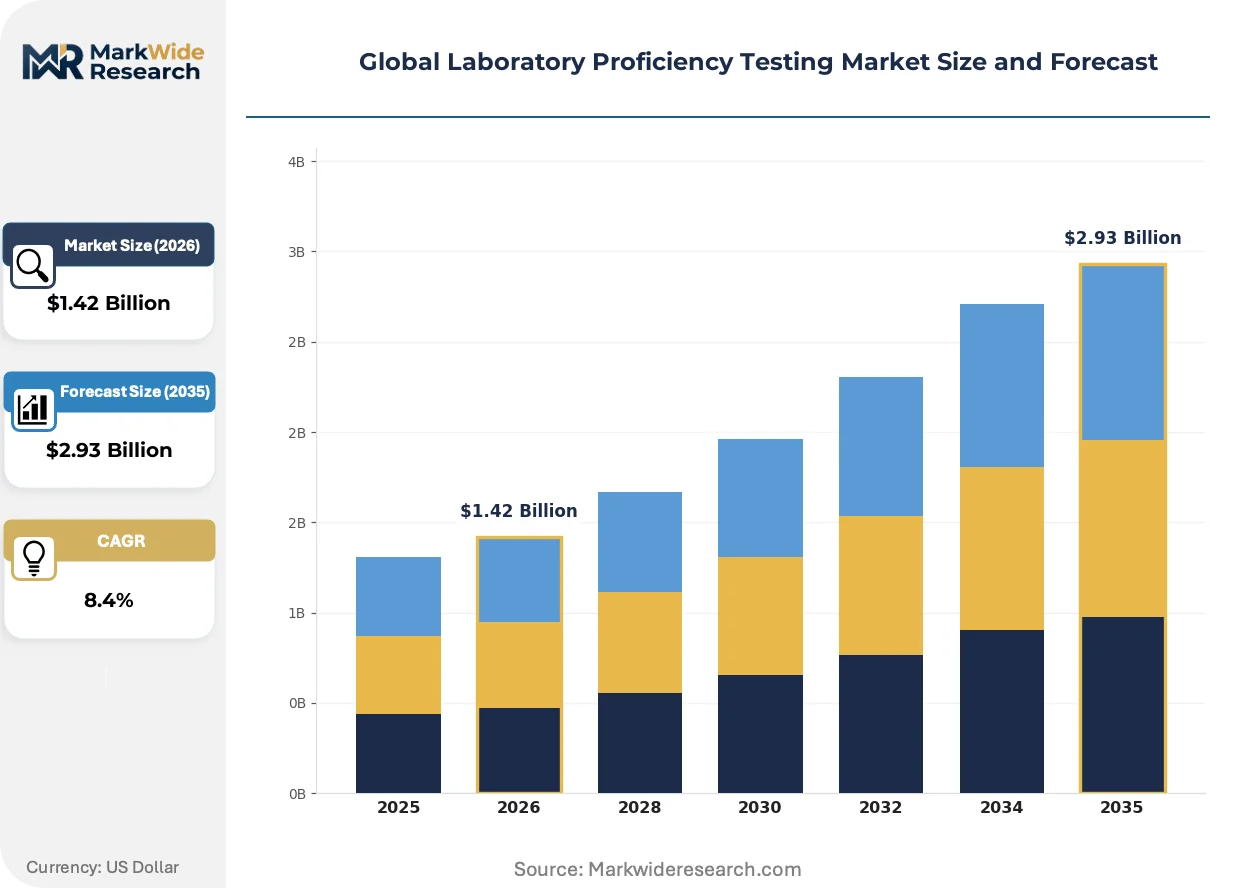
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Analysis, Microbiological Testing, Clinical Proficiency, Genetic Testing, Environmental Assessments Application: Clinical Diagnostics, Pharmaceutical Quality Control, Food Safety Evaluation, Environmental Monitoring, Forensic Investigations End User: Diagnostic Laboratories, Pharmaceutical Firms, Food Testing Facilities, Environmental Agencies, Forensic Institutes Service Type: External Quality Assurance, Inter-laboratory Comparison, On-site Evaluation, Data Analysis Support, Training Programs |
| Companies Covered | Merck KGaA, FAPAS, LGC Limited, Weqas, AOAC International, Bio-Rad Laboratories, American Proficiency Institute, NSI Lab Solutions, Randox Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Proficiency Testing Market Shifts & Advancements
Digital proficiency platforms are compressing result turnaround cycles while artificial intelligence tools reshape how laboratories interpret inter-laboratory comparison data. These shifts are redefining competitive differentiation beyond traditional analytical accuracy metrics.
Cloud-based proficiency testing software is migrating from on-premise laboratory information system modules to browser-native subscription platforms. Mid-sized clinical diagnostics laboratories are adopting these solutions fastest, driven by reduced IT maintenance burdens. This migration from capital-intensive infrastructure to operational expenditure models is compressing vendor switching costs and expanding addressable market penetration.
REACH chemical substance registration requirements are expanding analytical verification obligations for industrial testing laboratories across European member states. The regulation mandates documented measurement uncertainty for substances of very high concern. Environmental monitoring service providers in Germany and the Netherlands are responding by expanding accredited heavy metals and persistent organic pollutant panel offerings.
Subscription-based quality assurance bundles are displacing transactional proficiency testing purchases among integrated health networks. Hospital systems in the United States are consolidating vendor relationships and demanding consolidated invoicing across multiple testing disciplines. This consolidation is most visible among multi-site regional laboratory networks seeking procurement efficiency through single-provider contracts spanning chemistry, hematology, and microbiology verification.
Global Laboratory Proficiency Testing Market Segmentation
Segmentation in proficiency testing reveals how service delivery intensity varies dramatically across analytical disciplines and customer workflows. Laboratories purchasing chemical analysis panels require fundamentally different support cadences than those running genetic testing programs, creating distinct margin architectures within provider portfolios.
Product Type:
After-sales service intensity peaks in segments where sample stability windows are narrowest and regulatory reporting deadlines are tightest.
- Clinical Proficiency:Panels span hematology, immunoassay, and clinical chemistry with turnaround requirements often under 72 hours. Hospital laboratories in the United States and Germany drive recurring subscription demand through mandatory participation tied to CMS and DKG reimbursement eligibility.
- Microbiological Testing:Pathogen detection panels for Salmonella, Listeria, and E. coli verification require cold-chain logistics and rapid result reporting. Food safety evaluation protocols under Codex Alimentarius-aligned standards are expanding panel demand fastest across European member states and China.
- Chemical Analysis:Heavy metals, persistent organic pollutants, and residue testing dominate environmental monitoring applications.
- Genetic Testing:Molecular diagnostics and next-generation sequencing validation panels serve precision medicine workflows.
- Environmental Assessments:Water, soil, and air quality verification panels support EPA and MEE discharge compliance.
By volume, Chemical Analysis leads. By growth pace, Microbiological Testing is ahead.
Application:
Margin concentration follows regulatory enforcement intensity rather than absolute testing volume.
- Clinical Diagnostics:Mandatory proficiency participation structures under FDA oversight of laboratory-developed tests and EMA In Vitro Diagnostic Regulation lock in recurring revenue. Diagnostic laboratories in the United States, Germany, and China represent the deepest customer relationships.
- Food Safety Evaluation:Microbiological and chemical residue verification panels tighten under national standards aligned with Codex Alimentarius. Chinese and European food testing facilities are expanding panel density fastest.
- Pharmaceutical Quality Control:Release testing and stability verification for active pharmaceutical ingredients and finished dosage forms.
- Environmental Monitoring:EPA and MEE discharge regulations mandate periodic verification for industrial discharge permits.
- Forensic Investigations:DNA, toxicology, and trace evidence analytical performance verification for criminal justice applications.
Clinical Diagnostics commands the highest per-laboratory spend. Food Safety Evaluation is climbing the fastest.
End User:
Procurement sophistication separates centralized health networks from fragmented industrial testing facilities.
- Diagnostic Laboratories:Hospital-affiliated and independent clinical testing facilities purchase bundled quality assurance across multiple disciplines. Integrated health networks in the United States are consolidating vendor relationships and demanding consolidated invoicing.
- Pharmaceutical Firms:Quality control and release testing laboratories require GMP-aligned proficiency schemes with documented measurement uncertainty.
- Food Testing Facilities:Commercial and government laboratories supporting import inspection and domestic surveillance.
- Environmental Agencies:Regulatory monitoring laboratories and contracted industrial testing services.
- Forensic Institutes:State and federal crime laboratories with specialized accreditation requirements.
Diagnostic Laboratories anchor revenue concentration. Pharmaceutical Firms are gaining share fastest on biologics expansion.
Service Type:
Digital platform migration is compressing differentiation in commoditized service tiers while expanding premium advisory opportunities.
- External Quality Assurance:Blinded sample distribution with assigned reference values and statistical performance reporting constitutes the core service. Cloud-based subscription platforms are displacing transactional purchases among mid-sized clinical diagnostics laboratories.
- Inter-laboratory Comparison:Peer group benchmarking with z-score interpretation and trend analysis supports analytical quality improvement initiatives.
- On-site Evaluation:Direct technical assessment of laboratory procedures, equipment, and quality systems.
- Data Analysis Support:Statistical consulting for measurement uncertainty estimation and method validation.
- Training Programs:Workforce development in statistical competency and quality management system implementation.
External Quality Assurance dominates transaction volume. Data Analysis Support shows the steepest expansion trajectory on AI tool integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement mandates and FDA oversight of laboratory-developed tests compel diagnostic facilities across the United States to maintain continuous proficiency participation. Germany enforces similarly stringent requirements through DKG and national accreditation frameworks. China centralizes procurement through national health insurance schemes that mandate external quality assurance.
United States
Hospital-affiliated diagnostic laboratories in the United States purchase bundled quality assurance across chemistry, hematology, and microbiology disciplines. FDA oversight of laboratory-developed tests and CMS reimbursement eligibility requirements lock in mandatory participation structures. The Greater Boston and San Francisco Bay Area clusters concentrate precision medicine laboratories seeking next-generation sequencing validation panels.
Germany
DKG reimbursement frameworks and national accreditation requirements under DAkkS drive recurring subscription demand from hospital laboratories. REACH chemical substance registration mandates expand analytical verification obligations for industrial testing facilities. The Rhine-Ruhr metropolitan region anchors environmental monitoring service demand tied to EPA-aligned discharge regulations.
China
National health insurance procurement centralization mandates proficiency participation as a condition of reimbursement eligibility. MEE discharge regulations and GB standards compliance requirements expand chemical analysis panel demand. The Yangtze River Delta region concentrates food safety testing facilities responding to Codex Alimentarius-aligned national standards.
United Kingdom
UKAS accreditation requirements and NHS procurement consolidation drive vendor relationship rationalization among multi-site laboratory networks. The UK-EU regulatory divergence post-Brexit creates certificate recognition complexities for multinational networks. London and the Southeast cluster anchor clinical diagnostics demand while Manchester supports environmental monitoring service expansion.
Japan
PMDA oversight of in vitro diagnostics and MHLW reimbursement requirements compel analytical performance documentation from clinical testing facilities. METI industrial standards alignment drives quality system verification among pharmaceutical quality control laboratories. The Kanto region surrounding Tokyo concentrates diagnostic reagent manufacturers bundling proficiency services with consumable supply contracts.
Global Laboratory Proficiency Testing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated quality assurance platforms that bundle reference materials, digital reporting infrastructure, and statistical analysis tools. Diagnostic reagent manufacturers leverage installed base relationships to attach recurring proficiency subscriptions. Three strategic archetypes dominate: reference material specialists with captive accreditation credentials, diagnostic platform bundlers, and customized panel providers serving niche analytical segments. M&A activity concentrates among mid-sized European providers seeking UKAS and DAkkS credential expansion. Technology licensing partnerships between digital platform developers and established proficiency schemes accelerate cloud migration timelines.
Among reference material specialists, LGC Limited and Merck KGaA exemplify the archetype of UKAS-credentialed suppliers locking in quantitative method validation dependencies. Bio-Rad Laboratories represents the diagnostic platform bundler model, leveraging reagent installed bases to attach quality assurance subscriptions. Randox Laboratories occupies a position within the customized panel tier, competing on analytical density across clinical chemistry and immunoassay segments.
| Leading Market Players |
|---|
| Merck KGaA |
| FAPAS |
| LGC Limited |
| Weqas |
| AOAC International |
| Bio-Rad Laboratories |
| American Proficiency Institute |
| NSI Lab Solutions |
| Randox Laboratories |
| Others |
Supply & Pricing Matrix
Single-source dependency on UKAS-accredited reference material suppliers compresses pricing tier spreads while simultaneously elongating supply chain lead times for quantitative method validation. This concentration dynamic forces proficiency testing providers to absorb margin pressure or pass through costs to diagnostic laboratories already constrained by CMS reimbursement frameworks.
Pricing Analysis
Certification level creates the primary spread between premium ISO/IEC 17043-accredited schemes and standard inter-laboratory comparison offerings. Subscription-based SaaS pricing dominates as cloud platforms displace transactional purchases, with differentiation anchored in panel customization density and digital analytics bundling. Price erosion runs through the standard tier as mid-sized clinical laboratories consolidate vendor relationships and demand volume discounts across chemistry, hematology, and microbiology disciplines. Hospital-affiliated diagnostic laboratories exhibit highest price sensitivity due to fixed CMS reimbursement rates, while pharmaceutical quality control facilities show lowest sensitivity given GMP compliance imperatives.
Supply Chain Analysis
Export-control restrictions on synthetic biology reagents and nucleic acid reference materials limit cross-border flows from the United Kingdom and Germany into Chinese and Indian diagnostic markets. Production of certified reference materials concentrates in the United Kingdom, Germany, and the United States, with raw material dependencies spanning high-purity solvents, stabilized analyte matrices, and temperature-controlled packaging systems. Single-source vulnerability permeates the UKAS-accredited supplier tier, where captive production of quantitative standards locks in downstream proficiency scheme providers. Distribution runs through direct-to-laboratory digital portals and regional distributor networks serving fragmented food testing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Statistical competency scarcity among mid-sized laboratory technical staff constrains market expansion, as z-score interpretation expertise lags behind digital platform deployment. This capability gap favors providers investing in workforce development and AI-assisted analytics over pure sample distribution plays.
For Market Incumbents: Build captive reference material production moats through backward integration into UKAS-accredited synthesis capabilities. Defensive consolidation should prioritize DAkkS credential expansion in Germany and cloud platform interoperability investments that raise switching costs for hospital system customers. The threat of diagnostic reagent manufacturers bundling quality assurance subscriptions demands accelerated panel density expansion in clinical chemistry and immunoassay segments.
For New Entrants and Emerging Players: Establish a beachhead in environmental monitoring panels for MEE discharge compliance in China's Yangtze River Delta region. The most penetrable white space sits in data analysis support services, where AI tool integration lags behind external quality assurance commoditization. A go-to-market angle anchored in REACH-aligned chemical substance verification for industrial testing laboratories bypasses entrenched clinical diagnostics competition.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reference material specialists with captive accreditation credentials over pure digital platform plays. Long-term viability hinges on regulatory enforcement intensity rather than absolute testing volume expansion. Acquisition targets should display UKAS or DAkkS accreditation depth paired with recurring subscription revenue concentration. The signal to watch is mutual recognition arrangement expansion between ILAC signatories, which would compress duplicate scheme participation and reshape multinational laboratory network procurement patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Credential Expansion | UKAS or DAkkS accreditation unlocks mandatory participation structures under FDA and EMA frameworks. |
| Cloud Platform Migration | Browser-native subscription models reduce IT maintenance burdens for mid-sized clinical diagnostics laboratories. |
| Reference Material Backward Integration | In-house production of certified standards eliminates single-source dependencies and protects margin pools. |
| Multi-Analyte Panel Customization | Denser customized panels reduce per-test costs while maintaining analytical rigor for hospital networks. |
| AI-Assisted Data Analysis | Statistical consulting and z-score interpretation tools address competency gaps among technical staff. |
Research Methodology
Desk research of ISO/IEC 17043 accreditation databases, ILAC mutual recognition arrangements, and CLSI GP27-A framework documentation preceded structured interviews with proficiency scheme managers, diagnostic laboratory quality directors, and reference material production specialists. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation implementation guidance, and CMS reimbursement policy updates. Bottom-up triangulation across laboratory procurement databases and top-down cross-checks against regulatory mandate expansion timelines anchored market sizing.
Assumptions held fixed include sustained FDA oversight of laboratory-developed tests and EMA regulatory enforcement intensity, while variables included cloud platform adoption velocity and mutual recognition arrangement expansion between accreditation bodies. Segmentation modeling spanned product type, application, end user, and service type dimensions across the projection horizon. CAGRs derived from regression analysis against historical participation rate trends and regulatory mandate implementation schedules, with specific inputs including REACH chemical registration expansion and Codex Alimentarius alignment adoption curves.
Macroeconomic conditions sit as an overlay; deviation in healthcare procurement budgets or diagnostic reimbursement rates would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in ILAC mutual recognition progress or reference material supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Prothrombin Time Testing Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Malaria Ag Rapid Testing Market