
 Germany Honeycomb Paper Market | 2026-2036
Germany Honeycomb Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Honeycomb Paper Market Insights
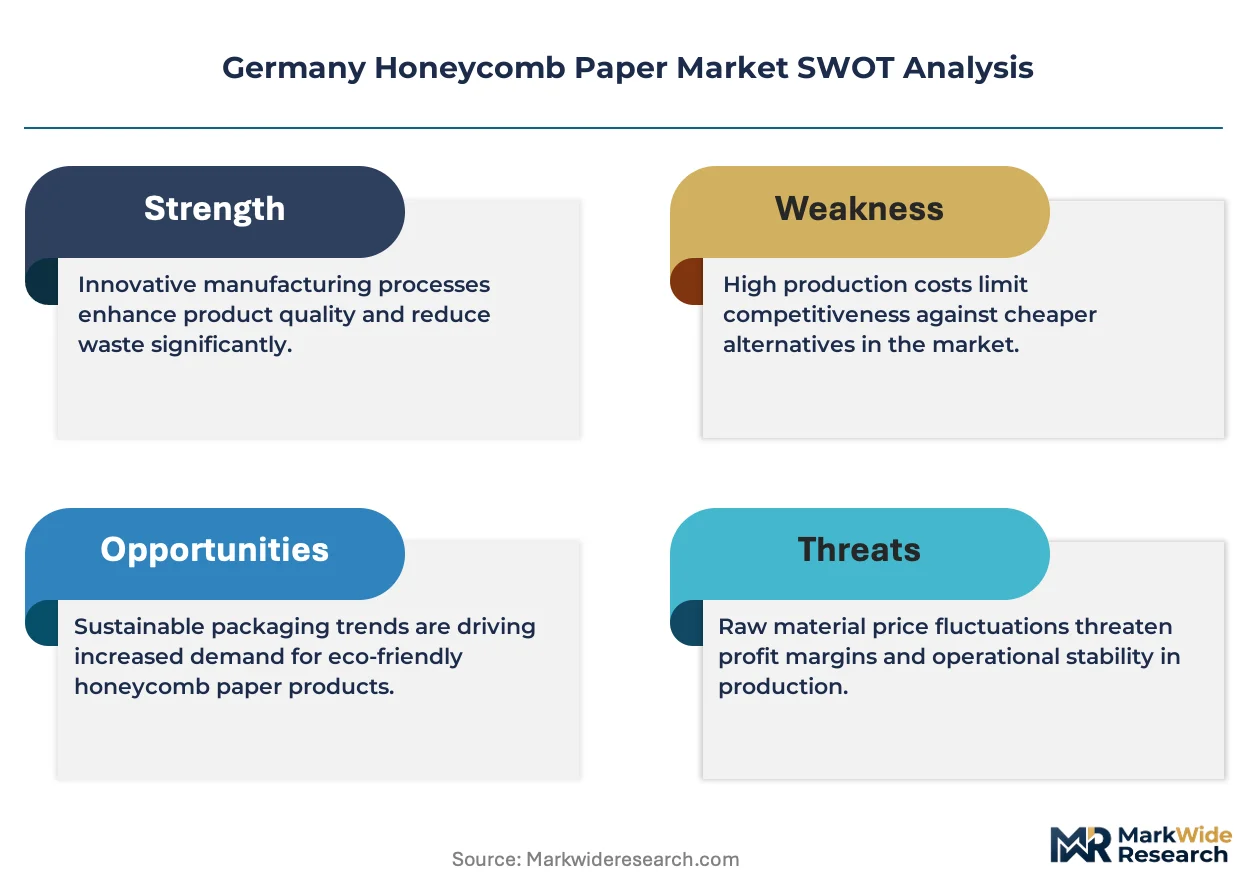
CE marking under the EU Construction Products Regulation is bifurcating the competitive landscape into certified and non-certified suppliers. DS Smith leverages its pan-European recycling infrastructure to secure consistent furnish for honeycomb core production. Honicel Group anchors its position through specialized machinery for continuous honeycomb expansion. Smurfit Kappa competes by integrating honeycomb panel output with its broader corrugated packaging network.
Honeycomb paper consists of hexagonal cells formed from kraft paper strips, bonded with water-based adhesives and expanded to create a cellular structure with high strength-to-weight ratios typically ranging from 20-150 kg/m³ density. The material functions primarily as a core substrate in sandwich panels and protective packaging systems where compressive strength and dimensional stability matter. Standard honeycomb dominates volume production for commodity packaging, while fire-resistant grades command premium positioning in building construction applications where EN 13501-1 classification governs market access. Reinforced honeycomb variants sustain faster growth in automotive interior programs as manufacturers substitute glass-mat thermoplastics with lighter paper-based alternatives.
Germany's Federal Environment Agency enforces the Packaging Act requirements that mandate minimum recycled content thresholds, directly steering brand owners toward paper-based protective solutions. The EU Green Deal's carbon border adjustment framework and Germany's national dual carbon goals pressure converters to document lifecycle emissions across honeycomb supply chains. REACH compliance through ECHA governs adhesive chemistry formulations used in cell bonding, limiting certain formaldehyde-based systems. Stakeholders must monitor how the EU Deforestation Regulation reshapes pulp sourcing certainties for kraft paper furnish.
Market Dynamics
Germany's Packaging Act enforcement is redirecting brand owner procurement toward paper-based protective substrates, compressing demand timelines for converters while automotive OEMs simultaneously pressure Tier 1 suppliers for lightweight interior structural materials.
Growth Catalysts
- Baden-Württemberg automotive corridor concentration:Stuttgart-centered OEM engineering offices co-locate with Tier 1 suppliers, compressing prototype-to-production cycles for honeycomb interior panels and reducing qualification friction.
- EU Green Deal carbon border adjustment:Documented lifecycle emissions now determine converter competitiveness, favoring domestic honeycomb producers with integrated recycling streams over imports lacking verified carbon accounting.
- REACH adhesive chemistry compliance:Water-based bonding systems certified through ECHA are displacing legacy formaldehyde formulations, opening specification pathways for kraft-based honeycomb in building construction applications.
Market Restraints
- Kraft pulp price volatility:Scandinavian furnish contracts indexed to NBSK pulp benchmarks expose German converters to input cost swings that compress margin stability during quarterly renegotiations.
- Continuous expansion machinery concentration:Specialized honeycomb production equipment sources from a narrow supplier base in Northern Italy, creating single-source vulnerability for capacity expansion decisions.
- Glass-mat thermoplastic substitution resistance:Automotive safety engineers retain default specifications for polymer cores in crash-critical interior applications, requiring extended validation protocols for paper-based alternatives.
Strategic Opportunities
- Bavaria packaging automation integration:Munich-area logistics hubs are piloting honeycomb dunnage systems with automated packing lines, opening volume contracts for standardized cell geometries.
- EN 13501-1 fire classification premium tier:Building contractors in Hamburg's high-rise residential zone face mandatory fire-resistant core specifications, creating price-insulated demand for treated honeycomb grades.
- Digital print-to-honeycomb convergence:Direct-to-substrate branding on protective packaging is merging with honeycomb fabrication, enabling converters to capture value-added decoration revenue from e-commerce fulfillment centers.
Industry Challenges
- CE marking certification timeline compression:Construction product regulation compliance requires extended third-party testing that delays market entry for new honeycomb panel formulations by 8-14 months.
- Adhesive formulation technical talent scarcity:Water-based bonding chemistry expertise concentrates among aging specialists in Saxony's paper technology institutes, constraining R&D throughput for next-generation cell structures.
- Recycled content verification system integration:Dual system operators under Germany's Packaging Act demand blockchain-tracked furnish documentation that many mid-scale converters lack infrastructure to provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Honeycomb Paper Market |
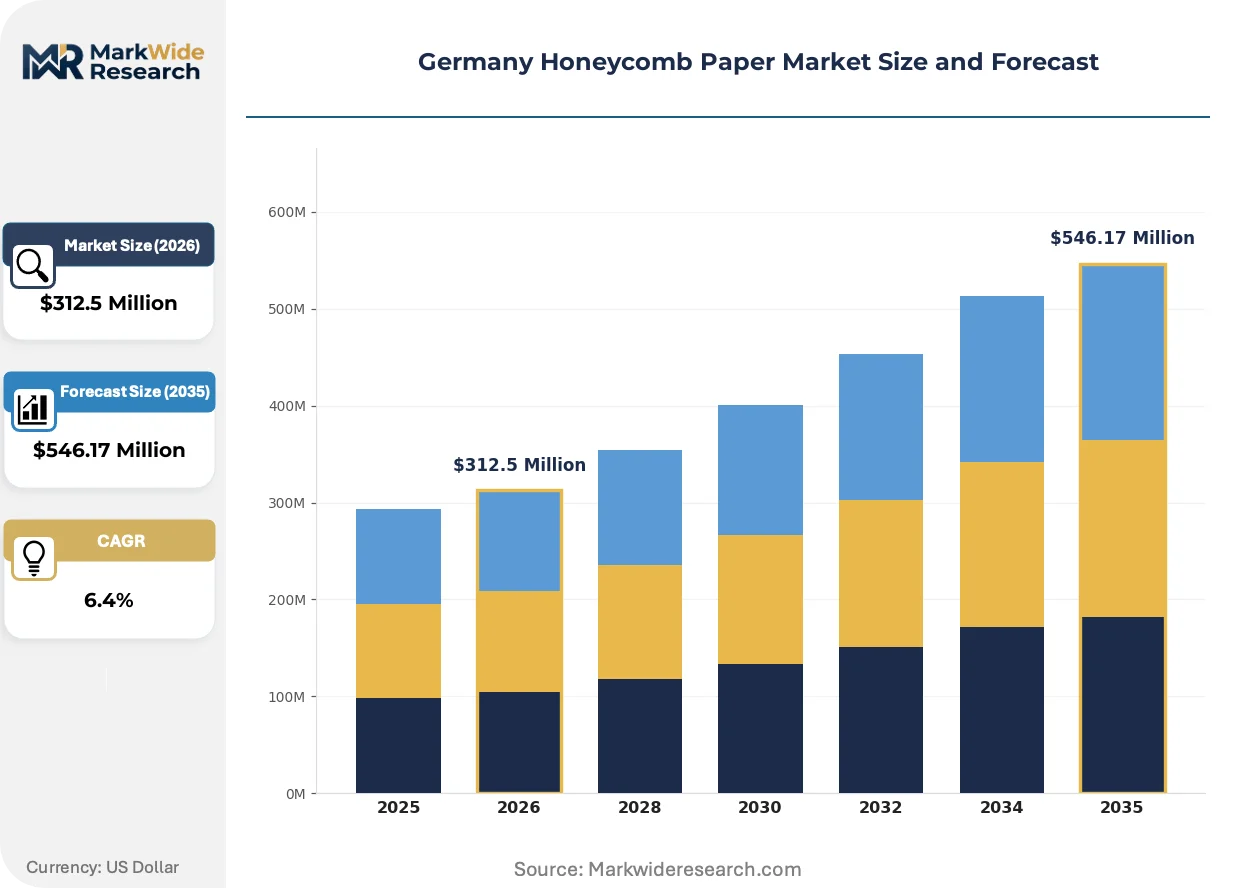
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Honeycomb, Reinforced Honeycomb, Fire-Resistant Honeycomb, Waterproof Honeycomb Application: Packaging, Furniture Manufacturing, Automotive Interior, Building Construction End User Industry: Consumer Goods, Vehicle Assembly, Residential Development, Commercial Fit-Out Packaging Type: Rolls, Sheets, Panels, Custom Profiles |
| Companies Covered | Hexacomb Corporation, Honicel Group, DS Smith, Tubus Baer GmbH, Axxor, Smurfit Kappa, Packaging Corporation of America, Grigeo, WestRock, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Honeycomb Paper Market Trends and Innovations
Material science advances and regulatory disclosure requirements are restructuring how honeycomb paper is specified, produced, and validated across German industrial supply chains.
Continuous honeycomb expansion technology is decomposing batch production economics in German converter facilities. Automotive Tier 1 suppliers in Stuttgart are adopting expanded-line systems that reduce core waste by 12-18% versus die-cut alternatives. This technology is decomposing the traditional volume thresholds that protected mid-scale regional producers from national competitors.
REACH adhesive chemistry restrictions through ECHA are eliminating formaldehyde-based bonding systems from building construction specifications. German facade panel manufacturers must reformulate with PVA or starch alternatives to maintain EN 13501-1 certification access. Fire-resistant honeycomb grades face 6-9 month requalification delays as testing laboratories process backlog from regulatory transition deadlines.
Lifecycle carbon accounting is penetrating procurement evaluation criteria for German brand owners. Retail fulfillment centers in North Rhine-Westphalia now require documented cradle-to-gate emissions for protective packaging tenders, displacing price-only award mechanisms. Automotive interior buyers at Wolfsburg and Munich engineering centers weight verified carbon data at 15-20% of supplier scorecards.
Germany Honeycomb Paper Market Segmentation
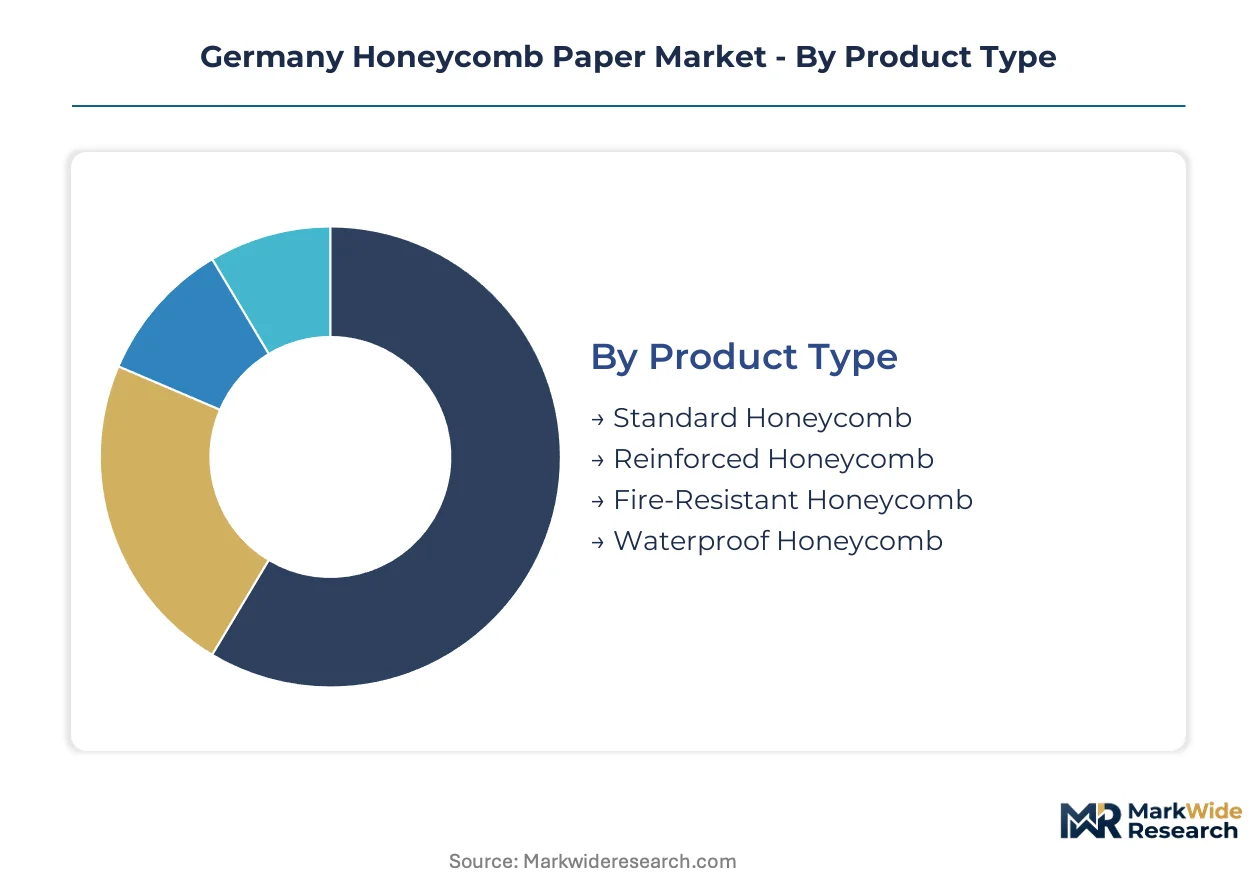
Honeycomb paper specification diverges sharply across German industrial buyers, with automotive interior programs demanding validated structural performance while e-commerce fulfillment centers prioritize cost-optimized protective geometries. Segmentation discipline separates commodity converters from specialists capturing premium positioning through certification depth.
Product Type:
Reinforced and fire-resistant grades face the stiffest substitution pressure from glass-mat thermoplastics and mineral wool boards, forcing specification battles around weight reduction credentials and EN 13501-1 compliance documentation.
- Standard Honeycomb:Hexagonal kraft paper cells bonded with water-based adhesives at 20-150 kg/m³ density serve commodity protective packaging and light-duty furniture core applications. Demand concentrates in North Rhine-Westphalia logistics hubs where e-commerce fulfillment centers specify bulk dunnage for automated packing lines, though margin compression from recycled corrugated alternatives limits converter pricing power.
- Reinforced Honeycomb:Glass fiber or synthetic scrim layers laminated to cell walls elevate compressive strength for automotive load floor and parcel shelf substrates. Stuttgart-area Tier 1 suppliers specify these grades for interior structural panels, driven by OEM lightweighting mandates that displace heavier glass-mat thermoplastic cores in non-crash-critical applications.
- Fire-Resistant Honeycomb:Intumescent coatings or mineral-doped kraft furnish achieve EN 13501-1 classification for facade sandwich panels and elevator shaft enclosures. Hamburg high-rise residential contractors represent the primary demand node under mandatory fire core regulations.
- Waterproof Honeycomb:Paraffin-impregnated or polymer-modified cell walls resist moisture degradation for outdoor furniture and marine interior applications. Bavarian garden furniture manufacturers specify limited volumes for export-oriented production.
Standard honeycomb anchors the volume base while reinforced honeycomb gains share at the steepest rate.
Application:
Margin structure inverts across application tiers, with automotive interior programs commanding triple-digit euro per cubic meter pricing against packaging's thin converter spreads.
- Packaging:Protective dunnage, edge protectors, and void-fill systems consume the majority of German honeycomb tonnage. Baden-Württemberg automotive parts distributors and North Rhine-Westphalia electronics fulfillment centers drive specification toward standardized cell geometries compatible with automated packing equipment.
- Automotive Interior:Door panels, headliners, and trunk floors utilize reinforced honeycomb cores laminated to decorative skins. Wolfsburg and Munich engineering centers weight supplier scorecards toward documented lifecycle carbon data, favoring domestic producers with integrated recycling streams.
- Furniture Manufacturing:Table tops, cabinet doors, and shelving units incorporate honeycomb cores to reduce weight and material cost. East German furniture clusters in Saxony and Thuringia source from regional converters serving mid-market residential segments.
- Building Construction:Curtain wall panels, cleanroom ceilings, and raised floor systems specify fire-resistant grades. Hamburg and Frankfurt commercial development corridors generate demand under stringent facade fire safety codes.
Packaging dominates absolute volume while automotive interior applications expand most quickly.
End User Industry:
Procurement sophistication varies dramatically, with vehicle assembly operations imposing full material certification protocols against consumer goods buyers prioritizing unit cost minimization.
- Vehicle Assembly:OEM engineering offices in Stuttgart, Wolfsburg, and Munich mandate PPAP-level qualification for honeycomb interior components, including crash simulation data and supply chain carbon documentation. Tier 1 seating and trim suppliers represent the critical intermediary specification layer.
- Consumer Goods:Appliance manufacturers and electronics brands specify protective honeycomb packaging for domestic and export shipment. Brand owner procurement teams under Germany's Packaging Act face recycled content verification requirements that favor established converters with blockchain-tracked furnish systems.
- Residential Development:Multi-family housing contractors in Berlin and Hamburg specify fire-resistant honeycomb panels for interior partition systems under energy efficiency renovation programs.
- Commercial Fit-Out:Office furniture dealers and retail fixture installers source custom-profile honeycomb components for display systems and workstation elements. Munich and Frankfurt corporate headquarters projects drive specification toward premium aesthetic finishes.
Consumer goods procurement anchors volume throughput while vehicle assembly commands the steepest pricing tier.
Packaging Type:
Supply chain configuration and converter capital intensity diverge across format types, with continuous expansion lines favoring rolls and sheets against batch-cut custom profiles.
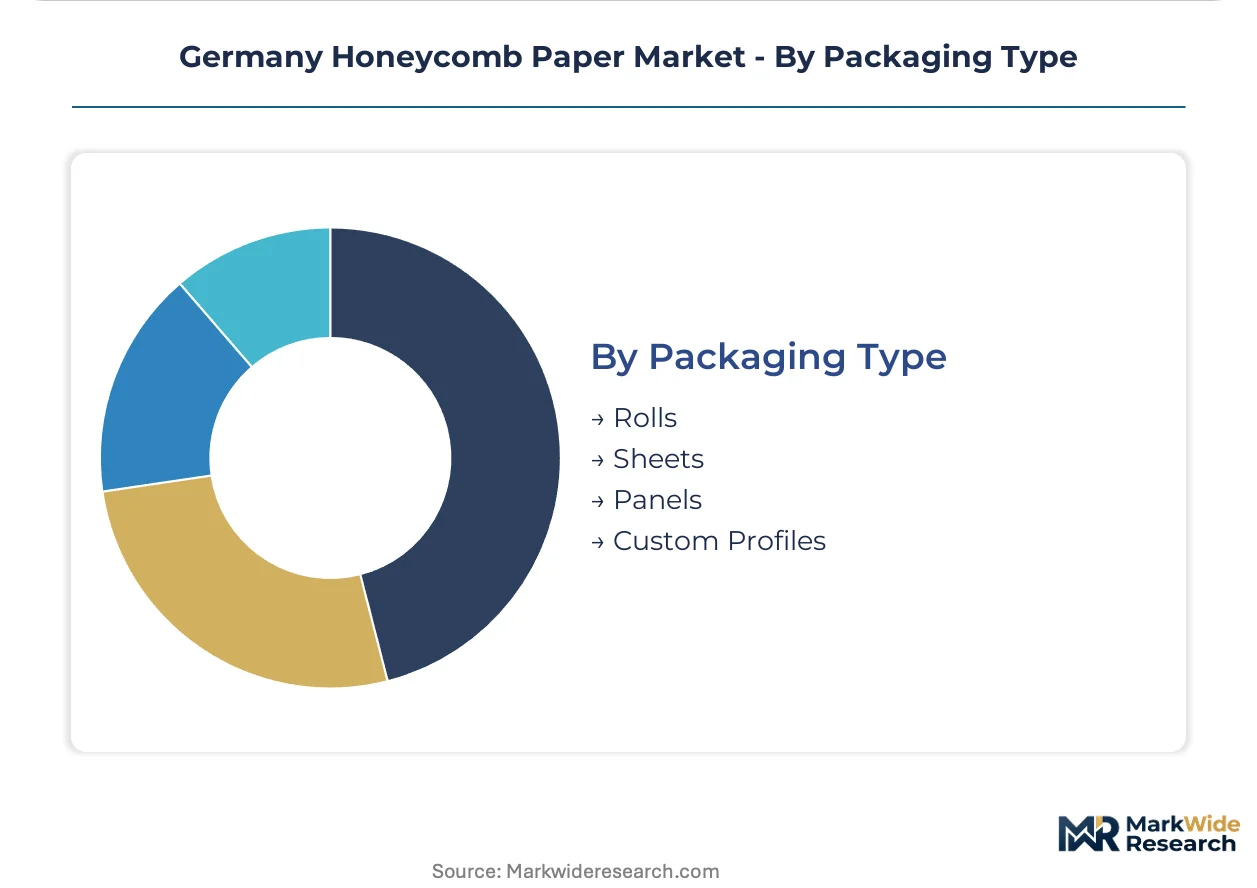
- Sheets:Flat honeycomb boards in standard thicknesses serve furniture core lamination and protective packaging layer applications. High-volume German converters run continuous expansion lines optimized for 1,200-2,500 mm width outputs.
- Panels:Laminated sandwich constructions with facing materials pre-bonded at converter facilities reduce downstream customer processing steps. Automotive Tier 1 suppliers in Baden-Württemberg specify ready-to-laminate panels to compress prototype-to-production cycles.
- Rolls:Continuous honeycomb wound onto cores enables automated unwind-and-cut operations at high-speed packaging lines. North Rhine-Westphalia fulfillment centers pilot roll-fed dunnage systems for e-commerce volume scaling.
- Custom Profiles:Die-cut or CNC-routed honeycomb geometries match specific product contours for high-value protective applications. Limited batch production concentrates among specialized Saxon converters serving aerospace and medical equipment segments.
Sheets and rolls dominate production volume while custom profiles capture the highest margin per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Packaging Act enforcement redirects procurement toward paper-based protective substrates, while Baden-Württemberg's automotive corridor concentrates demand for lightweight interior structural materials.
Baden-Württemberg
Automotive interior programs drive reinforced honeycomb adoption as Stuttgart-centered OEM engineering offices co-locate with Tier 1 suppliers. REACH adhesive chemistry compliance through ECHA governs water-based bonding systems used in cell wall lamination. Continuous expansion machinery operators in the Stuttgart region reduce core waste by 12-18% versus die-cut alternatives.
North Rhine-Westphalia
E-commerce fulfillment centers pilot roll-fed honeycomb dunnage systems for automated packing line integration. The Packaging Act mandates minimum recycled content thresholds that steer brand owners toward paper-based solutions. Cologne and Düsseldorf logistics hubs specify standardized cell geometries compatible with high-speed packaging equipment.
Bavaria
Munich-area automotive engineering centers weight supplier scorecards toward documented lifecycle carbon data for interior panel programs. EU Green Deal carbon border adjustment frameworks pressure converters to verify emissions across supply chains. Bavarian garden furniture manufacturers specify waterproof honeycomb grades for export-oriented production.
Hamburg
High-rise residential contractors face mandatory fire-resistant core specifications under EN 13501-1 classification for facade sandwich panels. The EU Construction Products Regulation requires CE marking compliance that delays market entry for new honeycomb formulations. Hamburg commercial development corridors generate demand for treated honeycomb grades in curtain wall applications.
Lower Saxony
Wolfsburg engineering centers mandate PPAP-level qualification for honeycomb interior components including crash simulation data. Germany's dual carbon goals pressure Tier 1 suppliers to document supply chain emissions for automotive programs. Regional converters serve seating and trim suppliers with certified structural core materials.
Germany Honeycomb Paper Market Competitive Landscape
Player mix skews toward integrated paperboard conglomerates with captive recycling infrastructure. Market structure consolidates around pan-European operators with continuous expansion capabilities and regional specialists with automotive qualification depth. Two strategic archetypes dominate: vertically integrated packaging conglomerates leveraging furnish security, and machinery-anchored specialists commanding premium positioning through continuous expansion technology. Competitive moves center on recycling infrastructure control and CE marking certification depth.
Among pan-European paperboard operators, DS Smith and Smurfit Kappa represent the integrated conglomerate archetype with recycling-fed furnish chains. Honicel Group occupies a specialist position anchored through continuous honeycomb expansion machinery capabilities. These three entities exemplify the competitive tension between scale-driven packaging volume and precision-engineered automotive qualification.
| Leading Market Players |
|---|
| Hexacomb Corporation |
| Honicel Group |
| DS Smith |
| Tubus Baer GmbH |
| Axxor |
| Smurfit Kappa |
| Packaging Corporation of America |
| Grigeo |
| WestRock |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with Scandinavian kraft pulp suppliers lock in furnish access for German converters while fixing input cost visibility against NBSK benchmark volatility. These arrangements compress margin uncertainty for continuous expansion operators serving automotive Tier 1 suppliers in Baden-Württemberg.
Pricing Analysis
Certification level (CE marking under EU Construction Products Regulation) creates the primary spread between construction-grade fire-resistant honeycomb and commodity packaging grades. Pricing stratifies across premium, standard, and economy tiers where EN 13501-1 classified panels command triple-digit euro premiums over undifferentiated dunnage. Cost compression in standard honeycomb intensifies because recycled corrugated alternatives erode converter pricing power. E-commerce fulfillment centers in North Rhine-Westphalia exhibit highest price sensitivity, while automotive interior buyers at Stuttgart engineering centers prioritize lifecycle carbon documentation over unit cost.
Supply Chain Analysis
Container availability on Baltic-Scandinavian trade lanes governs kraft pulp delivery reliability to German converter facilities. Supply concentrates in Sweden, Finland, and Norway for NBSK furnish, while continuous expansion machinery sources exclusively from Northern Italian equipment builders. Raw material dependencies center on bleached softwood pulp, water-based adhesive chemistries, and intumescent coating formulations. Single-source vulnerability in honeycomb expansion equipment creates capacity expansion bottlenecks. Distribution runs through converter-direct relationships with automotive Tier 1 suppliers and packaging distributors serving North Rhine-Westphalia logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across German federal states and EU member markets is fragmenting demand into certification-specific niches. The Packaging Act's recycled content mandates and EN 13501-1 fire classification requirements create distinct procurement pools that favor specialized over generalized supply.
For Market Incumbents: Consolidate recycling infrastructure control through backward integration into kraft pulp furnish streams. DS Smith and Smurfit Kappa already leverage pan-European recovery networks; smaller converters must secure blockchain-tracked recycled content documentation to defend against dual system operator audit requirements. CE marking certification depth represents the critical lever for construction market access. For New Entrants and Emerging Players: Digital print-to-honeycomb convergence services present an under-served layer where incumbents lack decoration capabilities. White-space targets include automated packing line integration for Bavaria logistics hubs and fire-resistant grade production for Hamburg high-rise contractors. A contract manufacturing model serving e-commerce fulfillment centers with standardized roll-fed geometries offers the most penetrable entry path. For Investors and Strategic Acquirers: Capital is best deployed toward machinery-anchored specialists with continuous expansion capabilities and automotive qualification depth. Long-term viability hinges on converters bridging packaging volume scale with precision-engineered structural core certification. The signal to watch is EN 13501-1 requalification backlog duration as REACH adhesive chemistry restrictions eliminate formaldehyde-based systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Recovery | Secures furnish access under Germany's Packaging Act recycled content mandates. |
| CE Marking Certification Investment | Unlocks Hamburg and Frankfurt construction corridors under EU Construction Products Regulation. |
| Continuous Expansion Machinery Upgrade | Reduces core waste 12-18% for Stuttgart automotive Tier 1 supplier contracts. |
| Water-Based Adhesive Reformulation | Maintains EN 13501-1 access as ECHA REACH restrictions eliminate formaldehyde bonding systems. |
| Lifecycle Carbon Documentation System | Satisfies Wolfsburg and Munich OEM supplier scorecard weighting for interior panel programs. |
Research Methodology
Cross-validation between converter production data and automotive Tier 1 procurement records anchors the qualitative findings in this study. Primary interviews with honeycomb production managers, adhesive chemistry specialists, OEM platform engineers, and packaging procurement leads at e-commerce fulfillment centers combined with secondary validation from ECHA REACH filings, EU Construction Products Regulation certification databases, German Federal Environment Agency enforcement records, and Scandinavian pulp trade statistics. Bottom-up capacity modeling and top-down demand estimation triangulate volume figures.
Sensitivity analysis around kraft pulp price volatility and automotive lightweighting adoption rates stress-tests projection robustness. The analytical framework segments by product type (standard, reinforced, fire-resistant, waterproof), application (packaging, automotive interior, furniture, construction), and end-user industry (vehicle assembly, consumer goods, residential development, commercial fit-out) across the projection horizon. CAGRs derive from regression against historical automotive production and e-commerce fulfillment center expansion patterns, with input from documented lifecycle carbon accounting penetration in procurement evaluation criteria.
Material uncertainties — regulatory transition timelines for EU Deforestation Regulation pulp sourcing requirements and adhesive chemistry requalification delays — sit outside the modeled envelope. Forecasts reflect assumptions about REACH compliance continuity and Packaging Act enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Postage Stamp Paper Market