
 Kraft Paper SOS Bag Market | 2026-2036
Kraft Paper SOS Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Paper SOS Bag Market Foresight
FSC Chain of Custody certification is redrawing supplier eligibility across European retail procurement. Mondi Group leverages integrated pulp-to-bag operations across Austria and Germany to sustain volume commitments to pan-European grocers. Smurfit Kappa anchors its position through recycled linerboard feedstock and regional converting networks in Iberia and the Nordic markets. International Paper competes on North American kraft paper exports that feed SOS bag machines in the United Kingdom and Ireland.
A Kraft Paper SOS Bag is a self-opening square-bottom carrier constructed from unbleached sulfate pulp, typically ranging from 70 to 120 grams per square meter, designed to stand upright without external support for retail and food service distribution. The square bottom configuration dominates European grocery adoption due to superior stacking efficiency and printability for brand messaging. E-commerce end users represent the fastest-expanding demand pool as corrugated outer boxes increasingly require inner paper cushioning and branded unboxing elements. Flat bottom variants occupy mature positions in bakery and quick-service restaurant channels where cost minimization outweighs structural sophistication.
EU REACH restrictions on chemical additives in food-contact paper and the F-Gas Regulation's indirect pressure on synthetic packaging alternatives are tightening material compliance requirements for converters. Germany's national packaging regulator enforces extended producer responsibility fees that favor mono-material kraft constructions over multi-layer laminates. Stakeholders must monitor recycled fiber availability cycles and certification backlog periods at FSC and PEFC accreditation bodies.
Market Dynamics
EU single-use plastic directives are forcing a wholesale substrate conversion across European retail checkout infrastructure, with bag converters racing to certify FSC Chain of Custody ahead of procurement deadlines.
Growth Catalysts
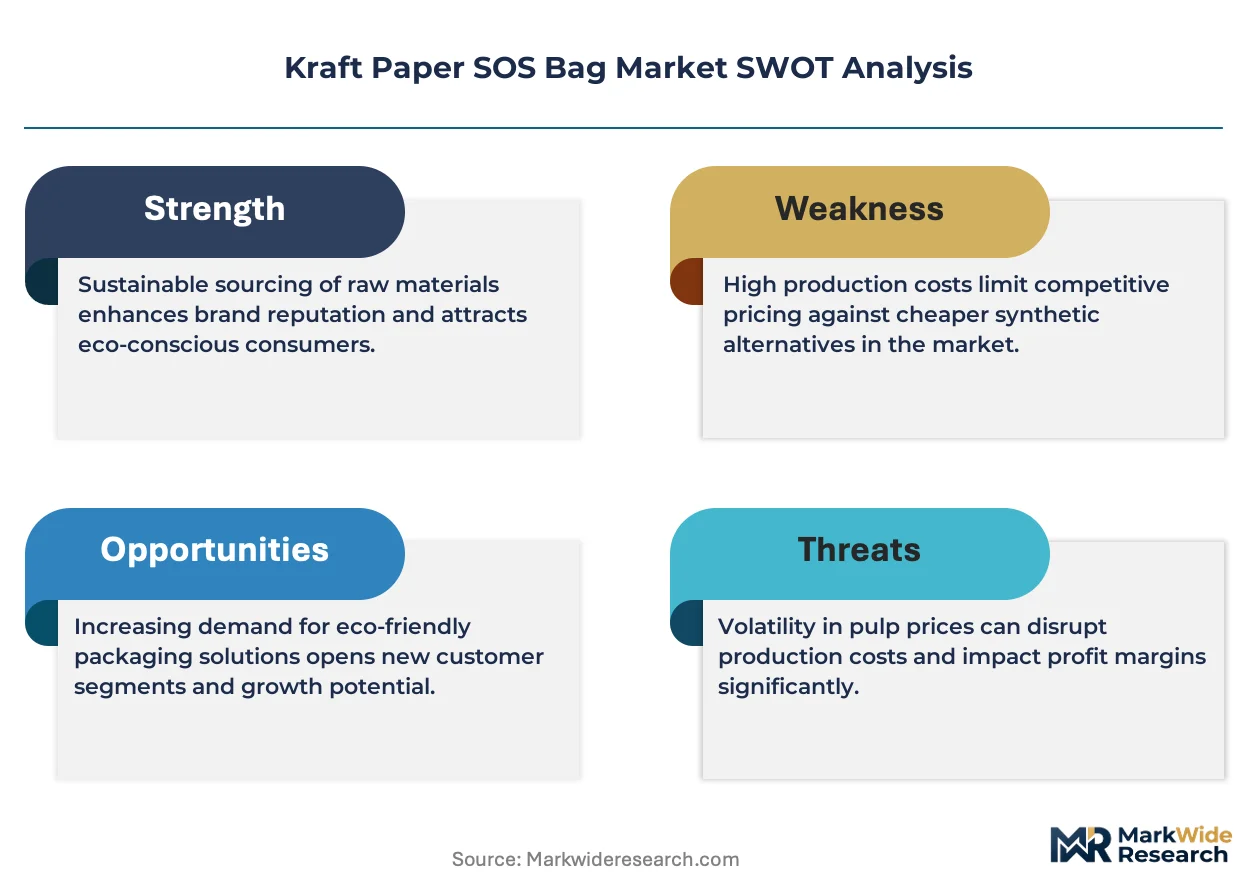
- REACH food-contact compliance:Brussels mandates on chemical additives in paper packaging are disqualifying plastic-laminated alternatives from grocery channels.
- E-commerce unboxing demand:Corrugated outer boxes increasingly require inner paper cushioning and branded carrier elements for premium customer experience.
- North Rhine-Westphalia converter clustering:Proximity to German retail distribution hubs enables just-in-time SOS bag supply with minimized logistics cost.
Market Restraints
- Recycled fiber cost volatility:OCC bale prices swing with municipal collection rates, compressing converter margins on fixed retail contracts.
- F-Gas Regulation substitution limits:Synthetic barrier coatings face phase-down pressure, narrowing moisture-protection options for frozen food applications.
- PEFC certification backlog:Accreditation body processing delays extend supplier qualification timelines by four to six months.
Strategic Opportunities
- Iberia recycled linerboard expansion:Smurfit Kappa's regional converting networks remain underweighted relative to German and French retail density.
- Quick-service restaurant flat-bottom conversion:Cost-minimized bakery channels present upgrade potential to square-bottom formats with print branding.
- Extended producer responsibility fee arbitrage:Germany's packaging regulator penalizes multi-layer laminates, advantaging mono-material kraft constructions.
Industry Challenges
- High-strength kraft pulping capex:Mill investments in recycled fiber processing equipment require eighteen-to-twenty-four month commissioning cycles.
- FSC audit scheduling congestion:Third-party certification body capacity constraints delay supplier eligibility for pan-European grocer tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Paper SOS Bag Market |
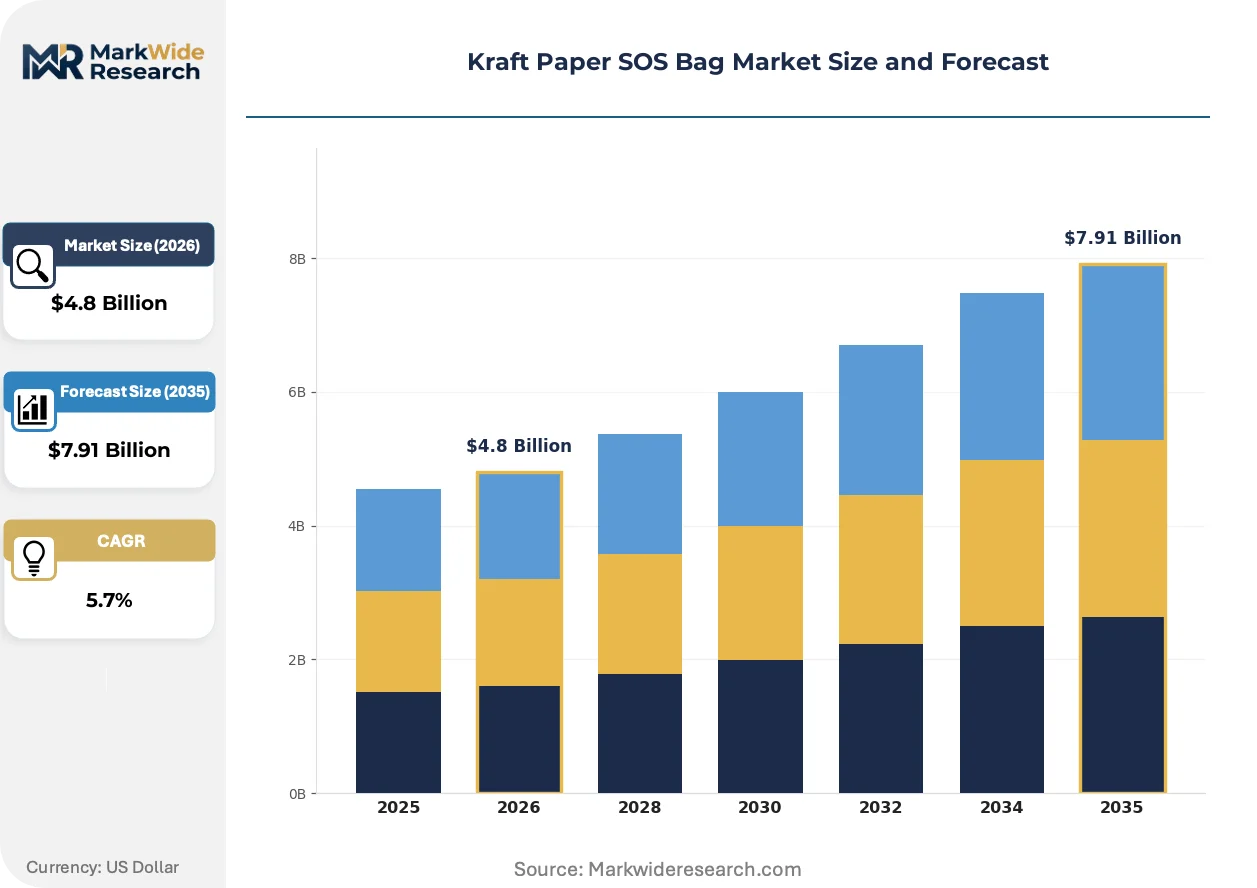
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottom, Square Bottom, Gusseted, Tapered End User: Retail, Food Services, Consumer Goods, E-Commerce Size: Small, Medium, Large, Extra Large Closure Type: Self-Adhesive, Tie, Tape, Open-Top |
| Companies Covered | Mondi Group, International Paper, Smurfit Kappa, WestRock Company, Huhtamaki, Sonoco, Oji Holdings Corporation, Klabin, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Paper SOS Bag Market Shifts & Advancements
Substrate engineering and regulatory chemistry are converging to redefine barrier performance expectations in food-contact paper packaging.
Water-based barrier coatings are decomposing the traditional polyethylene lamination stack in frozen food SOS bag applications. German discount grocers are piloting these formulations at scale for private-label seafood and vegetable lines. The technology is decomposing incumbent multi-layer supply chains by eliminating separate film conversion steps and enabling single-stream recycling claims.
EU F-Gas Regulation phase-down schedules are accelerating fluorochemical barrier elimination from grease-resistant grades. Brussels enforcement timelines compress converter reformulation windows to eighteen months for quick-service restaurant supply contracts. Nordic markets exhibit fastest compliance migration due to preemptive national chemical restriction regimes.
Retail procurement consolidation is compressing supplier qualification cycles from annual to quarterly review periods. Pan-European grocery alliances now mandate real-time Chain of Custody documentation through blockchain-tracked batch records. French hypermarket chains lead this transparency push, with German cooperatives following within one tender cycle.
Kraft Paper SOS Bag Market Segmentation
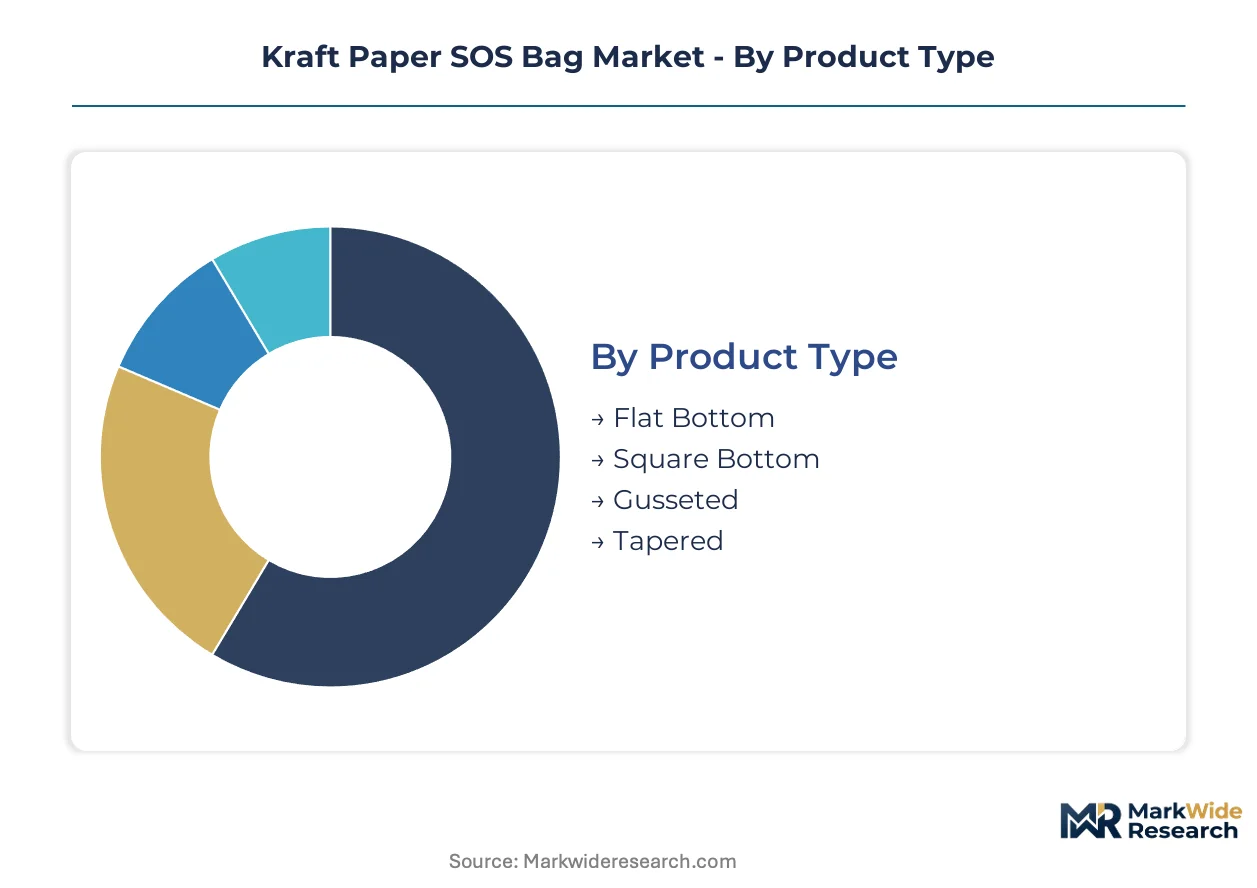
Structural configurations and end-use applications define margin capture in the Kraft Paper SOS Bag Market. Certification requirements and automation compatibility vary sharply across product formats, creating distinct competitive battlegrounds for converters.
Product Type:
Margin pools concentrate in square-bottom formats where FSC certification premiums and high-speed machine compatibility sustain pricing power. Flat-bottom variants compete on volume throughput for cost-sensitive channels.
- Square Bottom:Constructed with self-opening geometry from 80-120 gsm unbleached sulfate pulp. German retail distribution hubs in North Rhine-Westphalia drive concentration, as pan-European grocers mandate this format for checkout-line automation and brand printability. REACH food-contact compliance requirements favor mono-material kraft constructions over laminated alternatives.
- Flat Bottom:Simple folded-base design using lighter 70-90 gsm stock. Bakery and quick-service restaurant channels in France and Iberia dominate demand, where cost minimization outweighs structural sophistication and EPR fee structures penalize complex multi-layer alternatives.
- Gusseted:Side-pleated expansion panels accommodate irregular contents. Specialty retail applications in Nordic markets favor this format for gift and premium merchandise presentation.
- Tapered:Conical profile reduces material usage for lightweight contents. Limited adoption concentrated in pharmaceutical and cosmetics sampling programs.
Square Bottom holds installed capacity. Flat Bottom is rotating up the share rankings.
End User:
Application-specific compliance requirements reshape procurement priorities across customer categories. E-commerce specifications diverge most sharply from traditional retail formats.
- E-Commerce:Inner cushioning and branded unboxing elements drive specification divergence from retail formats. Corrugated outer boxes increasingly require protective paper inserts with carrier functionality, with German and French pure-play retailers expanding private-label packaging requirements fastest.
- Retail:Checkout-line automation compatibility and real-time Chain of Custody documentation dominate procurement. Pan-European grocery alliances now mandate blockchain-tracked batch records, with French hypermarket chains leading transparency requirements.
- Food Services:Grease-resistant grades face compressed reformulation windows under EU F-Gas Regulation phase-down schedules. Quick-service restaurant supply contracts require eighteen-month compliance migration timelines.
- Consumer Goods:Moderate specification intensity across personal care and household products. Private-label concentration in German discount channels sustains volume demand.
Retail commands current volume leadership. E-Commerce is climbing the fastest.
Size:
Capacity utilization and machine changeover economics favor medium formats, while oversized segments carry premium positioning.
- Medium:Optimal throughput on standard SOS bag machines with minimal changeover downtime. German retail distribution hubs concentrate procurement for standard grocery loads.
- Large:Higher gsm requirements and reinforced handles sustain margin premiums. French hypermarket chains specify this format for bulk household goods.
- Small:Convenience store and pharmacy applications in Iberia and Nordic markets. Limited automation compatibility constrains converter interest.
- Extra Large:Specialty applications for home improvement and garden retail. Low volume, high customization requirements.
Medium holds installed capacity. Large is rotating up the share rankings.
Closure Type:
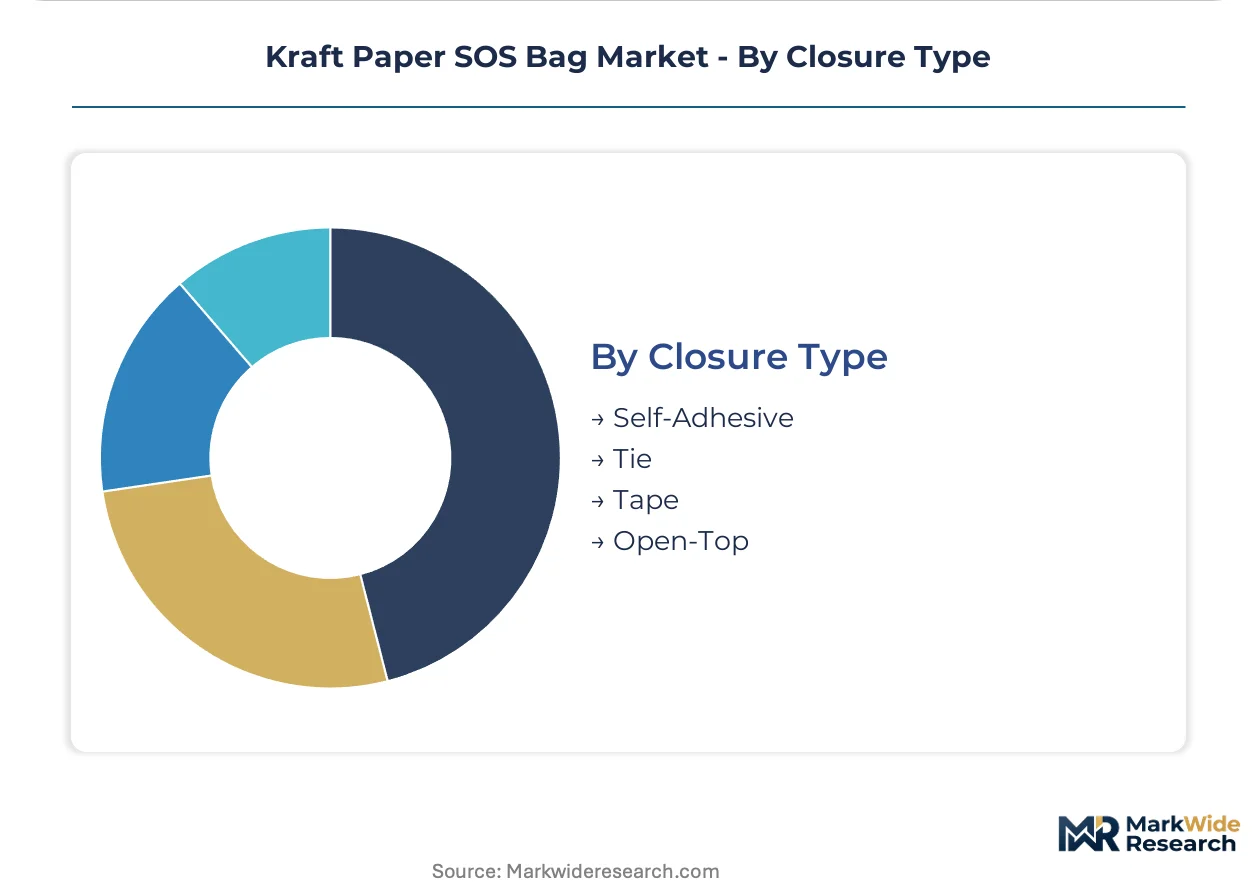
Automation compatibility and recycling stream simplicity determine adoption trajectories across sealing mechanisms.
- Open-Top:Standard configuration for retail checkout applications. Mono-material construction satisfies Germany's extended producer responsibility fee structures.
- Self-Adhesive:Tamper-evident functionality for e-commerce and pharmaceutical applications. Water-based adhesive formulations required under REACH chemical restrictions.
- Tie:Bakery and specialty food service preference. Manual handling requirements limit automation scaling.
- Tape:Reinforced sealing for heavy contents. Multi-material construction faces EPR fee penalties in German markets.
Open-Top holds installed capacity. Self-Adhesive is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pan-European grocery chains dominate procurement volumes, with checkout-line automation and extended producer responsibility fee structures dictating supplier selection across national markets.
Germany
North Rhine-Westphalia hosts dense converter clustering near retail distribution hubs in Düsseldorf and Cologne. The national packaging regulator enforces extended producer responsibility fees that penalize multi-layer laminates, advantaging mono-material kraft constructions. Mondi Group leverages integrated pulp-to-bag operations across Austria and Germany to sustain volume commitments.
France
French hypermarket chains lead blockchain-tracked Chain of Custody documentation mandates, compressing supplier qualification cycles to quarterly reviews. EU REACH restrictions on chemical additives in food-contact paper disqualify plastic-laminated alternatives from grocery channels. Smurfit Kappa anchors regional converting networks to serve retail density in Île-de-France.
United Kingdom
International Paper competes through North American kraft paper exports feeding SOS bag machines in Manchester and Birmingham. Brexit-adjusted customs regimes have restructured import logistics for unbleached sulfate pulp. E-commerce unboxing demand from London-based pure-play retailers drives specification divergence toward inner cushioning formats.
Spain
Iberian bakery and quick-service restaurant channels sustain flat-bottom variant demand where cost minimization outweighs structural sophistication. Smurfit Kappa's regional converting networks remain underweighted relative to German and French retail density. Barcelona and Madrid distribution hubs service southern European export routes.
Italy
Lombardy and Emilia-Romagna industrial corridors concentrate specialty retail applications requiring gusseted formats for gift and premium merchandise presentation. EU F-Gas Regulation phase-down schedules compress fluorochemical barrier elimination timelines to eighteen months. Milan-based procurement offices coordinate pan-European tender participation.
Kraft Paper SOS Bag Market Competitive Landscape
Player mix skews toward integrated pulp-to-paper converters with captive fiber supply and regional bag fabricators serving niche certification requirements. The structure concentrates around three strategic archetypes: vertically integrated multinationals controlling raw material through finished goods, specialist converters leveraging regional accreditation proximity, and paper merchants arbitraging spot pulp markets. Dominant competitive moves include FSC Chain of Custody certification racing ahead of retail procurement deadlines and water-based barrier coating reformulation to eliminate polyethylene lamination.
Within the integrated multinational tier, Mondi Group exemplifies captive pulp supply through Central European mill networks, while Smurfit Kappa represents recycled linerboard feedstock specialization with Iberian and Nordic converting reach. International Paper occupies a merchant position bridging North American kraft surplus with European SOS bag machine demand. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper |
| Smurfit Kappa |
| WestRock Company |
| Huhtamaki |
| Sonoco |
| Oji Holdings Corporation |
| Klabin |
| DS Smith |
| Others |
Supply & Pricing Matrix
Mill-scale economies in North Rhine-Westphalia kraft pulping operations concentrate bargaining power among integrated producers while establishing regional price floors for bag converters. This geographic clustering of high-capacity sulfate pulp production shapes both supply availability and contract indexation terms across European retail procurement.
Pricing Analysis
Cost-plus contracts indexed to OCC bale spot markets dominate converter-retailer agreements, with FSC-certified square-bottom formats commanding premiums over uncertified flat-bottom alternatives. Price differentiation hinges on certification tier and automation compatibility, with German discount grocers squeezing margins through volume aggregation. Cost compression in flat-bottom segments is intensifying because bakery channel buyers prioritize unit economics over structural performance. Quick-service restaurant procurement teams exhibit highest price sensitivity, while pan-European grocery alliances accept certification premiums for supply security.
Supply Chain Analysis
Just-in-time inventory strategies predominate among German retail distribution hubs, minimizing working capital exposure but amplifying vulnerability to recycled fiber availability cycles. Raw material sourcing draws from Austrian pulp mills, Swedish kraftliner producers, and Portuguese recycled fiber processors. Supply chain risk centers on single-source vulnerability for FSC-certified fiber streams facing accreditation body backlogs. Distribution runs through regional converting clusters co-located with North Rhine-Westphalia logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Kraft Paper SOS Bag Market sits in early-cycle expansion as EU single-use plastic directives force substrate conversion across checkout infrastructure ahead of enforcement deadlines.
For Market Incumbents: Compound FSC Chain of Custody certification advantages by accelerating water-based barrier coating R&D before REACH compliance windows narrow. Threat from Asian imports of machine-finished kraft paper necessitates backward integration into recycled fiber processing to defend margin position. Priority lever: captive pulp supply agreements with Austrian and German mills. For New Entrants and Emerging Players: Anchor in Iberia's underweighted converting capacity relative to retail density, where Smurfit Kappa networks leave service gaps in Barcelona-Madrid corridors. White-space targets include quick-service restaurant flat-bottom conversion to square-bottom upgrades and Nordic gusseted format specialty retail. Go-to-market angle: blockchain-tracked batch documentation for French hypermarket procurement cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pulp-to-bag operators with captive fiber supply and long-term retail offtake agreements. Five-to-ten year viability favors backward-integrated mid-caps over merchant paper traders exposed to OCC volatility. Acquisition target archetype: regional converters with FSC accreditation proximity and underutilized SOS machine capacity. Signal to watch: PEFC certification processing delays as inflection indicator for supplier qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain of Custody Certification | Pan-European grocery alliances now mandate real-time documentation through blockchain-tracked batch records. |
| Water-Based Barrier Coating R&D | German discount grocers pilot these formulations for private-label seafood lines under REACH compliance pressure. |
| Backward Integration into Recycled Fiber | Mill investments in high-strength kraft pulping require eighteen-to-twenty-four month commissioning cycles. |
| Iberia Converting Network Expansion | Barcelona and Madrid distribution hubs service southern European export routes with limited regional competition. |
| Quick-Service Restaurant Format Conversion | Bakery channels present upgrade potential from flat-bottom to square-bottom formats with print branding capabilities. |
Research Methodology
Cross-validation between converter production data and retail procurement records anchors the qualitative findings in this study. Primary interviews with bag machine operators, FSC certification auditors, grocery category buyers, and pulp mill technical directors combined with secondary validation from EU REACH regulatory filings, FSC/PEFC accreditation databases, and German packaging regulator EPR fee schedules. Bottom-up capacity assessments and top-down retail spend estimates triangulate market sizing.
Sensitivity analysis across recycled fiber price scenarios and certification adoption rates tests forecast robustness. The analytical framework models product type, end user, size tier, and closure mechanism dimensions over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by regional retail density and automation penetration. Industry-specific inputs include SOS machine installation counts and EU single-use plastic directive implementation timelines.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions on FSC certification processing speeds and OCC bale price normalization. Revision becomes warranted when extended producer responsibility fee structures cross threshold adjustments or when water-based barrier coating technical validation fails commercial scale-up.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market