
 Paper Canisters Market | 2026-2036
Paper Canisters Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Canisters Market Analytics
The EU Green Deal is repositioning paper canisters as the default rigid packaging format for dry goods and nutritional supplements across European retail channels. Mondi leverages its integrated pulp-to-packaging footprint to secure long-term supply contracts with pan-European grocery retailers. Sonoco sustains technology leadership through precision spiral-winding equipment that tightens dimensional tolerances for pharmaceutical applications. Stora Enso anchors Nordic supply security via its captive forestry and recycled fiber streams.
Paper canisters are cylindrical containers manufactured from laminated paperboard layers wound helically around a mandrel, typically incorporating aluminum or polymer barrier films to achieve moisture and oxygen resistance for shelf-stable contents. Their primary commercial purpose centers on replacing composite metal and all-plastic rigid packaging with fiber-dominant alternatives that maintain product protection while improving end-of-life recyclability. Rigid canisters dominate current volume owing to established tooling and filling-line compatibility across food and personal care sectors. Specialty canisters represent the fastest-expanding category as brands commission bespoke geometries and premium print finishes for gift and promotional applications.
EMA packaging guidelines, EU REACH chemical compliance frameworks, and F-Gas Regulation restrictions on fluorinated barrier technologies collectively shape material selection and migration-testing protocols for pharmaceutical and food-contact grades. FDA food-contact notification requirements and EPA sustainable materials management priorities extend parallel compliance obligations for North American suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and pending packaging-waste directives that will determine which barrier configurations retain market access.
Market Dynamics
EU Green Deal packaging directives are forcing material substitution decisions across European dry goods supply chains, converting single-use plastic volume into fiber-based rigid formats ahead of 2030 waste-reduction targets.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for single-use plastics are redirecting dry goods and nutritional supplement volumes toward fiber-dominant canister formats across German, French, and Benelux retail channels.
- Spiral-winding precision advances:Tighter dimensional tolerances now match pharmaceutical filling-line specifications, opening prescription and over-the-counter drug applications previously reserved for metal and composite containers.
- German retail procurement criteria:Sustainability scorecards at major grocery chains now weight recyclability and recycled content above unit cost, accelerating vendor qualification for paper-based rigid packaging.
Market Restraints
- Aluminum barrier film cost volatility:Laminated oxygen and moisture barriers depend on metalized film inputs whose pricing tracks commodity aluminum markets, compressing margin stability for mid-tier converters.
- Nordic pulp supply concentration:Captive forestry operations in Sweden and Finland control premium kraft fiber availability, creating bottleneck risk for non-integrated packaging producers elsewhere in Europe.
- F-Gas Regulation barrier restrictions:Pending limits on fluorinated chemistries threaten current high-performance grease and vapor barrier formulations, forcing R&D redirection without guaranteed replacement efficacy.
Strategic Opportunities
- Polish and Romanian retail expansion:Underpenetrated Central European markets lack established rigid packaging supply bases, creating first-mover advantage for spiral-winding capacity positioned near Warsaw or Bucharest distribution hubs.
- Pharmaceutical serialization integration:Track-and-trace compliance requirements are converging with anti-counterfeiting print technologies, enabling premium-positioned canisters that embed verification codes directly into helical wound structures.
- Extended Producer Responsibility incentives:France and Italy are advancing modulated fee structures that reward higher recycled content, tilting total cost of ownership toward fiber-based formats in competitive tenders.
Industry Challenges
- Migration testing protocol complexity:EFSA and national food-contact regulators demand substance-specific migration studies for each barrier film and adhesive combination, extending new product qualification timelines.
- Legacy filling-line retrofit requirements:Pharmaceutical and food manufacturers operate metal and plastic canister equipment with tight tolerance bands, requiring mandrel diameter standardization negotiations before volume conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Canisters Market |
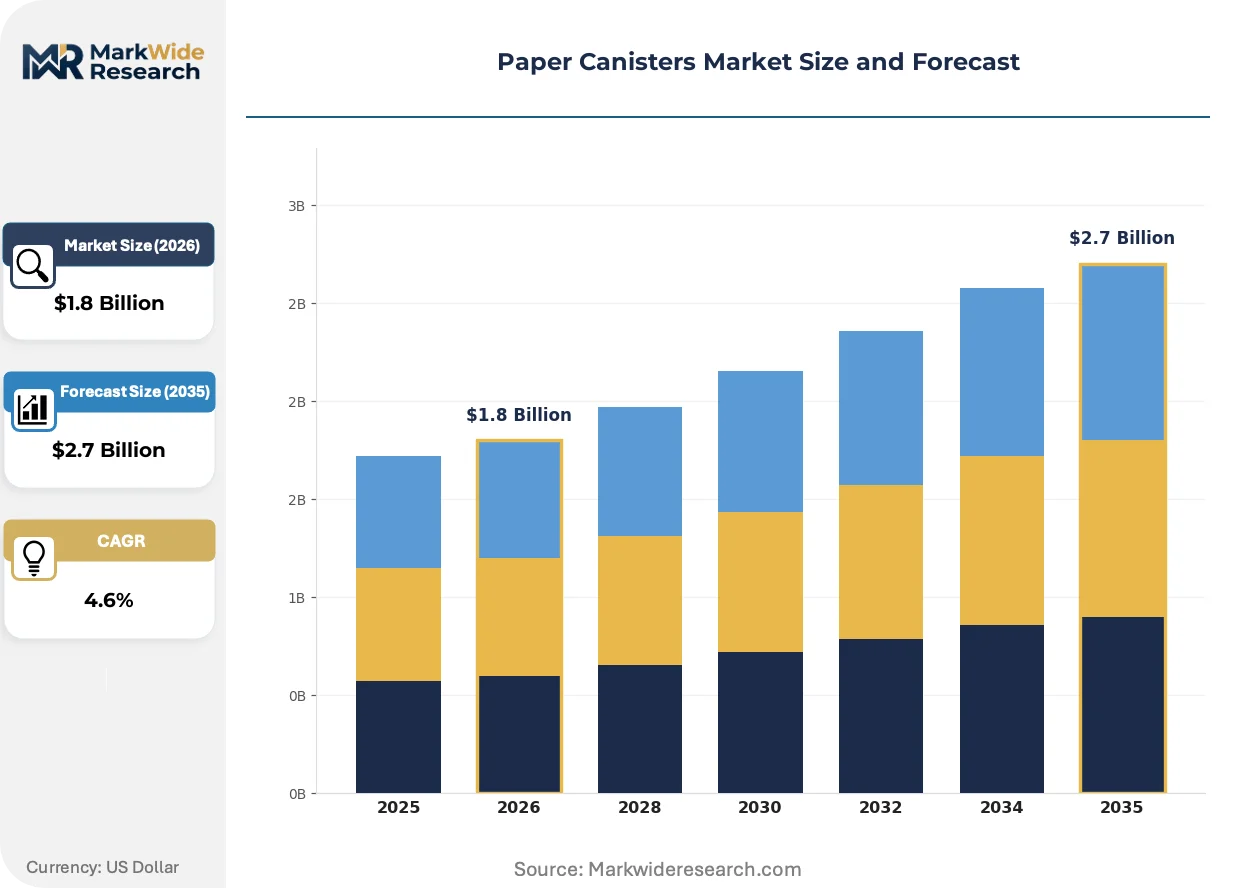
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Canisters, Flexible Canisters, Specialty Canisters, Custom Canisters End User: Food Industry, Pharmaceutical Companies, Beverage Sector, Personal Care Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Supermarkets Application: Storage Solutions, Packaging Materials, Promotional Items, Eco-Friendly Products |
| Companies Covered | Oji Holdings, Mondi, International Paper Co., Graphic Packaging International, Packaging Corporation of America, WestRock, Stora Enso, Sonoco, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Canisters Market Evolving Landscape
Barrier technology evolution and regulatory chemistry restrictions are converging to redefine material stacks, while buyer procurement centralization is compressing vendor qualification cycles across European retail and pharmaceutical channels.
Water-based polymer barrier coatings are expanding into high-moisture food applications previously blocked to unprotected fiberboard. Snack and confectionery packagers in Germany and the Netherlands are piloting these formulations at commercial scale. The technology is expanding into shelf-stable categories that historically required aluminum laminates, collapsing the performance gap between fiber-dominant and composite structures.
EU F-Gas Regulation phase-down schedules are eliminating per- and polyfluoroalkyl substance barriers from food-contact approval pathways by 2026. ECHA restriction proposals under REACH are accelerating substitution R&D across converter laboratories. Pharmaceutical and grease-resistant food segments face the steepest compliance cliffs, driving partnership formations between chemical suppliers and spiral-winding equipment manufacturers.
Pan-European grocery retail consolidation is compressing supplier panels and extending contract durations. Buyers at German and French headquarters now mandate sustainability certifications and recycled-content verification through centralized procurement functions. Poland and Spain represent the most visible geography where local packaging vendors face exclusion from expanded framework agreements without EMAS or comparable environmental management credentials.
Paper Canisters Market Segmentation
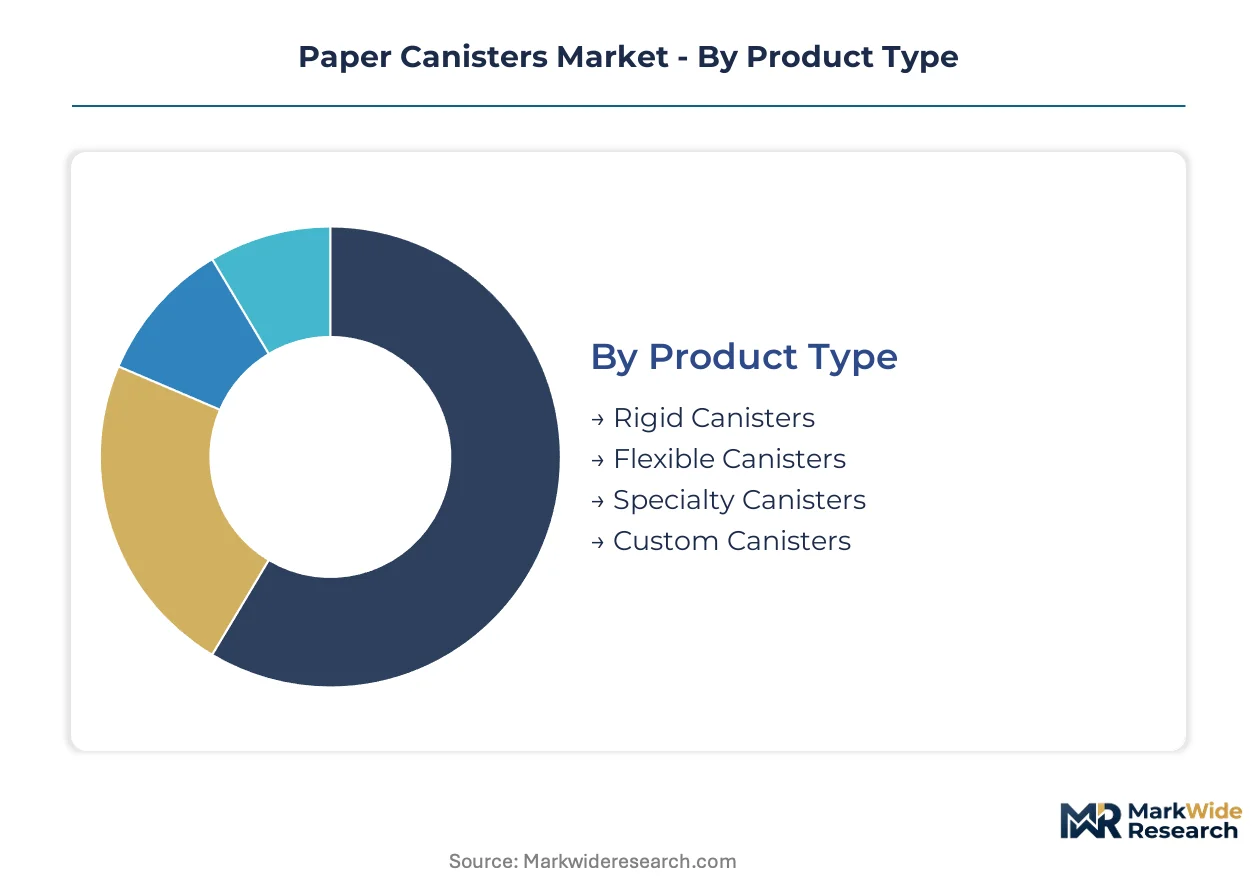
Paper canister segmentation reveals how buyer priorities split across performance requirements, regulatory compliance, and channel economics. Each dimension carries distinct margin structures and vendor qualification barriers that reshape competitive positioning.
Product Type:
Buyers select formats based on filling-line compatibility, barrier performance needs, and premium positioning requirements.
- Rigid Canisters:Helically wound paperboard with aluminum or polymer barrier laminates delivers dimensional stability for high-speed food and pharmaceutical filling lines. German retail chains specify these for dry goods and nutritional supplements under EU Green Deal procurement mandates.
- Specialty Canisters:Bespoke geometries and premium print finishes serve gift, promotional, and limited-edition applications. Brands in France and Italy commission these formats to differentiate shelf presence in consolidated retail environments.
- Flexible Canisters:Collapsible fiber structures reduce empty transport volume for e-commerce fulfillment.
- Custom Canisters:Engineered specifications for unique mandrel diameters or proprietary closure systems.
Rigid canisters lead on scale; specialty canisters lead on momentum.
End User:
Regulatory exposure and sustainability procurement criteria determine vendor selection intensity across buyer categories.
- Food Industry:Snack, confectionery, and dry goods packagers dominate order volumes. EFSA migration-testing protocols and national food-contact regulations in Germany and the Netherlands extend qualification timelines for new barrier formulations.
- Pharmaceutical Companies:Prescription and over-the-counter drug applications demand precision spiral-winding tolerances matching legacy metal canister equipment. EMA packaging guidelines and serialization requirements add compliance layers that filter supplier panels.
- Beverage Sector:Powdered drink mixes and nutritional formulations drive moisture-barrier specifications.
- Personal Care:Cosmetics and wellness brands prioritize premium finishes and tactile substrates.
Food industry buyers anchor volume; pharmaceutical qualification barriers protect margin.
Distribution Channel:
Channel selection reflects order scale, customization depth, and buyer supply chain integration.
- Wholesale Distributors:Pan-European packaging distributors aggregate demand from mid-sized food and personal care manufacturers. These intermediaries stock standard mandrel sizes and barrier configurations, compressing lead times for buyers without direct mill relationships.
- Direct Sales:Large grocery retailers and pharmaceutical multinationals negotiate multi-year supply agreements directly with integrated producers. Mondi and Stora Enso leverage captive fiber supply to secure these frameworks.
- Online Retailers:Digital procurement platforms serve small-batch and custom orders.
- Supermarkets:Private-label packaging specifications flow through retail headquarters procurement functions.
Direct sales concentrate value; wholesale distributors extend geographic reach.
Application:
Functional purpose shapes material stack complexity and end-of-life recyclability positioning.
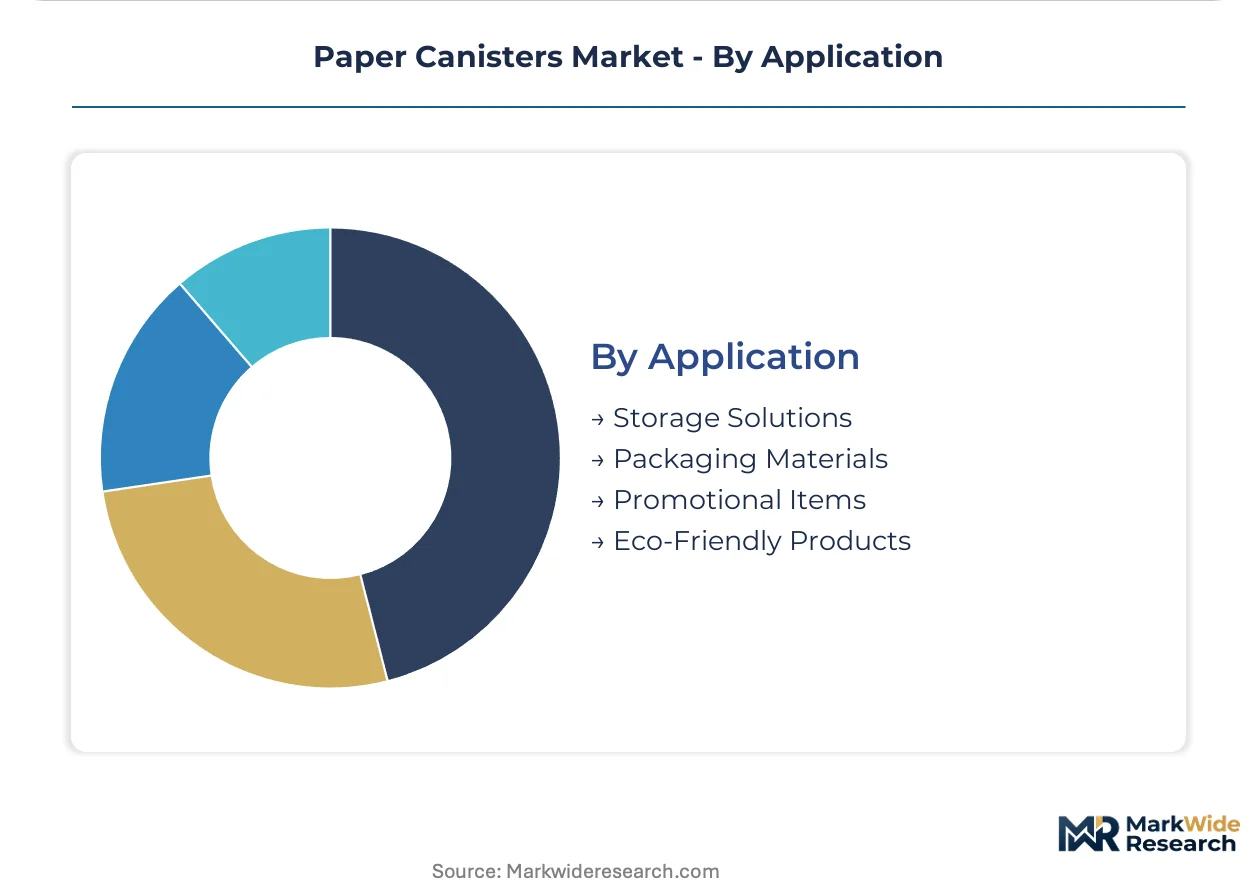
- Packaging Materials:Primary containment for shelf-stable goods requires laminated barrier films to achieve oxygen and moisture resistance. Water-based polymer coatings are displacing aluminum laminates in German and Dutch pilot programs.
- Eco-Friendly Products:Fiber-dominant formats with recyclable or compostable barrier systems target extended producer responsibility incentives. France and Italy are advancing modulated fee structures that reward higher recycled content in competitive tenders.
- Storage Solutions:Reusable canister designs for household organization and bulk goods.
- Promotional Items:Limited-run formats for marketing campaigns and seasonal releases.
Packaging materials dominate revenue; eco-friendly positioning gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper canister manufacturing traces its industrial lineage to European spiral-winding innovations developed in Germany and the Nordic countries during the mid-twentieth century. These technical foundations established quality benchmarks that persist in today's barrier-laminated formats. Contemporary demand geography reflects both this heritage and accelerating substitution mandates across multiple regulatory jurisdictions.
Germany
Retail chain sustainability scorecards now weight recyclability above unit cost in vendor qualification protocols. The EU Green Deal packaging directives enforce binding single-use plastic reduction targets that redirect dry goods volumes toward fiber-dominant formats. Major grocery headquarters in Munich and Hamburg centralize procurement decisions that cascade across Central European supplier panels.
France
Extended producer responsibility schemes advance modulated fee structures rewarding higher recycled content in competitive tenders. ANSM pharmaceutical packaging guidelines intersect with EMA requirements to create layered compliance frameworks for prescription drug applications. Industrial clusters around Lyon and the Paris Basin host converter operations specializing in premium print finishes for limited-edition promotional formats.
United States
FDA food-contact notification requirements and EPA sustainable materials management priorities shape barrier film selection for nutritional supplement packagers. Midwestern manufacturing corridors in Illinois and Wisconsin maintain legacy spiral-winding capacity serving North American dry goods brands. Water-based polymer barrier pilot programs in the Netherlands and Germany inform technology transfer discussions with US converters.
Poland
Underpenetrated Central European retail channels lack established rigid packaging supply bases near Warsaw distribution hubs. EU cohesion fund infrastructure investments improve logistics connectivity to German and Benelux procurement networks. Poznan and Wroclaw industrial zones attract first-mover spiral-winding capacity positioning for expanded framework agreements.
Sweden
Captive forestry operations control premium kraft fiber availability that anchors Nordic supply security. Stora Enso's integrated pulp-to-packaging footprint leverages this resource concentration for long-term European retail contracts. Gothenburg and Sundsvall production complexes export barrier-laminated substrates to converters lacking backward integration into fiber supply.
Paper Canisters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology sophistication and captive fiber access. The market structure organizes into three discernible tiers: integrated forest products groups with pulp-to-packaging control, specialized spiral-winding converters with precision pharmaceutical capabilities, and regional fabricators serving standard dry goods specifications. Strategic archetypes include sustainability-credentialed suppliers winning retail framework agreements, precision specialists qualifying for drug-contact applications, and scale operators amortizing equipment across high-volume food contracts. Dominant competitive moves encompass geographic expansion into underpenetrated Central European markets and technology licensing partnerships addressing F-Gas Regulation barrier substitution requirements.
Within the integrated forest products tier, Mondi and Stora Enso exemplify archetypes combining captive fiber supply with pharmaceutical-grade barrier lamination capabilities. Sonoco occupies a distinct position among precision spiral-winding specialists, representing the technology leadership segment that matches dimensional tolerances to legacy metal canister filling-line specifications. These three anchors demonstrate how competitive positioning splits between upstream resource control and downstream application engineering.
| Leading Market Players |
|---|
| Oji Holdings |
| Mondi |
| International Paper Co. |
| Graphic Packaging International |
| Packaging Corporation of America |
| WestRock |
| Stora Enso |
| Sonoco |
| Smurfit Kappa Group |
| Others |
Value Network & Pricing Analysis
Spiral-winding machine operators concentrated in Germany's Baden-Württemberg region command wage premiums that compress margin spreads between premium pharmaceutical-grade and standard food-grade canister tiers. Labor-cost differentials between Nordic integrated producers and Central European converters amplify pricing stratification across the three quality levels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by barrier complexity and regulatory certification. Price differentiation hinges on EMA pharmaceutical compliance tier and captive kraft fiber access. Cost compression in the economy tier is intensifying because aluminum laminate volatility transfers directly to converter margins. Pharmaceutical multinationals exhibit lowest price sensitivity; mid-sized dry goods packers in Poland and Romania show highest elasticity.
Supply Chain Analysis
Direct-to-retail channels handle German and French grocery chain demand through multi-year framework agreements with integrated producers. Geographic supply concentration centers on Sweden, Finland, and Germany where captive forestry and precision winding capabilities cluster. Raw material dependencies draw from Nordic kraft pulp, metalized aluminum films, and water-based polymer coatings. Single-source vulnerability in premium kraft fiber creates bottleneck exposure for non-integrated converters. Distribution runs through pan-European packaging distributors stocking standard mandrel configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper canisters represent a late-cycle quality story as EU Green Deal mandates force substitution toward fiber-dominant formats with verified recyclability credentials. Pharmaceutical serialization requirements and EMA compliance tiers are shifting procurement toward premium specifications that reward barrier technology leadership.
For Market Incumbents: Anchor long-term supply security through backward integration into Nordic kraft pulp streams or binding offtake agreements with Stora Enso and Mondi. Defend pharmaceutical qualification moats by investing in precision spiral-winding tolerance capabilities that match legacy metal canister equipment. Water-based polymer barrier R&D partnerships with chemical suppliers address F-Gas Regulation substitution cliffs before 2026 compliance deadlines. For New Entrants and Emerging Players: The 40-60% price-point gap between premium pharmaceutical and economy food-grade tiers creates entry space for mid-tier specialists. Target Polish and Romanian retail expansion where underpenetrated channels lack established rigid packaging supply bases near Warsaw and Bucharest distribution hubs. Lead with EMAS environmental management certification to qualify for centralized procurement panels at German grocery headquarters. For Investors and Strategic Acquirers: Valuations sit cheapest among regional food-grade converters without pharmaceutical qualification or captive fiber access. Five-to-ten year viability favors integrated forest products groups and precision specialists with drug-contact approvals. Watch EFSA migration-testing protocol streamlining as the inflection signal that compresses new product qualification timelines and accelerates barrier formulation substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber access locks in margin stability against Nordic supply concentration. |
| Water-Based Polymer Barrier Scale-Up | Pilot programs in Germany and Netherlands validate aluminum laminate displacement. |
| Pharmaceutical Serialization Integration | Track-and-trace compliance enables premium positioning in prescription drug channels. |
| Central European Capacity Positioning | Warsaw and Bucharest proximity captures Polish and Romanian retail expansion. |
| EMA Compliance Tier Investment | Drug-contact qualification filters supplier panels and protects pricing power. |
Research Methodology
Direct dialogue with spiral-winding equipment manufacturers, converter plant managers, pharmaceutical packaging procurement leads, German grocery chain sustainability officers, and EFSA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EU packaging directive filings, EMA packaging guidelines, FEFCO industry statistics, and Nordic forestry export data. Bottom-up demand modeling across food, pharmaceutical, and personal care segments triangulated against top-down macroeconomic drivers.
Segment-level volume and value trajectories emerged from mandrel diameter specifications, barrier film configurations, and end-use qualification tiers across the projection horizon. Analytical framework modeled product type, end-user industry, distribution channel, and application dimensions. CAGRs derived from substitution elasticity estimates tied to EU Green Deal plastic reduction mandates and pharmaceutical serialization compliance deadlines.
Caveats apply where F-Gas Regulation phase-down schedules, aluminum commodity volatility, or EFSA migration-testing protocol revisions could materially shift the outlook. Forecasts embed assumptions regarding barrier technology substitution timelines and Central European retail channel penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market