
 United States Corrugated Packaging Market | 2026-2036
United States Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Corrugated Packaging Market Analytics
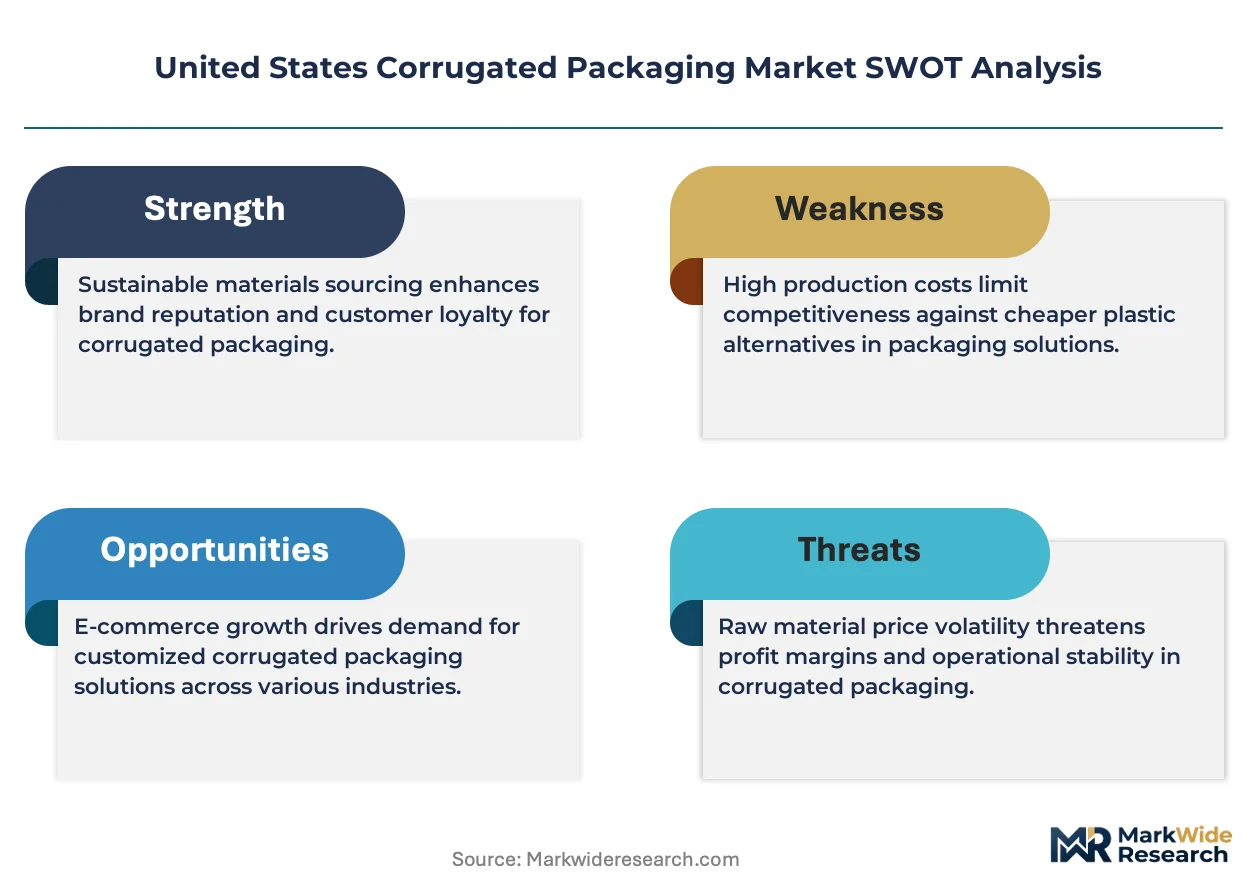
The EPA's recycled fiber content mandates for paper-based packaging is expanding compliance-driven demand across the corrugated value chain. WestRock Company leverages integrated pulp-to-box operations across the Southeast to sustain cost advantages in virgin and recycled linerboard. International Paper Company anchors national supply through its extensive containerboard mill network, while Packaging Corporation of America specializes in lightweight, high-performance board grades for e-commerce shippers. Georgia-Pacific LLC competes through geographic dominance in the South-Central states, where it controls access to both forest fiber and major logistics corridors.
Corrugated packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed in A-flute, B-flute, C-flute, or E-flute profiles with basis weights ranging from twenty-six to ninety pounds per thousand square feet, engineered to absorb compression and impact forces during transit. Its primary purpose is to protect goods through distribution networks while providing stackable, printable surfaces for branding and handling instructions. Single-wall and double-wall configurations lead volume due to their cost-efficiency in standard shipping applications, though triple-wall demand is accelerating in heavy industrial segments where load-bearing requirements exceed conventional limits. The food and beverage end-user channel commands the largest share of fiber consumption, while the electronics segment generates premium margin pools through anti-static and precision-fit insert specifications.
The EPA regulates wastewater discharge and air emissions from containerboard mills under Clean Water Act and Clean Air Act provisions, while OSHA sets exposure limits for dust and chemical hazards in converting facilities. The USDA's bio-preferred program and state-level extended producer responsibility frameworks in California and New York further shape material sourcing decisions and recyclability claims. Stakeholders must monitor how state packaging EPR legislation evolves, as fragmented compliance obligations will determine regional mill investment patterns and converter site selection.
Market Dynamics
The EPA's recycled fiber content mandates are compressing virgin linerboard demand while redirecting capital toward post-consumer fiber processing infrastructure across the Great Lakes manufacturing belt.
Growth Catalysts
- E-commerce fulfillment density:Protective shipping formats for electronics and consumer goods are pulling volume through Midwest distribution hubs clustered near containerboard mills.
- Extended Producer Responsibility frameworks:California and New York state legislation is mandating minimum recycled content thresholds, forcing converters to certify post-consumer fiber streams.
- Lightweight board engineering:High-performance micro-flute profiles are displacing heavier single-wall constructions in parcel post applications without sacrificing compression strength.
Market Restraints
- Old corrugated container price volatility:Post-consumer fiber input costs swing with municipal collection program funding and export demand from Asian packaging producers.
- Southeast mill concentration:Integrated pulp-to-box operations in Georgia and Alabama create geographic supply vulnerability to hurricane-related logistics disruptions.
- Plastic substitution threat:Reusable totes and flexible film envelopes are capturing share in apparel and soft-goods fulfillment where crush protection requirements are minimal.
Strategic Opportunities
- USDA BioPreferred program certification:Federal procurement preference for bio-based packaging opens institutional supply contracts for agricultural fiber corrugated alternatives.
- Anti-static precision inserts:Electronics manufacturing clusters in Texas and Arizona present unmet demand for electrostatic discharge-protective corrugated formats.
- Direct-to-factory digital printing:Inkjet technology convergence with board converting is enabling short-run branded packaging for craft beverage producers bypassing traditional label converters.
Industry Challenges
- Converting technician shortage:Rotary die-cutting and flexographic press operation require specialized training programs that community colleges have deprioritized.
- OSHA dust exposure compliance:Containerboard mill and converting facility ventilation upgrades demand capital deployment alongside fiber processing investments.
- Legacy enterprise resource planning integration:Real-time order-to-delivery tracking systems face friction with decades-old scheduling software at family-owned box plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Corrugated Packaging Market |
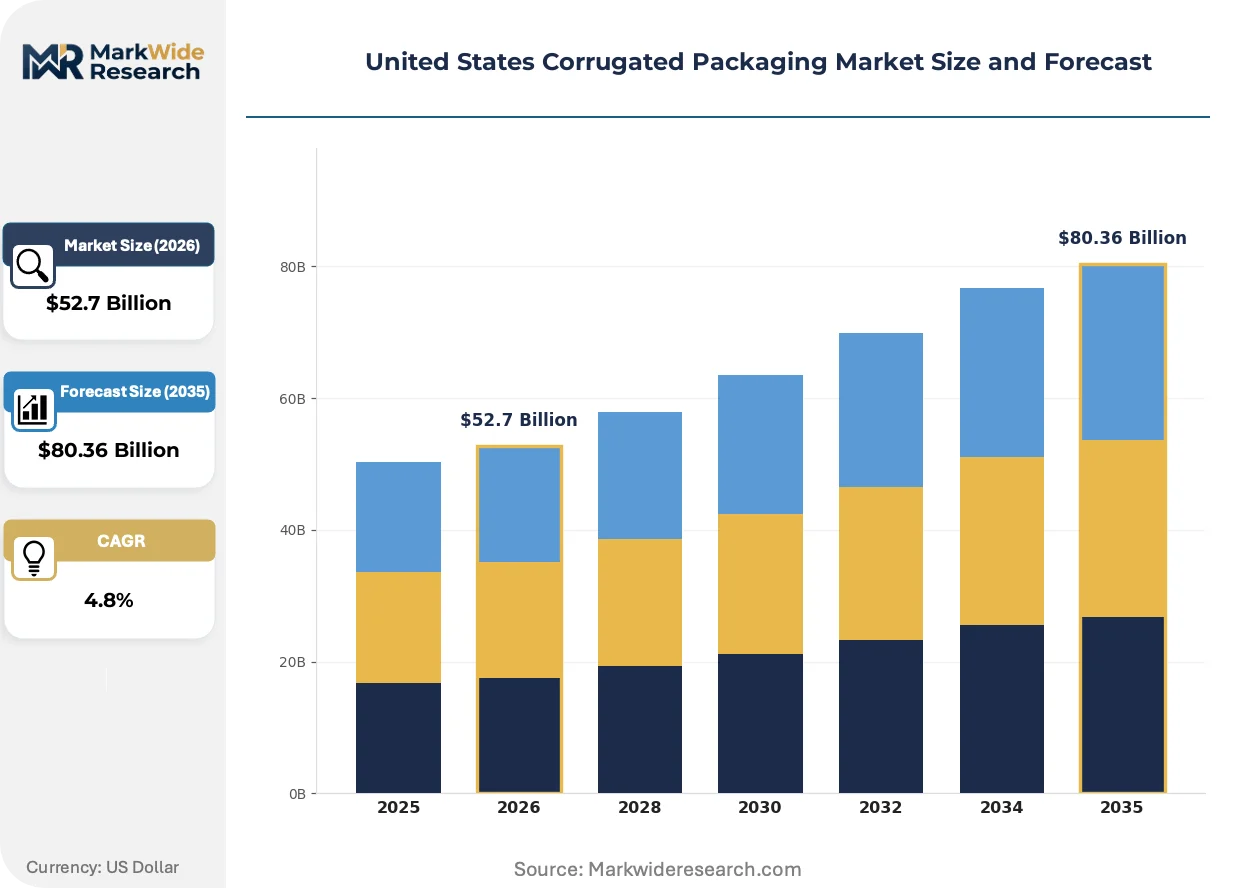
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Printed End User: Food & Beverage, Electronics, Cosmetics, Pharmaceuticals Application: Shipping, Retail Packaging, Storage, Display Material Type: Kraft, Recycled, Virgin Fiber, Others |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa, DS Smith, Packaging Corporation of America, Georgia-Pacific LLC, Mondi Group, Pratt Industries, Green Bay Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Corrugated Packaging Market Evolving Landscape
Digital printing integration, regulatory fiber mandates, and fulfillment automation are compressing production batch sizes while expanding customization capabilities across the value chain.
Water-based inkjet printing systems are decentralizing corrugated graphics production from centralized pre-print operations to individual converting facilities. Regional beverage and specialty food brands are adopting these systems for seasonal packaging with two-week turnaround requirements. This technology is decentralizing design-to-delivery timelines from months to days, compressing converter working capital cycles.
OSHA's updated permissible exposure limits for respirable crystalline silica and total dust are forcing containerboard mills to retrofit baghouse filtration and enclosed conveyor systems. Compliance investments are diverting capital from capacity expansion projects. Southern mill complexes face the steepest retrofit timelines due to aging infrastructure installed prior to 1990.
Shipper demand for right-size packaging is eliminating void fill and reducing dimensional weight charges in parcel networks. Automated box-sizing machinery is displacing manual case selection in high-volume e-commerce fulfillment centers. This behavioral shift concentrates most visibly in Ohio and Pennsylvania distribution corridors serving Northeast consumer markets.
United States Corrugated Packaging Market Segmentation
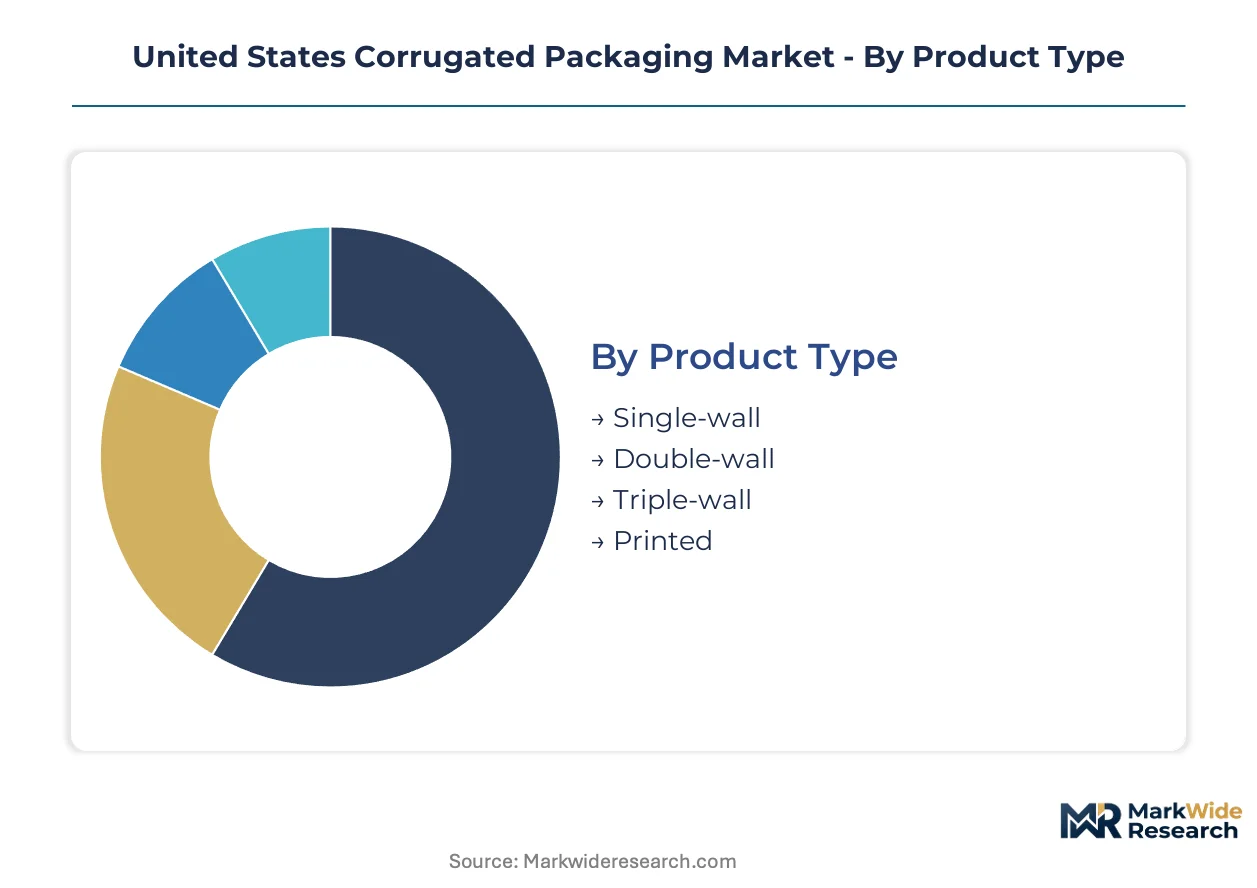
Corrugated packaging segmentation reveals how engineering specifications align with distinct fulfillment economics. Product architecture, end-use requirements, and material sourcing strategies each create divergent margin profiles and capital intensity thresholds across the value chain.
Product Type:
Flute profile and wall construction determine compression strength, stack height limits, and per-unit fiber consumption.
- Single-wall:One fluted medium between two linerboards, typically C-flute or B-flute profiles, dominates parcel post and standard shipping applications. Ohio and Pennsylvania distribution corridors pull the highest volumes as e-commerce fulfillment centers optimize for dimensional weight pricing.
- Double-wall:Two fluted layers separated by an intermediate linerboard deliver enhanced stacking strength for palletized distribution. Heavy industrial segments in Texas and Louisiana specify this construction for export shipments requiring extended transit durability.
- Triple-wall:Three fluted layers engineered for extreme load-bearing applications including automotive parts and machinery. Capital equipment manufacturers in Michigan and Illinois drive specification.
- Printed:Direct-to-substrate graphics capability enabling branded unboxing experiences and retail-ready presentation. Craft beverage producers in Colorado and Oregon adopt short-run digital workflows for seasonal rotations.
Single-wall leads on scale; printed leads on momentum.
End User:
Customer sector concentration shapes converter equipment configuration and certification requirements.
- Food & Beverage:FDA-compliant linerboard grades for direct food contact applications including produce trays and frozen pizza sleeves. California and Washington state processing facilities generate recurring demand for moisture-resistant coatings.
- Electronics:Anti-static and precision-fit insert specifications protecting semiconductors and consumer devices during transit. Manufacturing clusters in Arizona and Texas require electrostatic discharge certification.
- Cosmetics:Premium board surfaces and rigid box constructions for unboxing aesthetics and retail shelf presence. New York and Los Angeles brand headquarters influence packaging design standards.
- Pharmaceuticals:Serialization-ready formats and temperature-stable constructions for drug distribution compliance. FDA validation requirements extend production timelines.
Food & Beverage anchors volume; Electronics climbs the fastest on margin expansion.
Application:
Functional use case determines structural engineering priorities and graphic treatment intensity.
- Shipping:Protective transit formats optimized for compression strength and cube utilization. Midwest distribution hubs concentrate demand for automated box-sizing compatibility.
- Retail Packaging:Shelf-ready and point-of-purchase displays requiring high-graphics linerboard and die-cut features. Mass merchandisers in Arkansas and Minnesota dictate seasonal volume spikes.
- Storage:Archive and warehouse applications prioritizing long-term stacking stability over print quality. Industrial distributors in Georgia and North Carolina specify bulk quantities.
- Display:Temporary promotional structures with integrated headers and product cutouts. Beverage and snack brands deploy these for convenience store campaigns.
Shipping dominates tonnage; Display gains share fastest through retail media networks.
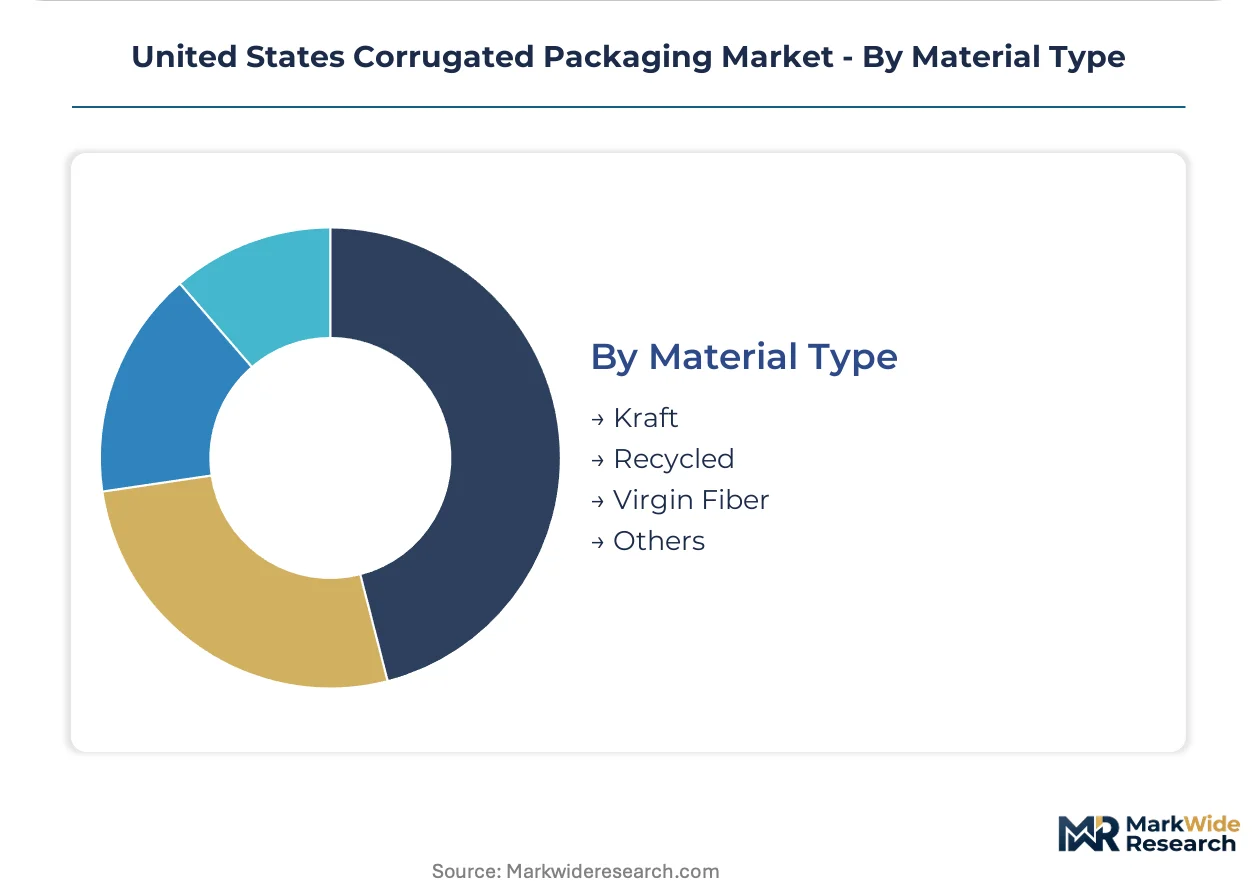
Material Type:
Fiber sourcing strategy balances cost position against regulatory compliance and customer sustainability mandates.
- Kraft:Unbleached virgin fiber delivering superior tear strength and printability for premium applications. Southeastern pulp mills supply Great Lakes converters through established rail corridors.
- Recycled:Post-consumer corrugated containers processed into linerboard and medium, subject to EPA recycled content thresholds. California and New York EPR frameworks accelerate procurement shifts.
- Virgin Fiber:Fresh pulp constructions for moisture-sensitive or food-contact applications requiring consistent fiber length. Integrated mill networks in Georgia and Alabama control cost position.
- Others:Agricultural fiber alternatives and hybrid constructions qualifying for USDA BioPreferred federal procurement preference. Emerging pilot programs in Iowa and Nebraska test wheat straw integration.
Recycled leads on policy tailwinds; virgin fiber retains structural performance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millwrights and corrugated technicians cluster in the Great Lakes manufacturing belt, where containerboard capacity and converting operations concentrate near Midwest distribution hubs. This workforce concentration anchors national supply chains for protective shipping formats.
Southeast
Pulp-to-box integration dominates capital deployment across Georgia and Alabama, where hurricane exposure creates logistics vulnerability. EPA Clean Air Act enforcement drives baghouse retrofits at aging mill complexes. Savannah and Charleston ports channel export linerboard to Latin American converters.
Midwest
Ohio and Pennsylvania distribution corridors generate dense demand for automated box-sizing compatibility in e-commerce fulfillment. State-level extended producer responsibility frameworks in neighboring New York redirect procurement toward certified post-consumer fiber streams. Detroit automotive parts manufacturers specify triple-wall constructions for machinery export.
West
California food processing facilities require FDA-compliant moisture-resistant coatings for produce and frozen goods. The state's packaging EPR legislation mandates minimum recycled content thresholds, forcing converters to document fiber provenance. Pacific Northwest craft beverage producers adopt short-run digital workflows for seasonal packaging rotations.
Southwest
Electronics manufacturing clusters in Arizona and Texas drive specification for electrostatic discharge-protective formats and precision-fit inserts. Semiconductor fabrication proximity creates demand for anti-static corrugated certification. Dallas-Fort Worth logistics hubs consolidate parcel post volume for Southwest consumer markets.
Mountain West
Agricultural fiber pilot programs in Colorado and Nebraska test wheat straw integration for USDA BioPreferred federal procurement qualification. Lower population density reduces municipal old corrugated container collection efficiency, elevating post-consumer fiber input costs. Denver distribution centers serve as relay points for Mountain time zone e-commerce delivery.
United States Corrugated Packaging Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light specialty converters for corrugated packaging contracts. The vendor base splits between multinational mill operators with captive pulp supply and independent box plants sourcing linerboard on the open market. Three archetypes dominate: integrated pulp-to-box conglomerates, regional converting specialists, and sustainability-focused post-consumer fiber processors. Competitive dynamics center on geographic mill placement for logistics advantage and lightweight board engineering for dimensional weight pricing compliance.
Among integrated producers, International Paper Company and WestRock Company exemplify scale-driven archetypes with extensive containerboard mill networks, while Packaging Corporation of America occupies a position emphasizing high-performance board grades. Georgia-Pacific LLC anchors South-Central geographic dominance through forest fiber access and corridor control. These named entities represent strategic positioning around virgin fiber integration, recycled content specialization, and regional logistics capture rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa |
| DS Smith |
| Packaging Corporation of America |
| Georgia-Pacific LLC |
| Mondi Group |
| Pratt Industries |
| Green Bay Packaging |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment center procurement teams in Ohio and Pennsylvania corridors anchor demand concentration for corrugated packaging, driving contract-based long-term offtake agreements that lock in volume commitments against Old Corrugated Container price volatility. This buyer concentration rewards integrated producers with captive fiber supply while squeezing independent converters exposed to spot market linerboard swings.
Pricing Analysis
Three-tier pricing structure across premium anti-static grades, standard single-wall constructions, and economy recycled-content tiers dominates the market. Price differentiation rests on flute profile engineering and EPA recycled content certification levels. Cost compression in standard single-wall grades is intensifying because lightweight board engineering displaces heavier constructions without sacrificing compression strength. Mass-market e-commerce shippers exhibit highest price sensitivity, while electronics manufacturers with anti-static requirements show lowest sensitivity due to precision-fit insert specifications.
Supply Chain Analysis
Direct-to-converter mill relationships handle high-volume Great Lakes demand, while distributor channels serve fragmented independent box plants. Geographic supply concentrates in Georgia, Alabama, and Wisconsin where containerboard mills cluster near pulp sources. Raw material dependencies draw from Southeastern pine pulp, Midwest post-consumer fiber streams, and Great Lakes water access for mill operations. Single-source vulnerability to hurricane-related logistics disruptions in the Southeast creates structural supply risk. Distribution runs through rail corridors linking mill complexes to Midwest distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States corrugated packaging market functions as a stable compounder anchored by e-commerce fulfillment infrastructure expansion that generates recurring protective shipping demand.
For Market Incumbents: Deepen backward integration into post-consumer fiber processing infrastructure across the Great Lakes manufacturing belt to secure EPA compliance advantage. Expand lightweight board engineering R&D to capture dimensional weight pricing optimization demand from Ohio and Pennsylvania fulfillment centers. Defend against plastic substitution threats in soft-goods segments by emphasizing crush protection specifications that flexible film cannot replicate. For New Entrants and Emerging Players: Digital printing equipment leasing routes offer lowest-capital entry into craft beverage and seasonal food segments requiring short-run branded packaging. Target Arizona and Texas electronics manufacturing clusters with anti-static certification capabilities that integrated producers underinvest in. Pursue USDA BioPreferred program qualification to access federal procurement contracts for agricultural fiber alternatives in Iowa and Nebraska pilot regions. For Investors and Strategic Acquirers: Private equity firms with packaging roll-up experience are the most active acquirer in this space, particularly targeting family-owned box plants with legacy ERP upgrade needs. Long-term viability centers on fiber sourcing flexibility and digital printing conversion capability as margin drivers. Watch California and New York EPR enforcement intensity as the inflection indicator for recycled content premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Fiber Processing Investment | EPA recycled content mandates in California and New York force compliance infrastructure deployment. |
| Lightweight Board Engineering R&D | High-performance micro-flute profiles capture dimensional weight pricing savings for e-commerce shippers. |
| Digital Printing Technology Integration | Inkjet systems enable two-week turnaround seasonal packaging for Colorado and Oregon craft beverage brands. |
| Anti-Static Certification Acquisition | Electrostatic discharge capabilities penetrate Arizona and Texas semiconductor manufacturing clusters. |
| USDA BioPreferred Program Qualification | Federal procurement preference opens institutional supply contracts for wheat straw fiber alternatives. |
Research Methodology
Bottom-up end-use demand modeling reconciled against top-down containerboard mill capacity tracking forms the analytical core of this study. Primary interviews with containerboard mill operations directors, corrugated converting plant managers, e-commerce fulfillment center procurement leads, and EPA compliance officers combined with secondary validation from EPA enforcement databases, OSHA permissible exposure limit filings, and USDA BioPreferred program records. Trade data from linerboard rail shipments and Old Corrugated Container pricing indices anchored supply-side calibration.
Input-output matrices map fiber flow from pulp sources through converting operations to end-use demand across the projection horizon. Segmentation dimensions modeled include flute profile construction, wall layer configuration, end-use vertical, and regional distribution corridor. CAGRs derive from compound growth trajectory analysis applied to e-commerce shipment volume correlations and recycled content mandate implementation schedules. Forecast inputs incorporate EPA enforcement intensity assumptions and lightweight board adoption curves in parcel post applications.
The model assumes a particular technology adoption path for digital printing integration; alternative pathways for inkjet convergence with board converting would alter the outlook. Forecasts reflect documented assumptions regarding EPR legislation expansion and post-consumer fiber collection efficiency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market