
 Saudi Arabia Paper and Paperboard Packaging Market | 2026-2036
Saudi Arabia Paper and Paperboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Paper and Paperboard Packaging Market Analytics
A shift from single-source imported board supply to multi-source domestic procurement is realigning how converters secure raw materials. United Carton Industries Company leverages its integrated mill-to-box operations to serve dairy and beverage accounts with shorter lead times. Middle East Paper Company anchors the recycled fiber segment with capacity geared toward corrugated medium and linerboard production. Tetra Pak Arabia competes through aseptic carton technology leadership and direct technical service ties to liquid food processors.
Paper and paperboard packaging encompasses containerboard, boxboard, and specialty paper grades formed through pulping, sheet forming, calendering, and converting operations into rigid or semi-rigid structures designed to protect, contain, and present goods during distribution and retail display. Corrugated containers dominate tonnage throughput due to e-commerce fulfillment expansion and bulk agricultural export requirements, while folding cartons command premium positioning in cosmetics and pharmaceutical blister packs where print fidelity and die-cut precision justify higher unit economics. Recycled paper feedstock now structures cost-competitive supply for brown-box applications, though coated paper grades retain preference in consumer goods segments where moisture resistance and graphic reproduction standards are non-negotiable.
SFDA mandates govern direct food-contact materials, requiring migration testing and substance inventories that shape converter qualification timelines and raw material sourcing decisions. SASO technical regulations for packaging materials and labeling, aligned with Gulf Standardization Organization frameworks, define market access criteria for both domestic producers and imported finished boxes. Stakeholders must monitor enforcement intensity around recycled content claims and extended producer responsibility consultations that could alter collection infrastructure investments and post-consumer fiber availability.
Market Dynamics
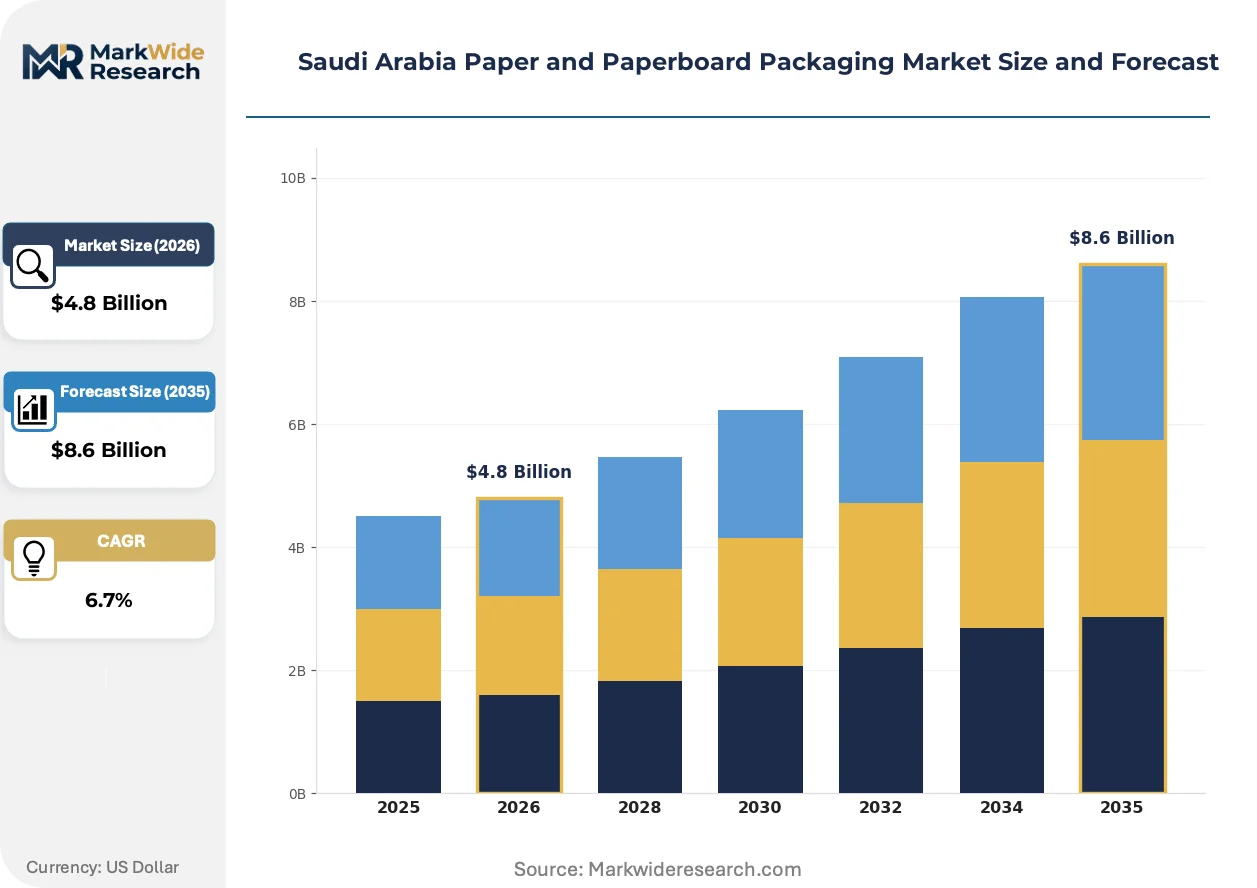
Saudi Vision 2030 industrial localization mandates are forcing converters to restructure raw material sourcing away from single-source imported board toward multi-source domestic procurement, compressing qualification timelines and reshaping mill-to-box supply relationships.
Growth Catalysts
- SFDA Food-Contact Compliance:Migration testing requirements for direct food-contact materials are accelerating converter investments in certified substrate inventories and laboratory partnerships.
- E-Commerce Fulfillment Expansion:Dairy, snack, and pharmaceutical processors in Riyadh and Jeddah industrial corridors are expanding corrugated container purchases for shelf-ready retail formats.
- Recycled Fiber Infrastructure:Domestic recycled paper feedstock capacity is structuring cost-competitive supply for brown-box agricultural export applications.
Market Restraints
- Imported Pulp Cost Volatility:Kraft linerboard and semi-chemical medium pricing fluctuates with global softwood pulp markets, squeezing converter margin buffers on fixed-price contracts.
- SFDA Qualification Timelines:Substance inventory documentation and migration testing protocols extend new supplier onboarding to 18-24 months, freezing sourcing flexibility.
- Plastic Flexible Substitution:Polyethylene pouches and multi-layer films are displacing folding cartons in moisture-sensitive snack and frozen food segments.
Strategic Opportunities
- Dammam Industrial City Expansion:Petrochemical and food processing clusters east of Riyadh remain underpenetrated by integrated boxboard converters with on-site sheeting.
- Saudi Vision 2030 Localization Incentives:Industrial development funds and preferential land allocation for domestic paperboard manufacturing are lowering capex barriers for greenfield mill investments.
- Aseptic Carton-Liquid Food Convergence:UHT dairy and juice processors are adopting direct-print gable-top formats that merge barrier coating technology with high-speed filling line integration.
Industry Challenges
- Migration Testing Talent Scarcity:Qualified analytical chemists capable of executing SFDA-mandated substance migration protocols are concentrated in Jeddah and Riyadh, constraining regional laboratory expansion.
- Legacy ERP Integration Friction:Converters upgrading to ISO-compliant quality management systems face data migration complexity with existing inventory modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Paper and Paperboard Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boxes, Corrugated Containers, Folding Cartons, Paper Bags End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Distribution Channel: Offline Retail, E-commerce, Wholesale, Direct Sales Material: Recycled Paper, Kraft Paper, Coated Paper, Others |
| Companies Covered | United Carton Industries Company, Obeikan Investment Group, Middle East Paper Company, Tetra Pak Arabia, NAPCO National, Gulf Carton Factory Company, Gulf East Paper & Plastic Industries LLC, Al Kifah Paper Products, Eastern Pak Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Paper and Paperboard Packaging Market Evolving Landscape
Digital printing and barrier coating technologies are converging with sustainability mandates to redefine converter capabilities, while regulatory enforcement intensifies around recycled content claims and extended producer responsibility frameworks.
Water-based barrier coatings are converging with digital inkjet printing systems to enable short-run customized folding cartons for cosmetics and pharmaceutical blister packs. Regional converters serving Riyadh-based dairy processors are piloting these lines for seasonal promotional formats. The technology convergence is compressing minimum order quantities from 50,000 units toward 5,000-unit runs.
SASO technical regulations for packaging materials and labeling, aligned with Gulf Standardization Organization frameworks, are tightening enforcement around recycled fiber content declarations and post-consumer sourcing documentation. Domestic corrugated medium producers must now maintain chain-of-custody records back to municipal collection points. Folding carton converters serving pharmaceutical accounts face the steepest compliance cost increases.
Buyer consolidation among Saudi dairy processors is compressing supplier rosters and extending contract durations from annual to multi-year frameworks. Regional co-manufacturers are responding by offering integrated design-to-delivery service bundles that merge structural engineering with direct-to-warehouse logistics. The shift is most visible in Jeddah's food and beverage manufacturing corridor.
Saudi Arabia Paper and Paperboard Packaging Market Segmentation
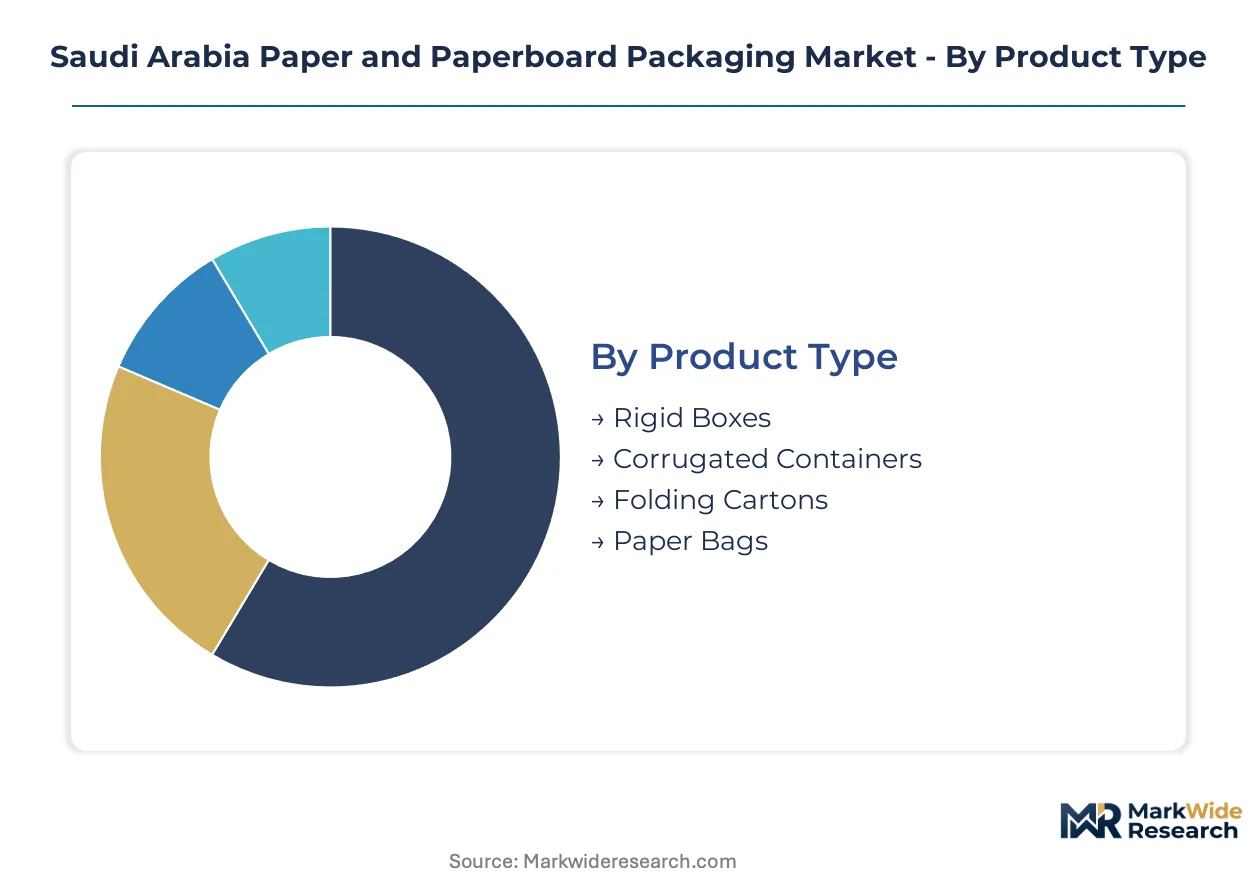
Converters in Saudi Arabia configure production lines around substrate specifications and end-use compliance requirements rather than generic volume tiers. Segmentation reveals how SFDA migration protocols and Vision 2030 localization mandates reshape procurement patterns across material grades and distribution channels.
Product Type:
Structural specifications determine converter capital allocation, with flute profiles and board grammage dictating line speed and die-cut precision capabilities.
- Corrugated Containers:Double-wall and triple-wall constructions with BC-flute combinations dominate agricultural export and e-commerce fulfillment applications. Riyadh and Jeddah industrial corridors concentrate demand from dairy processors expanding shelf-ready retail formats. SFDA-compliant kraft linerboard sourcing compresses converter margins on fixed-price contracts.
- Folding Cartons:SBS and CUK board grades with aqueous or UV coating systems serve pharmaceutical blister packs and cosmetics where print fidelity justifies premium unit economics. Jeddah-based converters pilot digital inkjet lines for 5,000-unit promotional runs. Water-based barrier coatings converge with direct-print gable-top formats for UHT dairy applications.
- Rigid Boxes:Thick paperboard laminates over rigid chipboard structures target premium cosmetics and gift packaging segments with hand-finished assembly requirements.
- Paper Bags:SOS and pinch-bottom constructions in recycled kraft serve grocery retail and quick-service food outlets with single-use regulatory pressures intensifying.
Corrugated containers lead on scale; folding cartons lead on momentum.
End User:
Customer procurement patterns split between compliance-driven qualification frameworks and cost-optimized volume contracting.
- Food & Beverage:Dairy, snack, and juice processors drive containerboard tonnage through aseptic carton adoption and corrugated shelf-ready formats. SFDA substance inventory documentation extends supplier onboarding timelines.
- Healthcare:Pharmaceutical manufacturers demand folding cartons with tamper-evident features and serialization compliance for blister pack applications.
- Consumer Goods:Cosmetics brands compress supplier rosters toward integrated design-to-delivery service bundles with direct-to-warehouse logistics.
- Electronics:Anti-static corrugated and foam-lined rigid boxes protect high-value components during last-mile distribution.
Food and beverage commands volume concentration; healthcare maintains the steepest compliance cost trajectory.
Distribution Channel:
Channel selection determines converter working capital intensity and inventory positioning requirements.
- E-commerce:Custom-sized corrugated with print-on-demand branding serves fulfillment centers requiring damage-resistant, right-sized packaging.
- Wholesale:Bulk agricultural exporters in Riyadh industrial corridors procure standard RSC containers through annual volume contracts.
- Direct Sales:Integrated mill-to-box operators like United Carton Industries compress lead times for dairy accounts through captive linerboard supply.
- Offline Retail:Supermarket chains specify shelf-ready packaging with retail-ready case counts and display-ready graphics.
E-commerce expands most quickly; wholesale retains contract stability.
Material:
Fiber sourcing strategies align with end-use barrier requirements and recycled content claim verification protocols.
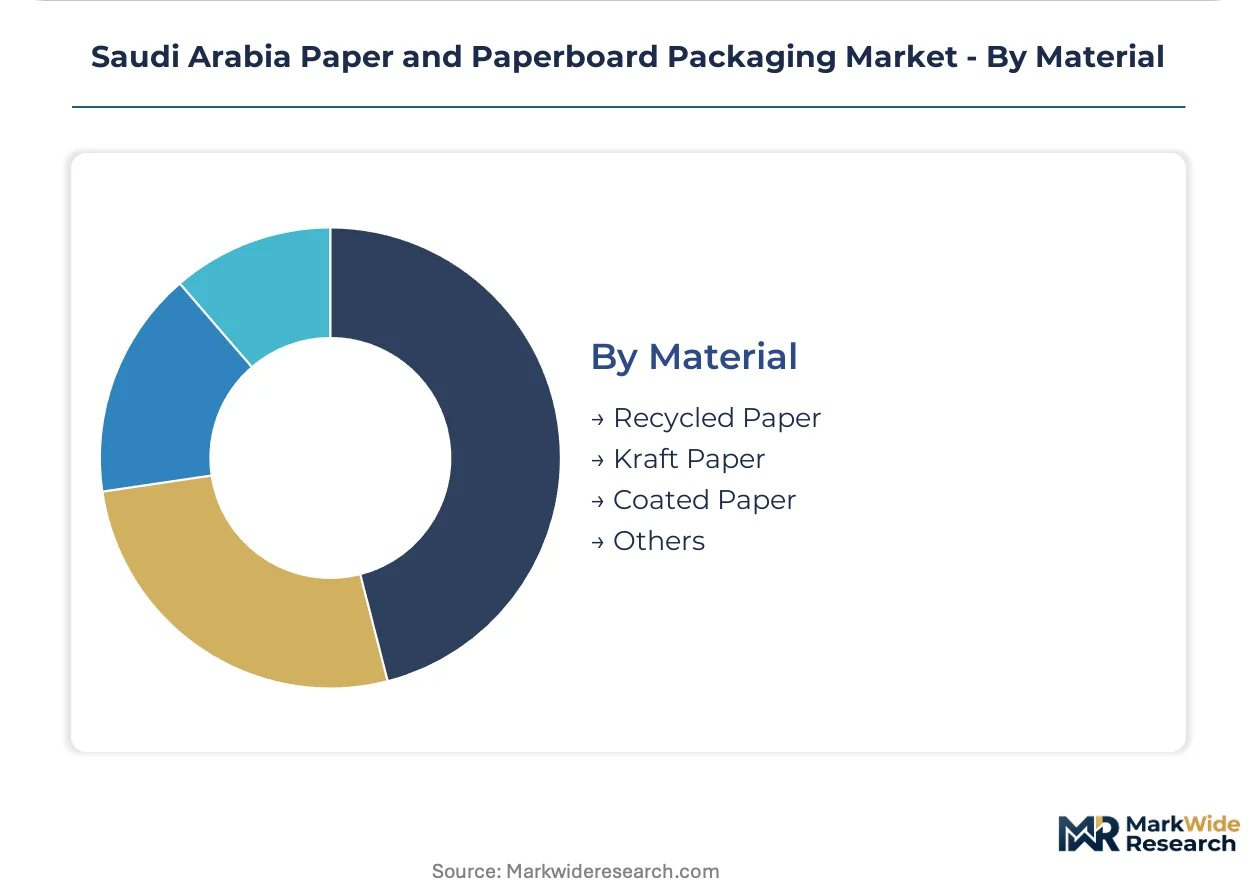
- Recycled Paper:OCC-based corrugated medium and linerboard from Middle East Paper Company supply brown-box agricultural exports. SASO chain-of-custody documentation requirements extend back to municipal collection points.
- Kraft Paper:Virgin unbleached softwood pulp provides tensile strength for heavy-duty shipping containers and direct food-contact applications.
- Coated Paper:Clay-coated SBS and CUK grades enable high-resolution lithographic printing for cosmetics and pharmaceutical folding cartons.
- Others:Specialty substrates including glassine, greaseproof, and molded fiber serve niche moisture-barrier and protective applications.
Recycled paper leads on volume; coated paper leads on margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting converter investment toward jurisdictions where SFDA compliance costs and Vision 2030 localization incentives create structural advantages for domestic board production over imported alternatives.
Riyadh
Dairy and snack processors in Riyadh's Second Industrial City drive containerboard demand through shelf-ready corrugated formats. SFDA substance inventory documentation requirements compress supplier qualification timelines to 18-24 months. Converter clusters near Al-Kharj Road leverage captive linerboard supply from integrated mill operations.
Jeddah
Pharmaceutical manufacturers in Jeddah's Al-Khomra district demand folding cartons with serialization compliance and tamper-evident features. SASO technical regulations for packaging materials align with Gulf Standardization Organization frameworks. Digital inkjet pilot lines serve cosmetics accounts with 5,000-unit promotional runs.
Eastern Province
Petrochemical and food processing clusters around Dammam remain underpenetrated by integrated boxboard converters with on-site sheeting capabilities. Industrial development funds under Vision 2030 lower capex barriers for greenfield mill investments. Agricultural exporters in Al-Ahsa procure double-wall corrugated for bulk shipment applications.
Western Region
UHT dairy and juice processors in Taif and Medina adopt direct-print gable-top formats merging barrier coating technology with high-speed filling lines. MOHAP-adjacent compliance frameworks in neighboring UAE create cross-border qualification complexity for converters serving dual markets. Regional co-manufacturers offer integrated design-to-delivery bundles.
Saudi Arabia Paper and Paperboard Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barrier-coating and digital-printing capabilities to escape commodity pricing pressure. The vendor base structures around three archetypes: integrated mill-to-box operators with captive fiber supply, independent converters dependent on merchant board, and technology-licensed specialists in aseptic formats. Dominant competitive moves include backward integration into linerboard production and strategic partnerships with dairy processors for multi-year supply contracts.
Within the integrated operator tier, United Carton Industries Company and Middle East Paper Company exemplify contrasting fiber strategies—virgin kraft versus recycled OCC-based corrugated medium. Tetra Pak Arabia occupies a distinct technology-licensed position serving liquid food processors with aseptic carton systems. These three anchors represent how SFDA compliance capabilities and Vision 2030 localization credentials now filter procurement decisions more than unit price alone.
| Leading Market Players |
|---|
| United Carton Industries Company |
| Obeikan Investment Group |
| Middle East Paper Company |
| Tetra Pak Arabia |
| NAPCO National |
| Gulf Carton Factory Company |
| Gulf East Paper & Plastic Industries LLC |
| Al Kifah Paper Products |
| Eastern Pak Limited |
| Others |
Value Network & Pricing Analysis
Kraft linerboard feedstock costs cascade through three distinct pricing tiers as converters balance SFDA-compliant virgin fiber against recycled OCC alternatives. Contract structures for dairy and pharmaceutical accounts compress margin buffers when global softwood pulp markets fluctuate, forcing integrated operators to prioritize captive supply over merchant board procurement.
Pricing Analysis
Input-cost pass-through from imported kraft pulp to finished corrugated containers operates on quarterly adjustment clauses with 60-90 day lags. Price differentiation separates SFDA-certified food-contact grades from standard industrial board, with migration testing documentation adding certification premiums. Pricing pressure stems from fixed-price annual contracts confronting spot pulp volatility, squeezing converter margins on agricultural export tonnage. Wholesale dairy processors exhibit highest price sensitivity due to volume scale and multi-year tender cycles, while pharmaceutical folding carton buyers prioritize print fidelity over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle integrated mill demand from Riyadh and Jeddah industrial corridors, while merchant board distributors serve independent converters with fragmented lot sizes. Geographic supply concentration draws from Saudi domestic mills, European kraft linerboard exporters, and Asian recycled fiber traders. Raw material dependencies center on softwood pulp, OCC recovered paper, and barrier coating chemicals. Supply chain risk manifests in single-source vulnerability for pharmaceutical-grade coated board. Distribution runs through mill-direct contracts for volume accounts and regional distributors for spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's paper and paperboard packaging market functions as a stable compounder anchored by Vision 2030 industrial localization mandates that structurally favor domestic capacity expansion over import dependency.
For Market Incumbents: To counter plastic flexible substitution in moisture-sensitive snack segments, integrated operators should deepen backward integration into linerboard production and secure multi-year supply contracts with consolidating dairy processors. Captive fiber supply and SFDA pre-qualified substrate inventories defend margin position against merchant-dependent competitors facing 18-24 month qualification timelines.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium pharmaceutical folding cartons and economy agricultural corrugated offers white-space entry for barrier-coating specialists targeting UHT dairy gable-top formats. Dammam Industrial City's underpenetrated petrochemical and food processing clusters present the most penetrable geography, with go-to-market execution through direct technical service partnerships rather than distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent converters lack SFDA laboratory partnerships and ISO-compliant quality management systems. The market reads as a long-term viable compounder over a multi-decade industrialization horizon, with acquisition targets clustering around mid-scale operators possessing Vision 2030 localization credentials but constrained by legacy ERP infrastructure. The signal to watch is enforcement intensity around extended producer responsibility frameworks that would alter post-consumer fiber availability economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linerboard Production | Captive kraft fiber supply compresses lead times for Riyadh dairy accounts and insulates margin buffers from pulp volatility. |
| SFDA Laboratory Partnership Investment | Migration testing capabilities in Jeddah and Riyadh accelerate supplier qualification timelines and lock in pharmaceutical accounts. |
| Digital Inkjet Printing Line Deployment | Short-run promotional carton capability serves cosmetics brands compressing supplier rosters toward design-to-delivery bundles. |
| Dammam Industrial City Greenfield Mill | Vision 2030 development funds lower capex barriers for integrated boxboard capacity serving underpenetrated Eastern Province demand. |
| Water-Based Barrier Coating R&D Program | Aqueous coating convergence with gable-top formats captures UHT dairy and juice processor adoption curves. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with converter operations managers, SFDA regulatory affairs specialists, dairy procurement directors, pharmaceutical packaging engineers, and corrugated line supervisors with secondary validation against SASO technical regulations, SFDA substance migration protocols, Gulf Standardization Organization frameworks, customs trade data for containerboard imports, and industrial development fund disclosures under Vision 2030. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures across the analysis window.
Comparable-period anchoring tied projection assumptions to historical demand patterns in Riyadh and Jeddah industrial corridors, with segmentation modeling across product type, end-user industry, material grade, and distribution channel dimensions. CAGRs derived from regression analysis of tonnage throughput against macro industrial output indicators, incorporating converter capex cycles, dairy processor expansion timelines, and pharmaceutical serialization compliance deadlines as industry-specific forecast inputs.
Caveats apply where SFDA enforcement intensity, global softwood pulp price shocks, or extended producer responsibility implementation could materially shift the outlook. Forecasts reflect documented assumptions about localization incentive continuity and import substitution trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market