
 Global Cooking and Baking Papers Market | 2026-2036
Global Cooking and Baking Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cooking and Baking Papers Market Foresight
Plant-based silicone coatings is narrowing the performance gap between conventional quilon-treated papers and premium fluoropolymer alternatives, forcing reformulation roadmaps across the supply base. Nordic Paper leverages its integrated pulp-to-paper operations in Scandinavia to sustain cost discipline on specialty greaseproof grades. Reynolds Consumer Products anchors North American shelf presence through dominant retail channel control and private-label partnerships. Mondi Group competes on coated-paper technical service, embedding food-safety compliance into customer specifications across European industrial bakeries.
Cooking and baking papers are cellulose-based substrates, typically 30–50 gsm, treated with silicone, quilon, or plant-derived release agents to withstand temperatures up to 220°C while preventing food adhesion. These papers serve as disposable, food-safe interfaces between prepared goods and heated surfaces in commercial and residential kitchens. Parchment paper occupies the largest value share among product types due to universal oven-baking utility and established consumer recognition, while silicone paper captures the fastest growth trajectory as quick-service restaurants specify higher release performance for high-throughput operations. Bakeries and food service providers represent the dominant end-user pool, with wholesale distributors and direct sales channels capturing margin concentration through volume contracts and just-in-time replenishment programs.
FDA food-contact substance notifications govern silicone and quilon coating approvals in the United States, while EU REACH and the F-Gas Regulation constrain fluorinated chemistry migration into European food-contact materials. These frameworks elevate compliance costs for imported papers and reward domestic producers with certified substrate-coating integration. Stakeholders must monitor regulatory divergence between North American and European release-agent approval pathways, as divergent substance restrictions threaten to fragment product specifications and complicate global sourcing strategies.
Market Dynamics
Fluorine-free barrier chemistry is forcing wholesale coating reformulation across the supply base as EU REACH and FDA food-contact rules harden substrate specifications simultaneously.
Growth Catalysts
- Quick-service restaurant expansion:Chains in the United States and China are specifying silicone-treated papers for high-throughput baking operations, pulling volume through wholesale distribution channels.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in food-contact materials is redirecting R&D investment toward plant-derived release agents and quilon alternatives.
- Home meal preparation persistence:Sustained residential baking activity in Germany and the United Kingdom is maintaining retail parchment paper velocity through supermarket private-label programs.
Market Restraints
- Pulp cost volatility:Hardwood and softwood fiber prices fluctuate with Nordic and Brazilian pulp mill output, compressing margins on uncoated base stock.
- Silicone supply concentration:Specialty silicone fluid production clusters in Germany and China create single-source vulnerability for coating operations.
- Performance ceiling of plant-based coatings:Current bio-barrier formulations fail to match fluoropolymer release performance above 200°C, limiting oven-grade applications.
Strategic Opportunities
- Indian food service penetration:Quick-service bakery chains in Mumbai and Bangalore remain underpenetrated by silicone-treated paper suppliers relative to China.
- Compostable certification tailwind:TÜV Austria and BPI compostability standards are creating premium positioning for certified home-compostable baking papers in European retail.
- Direct-to-bakery digital channels:E-procurement platforms are disintermediating traditional distributor relationships for mid-size industrial bakeries in France and Italy.
Industry Challenges
- Coating technician scarcity:Formulation chemists with dual expertise in food-contact compliance and silicone emulsion chemistry command premium compensation in Germany and Switzerland.
- Dual-certification timeline compression:Simultaneous FDA notification and EU REACH dossier preparation extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cooking and Baking Papers Market |
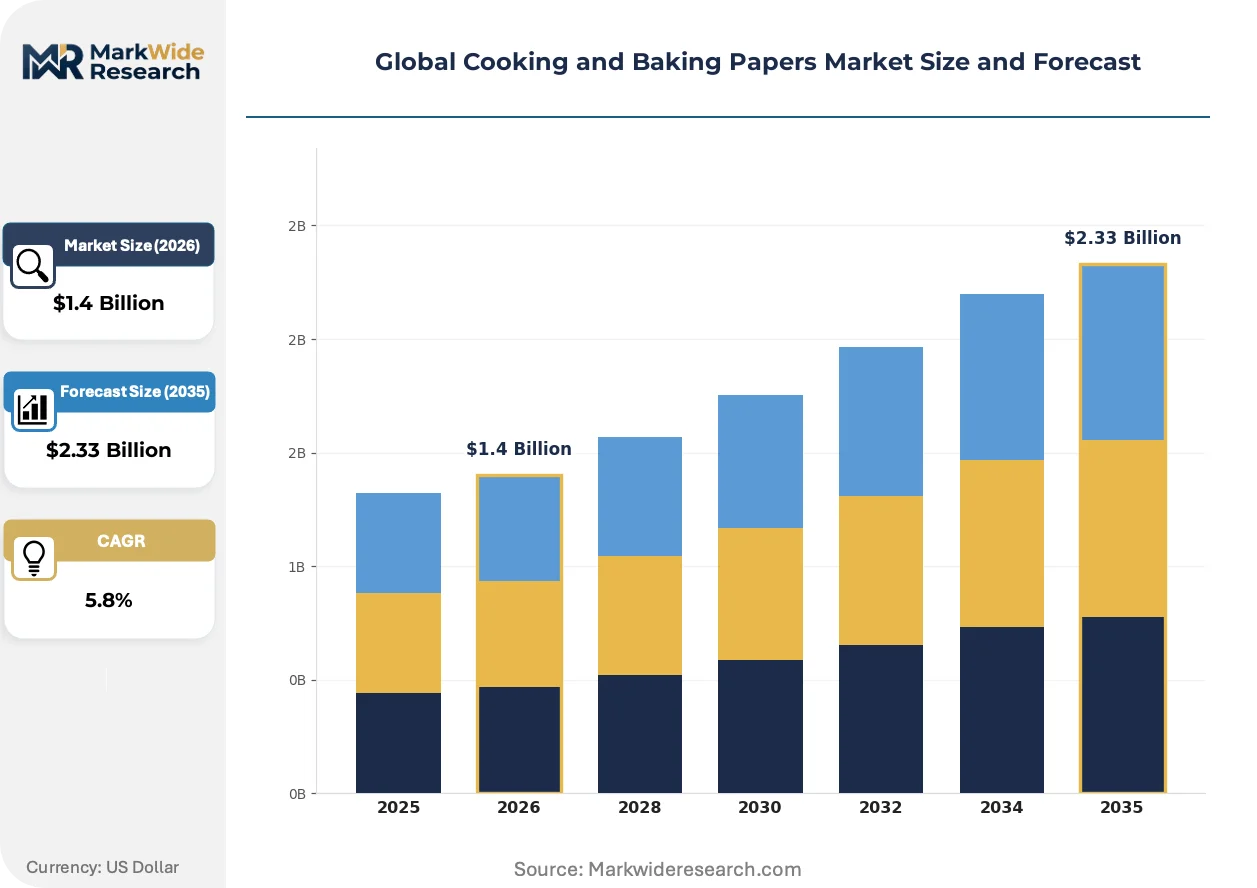
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parchment Paper, Wax Paper, Aluminum Foil, Silicone Paper, Butcher Paper, Greaseproof Paper Application: Oven Baking, Food Wrapping, Cake Decoration, Grill Lining, Microwave Cooking, Steaming End User: Bakeries, Food Service Providers, Catering Companies, Household Consumers, Cafés, Restaurateurs Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Nordic Paper, Reynolds Consumer Products, Mondi Group, Ahlstrom-Munksjö, Delfortgroup AG, Koninklijke Ahrend N.V., Stora Enso, Georgia-Pacific, Expera Specialty Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cooking and Baking Papers Market Shifts & Advancements
Coating chemistry substitution and procurement digitization are compressing traditional supplier relationships while elevating technical service intensity as a competitive differentiator.
Water-based silicone emulsion technology is rendering obsolete solvent-based coating lines in European industrial baking paper production. Mid-size Italian and Spanish converters are retrofitting aqueous application systems to meet EU solvent emission directives. The shift is compressing capital recovery timelines for legacy equipment while favoring integrated pulp-to-paper operators with captive coating capacity.
EU REACH substance restrictions on per- and polyfluoroalkyl substances are disqualifying legacy fluoropolymer-coated papers from food-contact applications in Germany, France, and the Netherlands. Industrial bakeries are rewriting material specifications to exclude PFAS-containing substrates entirely. Nordic Paper and integrated Scandinavian producers are capturing specification shifts through pre-certified fluorine-free product lines.
Volume-contract purchasing is consolidating procurement authority among quick-service restaurant chains and industrial bakery groups in the United States and China. Direct sales teams are displacing traditional paper merchant intermediaries for accounts above five-thousand-ton annual volume. The concentration is visible most acutely in California and Texas, where regional bakery clusters negotiate coating-customization clauses into multi-year supply agreements.
Global Cooking and Baking Papers Market Segmentation
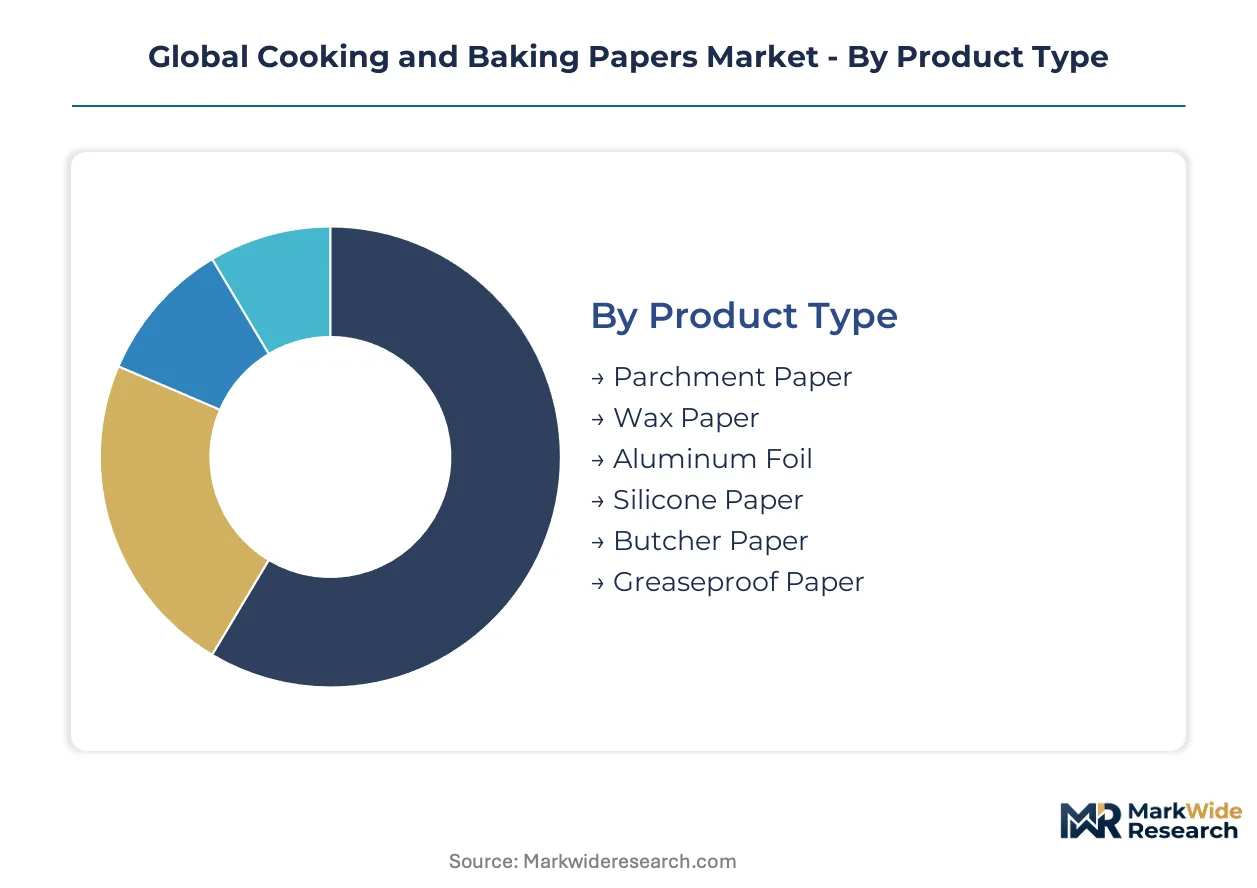
Cooking and baking papers fragment across four intersecting dimensions that determine pricing power, margin capture, and channel strategy. Each category carries distinct velocity profiles and specification intensity that shape supplier prioritization.
Product Type:
Parchment paper and silicone paper turn inventory fastest in food service procurement cycles, while wax paper and butcher paper move slower through retail channels with longer replenishment intervals.
- Parchment Paper:Cellulose substrate treated with silicone or quilon release agents, rated to 220°C. German and United States industrial bakeries specify this grade for universal oven compatibility, driving volume through wholesale distributor contracts.
- Silicone Paper:Double-sided silicone coating delivers superior release performance above 200°C. Quick-service restaurant chains in China and the United States are consolidating procurement around this grade for high-throughput baking operations, pulling fastest expansion within the category.
- Wax Paper:Paraffin-coated cellulose for cold-food wrapping and short-duration heating. United States retail private-label programs maintain steady offtake for sandwich preparation and food storage.
- Aluminum Foil:Metal substrate for high-heat grilling and moisture-sealed cooking. Household consumers in Germany and France favor this for barbecue and freezer applications.
- Butcher Paper:Untreated or lightly treated kraft paper for meat wrapping and smoking. Texas and California barbecue culture sustains niche demand through specialty retailers.
- Greaseproof Paper:Dense cellulose structure without silicone coating, relying on mechanical refining for oil resistance. Nordic Paper's integrated Scandinavian operations dominate supply to European industrial bakeries.
Parchment paper dominates installed base across commercial and residential kitchens. Silicone paper is where expansion concentrates as quick-service chains rewrite material specifications.
Application:
Cost tier stratification separates commodity wrapping applications from premium oven-grade specifications that command coating-customization premiums.
- Oven Baking:Temperature-rated silicone or quilon coatings prevent adhesion during prolonged heat exposure. Industrial bakeries in Germany and the United States negotiate coating-thickness clauses into multi-year supply agreements.
- Food Wrapping:Lower specification barrier papers for cold or ambient-temperature storage. Retail channels in the United Kingdom and France move volume through supermarket private-label programs with minimal technical service requirements.
- Cake Decoration:Precision-cut parchment circles and sheets for professional pastry finishing. Italian and French artisan bakeries source through specialty distributors with just-in-time replenishment.
- Grill Lining:Heavy-duty silicone papers rated for direct flame contact. United States outdoor cooking culture sustains seasonal demand spikes through home improvement retailers.
- Microwave Cooking:Susceptor-compatible papers for crisping and browning. Japanese and South Korean appliance manufacturers specify custom grades for bundled accessory programs.
- Steaming:Perforated or breathable papers for Asian cooking techniques. Restaurant chains in China specify bamboo-pulp alternatives for traditional dim sum preparation.
Oven baking commands highest specification intensity and supplier technical engagement. Food wrapping generates volume scale with thinner margins and distributor-mediated relationships.
End User:
Customer type determines contract structure, with industrial accounts consolidating procurement authority while fragmented household demand flows through retail intermediaries.
- Bakeries:Industrial and artisan producers specifying coating performance by application. German bakery clusters in Bavaria and North Rhine-Westphalia anchor European volume offtake through direct sales relationships.
- Food Service Providers:Quick-service restaurant chains and contract caterers with centralized procurement. United States and Chinese chains above five-thousand-ton annual volume are displacing traditional paper merchants.
- Catering Companies:Event-focused operators with seasonal demand spikes and lower specification consistency. French and Italian catering markets show underpenetration by silicone-treated grades relative to Northern Europe.
- Household Consumers:Fragmented residential demand channeled through supermarkets and online retailers. United Kingdom and German retail markets sustain parchment paper velocity through sustained home baking activity.
- Cafés:Small-format food service with mixed baking and wrapping requirements. Urban clusters in Mumbai and Bangalore present expansion opportunity for silicone-treated paper suppliers.
- Restaurateurs:Independent operators with irregular purchasing patterns and price sensitivity. Italian and Spanish mid-size restaurants remain distributor-dependent with limited direct supplier engagement.
Bakeries and food service providers dominate contract value and technical service intensity. Household consumers represent volume dispersion across retail channels with lowest per-account revenue concentration.
Distribution Channel:
Supply concentration favors integrated operators with captive coating capacity, while fragmented retail channels reward brand recognition and shelf-space negotiation.
- Supermarkets & Hypermarkets:Retail shelf presence requiring trade spend and private-label program participation. Reynolds Consumer Products anchors United States presence through dominant channel control.
- Online Retailers:E-commerce growth accelerating in post-pandemic household replenishment patterns. German and United Kingdom markets show fastest platform penetration for specialty and bulk formats.
- Specialty Stores:Culinary retailers and professional kitchen suppliers serving artisan bakeries and serious home cooks. French and Italian specialty channels maintain higher parchment paper specification diversity.
- Wholesale Distributors:Traditional intermediaries for mid-size food service accounts. California and Texas regional bakery clusters are consolidating procurement authority away from this channel toward direct sales.
- Direct Sales:Supplier-customer relationships for accounts above volume thresholds with coating-customization requirements. Mondi Group competes on technical service embedding food-safety compliance into European industrial bakery specifications.
Wholesale distributors retain installed base among fragmented mid-size accounts. Direct sales is where supplier investment concentrates as procurement authority consolidates among large food service chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in cooking and baking papers tilt toward net-exporting Scandinavian integrated producers and net-importing industrial bakery clusters in Asia-Pacific. Import dependency concentrates in markets lacking captive pulp-to-paper coating capacity.
Germany
Industrial bakery clusters in Bavaria and North Rhine-Westphalia consume silicone-treated parchment at scale for automated bread lines. EU REACH substance restrictions on PFAS redirect procurement toward fluorine-free certified grades from domestic converters. The F-Gas Regulation accelerates coating reformulation investments by Stuttgart-area technical service providers.
United States
Quick-service restaurant chains in California and Texas consolidate procurement authority above five-thousand-ton annual volumes. FDA food-contact substance notifications govern silicone coating approvals, extending product launch timelines for European imports. Regional bakery clusters in the Midwest negotiate coating-customization clauses into multi-year direct supply agreements.
China
Quick-service bakery expansion in Shanghai and Beijing pulls silicone paper through wholesale distribution channels. The national food safety regulator enforces GB standards on food-contact materials, elevating compliance costs for uncoated base stock imports. Yangtze River Delta converters retrofit water-based silicone emulsion lines to meet emission directives.
India
Quick-service bakery chains in Mumbai and Bangalore remain underpenetrated by silicone-treated paper suppliers relative to East Asian markets. FSSAI food-contact material regulations tighten substrate specifications for imported coated papers. Maharashtra and Karnataka industrial zones show emerging demand for high-release grades in commercial kitchen operations.
United Kingdom
Sustained residential baking activity maintains retail parchment paper velocity through supermarket private-label programs. Post-Brexit divergence from EU REACH dossier requirements complicates sourcing for importers serving industrial accounts. Greater London food service distributors consolidate inventory positions for pan-European bakery chains operating UK outlets.
Global Cooking and Baking Papers Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated pulp-to-paper operators with captive coating capacity and specialty converters serving technical niche specifications. Three archetypes dominate: Scandinavian integrated producers controlling fiber supply, North American consumer brand houses anchoring retail shelf presence, and European technical service specialists embedding compliance into customer specifications. Competitive moves concentrate on backward integration into base stock production and direct sales team expansion displacing traditional paper merchants.
Among Scandinavian integrated operators, Nordic Paper exemplifies cost discipline through pulp-to-paper control. Reynolds Consumer Products occupies a position as the North American retail channel anchor. Mondi Group sits within the European technical service tier, competing on specification embedding. These three represent distinct strategic postures without overlapping core market focus.
| Leading Market Players |
|---|
| Nordic Paper |
| Reynolds Consumer Products |
| Mondi Group |
| Ahlstrom-Munksjö |
| Delfortgroup AG |
| Koninklijke Ahrend N.V. |
| Stora Enso |
| Georgia-Pacific |
| Expera Specialty Solutions |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors shape coating chemical delivery economics, compressing margins for German and Belgian converters while amplifying price spreads between integrated Nordic producers and merchant base-stock buyers. Pulp cost volatility from Brazilian and Nordic mill output feeds directly into silicone-treated paper quotations, with volume-contract industrial bakeries capturing stability unavailable to fragmented food service accounts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across European and North American silicone paper procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by fluorine-free certification grade and coating customization depth. Cost compression in standard-grade parchment intensifies as Yangtze River Delta converters expand water-based silicone capacity. Quick-service restaurant chains above five-thousand-ton annual volumes exhibit lowest price sensitivity due to specification-locked supply agreements, while independent restaurateurs and café operators remain highly price-responsive.
Supply Chain Analysis
Specialty silicone fluid production concentrates in Germany and China, creating single-source vulnerability for coating operations dependent on organosilane precursors. Base paper supply draws from integrated Scandinavian pulp-to-paper operations and merchant uncoated stock from Nordic and Brazilian fiber sources. Logistics chokepoint risk concentrates in Rotterdam port congestion and Yangtze River seasonal shipping constraints. Distribution runs through wholesale distributors for fragmented mid-size accounts, while direct sales relationships displace intermediaries for large industrial bakery and quick-service restaurant procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
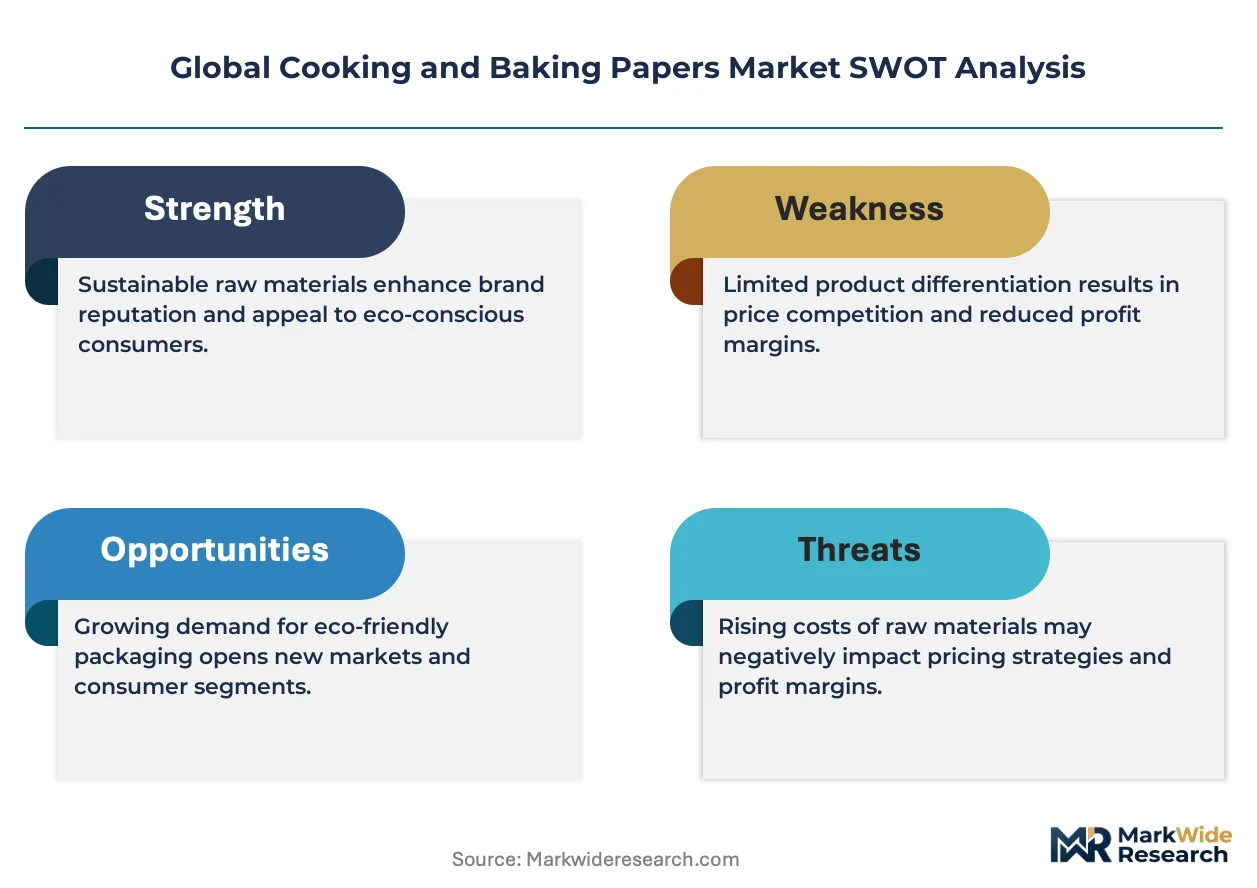
This market functions as a regulatory-entrenchment defensive moat, where EU REACH and FDA food-contact compliance timelines create eight-to-fourteen-month barriers that protect incumbent coating formulators with certified substrate integration.
For Market Incumbents: Insulate specification-locked relationships with industrial bakeries through captive fluorine-free coating capacity expansion in Germany and Scandinavia. Deepen upstream control over specialty silicone emulsion supply by securing long-term offtake from German chemical producers. Plant-based coating R&D investment represents the critical lever against emerging bio-barrier entrants threatening premium positioning. For New Entrants and Emerging Players: Pursue underpenetrated quick-service bakery chains in Mumbai and Bangalore where FSSAI compliance requirements remain less stringent than EU REACH barriers. Target compostable-certified retail positioning in United Kingdom and German supermarket private-label programs as the most penetrable premium tier. Digital e-procurement platform partnerships with French and Italian mid-size industrial bakeries offer direct channel access bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified paper conglomerates with non-core specialty food-contact divisions lacking integrated coating capacity. Five-to-ten year viability hinges on fluorine-free transition completion and water-based silicone emulsion retrofit execution. Monitor EU F-Gas Regulation phase-down acceleration and FDA notification backlog clearance as inflection signals for valuation compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Transition | EU REACH PFAS restrictions in Germany and Netherlands disqualify legacy formulations from food-contact applications. |
| Water-Based Silicone Emulsion Retrofit | Italian and Spanish converters retrofit aqueous lines to meet EU solvent emission directives. |
| Direct Sales Team Expansion | California and Texas bakery clusters negotiate coating-customization clauses displacing wholesale distributors. |
| Compostable Certification Investment | TÜV Austria and BPI standards create premium positioning for certified home-compostable baking papers in European retail. |
| Indian Food Service Penetration | Mumbai and Bangalore quick-service chains remain underpenetrated relative to East Asian silicone-treated paper markets. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulation chemists, industrial bakery procurement directors, quick-service restaurant supply chain managers, and wholesale distributor category buyers and refined through secondary validation. Trade data from Eurostat and U.S. Census Bureau customs records, ECHA REACH dossier filings, FDA food-contact substance notifications, and Nordic Paper industry association reports anchored supply-side quantification. Bottom-up volume aggregation across product grades and top-down macroeconomic anchoring were triangulated to converge estimates.
Demand-supply-balance framing governed the analytical framework across the analysis window, with segmentation dimensions spanning product type, application temperature rating, end-user scale tier, and distribution channel structure. CAGRs were derived from elasticity-adjusted volume projections and value-per-ton coating premium evolution. Silicone fluid price indices and pulp futures curves from Brazilian and Nordic exchanges fed directly into cost-pass-through modeling for coated paper quotations.
Sensitivities concentrate around EU F-Gas Regulation acceleration, FDA notification timeline compression, and Yangtze River Delta environmental enforcement intensity. Forecasts embed assumptions regarding fluorine-free coating performance ceiling resolution and water-based emulsion adoption rates. Quarterly review of ECHA substance restriction proposals, FDA FCN clearance backlogs, and Brazilian pulp mill operating rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market