
 Paper and Board Technologies Market | 2026-2036
Paper and Board Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Paper and Board Technologies Market Analytics
Project finance for energy-efficient rebuilds is reconfiguring competitive entry barriers across the paper and board machinery sector. Valmet Oyj leverages its turnkey recovery boiler installations to anchor long-term service contracts in Nordic markets. Andritz AG specializes in high-consistency refining systems that extend its reach into Asian hardwood pulp lines. Siemens AG competes through integrated drive and automation platforms that dominate greenfield mill electrification.
Paper and Board Technologies encompass machinery, chemical systems, and process control platforms engineered to convert wood pulp, recycled fiber, and agricultural residues into finished paper grades and board structures at basis weights typically spanning 40 to 450 grams per square meter. Coated paper lines command premium margin pools where gloss uniformity and print receptivity determine commercial value. Corrugated board capacity is expanding fastest across packaging applications as shelf-ready display formats displace rigid alternatives. Recycled Technologies face structural cost pressure from contaminant removal demands even as regulatory mandates for post-consumer content intensify.
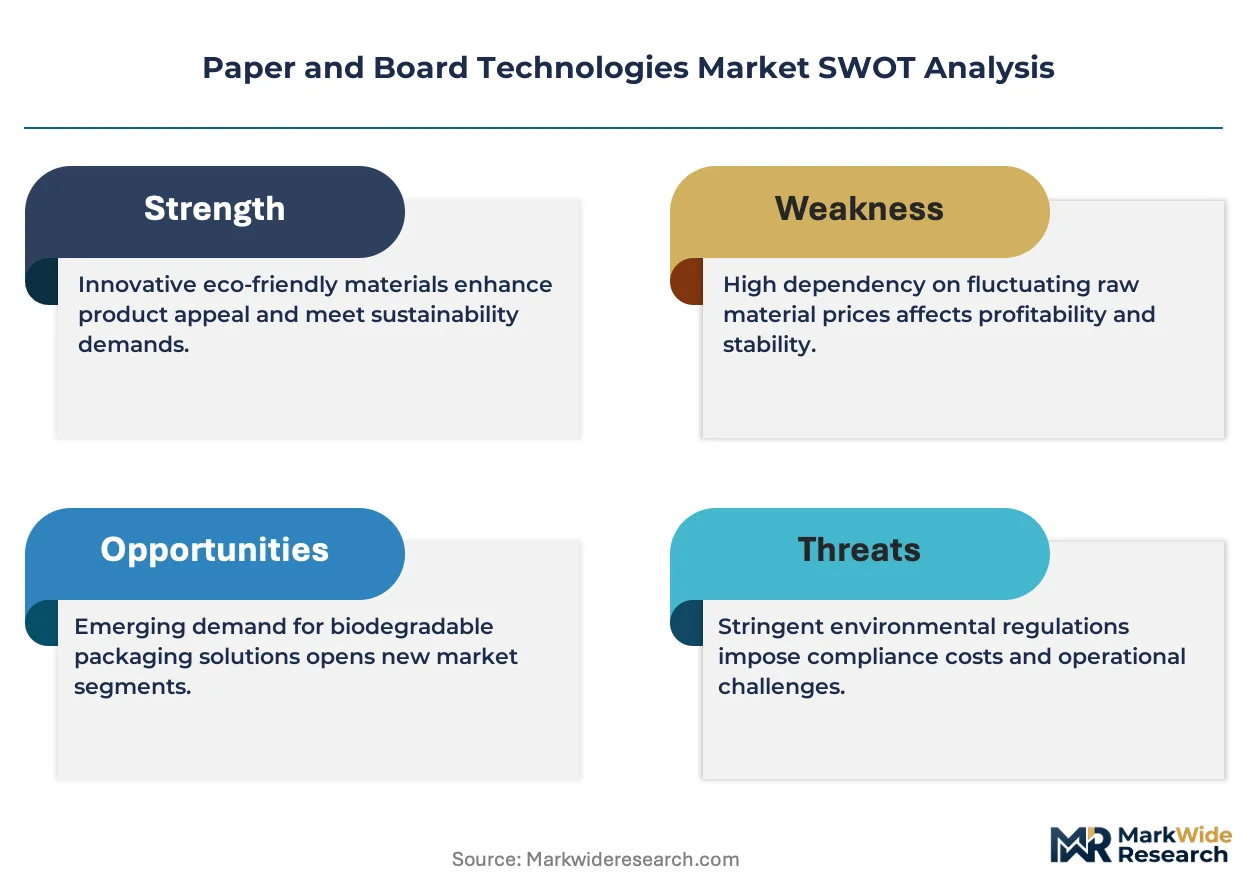
EPA effluent guidelines in the United States enforce Best Available Technology limits on biochemical oxygen demand and adsorbable organic halides from bleached kraft operations. REACH chemical authorization in Europe restricts formaldehyde-based wet-strength resins, redirecting formulation R&D toward polyamide-epichlorohydrin alternatives. China's MEE enforces dual carbon goals that cap energy intensity per ton of paper produced. Stakeholders must monitor how divergent regional compliance costs reshape site selection for new capacity and determine which technology suppliers can credibly certify cross-border environmental performance.
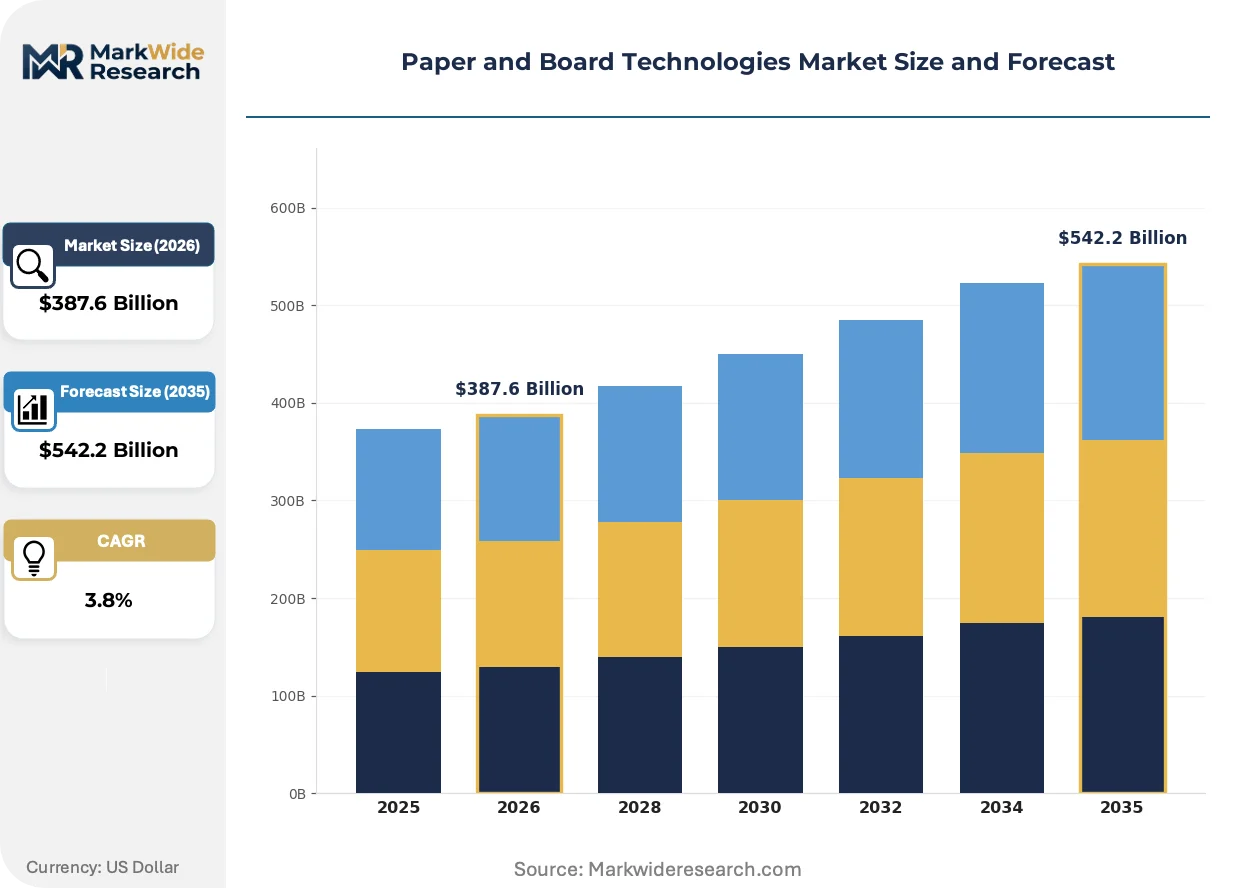
Market Dynamics
The EU F-Gas Regulation and EPA effluent guidelines are forcing simultaneous capital deployment into emissions abatement and water treatment systems, compressing project payback periods while raising the technical threshold for new mill entrants.
Growth Catalysts
- E-commerce packaging surge:Consumer goods brands are converting shelf-ready display formats from rigid plastics to corrugated board structures, pulling demand for high-speed corrugator lines and precision die-cutting systems.
- REACH chemical restrictions:The European ban on formaldehyde-based wet-strength resins is redirecting formulation R&D toward polyamide-epichlorohydrin alternatives, creating replacement demand for chemical delivery and dosing equipment.
- China's dual carbon goals:MEE enforcement of energy intensity caps per ton of paper produced is accelerating mill consolidation and technology upgrades in Shandong and Guangdong provinces.
Market Restraints
- Recycled fiber contamination costs:Post-consumer mixed paper streams require advanced optical sorting and deinking chemistry, elevating operating expenditures for mills dependent on recycled furnish.
- Recovery boiler supply concentration:Turnkey installation capacity for high-pressure recovery boilers concentrates among Nordic engineering groups, extending delivery timelines for greenfield kraft mill projects.
- Hardwood pulp line technical barriers:High-consistency refining systems for eucalyptus and acacia fibers demand specialized metallurgy and control algorithms that limit supplier options.
Strategic Opportunities
- Agricultural residue valorization:Wheat straw and bagasse pulping technologies open fiber sourcing in grain-producing regions lacking softwood timber reserves, particularly across the Indian subcontinent.
- Digital twin convergence:Integration of process simulation with predictive maintenance platforms enables remote optimization of drying section energy profiles without on-site specialist deployment.
- Extended producer responsibility mandates:EU packaging waste directives are creating service revenue streams for machinery suppliers offering closed-loop fiber recovery and repulping system retrofits.
Industry Challenges
- Process control talent scarcity:Distributed control system programming and model predictive control tuning expertise concentrates among aging specialist engineers, constraining mill automation upgrade execution.
- Legacy drive system integration:Electrification retrofits for aging paper machines must synchronize new medium-voltage variable frequency drives with existing DC motor foundations and mechanical power transmission components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper and Board Technologies Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $542.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Molded Fiber, Corrugated Board Application: Packaging, Printing, Stationery, Industrial Use End User: Consumer Goods, Food & Beverage, Pharmaceuticals, Electronics Technology: Recycled Technologies, Digital Printing, Coating Technologies, Pulping Techniques |
| Companies Covered | Valmet Oyj, Siemens AG, Andritz AG, ABB Ltd, Honeywell International Inc, Flint Group, Covestro AG, BW Papersystems, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper and Board Technologies Market Evolving Landscape
Machine learning-based quality prediction and virtual commissioning platforms are compressing startup timelines while reducing physical prototype requirements for new paper grade introductions.
Digital twin technology for paper machine drying sections is virtualizing the traditional wet-end pilot plant validation process. Major packaging board producers in Germany and Finland are deploying these simulations to optimize steam consumption profiles before physical rebuilds. The approach compresses capital project risk by enabling iterative design validation without production line downtime.
REACH authorization procedures for wet-strength chemistry are tightening discharge monitoring requirements for European mills operating bleached kraft lines. The regulation forces simultaneous investment in adsorbable organic halide measurement systems and biological treatment capacity expansions. Coated fine paper producers in the Netherlands and Austria face the steepest compliance cost escalation due to existing reliance on formaldehyde-based resin systems.
Brand procurement teams are consolidating supplier relationships around full-line system integrators capable of certifying cross-border environmental performance. This concentration displaces the historical pattern of fragmented equipment sourcing from multiple regional vendors. The shift is most pronounced among multinational consumer packaging companies operating integrated pulp-to-board complexes in Scandinavia and the Baltic states.
Paper and Board Technologies Market Segmentation
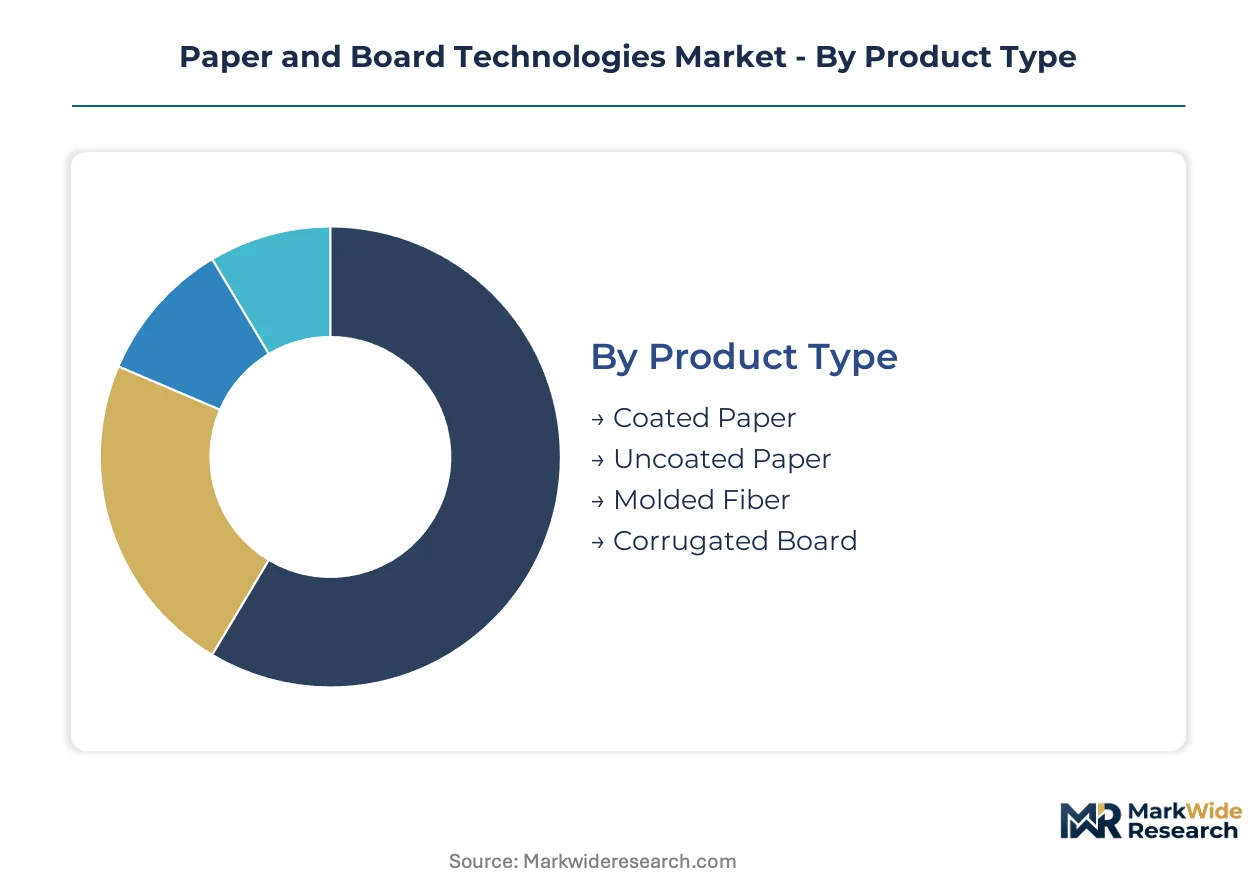
Technology selection in paper and board production locks in capital intensity, energy profiles, and compliance pathways for decades. Segment boundaries increasingly blur as packaging converters demand multi-functional substrates combining printability, barrier properties, and recyclability credentials.
Product Type:
Cycle times diverge sharply: corrugated board lines refresh every 7-10 years amid e-commerce capacity surges, while coated paper machines operate 20-25 year lifespans barring major grade shifts.
- Coated Paper:Clay and calcium carbonate surface treatments deliver gloss uniformity and ink receptivity for high-end commercial printing. Dutch and Austrian mills face steepest REACH compliance costs due to formaldehyde-based wet-strength resin dependencies.
- Corrugated Board:Fluted medium sandwiched between linerboards dominates shelf-ready display format conversions from rigid plastics. German packaging board producers deploy digital twin simulations to optimize steam consumption before physical rebuilds.
- Uncoated Paper:Office copy and uncoated freesheet grades serve transactional printing and envelope applications.
- Molded Fiber:Thermoformed pulp structures replace expanded polystyrene in protective packaging for electronics and food service.
Corrugated board anchors the volume base while molded fiber gains share at the steepest rate.
Application:
Margin structures invert across applications: industrial use commands specification premiums for chemical resistance and dimensional stability, while stationery operates at commodity economics.
- Packaging:E-commerce fulfillment requirements pull demand for high-speed corrugator lines and precision die-cutting systems. Consumer goods brands consolidate supplier relationships around full-line system integrators certifying cross-border environmental performance.
- Printing:Publication and commercial print segments face secular pressure from digital media substitution. Coated fine paper producers in the Netherlands and Austria navigate EPA effluent guidelines and REACH chemical authorization simultaneously.
- Stationery:Office supplies and educational materials maintain steady replacement demand cycles.
- Industrial Use:Filter media, abrasive backings, and electrical insulation papers require specialized fiber refining and synthetic binder integration.
Packaging absorbs the majority of capacity additions while industrial use captures the highest per-ton margin realization.
End User:
Procurement sophistication varies: pharmaceutical buyers enforce batch traceability and extractable testing protocols, while food and beverage prioritizes migration-compliant barrier coatings.
- Food & Beverage:Grease-resistant and moisture-barrier board specifications dominate folding carton demand. EU packaging waste directives create service revenue streams for machinery suppliers offering closed-loop fiber recovery retrofits.
- Pharmaceuticals:Serialization requirements and tamper-evident features drive investment in integrated printing and inspection systems. China's MEE dual carbon goals accelerate mill consolidation affecting secondary packaging substrate supply.
- Consumer Goods:Brand owners specify post-consumer recycled content percentages in corrugated shipping containers.
- Electronics:Anti-static and cushioning specifications protect high-value components through distribution.
Food and beverage generates the broadest substrate demand while pharmaceuticals imposes the most stringent qualification barriers.
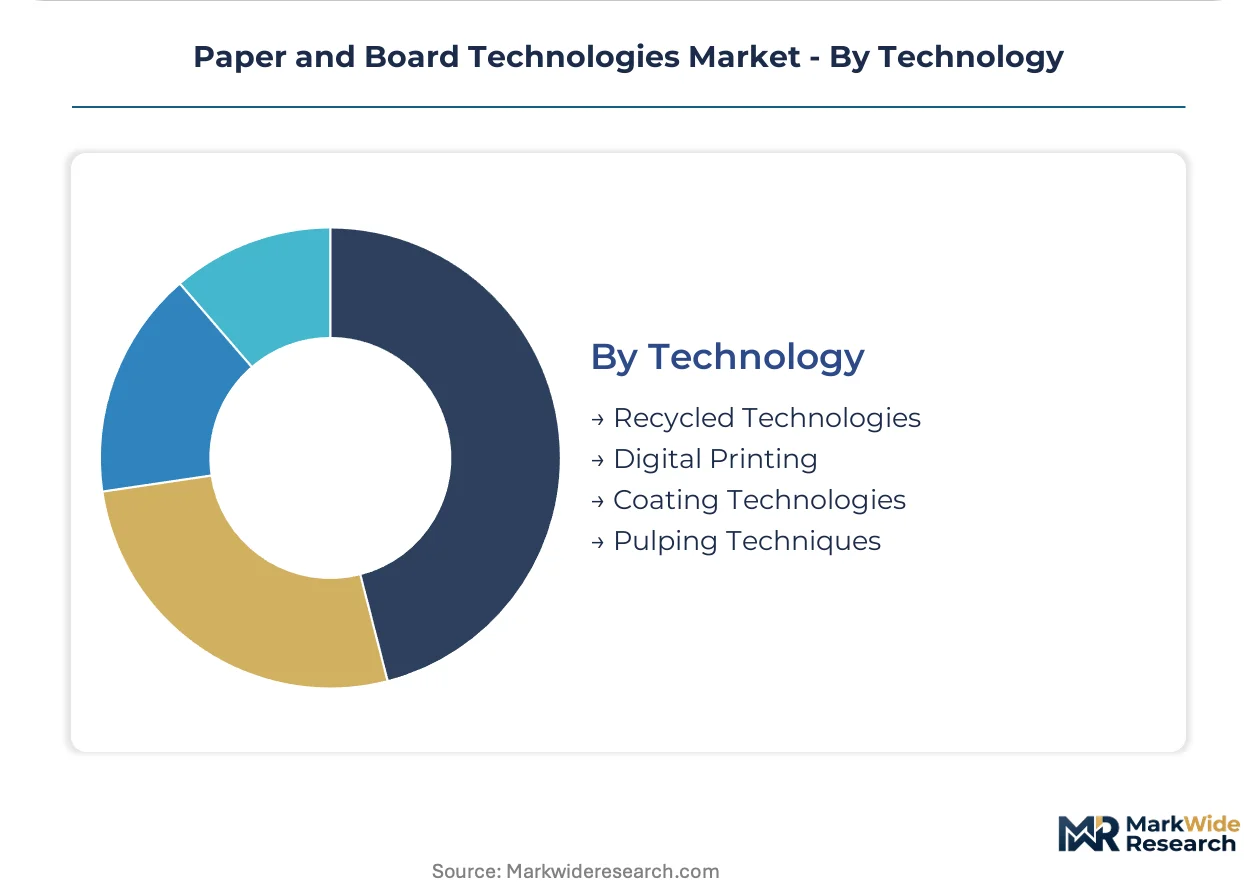
Technology:
Capital deployment timing separates segments: pulping technique investments lock in fiber sourcing for 15-20 years, while digital printing modules retrofit within months.
- Recycled Technologies:Advanced optical sorting and deinking chemistry address post-consumer mixed paper stream contamination. Operating expenditures climb for mills dependent on recycled furnish as collection quality deteriorates.
- Digital Printing:Inkjet and toner-based systems enable short-run customization and variable data integration. Machine learning-based quality prediction platforms compress startup timelines for new grade introductions.
- Coating Technologies:Blade, rod, and curtain coating methods apply functional layers for barrier and print performance.
- Pulping Techniques:Kraft, mechanical, and chemithermomechanical processes determine fiber yield and strength properties.
Pulping techniques represent the longest-cycle infrastructure commitment while digital printing expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal subsidies and China's dual carbon enforcement are redirecting capital toward energy-efficient rebuilds in established pulp-to-board corridors. Mill operators in Germany and Finland deploy digital twin validation to compress project timelines. Shandong province accelerates consolidation under MEE energy intensity caps.
United States
E-commerce fulfillment networks pull demand for high-speed corrugator installations across the Midwest and Southeast. EPA effluent guidelines enforce Best Available Technology limits on biochemical oxygen demand from bleached kraft mills. Wisconsin and Georgia host integrated pulp-to-board complexes where producers navigate simultaneous emissions and water treatment compliance.
Germany
Packaging board producers convert shelf-ready display formats from rigid plastics to corrugated structures, anchoring European demand. REACH chemical authorization restricts formaldehyde-based wet-strength resins, redirecting formulation R&D toward polyamide-epichlorohydrin alternatives. The Ruhr and Bavarian industrial clusters concentrate recovery boiler installation capacity among Nordic engineering service providers.
China
MEE dual carbon goals cap energy intensity per ton of paper produced, accelerating mill consolidation in Shandong and Guangdong provinces. National regulators enforce emissions trading scheme compliance across integrated pulp-to-board facilities. Yangtze River Delta producers retrofit aging machines with medium-voltage variable frequency drives to meet tightening efficiency benchmarks.
Finland
Nordic engineering groups anchor turnkey recovery boiler installation capacity serving greenfield kraft mill projects across the Baltic region. EU F-Gas Regulation tightens emissions standards for fluorinated greenhouse gases used in mill refrigeration and process cooling. Tampere and Helsinki clusters specialize in digital twin simulations for drying section optimization before physical rebuilds.
India
Agricultural residue valorization opens fiber sourcing in grain-producing regions lacking softwood timber reserves, particularly across Punjab and Haryana. Central Electricity Authority grid codes shape captive power plant investments for energy-intensive pulping operations. Gujarat and Maharashtra packaging converters demand multi-functional substrates combining printability, barrier properties, and recyclability credentials.
Paper and Board Technologies Market Competitive Landscape
On the supply side, the industry is consolidating around full-line system integrators capable of certifying cross-border environmental performance. Strategic archetypes separate into turnkey recovery boiler specialists, high-consistency refining system providers, and integrated drive and automation platform vendors. Dominant competitive moves include strategic partnerships for digital twin deployment and geographic expansion through service contract anchoring in Nordic and Asian markets.
Among Nordic-based engineering groups, Valmet Oyj and Andritz AG exemplify the turnkey installation archetype, with the former representing recovery boiler specialization and the latter occupying a position in high-consistency refining systems for hardwood pulp lines. Siemens AG anchors the integrated automation tier, sitting within the electrification and process control segment that dominates greenfield mill projects. These three entities collectively represent the supplier concentration extending delivery timelines for complex capital deployments.
| Leading Market Players |
|---|
| Valmet Oyj |
| Siemens AG |
| Andritz AG |
| ABB Ltd |
| Honeywell International Inc |
| Flint Group |
| Covestro AG |
| BW Papersystems |
| Syntegon Technology GmbH |
| Others |
Value Network & Pricing Analysis
Recovery boiler installation capacity concentrates among Nordic engineering groups in Finland and Sweden, anchoring margin pools in long-term service contracts and captive aftermarket revenues rather than equipment sales alone. This upstream concentration cascades downstream, where mills in Germany and China absorb extended delivery timelines and premium pricing for turnkey thermal systems.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with EU Green Deal compliance and EPA effluent guideline adherence commanding substantial premia over baseline equipment. Project-based pricing dominates complex rebuilds, while chemical delivery systems operate on contract-based long-term offtake arrangements. Price differentiation stems from energy efficiency guarantees and cross-border environmental performance certification. Cost compression in standard-grade corrugator lines is intensifying due to Chinese equipment imports. Recycled technology-dependent mills exhibit highest price sensitivity, while integrated pulp-to-board complexes in Scandinavia prioritize compliance over unit economics.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk calculus for high-consistency refining systems and digital control platforms. Manufacturing concentrates in Germany, Finland, and China, with specialized metallurgy for hardwood pulp lines drawing from Austrian and Japanese foundries. Raw material dependencies center on high-grade steel alloys, precision control electronics, and specialized ceramic coatings. Single-source vulnerability persists for recovery boiler pressure vessel fabrication. Distribution runs through mill-direct procurement channels and regional engineering service partnerships rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin convergence and predictive maintenance platforms are disrupting traditional service revenue models, creating asymmetric opportunities for technology-anchored suppliers against legacy equipment vendors.
For Market Incumbents: Build regulatory certification moats by pre-validating equipment against EU F-Gas Regulation and REACH chemical authorization requirements before competitor systems reach market. Anchor long-term service contracts through embedded sensor networks that lock in aftermarket exclusivity. Capacity addition in Shandong province offers defensive positioning against Chinese domestic supplier consolidation. Threat substitution emerges from AI-native startups offering virtual commissioning without physical pilot plant requirements. For New Entrants and Emerging Players: Agricultural residue pulping systems across Punjab and Haryana represent the most penetrable entry point, where softwood timber scarcity eliminates incumbent fiber line competition. Mid-tier packaging converters in Gujarat and Maharashtra seek multi-functional substrate solutions combining barrier performance with recyclability credentials absent from established supplier portfolios. Go-to-market execution should leverage equipment-as-a-service financing to bypass capital-constrained mill operator procurement barriers. For Investors and Strategic Acquirers: Capital is best deployed toward digital twin platform specialists with proven drying section optimization deployments in German and Finnish mill installations. Long-term viability over the analysis window favors suppliers integrating process simulation with predictive maintenance rather than pure equipment manufacturers. Acquisition target archetype: mid-scale automation vendors with existing Nordic service footprints and MEE certification capabilities for Chinese market access. Signal to watch: consolidation velocity among Shandong province mills under dual carbon enforcement caps.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Virtual commissioning compresses startup timelines for German packaging board producers before physical rebuilds. |
| Backward Integration into Recovery Boiler Fabrication | Captive pressure vessel capacity insulates Nordic engineering groups from extended delivery timeline risks. |
| REACH-Compliant Chemical System Retrofit | Polyamide-epichlorohydrin alternatives capture replacement demand from Dutch and Austrian coated paper mills. |
| Agricultural Residue Pulping Partnership | Wheat straw and bagasse technologies open fiber sourcing in Indian grain-producing regions lacking timber reserves. |
| Extended Producer Responsibility Service Contract | Closed-loop fiber recovery retrofits generate recurring revenue from EU packaging waste directive compliance mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mill engineering directors, procurement leads at integrated pulp-to-board complexes, aftermarket service heads, and regulatory compliance officers. Secondary validation drew from MEE enforcement disclosures, EU ETS transaction registries, EPA effluent guideline dockets, and customs data on recovery boiler imports. Bottom-up equipment shipment analysis triangulated against top-down capacity utilization surveys across German, Finnish, and Chinese mill clusters.
Calibration against historical capital expenditure cycles and energy intensity improvement trajectories shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, end-use industry, pulping technique, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and e-commerce packaging demand elasticity. Forecast inputs incorporated MEE dual carbon enforcement stringency and EU Green Deal subsidy allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in pulp fiber pricing, energy cost volatility, or trade policy fragmentation would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Medical Grade Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Ceramic Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Americas Stone Paper Market
Paper Products
Abaca Pulp Market
Paper Products
Photographic Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Pharma Grade Paper Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Household Paper Market
Paper Products
Glassine Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market