
 Americas Stone Paper Market | 2026-2036
Americas Stone Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Stone Paper Market Analytics
EPA guidelines on recycled content thresholds is restructuring compliance pathways for stone paper entrants in the United States. Karst Stone Paper leverages its direct-to-consumer channel strength to sustain premium positioning across North American stationery segments. Soluz Stone Paper anchors Brazilian demand through localized extrusion capacity. Taiwan Lung Meng Technology Co. dominates export supply into Mexico and Colombia with established coating technology leadership.
Americas Stone Paper comprises calcium carbonate-rich sheets manufactured through extrusion of mineral powder with non-toxic resin binders, yielding a waterproof, tear-resistant substrate that replaces wood-pulp and synthetic alternatives in label and print applications. The material serves commercial users seeking reduced water consumption and eliminated bleaching effluent in production cycles. Packaging Paper leads volume contribution as e-commerce shippers adopt stone-based cushioning and wrap formats to meet retailer sustainability scorecards. Extrusion technology occupies the dominant process position due to lower energy intensity versus coating alternatives, though Coating segments capture margin concentration in high-resolution printing grades. Specialty Paper differentiates through FDA-compliant food-contact certifications that command price premiums in premium chocolate and cosmetics labeling.
FDA food-contact substance notifications govern direct packaging applications, while EPA recycled-content standards under the Resource Conservation and Recovery Act shape procurement eligibility for federal suppliers. State-level extended producer responsibility frameworks in California and New York add compliance layers that favor mineral-based substrates over conventional plastics. Stakeholders must monitor pending FTC Green Guides revisions, as updated marketing-claims enforcement could recertify which environmental assertions survive competitive scrutiny.
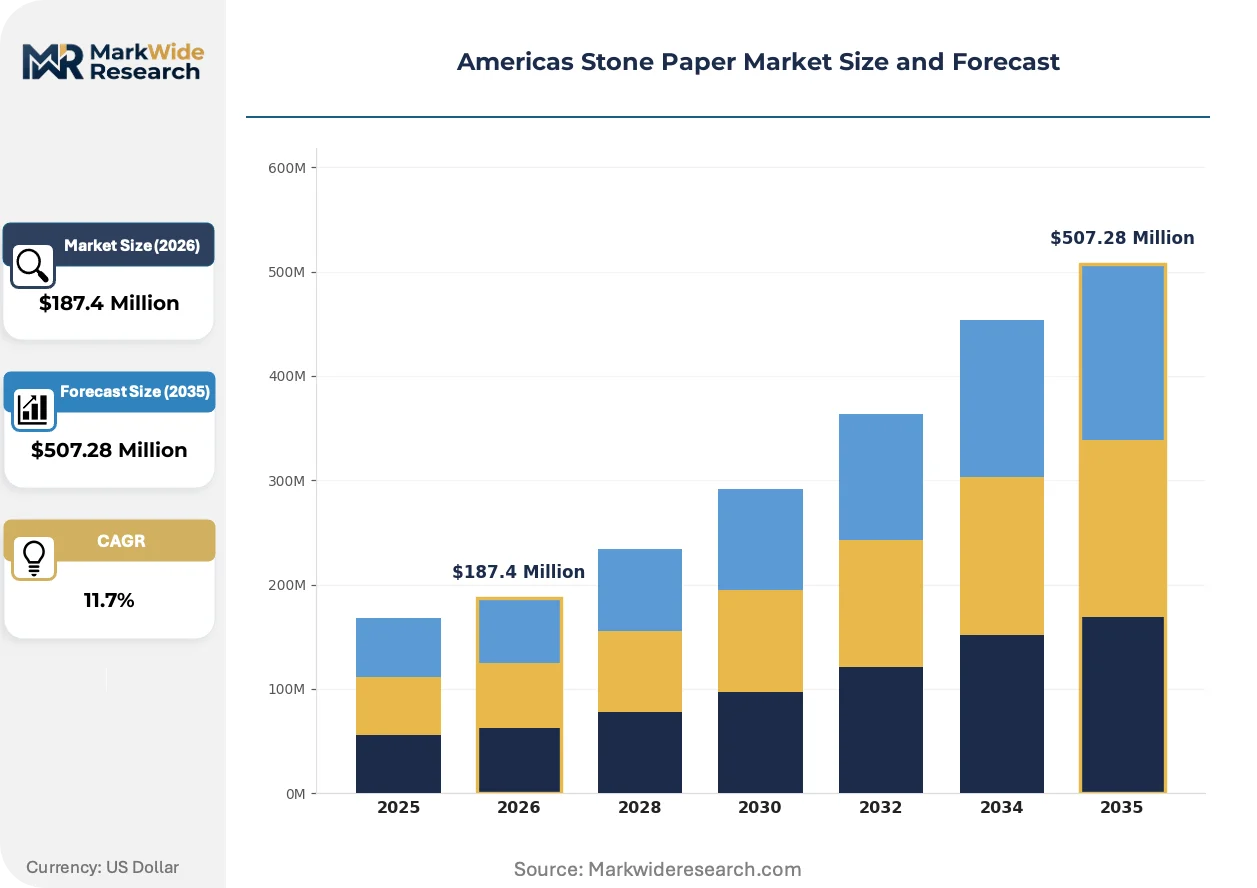
Market Dynamics
California's extended producer responsibility mandates are compressing substitution timelines for mineral-based substrates, while FDA food-contact compliance requirements favor calcium carbonate-rich sheets over conventional plastic coatings in premium packaging segments.
Growth Catalysts
- State-level plastic waste mandates:California and New York frameworks penalize petroleum-based alternatives, accelerating retailer scorecard adoption of stone-based cushioning formats.
- Calcium carbonate extraction advances:Mexican mining efficiency gains are lowering raw material costs for regional extrusion producers serving North American converters.
- E-commerce sustainability scorecards:Major retailers now require biodegradable or mineral-based wrap formats, pulling stone paper into fulfillment center specifications.
Market Restraints
- Resin binder cost volatility:Non-toxic polyethylene and polypropylene input prices fluctuate with petrochemical feedstock markets, compressing margin stability for extrusion operators.
- Coating technology concentration:High-resolution printing grade supply depends on concentrated Asian coating equipment imports, creating import dependency for premium segment entrants.
- Thermal degradation threshold:Stone paper substrates face temperature limitations in heat-sealing applications that polyolefin films tolerate, restricting flexible packaging penetration.
Strategic Opportunities
- Colombian label conversion market:Underpenetrated food-grade label demand in Andean cosmetics and chocolate sectors offers first-mover positioning for FDA-certified stone paper suppliers.
- FTC Green Guides revision tailwind:Pending marketing-claims enforcement updates may recertify environmental assertions, rewarding substrates with verified lifecycle data.
- Digital printing convergence:UV-curable ink compatibility advances are unifying stone paper with short-run variable data applications previously locked to synthetic films.
Industry Challenges
- Extrusion technician scarcity:Mineral powder compounding expertise resides in narrow talent pools, forcing Brazilian and Mexican producers into wage competition with construction materials sectors.
- FDA food-contact notification timelines:Substance notification reviews for new resin formulations extend 12-18 months, delaying product launches for specialty paper entrants targeting direct food packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Stone Paper Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printing Paper, Writing Paper, Packaging Paper, Specialty Paper End Use: Stationery, Publishing, Packaging, Advertising Thickness: Thin, Medium, Thick, Extra Thick Technology: Extrusion, Coating, Laminating, Others |
| Companies Covered | Karst Stone Paper, Soluz Stone Paper, Taiwan Lung Meng Technology Co., Taber Industries, Mode Paper Company, AM Packaging Company Limited, Sphera International, STP Stone Paper GmbH, Stone Paper Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Stone Paper Market Evolving Landscape
Extrusion-coating hybrid processes are compressing energy intensity gaps while expanding printable surface quality, reshaping competitive positioning between regional producers and import-dependent converters.
Multi-layer co-extrusion systems are unifying calcium carbonate core layers with printable skin surfaces, eliminating separate coating steps. E-commerce fulfillment operators in California and Texas are adopting these substrates at accelerating pace for dunnage and wrap applications. The technology is unifying cost structures between standard and premium grades, eroding historical margin stratification.
EPA recycled-content standards under the Resource Conservation and Recovery Act are restructuring federal procurement eligibility, disqualifying conventional plastic-coated papers from supply contracts. Stone paper formulations with mineral content above threshold levels now qualify for preferential vendor status. Packaging segments serving defense and institutional foodservice are responding fastest, reformulating specifications around mineral substrate compliance.
Retailer sustainability scorecards are compressing supplier qualification cycles from annual to quarterly review periods. Brand procurement teams in cosmetics and premium food verticals are disintermediating traditional paper distributors, contracting directly with stone paper extruders for volume commitments. This pattern concentrates most visibly in California's sustainable packaging corridor, where state mandates amplify buyer power consolidation.
Americas Stone Paper Market Segmentation
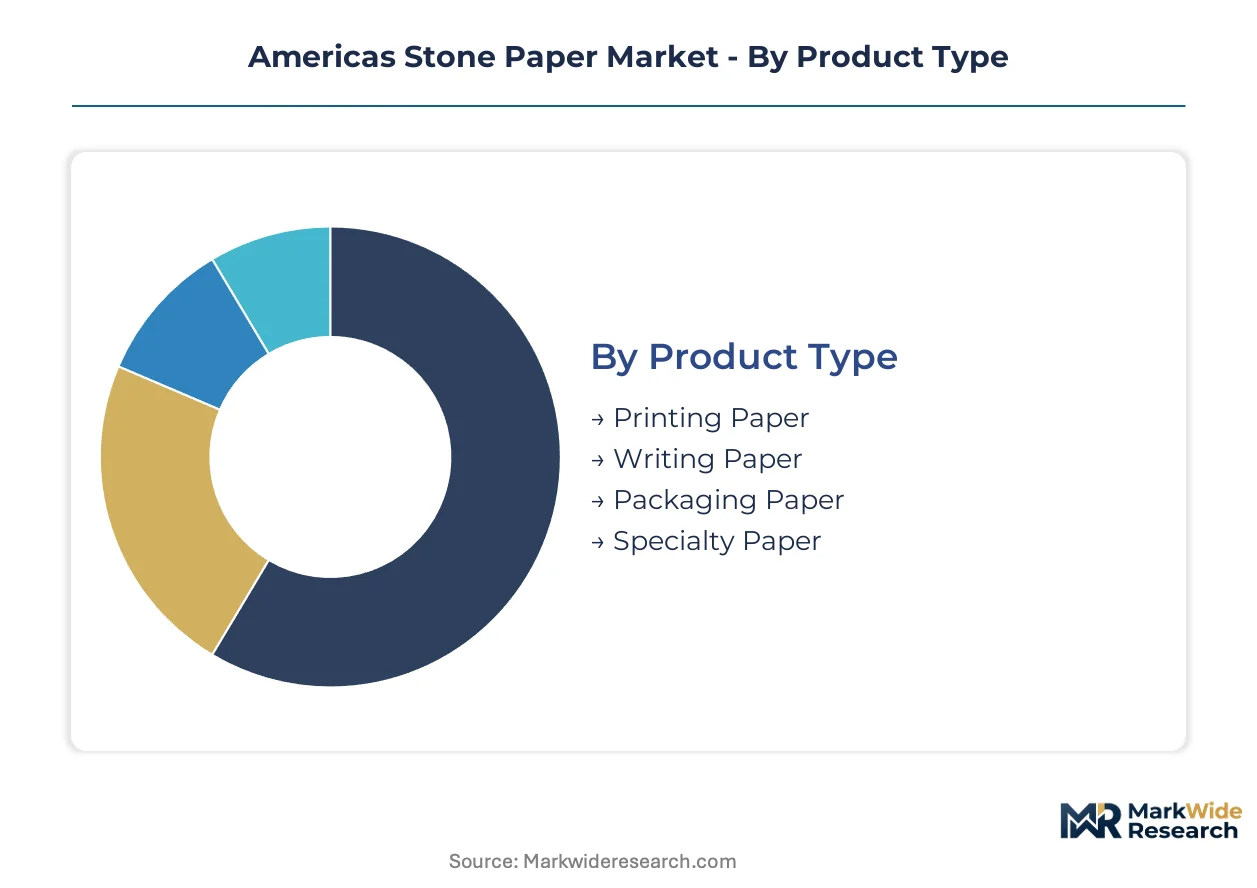
Stone paper manufacturers configure production lines around mineral loading ratios and resin binder specifications that determine end-use eligibility. Segment boundaries in this market reflect technical constraints on FDA food-contact compliance, print resolution thresholds, and heat-sealing temperature limits that channel demand into distinct application clusters.
Product Type:
Printing Paper operates as a standalone substrate for commercial print jobs, while Specialty Paper embeds into regulated food-contact systems requiring certification layers.
- Printing Paper:Calcium carbonate-rich sheets with medium mineral loading balance ink absorption against surface smoothness for offset and digital presses. Demand clusters in California's commercial print corridors where municipal procurement favors mineral-based alternatives.
- Specialty Paper:FDA-compliant formulations with enhanced barrier properties command premium positioning in chocolate and cosmetics labeling segments. Brazilian converters source these grades for Andean export markets where food-contact certification gates retailer acceptance.
- Writing Paper:Smooth surface treatment targets premium stationery segments.
- Packaging Paper:E-commerce cushioning and wrap formats dominate volume off-take.
Volume placements concentrate in Packaging Paper; the faster expansion belongs to Specialty Paper.
End Use:
Stationery applications serve direct consumer channels with premium positioning, whereas Packaging integrates into retailer sustainability scorecard compliance systems.
- Packaging:E-commerce fulfillment operators specify stone-based dunnage and protective wrap to meet California EPR mandates and retailer biodegradability requirements. Mexican extrusion capacity supplies North American converters with cost-competitive mineral substrates.
- Advertising:Outdoor display and promotional formats exploit waterproof, tear-resistant properties for extended campaign durability. Texas and Florida outdoor media buyers are substituting stone-based posters for vinyl in humidity-exposed applications.
- Stationery:Premium notebooks and journals target direct-to-consumer channels.
- Publishing:Limited adoption in book and magazine production due to cost differentials.
Packaging captures the dominant share of current volume; Advertising climbs the fastest as outdoor media sustainability standards tighten.
Thickness:
Thin grades embed into multi-layer laminations, while Thick and Extra Thick segments serve as standalone structural substrates.
- Thin:Sub-100 micron sheets function as printable skins in co-extruded multi-layer constructions. California label converters specify these grades for food-grade applications where barrier performance must combine with print fidelity.
- Thick:Rigid boards replace folding carton and corrugated alternatives in premium gift and electronics packaging. Demand concentrates in New York and Los Angeles metro areas where unboxing experience drives material selection.
- Medium:General-purpose printing and writing applications.
- Extra Thick:Structural dunnage and display board applications.
Medium thickness holds the installed production base; Thin grades gain share fastest as co-extrusion technology diffuses.
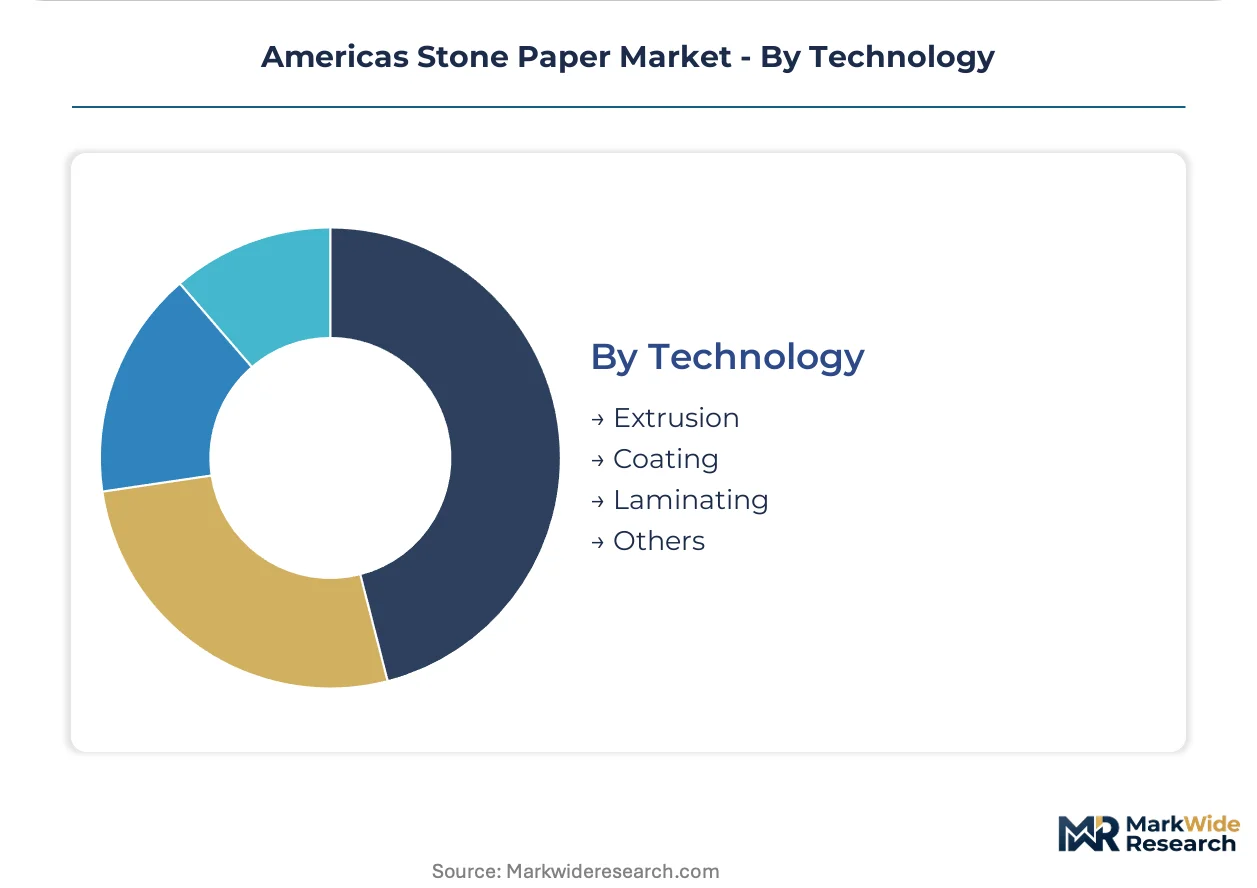
Technology:
Extrusion processes operate as standalone mineral compounding systems, while Coating and Laminating add functional layers that determine print resolution and barrier performance.
- Extrusion:Direct compounding of calcium carbonate powder with polyethylene or polypropylene binders yields the dominant cost structure for volume applications. Mexican mining advances are lowering raw material costs for regional producers serving North American markets.
- Coating:Surface treatment systems enable high-resolution inkjet and UV-curable printing for premium label segments. Equipment concentration in Asian supply chains creates import dependency for converters targeting FDA-certified food-contact grades.
- Laminating:Multi-layer bonding of stone paper with barrier films or other substrates.
- Others:Emerging hybrid processes combining extrusion and coating in single-pass systems.
Extrusion dominates current capacity installation; Coating expands most quickly as digital printing convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's sustainable packaging corridor functions as the hemisphere's primary demand concentration zone, with state-level extended producer responsibility frameworks compressing substitution timelines for mineral-based substrates across North American supply chains.
United States
FDA food-contact substance notifications and EPA recycled-content standards under the Resource Conservation and Recovery Act govern procurement eligibility for federal suppliers. California's plastic waste mandates penalize petroleum-based alternatives, accelerating retailer scorecard adoption of stone-based cushioning formats. The Los Angeles-Long Beach metro cluster anchors West Coast converter demand for FDA-certified food-contact grades.
Brazil
Localized extrusion capacity in São Paulo state anchors South American supply, with Andean export markets pulling specialty grades for cosmetics and chocolate labeling. ANVISA regulates food-contact applications, while state-level environmental frameworks in industrial zones favor mineral substrate substitution. The São Paulo-Rio de Janeiro corridor concentrates converter activity for premium packaging segments.
Mexico
Calcium carbonate extraction advances in northern mining districts are lowering raw material costs for regional extrusion producers serving North American markets. Federal environmental standards align with NAFTA-era procurement protocols, enabling cross-border supply integration. The Nuevo León industrial corridor hosts expanding extrusion capacity targeting Texas and California fulfillment networks.
Colombia
Underpenetrated food-grade label demand in Andean cosmetics and chocolate sectors offers first-mover positioning for FDA-certified stone paper suppliers. National packaging regulations emphasize biodegradability metrics that favor mineral-based substrates over conventional plastic coatings. The Bogotá metropolitan cluster concentrates label converter activity for premium export-oriented brands.
Canada
Health Canada and PMRA standards govern food-contact applications, while federal procurement policies emphasize recycled-content thresholds that mineral-rich substrates satisfy. Provincial extended producer responsibility frameworks in Ontario and British Columbia mirror California's compliance compression. The Greater Toronto Area anchors national converter demand for sustainable packaging alternatives.
Americas Stone Paper Market Competitive Landscape
North American producers anchor one tier; Asian specialists hold coating technology leadership that premium segment entrants depend upon. The vendor base stratifies across three functional tiers: integrated extrusion operators with captive mineral supply, coating-dependent converters serving high-resolution printing grades, and direct-to-consumer brands capturing premium stationery margins. Two dominant competitive moves are reshaping positioning: backward integration into calcium carbonate mining to secure raw material cost stability, and strategic licensing of hybrid extrusion-coating processes to bypass Asian equipment import dependencies.
Within the integrated extrusion tier, Karst Stone Paper and Soluz Stone Paper exemplify contrasting geographic anchoring strategies. Karst occupies a position aligned with direct-to-consumer channel strength across North American stationery segments, while Soluz anchors Brazilian demand through localized production capacity. Taiwan Lung Meng Technology Co. sits within the coating technology vector, representing the Asian specialist archetype that dominates export supply into Mexico and Colombia. These three entities collectively illustrate the regional fragmentation that characterizes competitive dynamics: North American brand-building, South American manufacturing scale, and Asian process technology leadership each command distinct value-capture zones.
| Leading Market Players |
|---|
| Karst Stone Paper |
| Soluz Stone Paper |
| Taiwan Lung Meng Technology Co. |
| Taber Industries |
| Mode Paper Company |
| AM Packaging Company Limited |
| Sphera International |
| STP Stone Paper GmbH |
| Stone Paper Company Limited |
| Others |
Value Network & Pricing Analysis
Extrusion technician scarcity in São Paulo state and Nuevo León industrial zones widens labor-cost differentials between Brazilian and Mexican production bases, compressing pricing-tier spreads as converters arbitrage regional wage gaps against freight economics.
Pricing Analysis
Short lead-time premiums command substantial markups from California e-commerce fulfillment operators facing quarterly retailer scorecard deadlines, while spot inventory discounts clear excess Mexican extrusion capacity during seasonal demand lulls. Three-tier pricing structure across FDA-certified premium, standard commercial, and economy cushion grades separates food-contact certification holders from commodity dunnage suppliers. Price differentiation hinges on resin binder specifications and mineral loading ratios. Cost compression in standard grades intensifies as polyethylene feedstock volatility erodes margin stability. E-commerce shippers exhibit highest price sensitivity; cosmetics label converters demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from California retailer procurement teams mandate multi-supplier qualification across Mexican and Brazilian extrusion bases, preventing single-origin dependency. Geographic supply concentration centers on Mexico, Brazil, and Taiwan for coating equipment. Raw material dependencies rest on calcium carbonate mining output, polyethylene resin contracts, and Asian coating machinery imports. Single-source vulnerability concentrates in high-resolution printing grade supply chains tethered to Taiwanese equipment manufacturers. Distribution runs through direct converter contracts disintermediating traditional paper distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Americas stone paper operates as a supply-constrained market where extrusion technician scarcity props pricing across all tiers by limiting capacity expansion velocity.
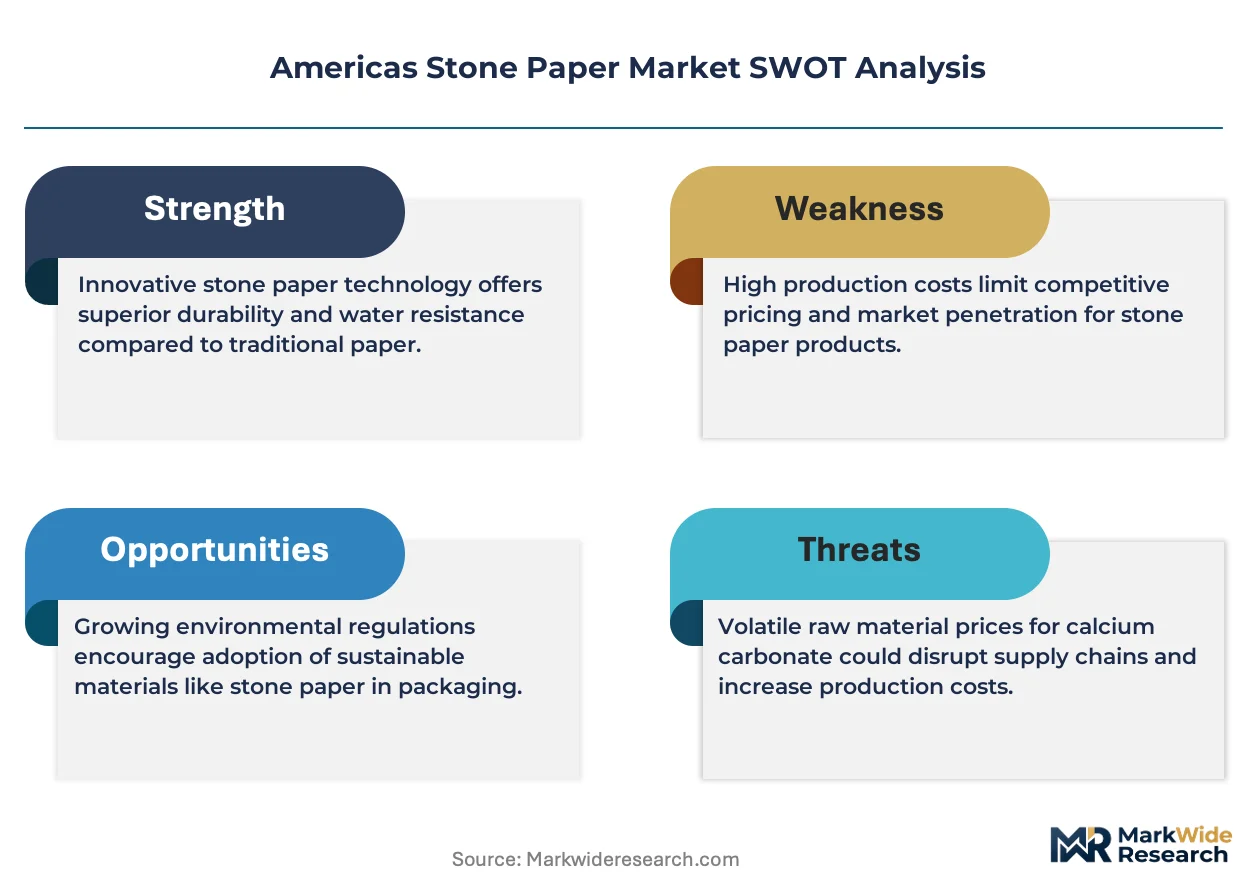
For Market Incumbents: Cement market position through backward integration into Nuevo León calcium carbonate mining to secure raw material cost stability against Mexican extraction efficiency gains. Lock in multi-year resin supply contracts before petrochemical feedstock volatility intensifies. Karst Stone Paper's direct-to-consumer channel strength demonstrates how brand equity defends margin against Asian coating technology imports. For New Entrants and Emerging Players: UV-curable ink compatibility advances offer technology-first wedge positioning for short-run variable data applications previously locked to synthetic films. Target Colombian Andean label converters serving underpenetrated cosmetics and chocolate sectors where FDA certification gates retailer acceptance. Pursue strategic licensing of hybrid extrusion-coating processes to bypass Asian equipment import dependencies. For Investors and Strategic Acquirers: Re-rating potential sits with integrated extrusion operators with captive mineral supply given EPA recycled-content standards restructuring federal procurement eligibility. Five-to-ten year viability favors producers achieving threshold mineral content levels for preferential vendor status. Watch FTC Green Guides revision timing as inflection indicator for marketing-claims enforcement recalibrating competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcium Carbonate Mining | Secures raw material cost stability against Mexican extraction efficiency gains lowering regional input prices. |
| Hybrid Extrusion-Coating Process Licensing | Bypasses Asian equipment import dependencies that constrain premium segment entrants seeking FDA certification. |
| FDA Food-Contact Notification Investment | Unlocks direct packaging applications in premium chocolate and cosmetics labeling commanding price premiums. |
| Direct-to-Consumer Channel Expansion | Replicates Karst Stone Paper's premium stationery positioning across North American urban sustainability corridors. |
| Multi-Year Resin Supply Contracting | Hedges polyethylene and polypropylene input price volatility compressing margin stability for extrusion operators. |
Research Methodology
Document review covered FDA food-contact substance notification filings, EPA recycled-content procurement standards, and California EPR regulatory frameworks, complemented by interviews with extrusion plant managers in São Paulo and Nuevo León, procurement leads at California e-commerce fulfillment operators, coating equipment distributors serving Mexican converters, and technical R&D directors at Brazilian specialty paper formulators. Secondary validation drew from customs trade data on calcium carbonate and resin imports, SEC filings of disclosed suppliers, and ANVISA regulatory submissions. Bottom-up capacity estimates triangulated against top-down demand projections from retailer sustainability scorecard disclosures.
Segment-level volume and value trajectories emerged from modeling across product type, thickness grade, technology process, and end-use application dimensions throughout the forecast period. CAGRs derived from mineral loading ratio adoption curves, e-commerce fulfillment network expansion rates, and FDA certification penetration assumptions. Key inputs included resin binder cost indices, Mexican mining productivity trends, and digital printing convergence velocity.
Several conditions sit outside the modeled scope, including pending FTC Green Guides revision outcomes, ANVISA regulatory alignment shifts with FDA standards, and breakthrough biodegradable resin formulations eliminating petroleum-based binders. Deviation in California EPR enforcement intensity or polyethylene feedstock price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pulp and Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Inlay Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Glassine Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Organic Tissue Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Recording Chart Paper Market
Paper Products
Aramid Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Drum Pulper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Synthetic Paper Market