
 Glassine Paper Market | 2026-2036
Glassine Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Glassine Paper Market Foresight
Buyer concentration among food packaging converters is rebalancing as artisanal bakeries and direct-to-consumer confectionery brands fragment procurement while multinational CPG houses consolidate volume contracts. Stora Enso leverages its Nordic pulp integration to secure cost-advantaged supercalendered grades for European release liner producers. Ahlstrom-Munksjö anchors its position through specialty coating capabilities that serve pharmaceutical blister pack interleaving demands. Mondi Group competes via integrated kraft-to-glassine operations spanning Central European mills.
Glassine paper is a dense, translucent paper manufactured from highly refined chemical wood pulp through extended beating and supercalendering, yielding a smooth, low-porosity surface with grease resistance measured by Kit values typically exceeding 12. Its primary commercial purpose centers on protective packaging, release liner substrates, and food-grade barrier applications where moisture and oil resistance must combine with fiber-based recyclability. Silicone glassine dominates the release liner segment due to its direct coating compatibility with pressure-sensitive adhesive systems, while vegetable glassine represents the fastest-growing product type as botanical wax coatings displace petroleum-derived barriers in cosmetic and premium food wraps. Food packaging applications command the deepest margin pools where brand owners pay certification premiums for compostable greaseproof solutions.
The EU F-Gas Regulation and REACH chemical restrictions are reshaping glassine demand by disqualifying fluorinated grease barriers in favor of mechanical supercalendering and bio-based coatings. FDA food contact substance notifications govern US import acceptance of coated glassine for direct food applications, while China's GB standards for paper packaging establish migration limits that influence exporter formulation choices. Stakeholders must monitor evolving extended producer responsibility schemes across Germany, France, and Italy that will recalibrate cost structures for single-use food wrappers through 2030.
Market Dynamics
The EU F-Gas Regulation and REACH chemical restrictions are structurally disqualifying fluorinated grease barriers, forcing converters toward mechanical supercalendering and bio-based coatings that reshape cost structures and supplier qualifications across food packaging value chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation (PPWR):Mandates for recyclable, plastic-free barrier papers accelerate glassine substitution for polypropylene laminates in premium chocolate and specialty coffee packaging across Germany and France.
- Vegetable glassine coating chemistry:Botanical wax formulations displace petroleum-derived barriers in cosmetic and premium food wraps, opening margin pools where brand owners pay certification premiums for compostable greaseproof solutions.
- Pharmaceutical blister pack interleaving:Silicone glassine dominates release liner substrates as pressure-sensitive adhesive systems expand in transdermal patch and medical device packaging.
Market Restraints
- Bleached chemical wood pulp cost volatility:Extended beating requirements for supercalendered grades tie glassine margins to Nordic pulp pricing cycles and energy-intensive refining processes.
- Supercalendering capacity concentration:Specialized calendering equipment for low-porosity, high-Kit-value production concentrates among integrated European mills, limiting new entrant supply flexibility.
- Fluorinated barrier substitution timeline:REACH restrictions on per- and polyfluoroalkyl substances force rapid formulation pivots, but bio-based coatings still lag polypropylene laminates on grease resistance at equivalent basis weights.
Strategic Opportunities
- Direct-to-consumer confectionery channels:Artisanal bakeries and boutique chocolate brands fragment procurement away from multinational CPG volume contracts, creating entry points for specialty coating capabilities.
- Extended producer responsibility schemes:Germany, France, and Italy will recalibrate cost structures for single-use food wrappers through 2030, advantaging fiber-based recyclability over plastic laminates.
- Silicone coating and pressure-sensitive adhesive convergence:Release liner producers demand direct coating compatibility, consolidating demand for supercalendered grades with optimized surface chemistry.
Industry Challenges
- Compostable certification timelines:Home and industrial compostability standards for wax-coated glassine require multi-year testing protocols that delay product launches and tie up R&D resources.
- Supercalendering operator skill scarcity:The precise control of nip pressure, temperature, and speed to achieve Kit values exceeding 12 demands experienced papermakers that mills struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glassine Paper Market |
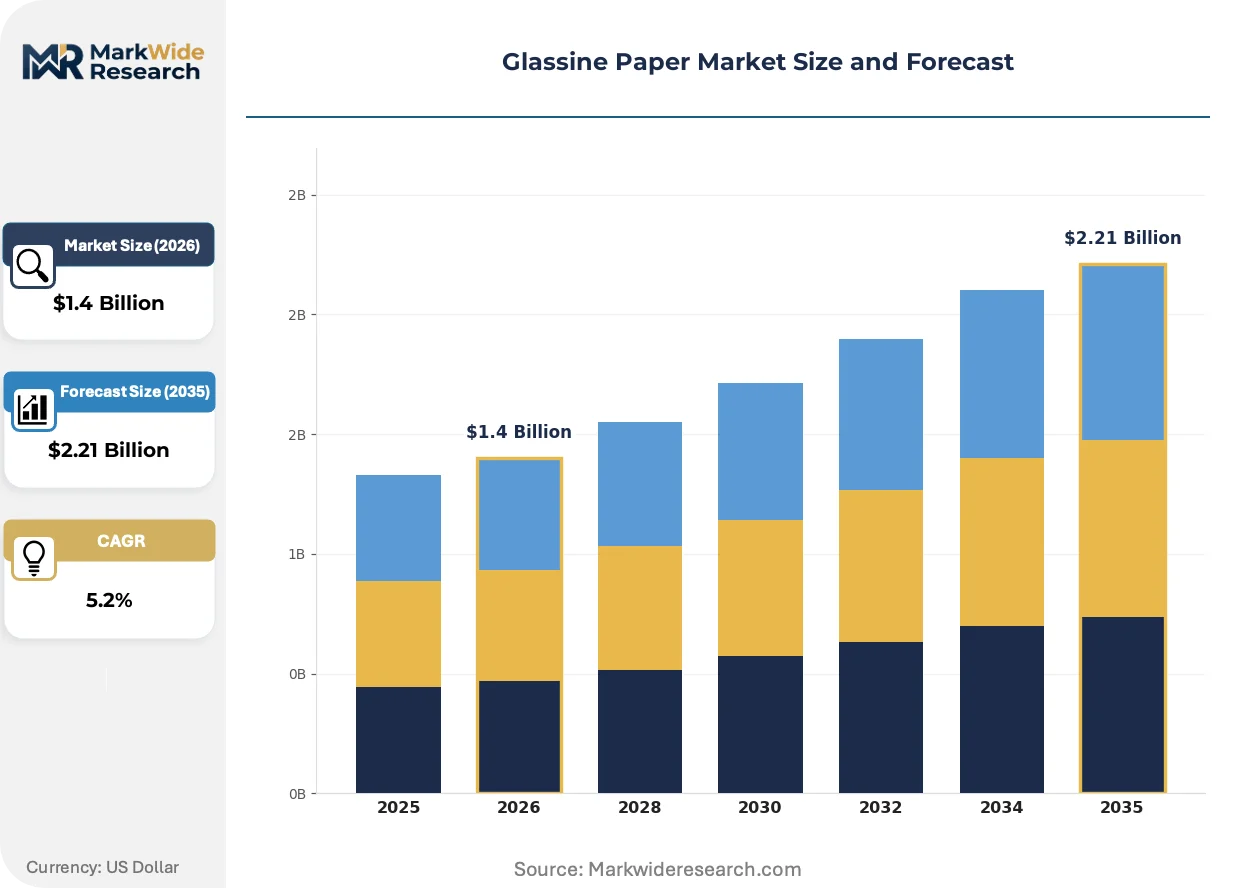
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supercalendered, Machine Finished, Coated Glassine, Silicone Glassine, Vegetable Glassine Application: Food Packaging, Release Liners, Industrial Packaging, Electrical Insulation, Craft & Stationery End User Industry: Printing, Pharmaceutical, Electronics Manufacturing, Textile Production, Cosmetic Packaging Packaging Type: Rolls, Sheets, Fanfold, Jumbo Rolls, Cut Sizes |
| Companies Covered | Stora Enso, Ahlstrom-Munksjö, UPM-Kymmene Corporation, Loparex Group, Mondi Group, Glatfelter, Nippon Paper Industries, Delfortgroup AG, Sappi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glassine Paper Market Shifts & Advancements
Mechanical supercalendering and bio-based coating chemistry are displacing fluorinated barriers as the central technical pivot, while procurement fragmentation and regulatory compliance reshape competitive positioning across food, pharmaceutical, and industrial release liner segments.
Vegetable glassine is consolidating its position as the dominant sustainable alternative to petroleum-derived barrier coatings. Botanical wax formulations from rice bran, carnauba, and candelilla sources provide grease resistance measured by Kit values approaching fluorinated standards. Premium cosmetic brands and specialty food packagers in Germany and France are adopting these grades at accelerated pace, compressing the price premium versus conventional glassine and forcing coating specialists to scale production or exit the segment.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from EU food contact applications. The regulation's industrial consequence is a forced migration toward mechanical densification through extended beating and supercalendering, supplemented by bio-based topical treatments. Bakery wrap and confectionery interleaving applications in Germany, where premium chocolate brands previously favored polypropylene laminates, are most affected and are responding by qualifying new suppliers with certified compostable coating capabilities.
Buyer concentration patterns are fragmenting as artisanal bakeries and direct-to-consumer confectionery brands disintermediate traditional packaging distributors. These smaller-volume, higher-margin accounts prioritize certified compostable solutions over unit cost minimization, replacing the procurement leverage of multinational CPG houses with specification-driven selection. This behavioral shift is most visible in France and Italy, where regional specialty food producers and boutique cosmetic brands drive demand for vegetable glassine with traceable supply chains and third-party compostability verification.
Glassine Paper Market Segmentation
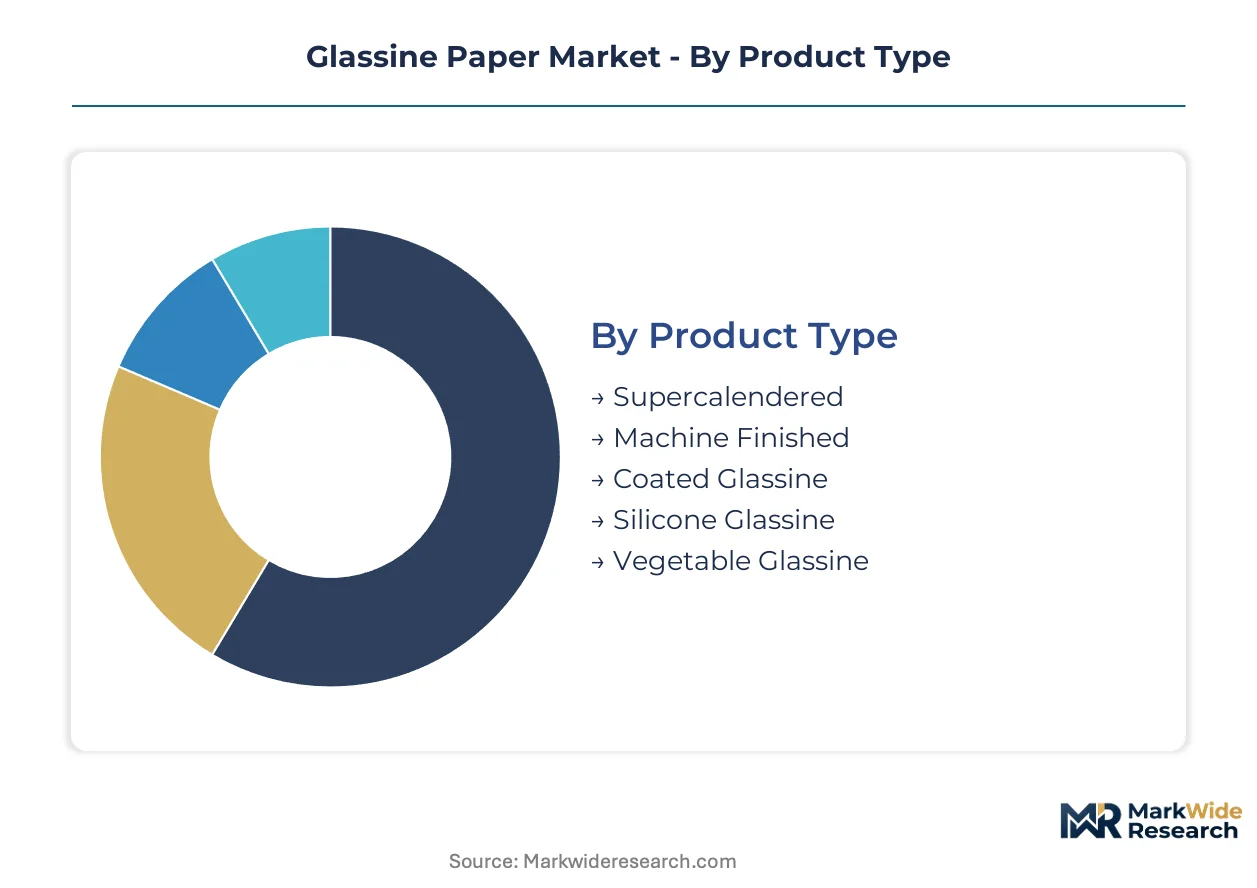
Glassine paper specifications diverge sharply across end-use requirements, with supercalendering intensity, coating chemistry, and format dimensions determining suitability for food contact, pharmaceutical interleaving, or adhesive release functions. Understanding these technical axes reveals where margin pools concentrate and which formulations command certification premiums.
Product Type:
Technical specifications around densification method and barrier chemistry define performance ceilings and regulatory compliance pathways.
- Supercalendered:Manufactured through extended beating of bleached chemical pulp followed by multi-nip calendering, achieving Kit grease resistance values above 12 without fluorinated additives. German chocolate and specialty coffee brands specify these grades for direct food contact under EU PPWR mandates, though capacity concentrates among Nordic integrated mills.
- Vegetable Glassine:Botanical wax coatings from rice bran, carnauba, and candelilla displace petroleum-derived barriers, delivering compostable greaseproof solutions that cosmetic and premium food packagers in France and Italy adopt at accelerated pace. REACH restrictions on per- and polyfluoroalkyl substances compress the price premium versus conventional grades.
- Silicone Glassine:Optimized surface chemistry enables direct coating compatibility with pressure-sensitive adhesive systems for transdermal patch and medical device release liners.
- Coated Glassine:Topical treatments enhance moisture barrier performance for industrial applications requiring controlled porosity.
- Machine Finished:Lower densification yields cost-efficient grades for craft and non-food protective wrapping where grease resistance thresholds are modest.
Supercalendered leads on scale; vegetable glassine leads on momentum.
Application:
End-use performance requirements segment the market by barrier intensity, regulatory scrutiny, and certification complexity.
- Food Packaging:Grease-resistant bakery wraps and confectionery interleaving demand the highest Kit values and compostable certifications, with German and French brand owners paying premiums for plastic-free barrier papers under extended producer responsibility schemes.
- Release Liners:Silicone-coated substrates for pressure-sensitive adhesive systems in transdermal patches and medical devices require precise surface energy control and low extractable content governed by EMA and FDA standards.
- Industrial Packaging:Moisture-resistant interleaving for metal components and precision parts prioritizes cost efficiency over food-contact compliance.
- Electrical Insulation:Dielectric strength and thermal stability specifications serve transformer and capacitor manufacturing.
- Craft & Stationery:Translucency and printability drive demand for scrapbooking, envelope windows, and archival applications with minimal barrier requirements.
Food packaging commands the deepest margins; release liners offer the most defensible technical moats.
End User Industry:
Customer technical sophistication and procurement scale determine specification stringency and supplier qualification barriers.
- Pharmaceutical:Blister pack interleaving and transdermal patch substrates demand batch traceability, low bioburden, and compliance with EU MDR and FDA food contact notifications.
- Cosmetic Packaging:Premium brands in France and Germany specify vegetable glassine with third-party compostability verification for sustainable brand positioning.
- Printing:Commercial printers prioritize dimensional stability and ink adhesion across variable humidity conditions.
- Electronics Manufacturing:Cleanroom-compatible release liners for component handling require particulate control and static dissipation properties.
- Textile Production:Pattern interleaving and fusible backing applications use lower-density grades where heat resistance exceeds grease barrier requirements.
Pharmaceutical leads on specification intensity; cosmetic packaging leads on sustainability-driven specification change.
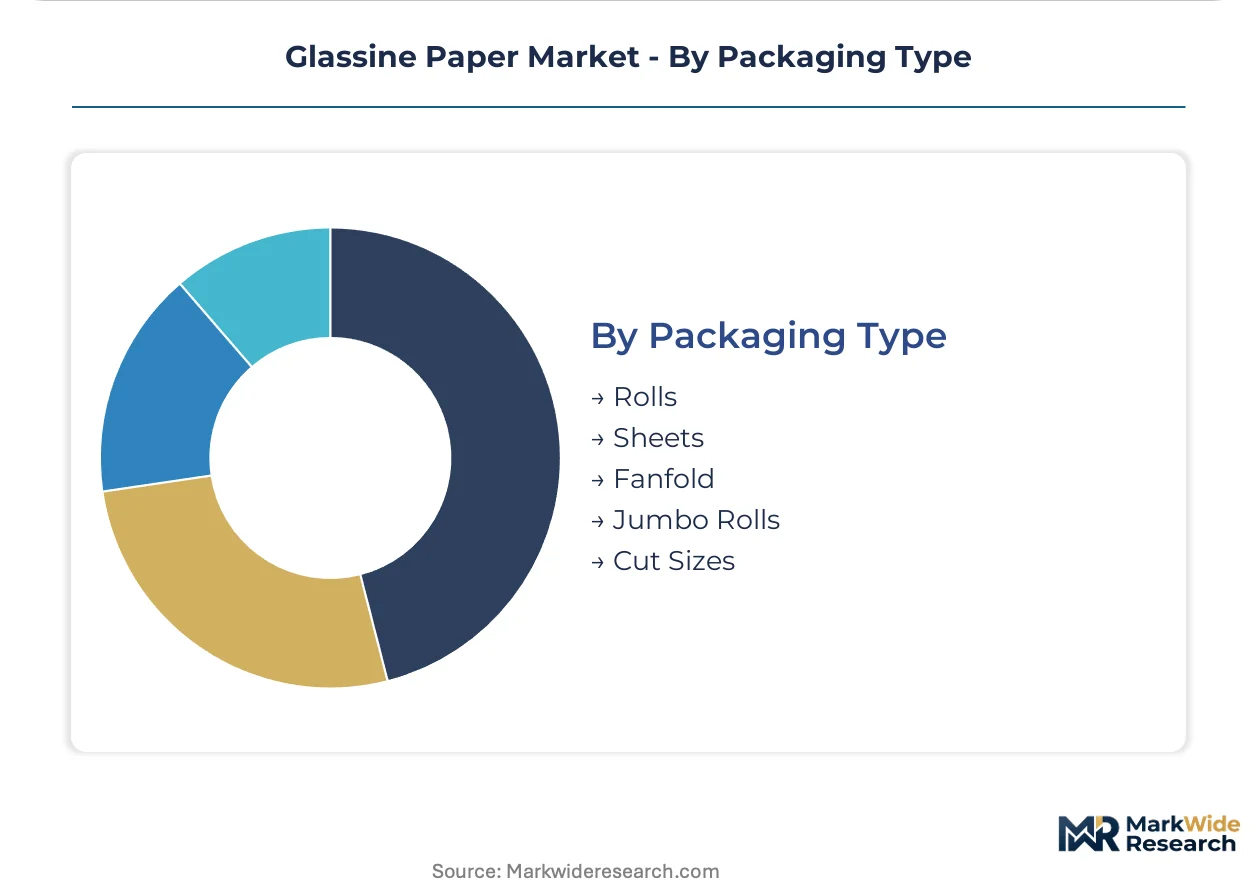
Packaging Type:
Format dimensions align with converter equipment configurations and end-use processing economics.
- Rolls:Continuous web supply for high-speed flexographic and gravure printing lines, with German and Italian converters specifying tight width tolerances for automated splicing.
- Jumbo Rolls:Mill-direct formats minimize slitting costs for large-volume release liner producers with in-house converting capabilities.
- Sheets:Cut-to-size supply serves artisanal bakeries and boutique confectionery brands with small-batch packaging requirements.
- Fanfold:Continuous zig-zag folding enables manual or semi-automated interleaving operations in textile and industrial settings.
- Cut Sizes:Precision-dimensioned pieces for craft, stationery, and specialty food wrapping where retail presentation matters.
Rolls lead on volume throughput; sheets lead on margin capture per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Papermaking talent clusters in Nordic integrated mills anchor European supply, while converter networks in Germany and France concentrate demand for certified compostable grades. North American capacity serves FDA-regulated food contact applications, and Asian producers scale mechanical densification for export markets.
Germany
Premium chocolate brands and specialty coffee roasters specify supercalendered glassine for direct food contact under extended producer responsibility schemes. The EU Packaging and Packaging Waste Regulation mandates plastic-free barrier papers, disqualifying polypropylene laminates. The Baden-Württemberg and Bavaria industrial corridors host converter clusters qualifying new suppliers with certified compostable coating capabilities.
United States
Artisanal bakeries and direct-to-consumer confectionery brands fragment procurement toward specification-driven selection. FDA food contact substance notifications govern import acceptance of coated glassine for direct food applications. The Midwest papermaking belt and Northeast packaging corridors concentrate release liner production for pressure-sensitive adhesive systems.
France
Regional specialty food producers and boutique cosmetic brands drive demand for vegetable glassine with traceable supply chains. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated grease barriers from food contact applications. The Île-de-France and Auvergne-Rhône-Alpes regions anchor procurement networks prioritizing third-party compostability verification over unit cost minimization.
China
GB standards for paper packaging establish migration limits that influence exporter formulation choices for coated glassine. The dual carbon goals framework pressures energy-intensive supercalendering operations to decarbonize refining processes. The Yangtze River Delta and Shandong Peninsula clusters scale mechanical densification capacity for pharmaceutical blister pack interleaving exports.
Italy
Boutique confectionery brands and artisanal food packagers specify vegetable glassine for sustainable brand positioning. Extended producer responsibility schemes will recalibrate cost structures for single-use food wrappers through 2030. The Emilia-Romagna and Lombardy industrial districts concentrate converter operations serving premium cosmetic and specialty food segments.
Glassine Paper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Integrated Nordic pulp-to-paper producers occupy the upstream cost-advantaged position, while coating specialists command premium tiers through certified compostable capabilities. Converter-integrated players and independent release liner substrate suppliers populate the mid-market. Dominant competitive moves include backward integration into Nordic pulp supply and specialty coating technology licensing for bio-based barrier formulations.
Among Nordic integrated producers, Stora Enso and UPM-Kymmene Corporation exemplify the upstream-cost-advantage archetype through captive pulp supply. Ahlstrom-Munksjö occupies a position within the specialty coating tier, representing the certified-compostable capability focus that premium brand owners specify. Mondi Group sits within the converter-integrated tier, exemplifying kraft-to-glassine operational span across Central European mill networks.
| Leading Market Players |
|---|
| Stora Enso |
| Ahlstrom-Munksjö |
| UPM-Kymmene Corporation |
| Loparex Group |
| Mondi Group |
| Glatfelter |
| Nippon Paper Industries |
| Delfortgroup AG |
| Sappi Limited |
| Others |
Supply & Pricing Matrix
Supercalendering operator skill scarcity in Nordic integrated mills widens labor-cost differentials between premium Kit-value grades and standard mechanical finishes. This workforce concentration compresses margin spreads at the economy tier while certification premiums for compostable vegetable glassine sustain elevated pricing floors in Germany and France.
Pricing Analysis
The bundled-versus-unbundled service split separates mill-direct jumbo roll supply from converter-managed slitting and coating operations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with silicone glassine commanding sustained premiums for pharmaceutical release liner compatibility. Cost compression in economy grades is intensifying because Asian mechanical densification capacity expands export availability. Artisanal bakeries and boutique confectionery brands show least price sensitivity, prioritizing compostable verification over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle multinational CPG volume contracts, while specialty distributors serve fragmented artisanal accounts. Geographic supply concentrates in Finland, Sweden, and Germany where integrated pulp-to-paper operations anchor supercalendered capacity. Raw material dependencies draw from Nordic bleached chemical pulp, botanical wax feedstocks, and silicone coating chemistries. Single-source vulnerability sits with specialized calendering equipment manufacturers concentrated in Central Europe. Distribution runs through mill-direct arrangements for release liner producers and regional paper merchants for food packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glassine paper market functions as a regulatory compounder where EU PPWR mandates for plastic-free barrier papers structurally displace polypropylene laminates and revalue fiber-based recyclability.
For Market Incumbents: Hedge fluorinated barrier obsolescence by accelerating bio-based coating R&D partnerships and securing Nordic pulp offtake agreements. Stora Enso and UPM-Kymmene should extend supercalendering capacity utilization through pharmaceutical release liner qualifications that lock in multi-year silicone glassine contracts.
For New Entrants and Emerging Players: Enter via vegetable glassine coating specialization targeting French cosmetic packagers and Italian boutique confectionery brands demanding traceable supply chains. White-space concentration sits in certified compostable interleaving for direct-to-consumer chocolate channels where specification-driven procurement fragments away from volume-discount contracts.
For Investors and Strategic Acquirers: Specialty coating pure-plays with EU compostability certifications are the most active acquirer targets in this space as integrated conglomerates seek downstream barrier technology. Acquisition focus should center on mid-scale vegetable glassine producers in France and Italy. The signal to watch is accelerated qualification timelines for home compostability standards that compress certification premiums and force coating scale-or-exit dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive bleached chemical pulp access insulates margin volatility from spot market cycles. |
| Specialty Coating Technology Licensing | Bio-based barrier formulation partnerships accelerate REACH-compliant product pipelines for German chocolate brands. |
| Compostability Certification Investment | Third-party verification unlocks premium positioning under France and Italy extended producer responsibility schemes. |
| Release Liner Substrate Qualification | Silicone glassine approvals for transdermal patch applications anchor defensible pharmaceutical revenue streams. |
| Direct-to-Consumer Channel Development | Artisanal bakery and boutique confectionery relationships capture specification-driven margin pools outside CPG volume contracts. |
Research Methodology
Multiple input streams — executive interviews with paper mill operations directors, procurement leads at German and French food packaging converters, and regulatory affairs specialists at coating technology providers — were reconciled against customs trade data, EU PPWR implementation timelines, and SEC filings from publicly traded pulp producers. Secondary validation drew from Nordic pulp pricing indices, REACH restriction update notices, and compostability certification registry databases. Bottom-up volume estimates from mill capacity utilization rates were triangulated with top-down demand segmentation across food, pharmaceutical, and industrial release liner applications.
Data-stream reconciliation anchored the analytical framework across the analysis window, modeling product type, application intensity, end-use industry sophistication, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating EU F-Gas Regulation phase-out schedules and vegetable glassine substitution curves. Forecast inputs included supercalendering capacity expansion announcements and extended producer responsibility scheme implementation trajectories in Germany, France, and Italy.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time mill operating rate disclosures introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding REACH enforcement intensity and compostability standard adoption timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Sanitary Paper Products Market
Paper Products
Global Paperboard Market
Paper Products
Medical Grade Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Printing and Writing Papers Market
Paper Products
Sawn Wood Market
Paper Products
Thermal Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Paper Making Machine Market
Paper Products
Graphic Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Heat Transfer Paper Market