
 North America Medium-Density Fiberboard Market | 2026-2036
North America Medium-Density Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medium-Density Fiberboard Market Intelligence
Aftermarket panel refinishing and resurfacing services is reshaping margin distribution away from virgin board sales toward lifecycle value capture in the North America Medium-Density Fiberboard Market. Roseburg Forest Products leverages backward integration into timberlands and resin chemistry to control input costs across Oregon and the US Southeast. Weyerhaeuser Company anchors its position through massive manufacturing scale and direct distribution to national homebuilders. Georgia-Pacific differentiates via proprietary moisture-resistant formulations that command specification in kitchen and bath cabinetry.
Medium-density fiberboard is an engineered wood product manufactured from refined wood fibers bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 800 kilograms per cubic meter. The material provides a uniform, machinable substrate primarily serving furniture manufacturing, interior millwork, and decorative surfacing applications where dimensional stability and paint-grade finish quality matter. Moisture-resistant MDF commands premium positioning in kitchen and bath segments where ANSI A208.2 performance standards govern swell resistance. Standard MDF retains the largest volume footprint across furniture and decorative panel applications. Fire-retardant grades are gaining specification share in commercial and institutional build-outs where ICC-ES evaluation reports drive code compliance.
EPA TSCA Title VI and CARB ATCM Phase 2 set formaldehyde emission ceilings that force resin reformulation and third-party certification across all domestic production. US OSHA workplace exposure limits and state-level air quality districts in California, Oregon, and Washington add layered compliance obligations for panel finishing and fabrication facilities. Stakeholders must monitor evolving LEED v5 material health criteria and biogenic carbon accounting rules that will reshape specification power between domestic mills and import-dependent distributors.
Market Dynamics
EPA TSCA Title VI formaldehyde emission ceilings are compressing resin chemistry choices across North American mills, forcing simultaneous capital deployment into low-emission adhesive systems and third-party certification infrastructure while timber supply concentration in the US Southeast reshapes procurement geography.
Growth Catalysts
- CARB ATCM Phase 2 alignment:California's Air Resources Board maintains the continent's strictest formaldehyde thresholds, creating certification premiums for compliant producers serving kitchen cabinetry and institutional furniture.
- Ready-to-assemble furniture expansion:Flat-pack residential furniture manufacturers are specifying higher MDF volumes for knock-down construction where dimensional stability and machinability reduce assembly labor.
- US Southeast timber clustering:Integrated pulp-to-panel mill complexes in Georgia, Alabama, and Mississippi capture logistics advantages from proximity to pine plantation feedstock.
Market Restraints
- Urea-formaldehyde resin cost volatility:Natural gas and methanol pricing swings directly compress margin on standard-grade production where petrochemical inputs dominate formulation economics.
- Single-region timber dependence:Pine plantation supply concentration across the US Southeast creates weather and disease exposure that propagates through fiber costs.
- Particleboard substitution in economy furniture:Lower-density engineered panels capture specification share in price-sensitive retail furniture where surface finish requirements are relaxed.
Strategic Opportunities
- Canadian underpenetration:Ontario and Quebec markets show lower MDF per-capita consumption versus US counterparts, with opportunity in residential renovation and multi-family construction.
- Biogenic carbon accounting integration:LEED v5 material health criteria are elevating specification power for domestically produced panels with verified forest certification and resin emission documentation.
- Direct-to-fabricator digital channels:E-procurement platforms are compressing distributor layers for mid-size millwork shops seeking specification-grade material with lot traceability.
Industry Challenges
- Resin chemistry talent scarcity:Formulation expertise for low-emission adhesive systems remains concentrated among a narrow cohort of specialized chemists, constraining R&D velocity.
- Certification timeline compression:Third-party TSCA Title VI validation cycles create working capital pressure for mills launching new product grades.
- Legacy finishing equipment compatibility:Fabricators running solvent-based coating lines face retrofit costs to handle moisture-resistant MDF surfacing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medium-Density Fiberboard Market |
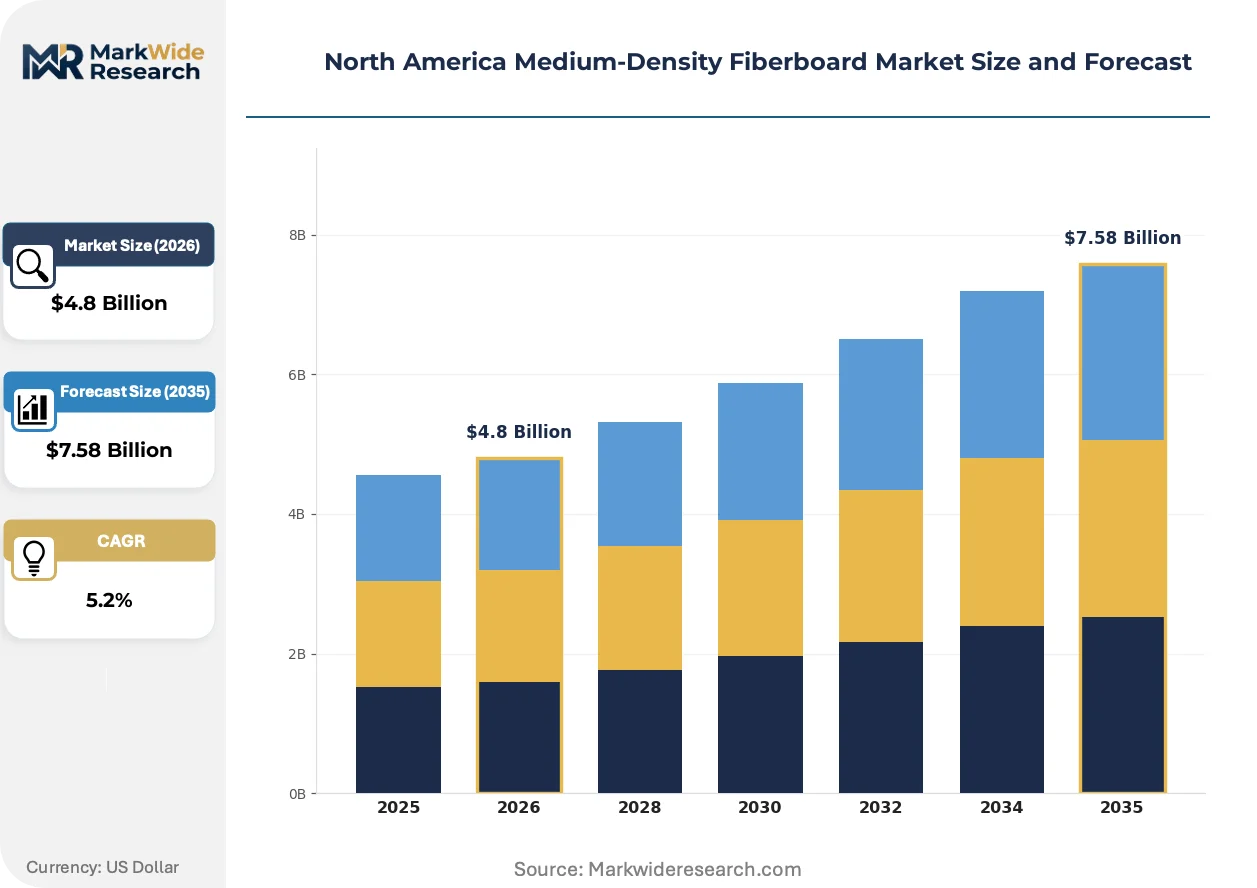
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MDF, Moisture-Resistant MDF, Fire-Retardant MDF, Ultralight MDF Application: Furniture, Cabinetry, Flooring, Decorative Panels End User: Residential, Commercial, Institutional, Industrial Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | Roseburg Forest Products, Weyerhaeuser Company, West Fraser Timber Co. Ltd., Swiss Krono AG, Uniboard, Georgia-Pacific, ARAUCO, Norbord Industries, EGGER Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medium-Density Fiberboard Market Strategic Shifts & Innovations
Low-emission adhesive chemistry and digital procurement infrastructure are compressing traditional competitive advantages in the North America Medium-Density Fiberboard Market, while lifecycle service models capture margin beyond virgin panel sales.
Polymeric diphenylmethane diisocyanate (pMDI) resin systems are displacing urea-formaldehyde in moisture-resistant grades, delivering ANSI A208.2-compliant swell performance without formaldehyde emissions. Kitchen and bath cabinet manufacturers are specifying pMDI-bonded panels for warranty-backed installations. This chemistry shift is rendering obsolete legacy particleboard substrates in wet-zone applications.
EPA TSCA Title VI third-party certification requirements are consolidating the supplier base toward mills with capitalized testing infrastructure. Smaller regional producers face compliance cost barriers that favor integrated manufacturers with in-house laboratories. The US Southeast and California specification markets are responding with preferential procurement from certified domestic sources over import-dependent distributors.
Fabricator procurement is consolidating toward direct mill relationships with lot-traceable documentation for LEED and CARB compliance. Mid-size millwork shops are bypassing traditional two-step distribution for volume commitments with Tier-1 producers. This channel compression is most visible in Texas, Florida, and Pacific Northwest metropolitan construction corridors where project-scale documentation requirements are strictest.
North America Medium-Density Fiberboard Market Segmentation
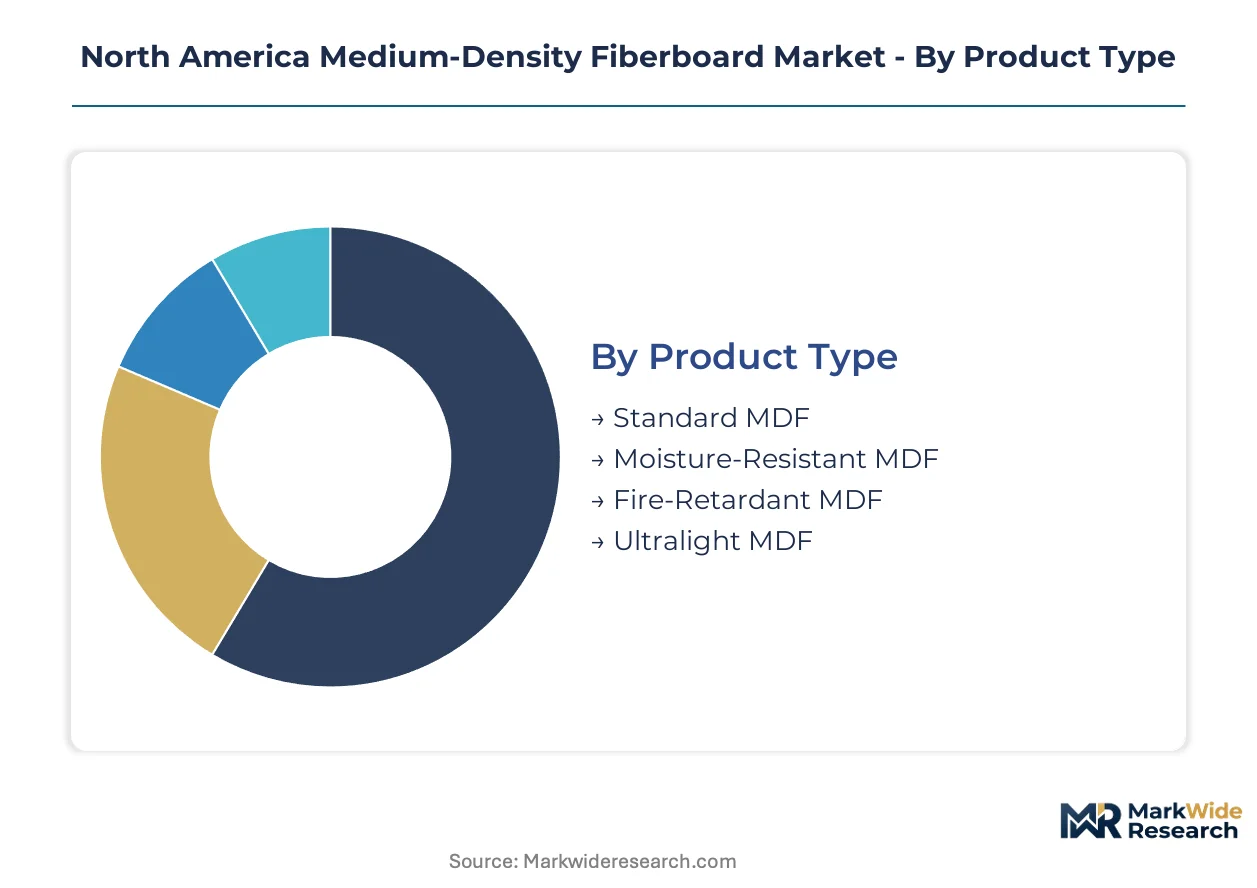
Segmentation in the North America Medium-Density Fiberboard Market reveals how resin chemistry, moisture performance, and fire-rated specifications create distinct procurement tiers. Buyers segment demand by regulatory exposure, end-use durability requirements, and fabrication method.
Product Type:
Cost tier differentiation separates commodity-grade panels from premium formulations that command specification premiums in code-sensitive applications.
- Standard MDF:Urea-formaldehyde bonded panels at 600-800 kg/m³ density serve paint-grade furniture and decorative surfacing where emission compliance meets baseline EPA TSCA Title VI thresholds. Furniture manufacturers in the US Southeast specify this grade for ready-to-assemble bedroom and living room collections where cost control dominates procurement.
- Moisture-Resistant MDF:pMDI resin systems replace formaldehyde-based adhesives to achieve ANSI A208.2 swell resistance below 8% thickness expansion. Kitchen and bath cabinet manufacturers in California and Florida specify this grade for warranty-backed installations near water sources.
- Fire-Retardant MDF:ICC-ES evaluation report compliance drives specification in commercial build-outs requiring Class A flame spread ratings.
- Ultralight MDF:Reduced density formulations target display fixtures and trade-show construction where transport weight limits fabrication feasibility.
Standard MDF holds installed capacity. Moisture-Resistant MDF is rotating up the share rankings.
Application:
End-use durability requirements segment demand by exposure severity and surface finish specifications.
- Furniture:Flat-pack residential manufacturers specify high-volume standard grades for knock-down construction where dimensional stability reduces assembly labor. IKEA-scale producers in Texas and the Carolinas drive procurement concentration for this segment.
- Cabinetry:Moisture-resistant and fire-retardant grades capture specification share in kitchen, bath, and commercial millwork where ANSI performance standards govern warranty terms. California cabinet shops face CARB ATCM Phase 2 documentation requirements that filter supplier selection toward certified domestic mills.
- Flooring:High-density substrates serve laminate flooring cores where impact resistance and screw-holding strength matter.
- Decorative Panels:Surfacing-grade panels with ultra-smooth faces target thermofoil and high-pressure laminate bonding in hospitality and healthcare interiors.
Cabinetry commands the steepest expansion trajectory. Flooring maintains steady volume through replacement cycles.
End User:
Customer type determines compliance documentation depth and volume procurement patterns.
- Residential:Homebuilders and renovation contractors specify standard and moisture-resistant grades through direct mill relationships or two-step distribution. Multi-family construction in Florida and Texas drives recurring demand for paint-grade interior millwork.
- Commercial:Office, retail, and hospitality build-outs require fire-retardant certification and LEED documentation that favors domestic producers with chain-of-custody certification.
- Institutional:Schools, hospitals, and government facilities impose strict emission and fire-safety standards that consolidate procurement toward Tier-1 certified suppliers.
- Industrial:Packaging, fixtures, and equipment manufacturers consume ultralight and standard grades where structural performance requirements are relaxed.
Residential absorbs the highest absolute volume. Institutional buyers are consolidating supplier lists fastest.
Distribution Channel:
Supply chain configuration segments by documentation capability and lot traceability requirements.
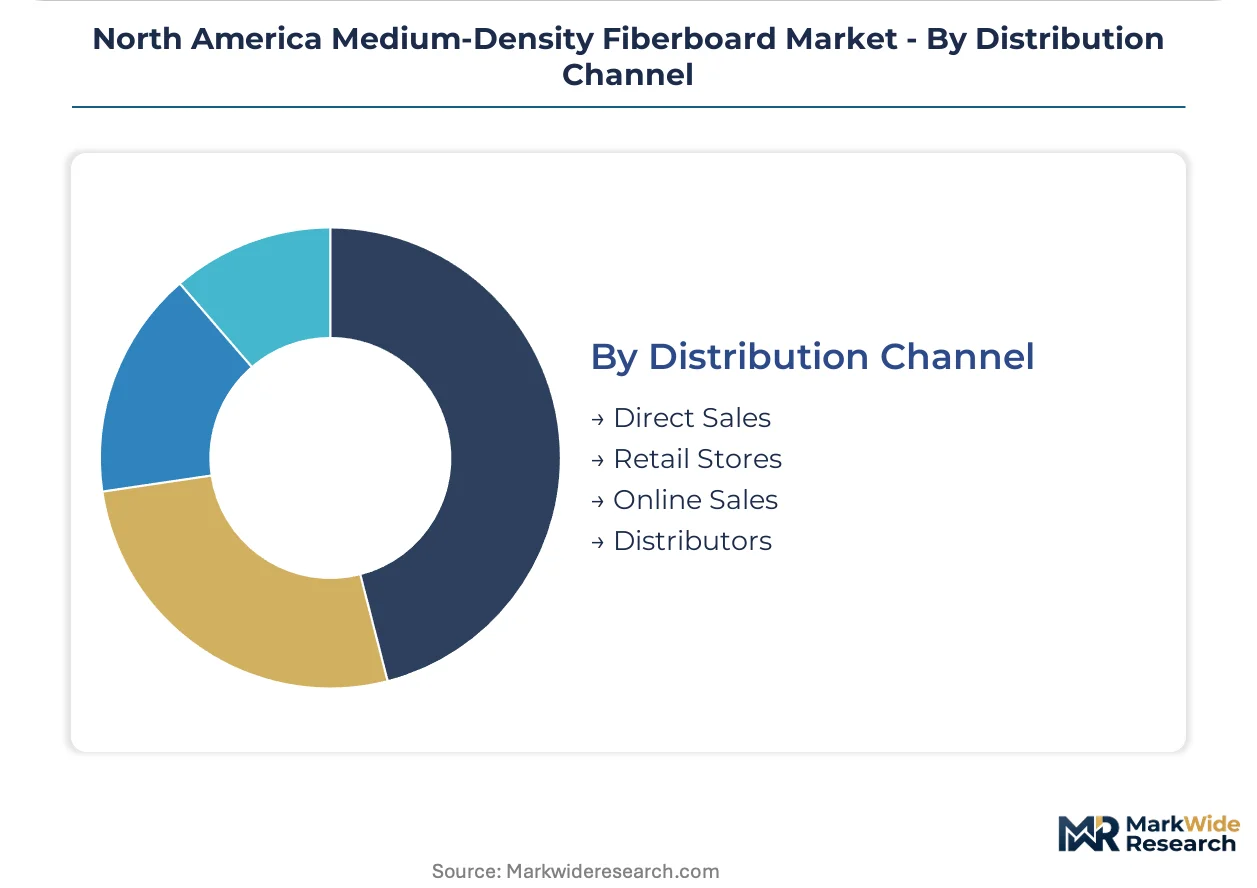
- Direct Sales:National homebuilders and large millwork fabricators contract directly with Roseburg, Georgia-Pacific, and Weyerhaeuser for volume commitments with project-level certification documentation. This channel captures the majority of moisture-resistant and fire-retardant specification volume.
- Retail Stores:Home centers and lumberyards serve small contractors and DIY renovators with standard-grade inventory held for immediate pickup. California retail locations increasingly stock CARB-certified product lines exclusively.
- Online Sales:E-procurement platforms aggregate mid-size fabricator demand with lot-traceable documentation for LEED compliance, compressing traditional distributor margins in Texas and Pacific Northwest metropolitan corridors.
- Distributors:Two-step distributors retain relevance in fragmented geographies and for smaller fabricators lacking volume to qualify for direct mill pricing.
Direct Sales holds margin concentration. Online Sales is gaining share fastest among mid-size fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the US Southeast show lowest price elasticity due to integrated mill proximity, while Canadian fabricators face higher delivered costs that compress margins on standard-grade procurement.
United States
Residential furniture manufacturers in Texas and the Carolinas drive volume demand for ready-to-assemble construction. EPA TSCA Title VI certification requirements filter supplier selection toward domestic mills with third-party validation infrastructure. Georgia and Alabama host integrated pulp-to-panel complexes capturing logistics advantages from pine plantation feedstock proximity.
Canada
Ontario and Quebec markets exhibit lower per-capita MDF consumption versus US counterparts, with renovation contractors and multi-family builders representing underpenetrated demand pools. Health Canada maintains aligned emission standards with EPA thresholds, reducing regulatory friction for cross-border suppliers. British Columbia coastal mills face fiber cost pressures from mountain pine beetle salvage timber depletion.
Mexico
Furniture export manufacturers in Guanajuato and Nuevo León specify MDF for US-bound finished goods, leveraging maquiladora duty advantages. Mexico's national environmental regulator enforces formaldehyde emission protocols through NOM standards that approximate CARB Phase 2 stringency. Querétaro hosts growing cabinet fabrication clusters serving domestic middle-class housing expansion.
North America Medium-Density Fiberboard Market Key Industry Players
Integrated timberland owners and specialty resin formulators split the market between cost-controlled volume production and premium-grade specification capture. Three archetypes dominate: backward-integrated forest products conglomerates with captive timber supply; chemical technology specialists commanding moisture-resistant formulation premiums; and regional mill operators dependent on spot fiber markets. Competitive moves concentrate on direct-to-fabricator channel compression and certification infrastructure deployment.
Among North American integrated producers, Roseburg Forest Products and Weyerhaeuser Company exemplify the timberland-backed archetype with upstream resource control, while Georgia-Pacific represents the formulation-differentiated position. These three occupy the Tier-1 supplier tier where project-scale documentation and lot traceability consolidate procurement relationships.
| Leading Market Players |
|---|
| Roseburg Forest Products |
| Weyerhaeuser Company |
| West Fraser Timber Co. Ltd. |
| Swiss Krono AG |
| Uniboard |
| Georgia-Pacific |
| ARAUCO |
| Norbord Industries |
| EGGER Group |
| Others |
Cost & Logistics Intelligence
Interstate freight corridors connecting Georgia pine plantations to Texas furniture clusters transmit fiber cost volatility directly into panel pricing tiers, compressing margins on standard grades while amplifying premiums for certified moisture-resistant formulations.
Pricing Analysis
Aftermarket panel refinishing and lifecycle service contracts now capture margin beyond virgin board sales, rebalancing revenue toward recurring maintenance streams. Pricing stratifies across premium, standard, and economy tiers where CARB ATCM Phase 2 certification commands specification premiums in California cabinetry markets. Cost compression in commodity grades intensifies because particleboard substitution erodes volume leverage. Small retail fabricators exhibit highest price sensitivity, while institutional buyers with LEED documentation requirements accept premium positioning for lot-traceable domestic supply.
Supply Chain Analysis
Pine plantation fiber supply concentrates across Georgia, Alabama, and Mississippi where integrated pulp-to-panel mills anchor production economics. Manufacturing draws from softwood timber, urea-formaldehyde and pMDI resin systems, and third-party certification infrastructure. Single-region timber dependence creates disease and weather exposure that propagates through input costs. Distribution runs through direct mill relationships for large fabricators and two-step distributors for fragmented geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA TSCA Title VI emission ceilings constitute a regulatory inflection that compresses resin chemistry choices and consolidates procurement toward certified domestic mills, transforming competitive positioning across the forecast window.
For Market Incumbents: Insulate market position by deepening backward integration into captive timberlands and resin formulation capabilities, neutralizing fiber cost volatility that threatens standard-grade margins. Deploy capital into in-house TSCA Title VI certification laboratories to accelerate product launch timelines and filter smaller competitors from specification markets.
For New Entrants and Emerging Players: Pursue white-space opportunity in Canadian residential renovation and multi-family construction where per-capita MDF consumption lags US benchmarks. Target Ontario and Quebec fabricator markets with digital procurement platforms offering lot-traceable CARB documentation, bypassing traditional distributor layers that dominate cross-border supply.
For Investors and Strategic Acquirers: EPA TSCA Title VI reshapes the acquisition landscape by elevating valuation premiums for mills with capitalized testing infrastructure and established third-party certification relationships. Focus diligence on mid-size regional producers with stranded compliance costs that integrated players can absorb. Watch for pMDI resin chemistry talent scarcity as the inflection signal indicating formulation-constrained supply bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberlands | Roseburg and Weyerhaeuser-style captive fiber supply neutralizes spot market volatility in Southeast pine plantations. |
| Low-Emission Resin Reformulation | pMDI chemistry investment displaces formaldehyde-based systems for ANSI A208.2 wet-zone specification capture. |
| Direct-to-Fabricator Digital Channels | E-procurement platforms compress distributor margins while delivering LEED-compliant lot traceability to mid-size millwork shops. |
| Third-Party Certification Infrastructure | In-house TSCA Title VI validation accelerates product launch timelines and filters non-compliant regional competitors. |
| Lifecycle Service Model Expansion | Aftermarket refinishing and resurfacing capture recurring revenue beyond virgin panel commoditization pressure. |
Research Approach
A standing panel of resin formulation chemists, MDF plant operations managers, cabinet shop procurement leads, and EPA compliance officers provided ongoing calibration across primary interview rounds, cross-checked against secondary sources including EPA TSCA filings, CARB certification databases, USFS timber supply reports, and SEC disclosures from integrated forest products companies. Bottom-up volume estimates from mill capacity utilization and top-down demand triangulation from furniture production indices were reconciled through iterative stakeholder validation.
Scenario bracketing around resin chemistry transition timelines and timber supply disruption probabilities anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, customer type, and distribution channel configuration. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules, with specific inputs from pMDI resin adoption rates and US Southeast pine plantation inventory cycles.
Sensitivities concentrate around EPA enforcement intensity, natural gas price swings affecting urea-formaldehyde economics, and Canadian cross-border tariff exposure. Forecasts reflect documented assumptions about certification timeline compression and resin chemistry R&D velocity. Cross-checking against US Census Bureau construction spending data and AHRI furniture production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pigmented Paper Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Leatheroid Paper Market
Paper Products
Global Kraft Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Writing Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Metallized Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Paper Machine Systems Market
Paper Products
Chemical Cellulose Market
Paper Products
Paper Pigment Market