
 Abaca Pulp Market | 2026-2036
Abaca Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Abaca Pulp Market Analytics
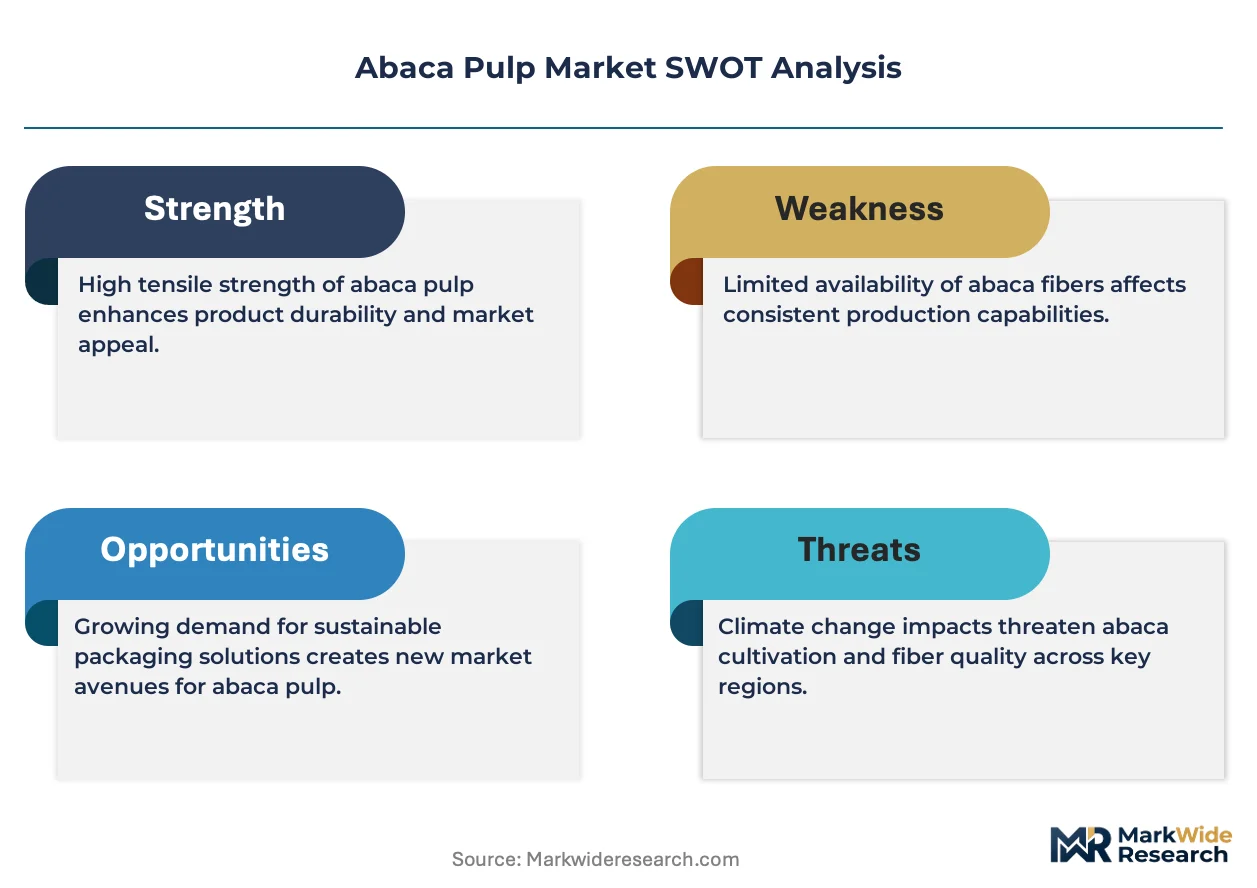
FSC chain-of-custody certification is collapsing the supplier base to a handful of qualified operators. Specialty Pulp Manufacturing, Inc. leverages its integrated Bicol plantation-to-pulp operations to secure raw fiber access. ALINDECO anchors Philippine government-backed cooperative networks across Albay province. Ahlstrom competes through its European teabag paper specialization, sourcing abaca pulp for heat-sealable filter grades.
Abaca pulp consists of cellulose fibers extracted from the leaf sheaths of Musa textilis, a banana-relative native to the Philippines, with fiber lengths of 3–12 mm and high tensile strength enabling wet-laid nonwoven applications. Bleached abaca pulp dominates pharmaceutical-grade filter paper and premium teabag segments where purity standards command margin premiums. Unbleached abaca pulp sustains growing demand in biodegradable food-service packaging as European single-use plastic restrictions tighten. Crude pulp occupies artisanal handicraft supply chains across Southeast Asian export markets with limited scale economies.
The Philippines Department of Environment and Natural Resources enforces watershed conservation rules that restrict abaca cultivation expansion, while EU REACH and F-Gas Regulation frameworks shape chemical processing standards for pulp bleaching sequences. FDA food-contact substance notifications govern abaca pulp migration limits in US filter and packaging applications. Stakeholders must monitor certification cost trajectories against synthetic fiber substitution economics as regulatory compliance becomes the primary market access gate.
Market Dynamics
FSC chain-of-custody certification requirements are consolidating supplier access for European specialty paper mills, forcing raw fiber procurement through a shrinking pool of qualified Philippine plantation-to-pulp operators.
Growth Catalysts
- EU F-Gas Regulation:Chemical processing standards for pulp bleaching sequences are tightening, advantaging Philippine producers with integrated chlorine-free facilities serving teabag and filter paper segments.
- Bleached abaca pulp:Pharmaceutical-grade filter paper manufacturers specify high-purity grades for migration-controlled applications, pulling volume through certified supply chains.
- Bicol Region concentration:Long-fiber grades from Philippine watershed-protected growing zones command premium positioning in wet-laid nonwoven applications.
Market Restraints
- Raw fiber access:Philippine Department of Environment and Natural Resources watershed conservation rules restrict abaca cultivation expansion, capping upstream supply elasticity.
- Synthetic fiber substitution:Polypropylene and polyester alternatives compete on cost in food-service packaging segments where EU single-use plastic restrictions have not yet fully phased out petroleum-based materials.
- Certification cost burden:FSC chain-of-custody compliance adds fixed overhead that artisanal crude pulp producers in Southeast Asian export markets cannot absorb, excluding them from European specialty paper supply chains.
Strategic Opportunities
- Biodegradable food-service packaging:Unbleached abaca pulp demand is accelerating as European Union Green Deal implementation tightens disposable product regulations.
- Heat-sealable filter grades:Convergence of wet-laid nonwoven processing with heat-seal coating technologies opens teabag paper applications previously served by synthetic fiber blends.
- Direct mill relationships:Specialty paper manufacturers in Germany are bypassing traders to contract directly with Bicol plantation-to-pulp operators, compressing channel margins and securing volume commitments.
Industry Challenges
- Certification timeline compression:FSC chain-of-custody audits require 12-18 month implementation cycles, delaying market access for Philippine cooperative networks seeking European qualification.
- Technical workforce scarcity:Chlorine-free bleaching sequence expertise concentrates with integrated operators, limiting expansion capacity for mid-scale Philippine pulp mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abaca Pulp Market |
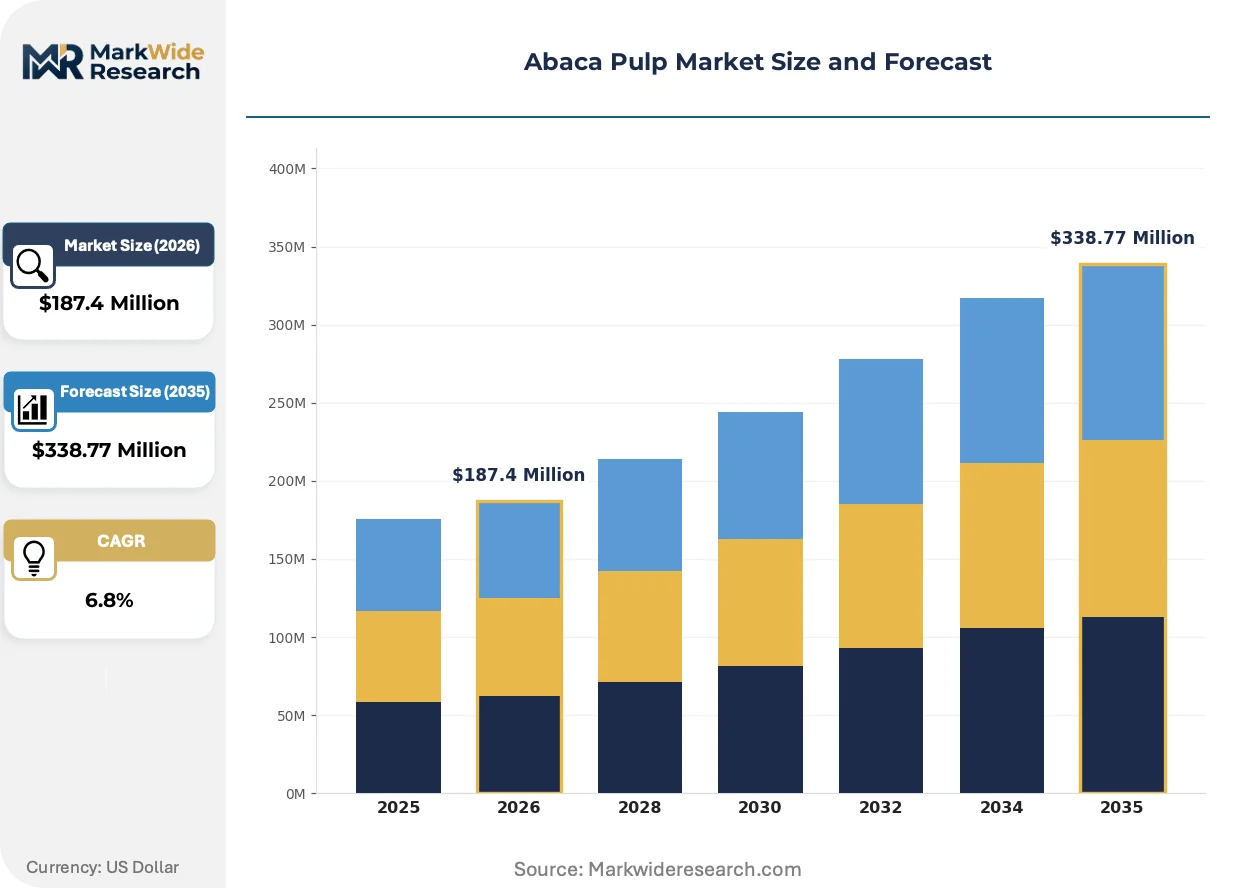
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Abaca Pulp, Unbleached Abaca Pulp, Crude Pulp, Refined Pulp End Use Industry: Textiles, Paper Manufacturing, Handicrafts, Biodegradable Products Form: Sheets, Rolls, Loose Fiber, Tow Grade: Premium Grade, Standard Grade, Industrial Grade, Specialty Grade |
| Companies Covered | Specialty Pulp Manufacturing, Inc., ALINDECO (Albay Agro-Industrial Development Corporation), Ahlstrom, Terranova Papers, Pulp Specialties Philippines, Inc., Veritiv Corporation, Oji Holdings Corporation, UNIVERSAL ROBINA CORPORATION, Glatfelter Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abaca Pulp Market Evolving Landscape
Processing technology convergence and regulatory chemistry standards are redefining competitive qualification in specialty pulp supply chains.
Mechanical refining optimization for long-fiber preservation is supplanting traditional beating approaches in Philippine pulp mills. German teabag paper manufacturers specify these refined grades for heat-sealable filter applications where fiber length retention determines seal integrity. The technology is compressing acceptable supplier lists to operators with capital-intensive refining infrastructure.
REACH framework restrictions on chlorinated bleaching byproducts are reshaping chemical processing standards across European specialty paper supply chains. Philippine integrated producers with captive chlorine-free sequences gain preferential qualification status. Bleached abaca pulp segments serving pharmaceutical-grade filters face the steepest compliance thresholds.
Direct contracting between European specialty paper mills and Philippine plantation-to-pulp operators is displacing trader-mediated procurement. German teabag paper specialists now specify FSC-certified abaca through bilateral volume agreements with Bicol-based suppliers. The pattern concentrates procurement leverage with vertically integrated Philippine operators holding watershed-protected fiber access.
Abaca Pulp Market Segmentation
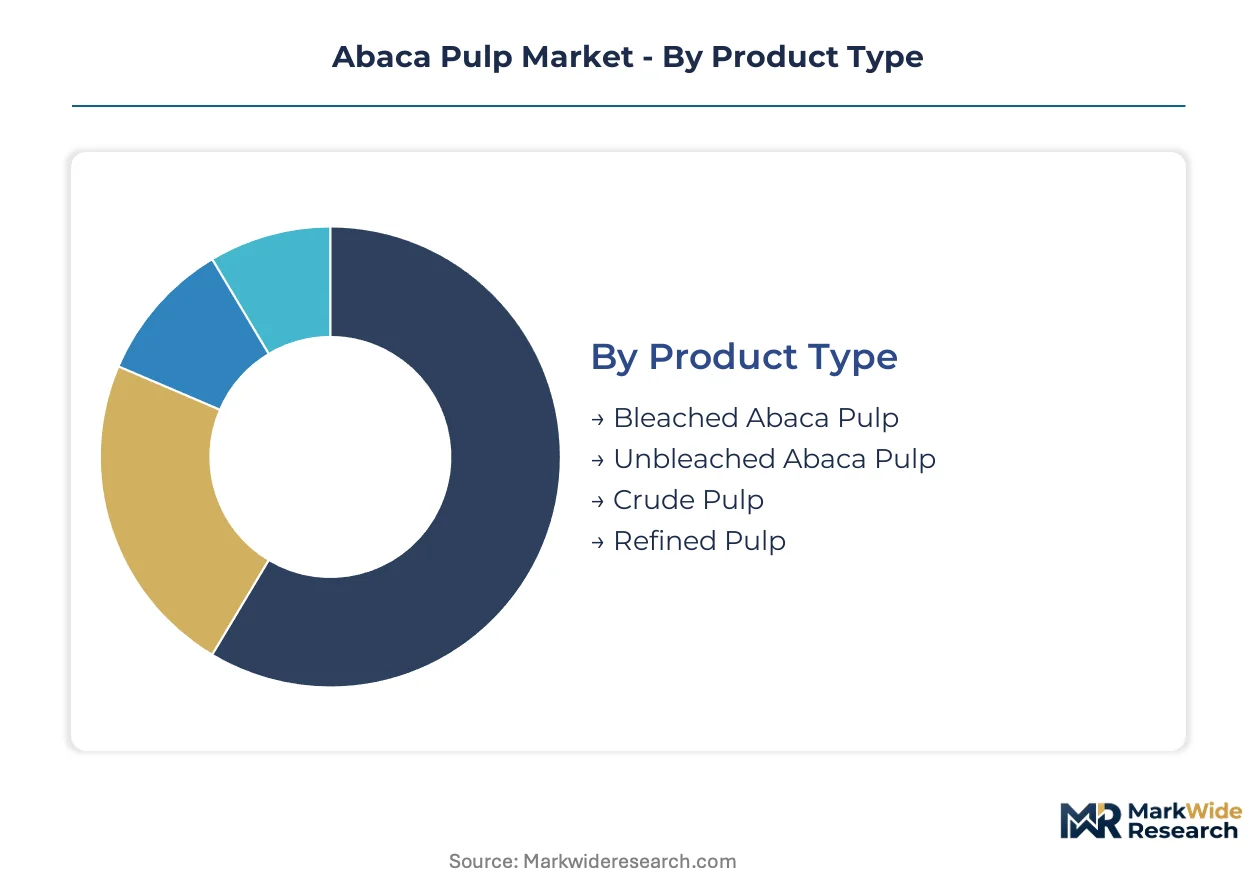
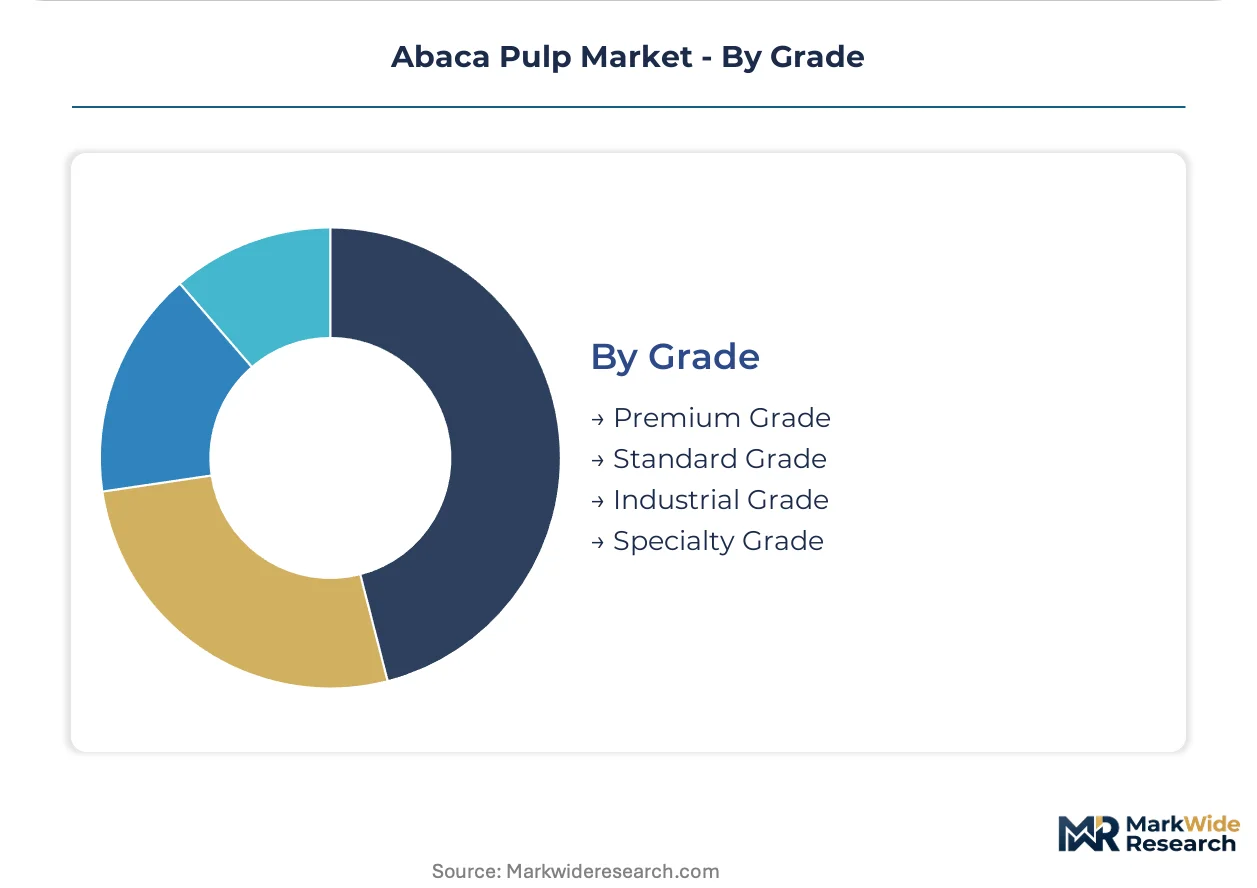
Abaca pulp segmentation reveals how fiber processing intensity and certification tiers partition margin capture across specialty paper value chains. Grade differentiation and product type specifications determine qualification access for pharmaceutical and food-contact applications.
Product Type:
Premium margin pools concentrate in chemically processed grades serving migration-controlled end-uses, while mechanical grades compete on fiber yield economics.
- Bleached Abaca Pulp:Cellulose fibers undergo chlorine-free or elemental chlorine-free sequences to achieve pharmaceutical-grade purity. European teabag paper manufacturers in Germany specify these grades for heat-sealable filter applications where FDA food-contact substance notifications govern migration limits.
- Unbleached Abaca Pulp:Retains natural lignin content and brown coloration, processed through mechanical refining without chemical bleaching. Demand from biodegradable food-service packaging producers in the European Union is climbing fastest as Green Deal implementation tightens disposable product regulations.
- Crude Pulp:Minimally processed fiber bundles serve artisanal handicraft supply chains across Southeast Asian export markets with limited scale economies.
- Refined Pulp:Mechanical refining optimization preserves long-fiber integrity for wet-laid nonwoven processing in specialty filter applications.
Bleached abaca pulp holds installed capacity. Unbleached abaca pulp is rotating up the share rankings.
End Use Industry:
Application-based value capture splits between regulated food-contact segments with certification barriers and commodity craft markets with price transparency.
- Paper Manufacturing:Specialty paper mills in Germany consume long-fiber grades for teabag and filter paper where FSC chain-of-custody certification gates market access.
- Biodegradable Products:Unbleached pulp grades serve food-service packaging and agricultural mulch films as EU single-use plastic restrictions phase out petroleum-based materials.
- Textiles:Abaca fibers blend with cotton and synthetic yarns for specialty apparel and home furnishing applications.
- Handicrafts:Crude pulp supplies artisanal weaving and decorative product markets across Philippine domestic and Southeast Asian export channels.
Paper manufacturing holds installed capacity. Biodegradable products is gaining share fastest.
Form:
Physical presentation determines logistics efficiency and downstream processing compatibility across wet-laid and dry-laid manufacturing lines.
- Sheets:Dried pulp sheets enable containerized ocean freight to European specialty paper mills with predictable moisture content and reduced contamination risk.
- Rolls:Continuous wound pulp supports high-speed converting operations for teabag paper manufacturers with integrated slitting and coating lines.
- Loose Fiber:Bulk fiber shipments serve textile blenders and handicraft processors with in-house opening and cleaning equipment.
- Tow:Rope-like fiber bundles target specific filtration and cordage applications requiring twist retention.
Sheets hold installed capacity. Rolls is expanding most quickly.
Grade:
Certification tier and fiber length specification create pricing stratification that separates plantation-to-pulp integrated operators from cooperative network suppliers.
- Premium Grade:Long-fiber grades from Bicol Region watershed-protected growing zones command positioning in pharmaceutical-grade filter paper where ECHA REACH restrictions on chlorinated byproducts enforce purity thresholds.
- Specialty Grade:Custom fiber length distributions and ash content specifications serve niche wet-laid nonwoven applications with technical performance requirements.
- Standard Grade:Mid-range fiber length and purity specifications balance cost and performance for general teabag and food packaging applications.
- Industrial Grade:Shorter fiber fractions and higher permissible defect rates serve abrasive substrates and non-food-contact applications with relaxed purity standards.
Premium grade holds installed capacity. Specialty grade is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical restrictions and FDA food-contact standards are redirecting abaca pulp procurement toward Philippine watershed-certified zones and German specialty paper clusters.
Germany
Teabag paper manufacturers in Baden-Württemberg specify FSC-certified abaca for heat-sealable filter grades. ECHA REACH restrictions on chlorinated bleaching byproducts enforce purity thresholds for pharmaceutical-grade applications. The Stuttgart-Karlsruhe corridor hosts wet-laid nonwoven specialists contracting directly with Bicol plantation-to-pulp operators.
Philippines
Bicol Region long-fiber grades command premium positioning in European specialty paper supply chains. The Department of Environment and Natural Resources tightened watershed conservation rules around Mount Isarog growing zones, capping cultivation expansion. Albay province cooperative networks anchor government-backed fiber procurement for integrated pulp mills serving export markets.
United States
Pharmaceutical-grade filter paper producers specify bleached abaca pulp for migration-controlled applications under FDA food-contact substance notifications. FDA migration limits govern pulp purity standards for teabag and packaging segments. East Coast specialty paper converters source sheet-form abaca through containerized freight from Philippine integrated operators.
Japan
Heat-sealable filter paper demand from METI-regulated food-packaging sectors pulls refined abaca grades for wet-laid nonwoven processing. Japanese technical standards for biodegradable food-service packaging align with EU Green Deal implementation timelines. Osaka-based trading houses maintain long-term volume agreements with Philippine pulp mills holding FSC chain-of-custody certification.
Abaca Pulp Market Competitive Landscape
Player mix skews toward plantation-to-pulp integrated operators with watershed-protected fiber access and European specialty paper mill direct relationships. The supplier base consolidates around FSC-certified Philippine operators and European teabag paper specialists with captive abaca sourcing. Three archetypes dominate: integrated plantation-to-pulp operators controlling upstream fiber supply, cooperative network aggregators leveraging government-backed procurement, and European specialty paper mills with direct Bicol contracting strategies. Competitive moves center on backward integration into watershed-protected growing zones and bilateral volume agreements compressing trader margins.
Within the integrated operator tier, Specialty Pulp Manufacturing, Inc. exemplifies plantation-to-pulp vertical control, while ALINDECO represents cooperative network aggregation across Albay province. Ahlstrom occupies a position among European specialty paper specialists sourcing abaca for heat-sealable filter applications. These three anchors illustrate how certification access and geographic proximity to Bicol fiber sources determine qualification status for regulated European and North American end-markets.
| Leading Market Players |
|---|
| Specialty Pulp Manufacturing, Inc. |
| ALINDECO (Albay Agro-Industrial Development Corporation) |
| Ahlstrom |
| Terranova Papers |
| Pulp Specialties Philippines, Inc. |
| Veritiv Corporation |
| Oji Holdings Corporation |
| UNIVERSAL ROBINA CORPORATION |
| Glatfelter Corporation |
| Others |
Value Network & Pricing Analysis
FSC chain-of-custody certification gates both supplier qualification and price differentiation simultaneously, compressing market access to Philippine integrated operators while forcing three-tier pricing stratification across premium, standard, and economy grades. Certification overhead and watershed-protected fiber scarcity feed directly into margin capture, with European specialty paper mills paying premiums for direct Bicol contracting relationships.
Pricing Analysis
Cost-plus contracts with Manila abaca fiber indexation dominate procurement between German teabag paper manufacturers and Bicol plantation-to-pulp operators. Price differentiation rests on FSC certification tier and fiber length retention, with pharmaceutical-grade filter specifications commanding the widest spreads. Cost compression in standard-grade segments is intensifying because polypropylene alternatives compete aggressively in food-service packaging applications. Artisanal crude pulp producers exhibit highest price sensitivity, while integrated operators serving heat-sealable filter grades demonstrate lowest elasticity due to captive supply relationships.
Supply Chain Analysis
The Philippines anchors global abaca pulp supply through Bicol Region watershed-protected growing zones, with secondary contributions from Ecuador and Costa Rica serving artisanal export channels. Philippine integrated operators draw from captive fiber estates, while European specialty paper mills source from direct mill relationships. Single-source vulnerability concentrates in Albay province cooperative networks, where DENR watershed restrictions cap cultivation expansion. Distribution runs through containerized ocean freight of sheet-form pulp to Baden-Württemberg specialty paper clusters, bypassing trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Abaca pulp market fragmentation creates acquisition and positioning opportunities as EU Green Deal implementation splinters demand across biodegradable packaging and pharmaceutical-grade filter niches. Certification barriers and fiber access constraints reward targeted capability building over broad market entry.
For Market Incumbents: Consolidate backward integration into Mount Isarog watershed-protected growing zones before DENR restrictions harden further. Secure chlorine-free bleaching sequence expertise through technical workforce development, as REACH framework compliance becomes the primary qualification gate for European teabag paper contracts. Capacity addition in Albay province cooperative networks defends against direct mill contracting trends compressing trader margins. For New Entrants and Emerging Players: Lead with unbleached abaca pulp specialization targeting biodegradable food-service packaging segments where EU single-use plastic restrictions outpace synthetic fiber substitution economics. Japan METI-regulated food-packaging sectors offer the most penetrable geography for refined pulp grades. Go-to-market positioning should emphasize wet-laid nonwoven processing compatibility with heat-seal coating technologies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified paper conglomerates with stranded abaca pulp assets lacking FSC certification investment. Long-term viability hinges on 5-10 year regulatory continuity in EU REACH and FDA food-contact substance notification frameworks. Watch for inflection signals in Philippine DENR watershed policy enforcement tightening, which would accelerate supplier consolidation toward integrated plantation-to-pulp operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Watershed-Protected Fiber Supply | DENR conservation rules cap expansion, making captive Bicol growing zones irreplaceable assets. |
| Chlorine-Free Bleaching Sequence Certification | ECHA REACH restrictions on chlorinated byproducts enforce purity thresholds for pharmaceutical-grade filter applications. |
| Direct Mill Contracting with European Specialty Paper Manufacturers | Baden-Württemberg teabag paper specialists now bypass traders for bilateral volume commitments with Bicol operators. |
| Heat-Sealable Filter Grade Development | Convergence of wet-laid nonwoven processing with coating technologies opens teabag paper applications previously served by synthetic blends. |
| FSC Chain-of-Custody Audit Implementation | 12-18 month certification cycles gate European market access, excluding artisanal crude pulp producers from specialty paper supply chains. |
Research Methodology
The analysis maps bleached, unbleached, crude, and refined pulp sub-sectors, each validated through plantation operations managers, specialty paper mill procurement directors, and FSC certification auditors. Primary interviews with German teabag paper manufacturers, Philippine cooperative network coordinators, and Japanese trading house commodity specialists combined with secondary validation from EU ECHA regulatory filings, Philippine DENR watershed policy documents, and FDA food-contact substance notification databases. Bottom-up fiber yield modeling and top-down European specialty paper demand triangulation anchored volume estimates.
Consistency checks against customs trade data and containerized freight flows validated output ranges across the analysis window. Segmentation dimensions modeled include product type, end-use industry, physical form, and grade tier alongside watershed certification status and chlorine-free processing capability. CAGRs derived from fiber access elasticity constraints and substitution economics between abaca and synthetic filter materials. Forecast inputs incorporated EU Green Deal implementation timelines and FDA migration limit enforcement patterns.
Forecasts assume regulatory continuity in EU REACH, FDA food-contact substance notifications, and Philippine DENR watershed frameworks; material policy shifts would require re-modeling fiber supply elasticity and certification cost trajectories. Recalibration cycles align with material shifts in EU F-Gas Regulation enforcement, DENR conservation rule amendments, and heat-sealable filter grade adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Europe Coated Paper Market
Paper Products
Stone Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Specialty Paper Market
Paper Products
Insulation Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Paper and Board Technologies Market
Paper Products
Chemical Cellulose Market
Paper Products
Inlay Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Paper Goods Market
Paper Products
Europe Decor Paper Market